
 United Kingdom Automotive OEM Coatings Market | 2026-2036
United Kingdom Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Automotive OEM Coatings Market Outlook
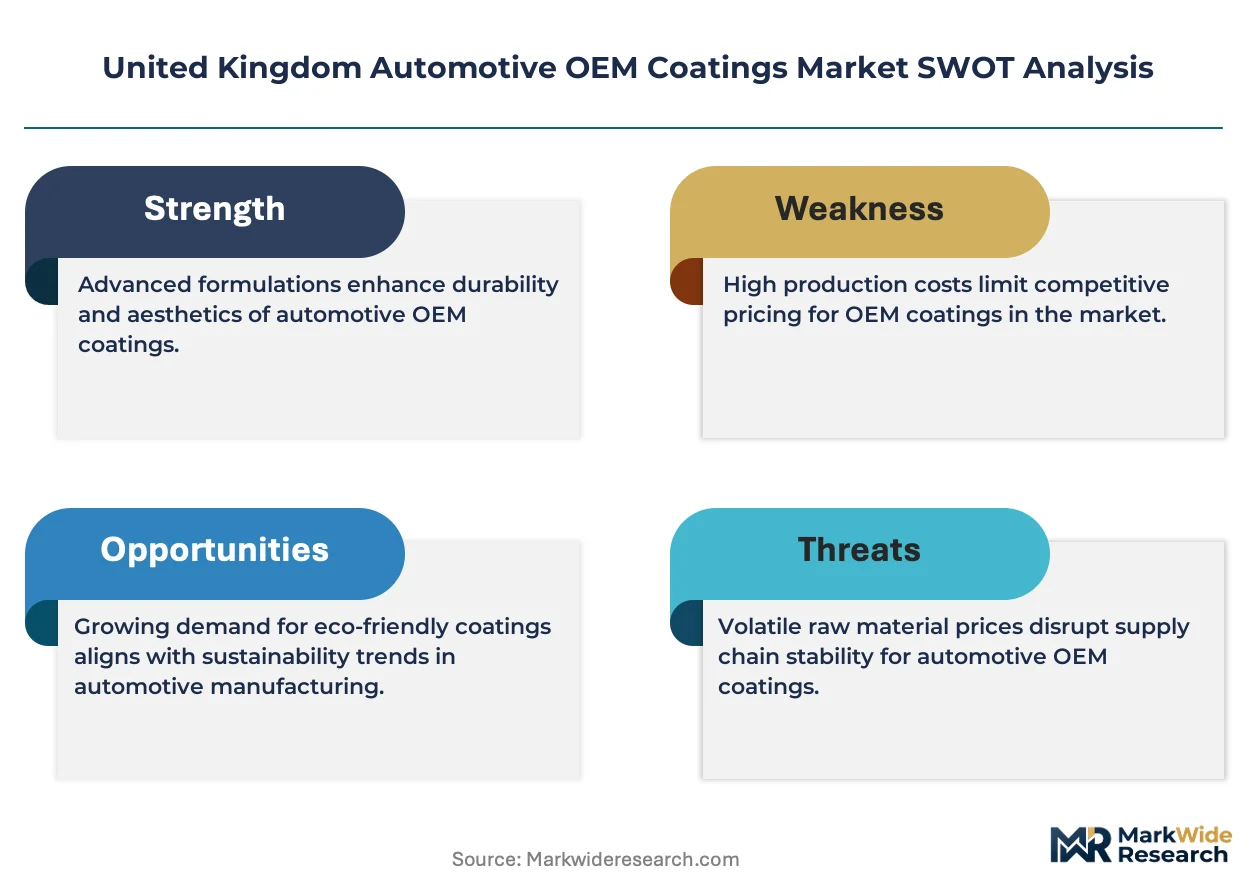
EU REACH compliance is rebalancing the cost-of-entry calculus for coating suppliers serving UK vehicle manufacturers. BASF SE leverages its integrated resin-to-coating pipeline to manage regulatory complexity across its UK operations. PPG Industries, Inc anchors its position through deep relationships with premium British marques requiring bespoke colour-matching capabilities. Akzo Nobel N.V. competes by sustaining a dedicated technical service centre in the Midlands.
Automotive OEM coatings are multi-layer protective and decorative systems applied to vehicle bodies before final assembly, typically comprising electrodeposited primers, pigmented basecoats, and transparent clearcoats that must achieve specific film builds, gloss retention, and chip resistance measured against OEM engineering specifications. Their primary purpose is to protect steel and aluminium substrates from corrosion while delivering the aesthetic finish that defines brand identity at point of sale. Water-based basecoat formulations now lead technology adoption as British manufacturers phase out solvent-borne alternatives under environmental mandates, while clearcoat demand concentrates in high-solids and UV-cured variants where margin pools remain deepest. Electric vehicle application segments are expanding fastest as dedicated UK battery-electric platforms require modified coating protocols for aluminium-intensive body structures.
The Health and Safety Executive enforces workplace exposure limits that constrain solvent-based coating use in British manufacturing facilities, while BSI standards govern adhesion and weathering performance for OEM-qualified products. The Environment Agency's permitting regime shapes wastewater treatment investments at coating facilities, particularly around volatile organic compound capture. Stakeholders must monitor how post-Brexit divergence from EU chemical regulations alters formulation approval timelines and cross-border supply chain certification requirements.
Market Dynamics
The UK's 2030 internal combustion engine sales ban is compressing coating formulation cycles as British OEMs retool Sunderland and Solihull lines for aluminium-intensive electric platforms, forcing suppliers to validate water-based primers under accelerated automotive qualification timelines.
Growth Catalysts
- EU REACH compliance:The regulatory framework is elevating technical barriers that favour integrated resin-to-coating suppliers with dedicated UK compliance infrastructure, consolidating procurement toward qualified vendors.
- West Midlands automotive cluster:Concentrated OEM assembly capacity around Birmingham and Coventry generates dense coating demand pools that justify dedicated technical service investments and just-in-time supply contracts.
- Water-based basecoat technology:British manufacturers are phasing out solvent-borne alternatives under environmental mandates, creating specification pull for compliant coating systems across passenger and commercial vehicle segments.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and acrylic resin prices fluctuate with crude oil derivatives, compressing margin predictability for coating formulators serving volume OEM contracts.
- Midlands supplier concentration:Technical service centres and blending capacity cluster disproportionately in Birmingham-Coventry corridor, creating geographic vulnerability to regional logistics disruptions.
- Aluminium substrate adhesion limits:Conventional pretreatment chemistries struggle with oxide layer variability on electric vehicle body structures, requiring costly process revalidation.
Strategic Opportunities
- Scottish automotive corridor:Underdeveloped coating infrastructure near emerging electric component manufacturing in Central Belt offers first-mover positioning for technical service expansion.
- UV-cured clearcoat convergence:Combination of energy-curable chemistry with high-solids formulations enables premium finish differentiation for luxury British marques seeking bespoke aesthetic capabilities.
- Environment Agency VOC capture incentives:Permitting regime rewards investment in thermal oxidiser and carbon adsorption systems, creating competitive advantage for compliant coating facilities.
Industry Challenges
- Formulation chemist scarcity:British universities produce insufficient polymer science graduates with automotive coating specialisation, elongating R&D cycle times for bespoke OEM colour-matching requirements.
- Post-Brexit certification divergence:Divergent EU-UK chemical approval timelines create inventory risk for coating suppliers managing cross-border formulation registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Automotive OEM Coatings Market |
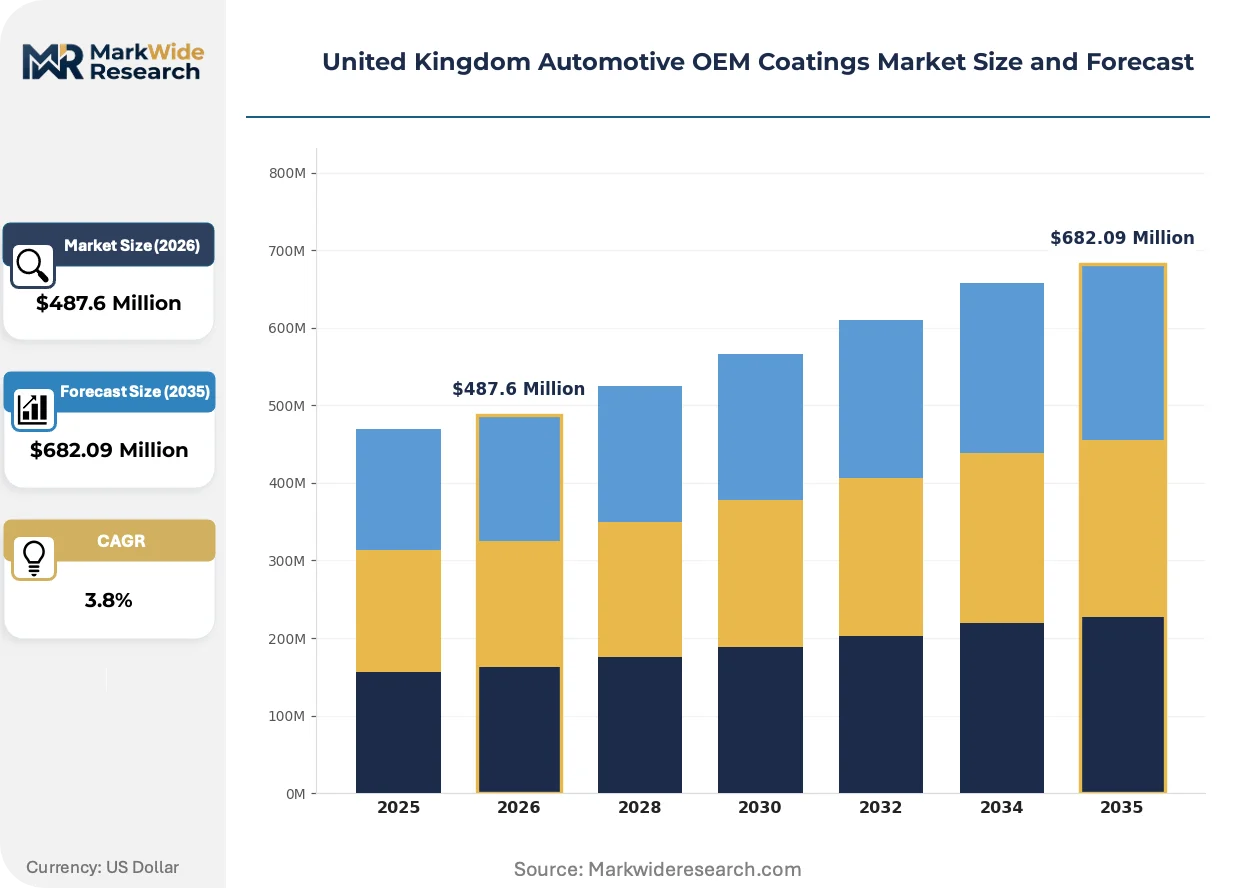
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $682.09 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primer, Basecoat, Clearcoat, Specialty Coating Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Technology: Water-Based, Solvent-Based, Powder Coating, UV-Cured Coatings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Akzo Nobel N.V., Axalta Coating Systems, BASF SE, PPG Industries, Inc, The Sherwin-Williams Company, Nippon Paint Holdings Co Ltd, Kansai Paint Co Ltd, Covestro AG, Jotun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Automotive OEM Coatings Market Strategic Shifts
Coating chemistry is pivoting toward energy-efficient cure technologies and substrate-flexible formulations as British electric vehicle platforms proliferate, with regulatory pressure and OEM sustainability targets converging to accelerate specification change.
UV-cured clearcoat systems are rewriting performance benchmarks for premium British automotive finishes. These formulations deliver superior gloss retention and scratch resistance while eliminating thermal oven energy consumption. Jaguar Land Rover and Bentley Motors are specifying UV-cured topcoats for bespoke colour programmes. The technology is compressing traditional high-solids clearcoat margin pools by enabling thinner film builds with equivalent durability.
REACH registration requirements are tightening substance authorisation timelines for coating raw materials imported into UK manufacturing facilities. The Health and Safety Executive's workplace exposure limits now constrain solvent-based primer application in British assembly plants. Water-borne electrodeposition systems are capturing specification share as OEMs eliminate solvent-borne E-coat lines ahead of regulatory deadlines.
British OEM procurement departments are consolidating coating supply contracts toward full-system vendors capable of integrated primer-basecoat-clearcoat qualification. Tier-1 suppliers with captive resin production and Midlands-based technical service infrastructure are displacing single-layer specialists. This concentration is most visible in premium passenger vehicle segments where colour-matching complexity and just-in-time delivery requirements favour vertically integrated coating partners.
United Kingdom Automotive OEM Coatings Market Segmentation
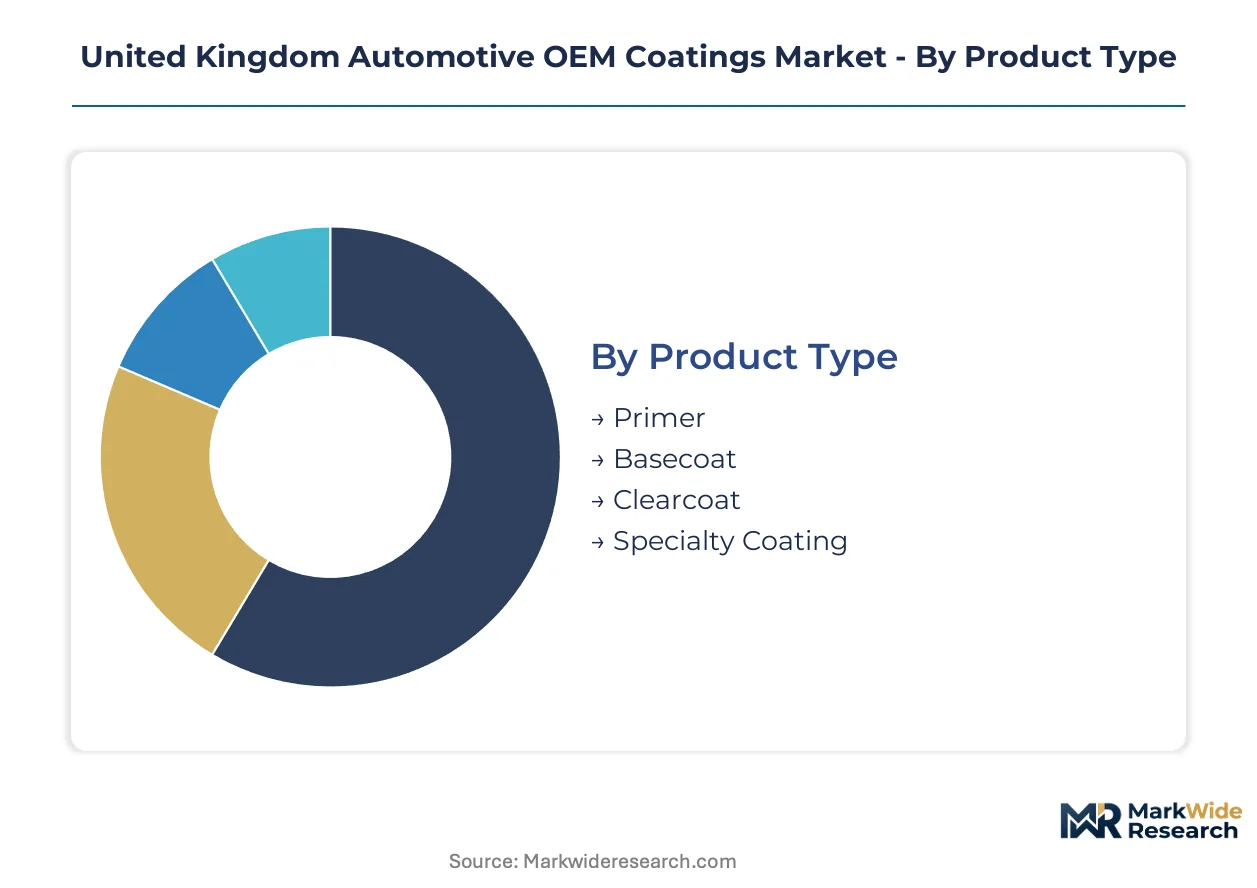
Automotive OEM coatings segment by formulation chemistry, vehicle platform requirements, and supply chain position. Each dimension carries distinct margin profiles and technical qualification barriers that reshape competitive positioning across British manufacturing facilities.
Product Type:
Product differentiation tracks functional layer hierarchy and film build specifications required by British OEM engineering standards.
- Primer:Electrodeposited coatings provide corrosion protection on steel and aluminium substrates through cathodic deposition processes. Nissan Sunderland and Jaguar Land Rover Solihull are expanding water-based primer capacity ahead of the 2030 combustion engine ban, validating formulations under compressed automotive qualification timelines.
- Basecoat:Pigmented layers deliver colour and aesthetic definition through water-borne or solvent-borne resin systems. West Midlands automotive clusters around Birmingham and Coventry concentrate basecoat demand pools that justify dedicated technical service investments from qualified suppliers.
- Clearcoat:Transparent protective topcoats provide gloss retention and chip resistance against OEM durability specifications. High-solids and UV-cured variants command deepest margin pools as British luxury marques specify bespoke finish capabilities.
- Specialty Coating:Functional formulations including anti-chip, sound-dampening, and thermal management layers address electric vehicle platform requirements. Aluminium-intensive battery-electric architectures demand modified adhesion protocols.
Volume sits with primer and basecoat systems; growth tilts toward specialty coatings serving electric vehicle thermal management needs.
Application:
Vehicle category determines substrate mix, colour complexity, and just-in-time delivery requirements across British assembly lines.
- Passenger Vehicles:High-volume production lines at Nissan Sunderland specify standardised colour palettes with rapid batch changeover capabilities. Water-based basecoat adoption is most advanced in this segment under Health and Safety Executive workplace exposure limits.
- Commercial Vehicles:Heavy-duty truck and van platforms prioritise durability and corrosion resistance over aesthetic complexity. Solvent-based formulations retain specification share where film build requirements exceed water-borne performance envelopes.
- Electric Vehicles:Battery-electric platforms require modified coating protocols for aluminium-intensive body structures. Dedicated UK production lines are expanding fastest as OEMs retool Sunderland and Solihull facilities.
- Luxury Vehicles:Bentley Motors and low-volume British marques demand bespoke colour-matching with extended development cycles. UV-cured clearcoat systems are gaining specification share for premium finish differentiation.
Passenger vehicles anchor procurement volumes; electric vehicle application segments are expanding most quickly.
Technology:
Formulation chemistry determines regulatory compliance position and energy consumption across curing operations.
- Water-Based:Emulsion and dispersion systems replace solvent-borne alternatives under Environment Agency VOC permitting regimes. British manufacturers are phasing out solvent-borne primers and basecoats ahead of regulatory deadlines.
- Solvent-Based:Conventional high-solids formulations retain niche application in commercial vehicle segments and specialty finishes where water-borne performance specifications remain unmet.
- Powder Coating:Thermoset polymer systems deliver zero-VOC application for underbody and component coating. Limited penetration in body-in-white applications due to film uniformity constraints on complex geometries.
- UV-Cured Coatings:Energy-curable clearcoat systems eliminate thermal oven consumption while delivering superior gloss retention. Jaguar Land Rover and Bentley Motors specify UV-cured topcoats for bespoke colour programmes.
Water-based systems dominate procurement volumes; UV-cured coatings are climbing the fastest as energy efficiency targets tighten.
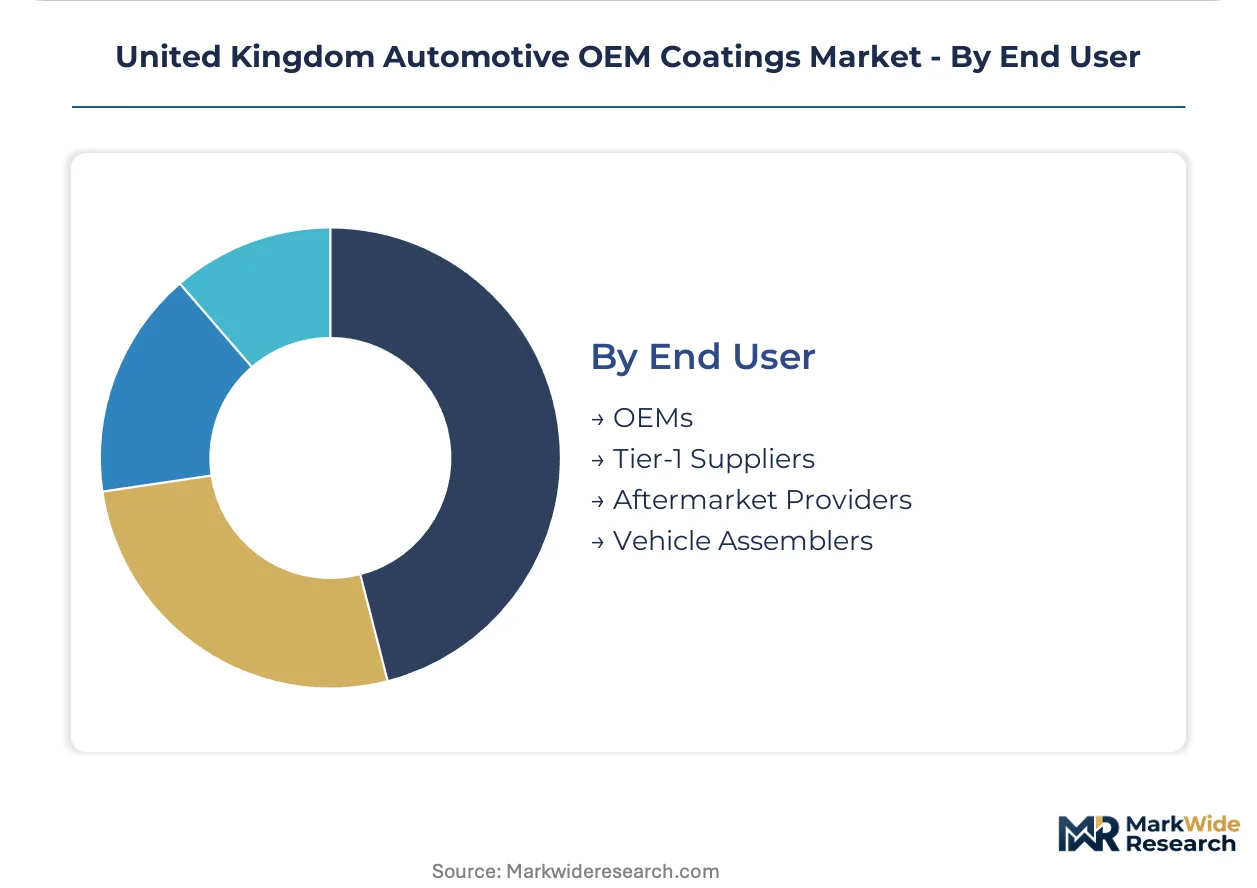
End User:
Supply chain position determines technical service intensity, inventory risk allocation, and formulation approval authority.
- OEMs:Vehicle manufacturers including Nissan Motor Manufacturing UK and Jaguar Land Rover hold final specification authority and conduct direct coating qualification. Integrated primer-basecoat-clearcoat contracts are consolidating toward full-system vendors.
- Tier-1 Suppliers:Component manufacturers and system integrators manage sub-assembly coating operations with captive blending capacity. Midlands-based technical service infrastructure supports just-in-time delivery requirements.
- Aftermarket Providers:Refinish and repair coating demand falls outside OEM qualification scope. Distinct distribution channels and colour-matching systems serve collision repair networks.
- Vehicle Assemblers:Contract manufacturing and niche vehicle builders purchase qualified coatings through distributor relationships. Lower volumes reduce bargaining leverage on formulation customisation.
Procurement concentrates with OEMs and Tier-1 suppliers; aftermarket providers operate outside the OEM coating qualification framework.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced Manufacturing Parks and Enterprise Zones across England concentrate coating demand through tax-incentive clustering around major OEM assembly sites. The West Midlands automotive corridor anchors procurement volumes, while emerging Scottish electric component manufacturing creates new geographic opportunity.
West Midlands
Nissan Sunderland and Jaguar Land Rover Solihull drive primer and basecoat procurement through expanding electric vehicle production lines. The Health and Safety Executive enforces workplace exposure limits that accelerate water-based formulation adoption across Birmingham-Coventry facilities. Dense technical service infrastructure supports just-in-time delivery contracts from qualified coating vendors.
North England
Commercial vehicle assembly at Leyland Trucks and specialist coachbuilders sustains solvent-based coating demand where durability specifications exceed water-borne performance envelopes. The Environment Agency's VOC permitting regime shapes wastewater treatment investments at regional coating facilities. Supply chain concentration around Manchester logistics hubs reduces inbound resin distribution costs.
Scotland
Emerging battery-electric component manufacturing in the Central Belt generates coating demand for aluminium-intensive substrates. Scottish Enterprise innovation funding supports process revalidation for modified adhesion protocols on electric vehicle architectures. Underdeveloped local blending capacity creates first-mover positioning for technical service expansion.
Wales
Steel-intensive component stamping at Port Talbot and Bridgend sustains electrodeposited primer volumes for corrosion protection on conventional platforms. The Welsh Government's automotive sector support programmes incentivise coating facility modernisation. Limited local formulation capacity drives reliance on Midlands-based supply routes.
South East England
Luxury vehicle finishing at Bentley Motors in Crewe demands bespoke colour-matching with extended development cycles. UV-cured clearcoat specifications from premium British marques concentrate technical service intensity in this corridor. Proximity to Dover-Folkestone logistics channels facilitates cross-border raw material movements under post-Brexit customs arrangements.
United Kingdom Automotive OEM Coatings Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the United Kingdom Automotive OEM Coatings Market, creating a tiered structure where integrated resin-to-coating suppliers capture procurement consolidation. Three strategic archetypes dominate: multinational chemical conglomerates with captive resin production, regional coating formulators with Midlands technical service infrastructure, and Asian manufacturers expanding European qualification portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for electric vehicle platform contracts.
Among integrated chemical conglomerates, BASF SE and Akzo Nobel N.V. occupy positions exemplifying the resin-to-coating pipeline archetype that manages regulatory complexity across UK operations. PPG Industries, Inc. anchors the premium-tier vector through relationships with British marques requiring bespoke capabilities. These three companies represent the full-system vendor consolidation pattern visible in OEM procurement departments.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| BASF SE |
| PPG Industries, Inc |
| The Sherwin-Williams Company |
| Nippon Paint Holdings Co Ltd |
| Kansai Paint Co Ltd |
| Covestro AG |
| Jotun |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin price indices cascade through UK automotive coating supply chains, compressing margin pools at formulation stages while concentrating pricing power among integrated resin-to-coating suppliers with captive feedstock production.
Pricing Analysis
Short-lead-time premiums dominate contract structures for just-in-time coating deliveries to West Midlands OEM facilities, while spot inventory positions trade at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity and certification grade. Cost compression in water-based primer tiers is intensifying because petrochemical feedstock volatility feeds raw material uncertainty into long-term contracts. Tier-1 suppliers with integrated resin production exhibit lowest price sensitivity; small vehicle assemblers purchasing through distributor channels face highest procurement cost volatility.
Supply Chain Analysis
Acrylic and epoxy resin supply rests on German and Dutch petrochemical producers, with specialty additive production concentrated in Belgium and Switzerland. UK coating formulators draw from imported resin feedstocks, titanium dioxide pigments, and UV-curable oligomers. Single-source vulnerability sits with cathodic electrodeposition resin supply from continental European producers. Distribution runs through Midlands-based technical service centres with just-in-time blending capacity adjacent to Birmingham-Coventry OEM clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance operates as a cost-of-compliance moat, elevating technical barriers that favour established suppliers with dedicated UK regulatory infrastructure and consolidated procurement relationships.
For Market Incumbents: Extend technical service coverage into the Scottish Central Belt to capture emerging battery-electric component manufacturing demand. Deepen backward integration into water-based resin production to defend margin position against petrochemical price volatility. Consolidate full-system contracts across primer-basecoat-clearcoat specifications before new entrants achieve automotive qualification timelines.
For New Entrants and Emerging Players: The price-point gap between premium UV-cured clearcoat specifications and economy water-based basecoat tiers offers positioning room for mid-market specialists. Scottish coating infrastructure remains underdeveloped relative to emerging electric vehicle component demand. Enter through technical service partnerships with Central Belt manufacturers seeking modified adhesion protocols for aluminium-intensive architectures.
For Investors and Strategic Acquirers: The window for entry favours integrated resin-to-coating specialists with established REACH compliance infrastructure. Long-term viability hinges on qualification relationships with British OEMs retooling for electric platforms. Monitor Environment Agency VOC permitting decisions as the inflection signal for competitive facility positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive epoxy and acrylic supply insulates BASF and Akzo Nobel from petrochemical price volatility. |
| Technical Service Expansion | Midlands-based centres support just-in-time delivery contracts with Jaguar Land Rover and Nissan Sunderland. |
| UV-Cured Clearcoat Qualification | Bentley Motors and premium British marques specify energy-curable systems for bespoke finish programmes. |
| Water-Based Primer Validation | Health and Safety Executive workplace limits accelerate specification pull for compliant electrodeposition systems. |
| Scottish Corridor Positioning | Scottish Enterprise innovation funding supports first-mover technical service investment near emerging battery manufacturing. |
Study Parameters
Document review covered regulatory filings from the Health and Safety Executive and Environment Agency, trade data from HM Revenue and Customs, and automotive production databases, complemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, coating formulator technical directors, and Midlands distribution channel partners. Secondary validation drew from SEC filings of multinational chemical conglomerates, British Coatings Federation industry reports, and EU REACH substance registration databases. Bottom-up coating demand estimates triangulated against top-down automotive production forecasts.
Value projections across the analysis window derived from segmented modeling of primer, basecoat, clearcoat, and specialty coating demand by vehicle platform and formulation chemistry. The analytical framework incorporated propulsion architecture transitions, content-per-vehicle assumptions for electric platforms, and regional production cluster concentration around Birmingham-Coventry and Sunderland-Solihull corridors. CAGRs emerged from regression analysis of historical coating intensity trends and OEM retooling timelines.
Inputs from Health and Safety Executive exposure limit determinations and Environment Agency permitting records were available through the study window; gaps in post-Brexit chemical registration divergence timelines introduce uncertainty bands around cross-border formulation approval assumptions. Forecasts reflect documented assumptions regarding electric vehicle platform adoption and REACH compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Marine Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Cool Roof Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
High Performance Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Protective Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Global Smart Coating Market