
 Mexico Protective Coatings Market | 2026-2036
Mexico Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Protective Coatings Market Foresight
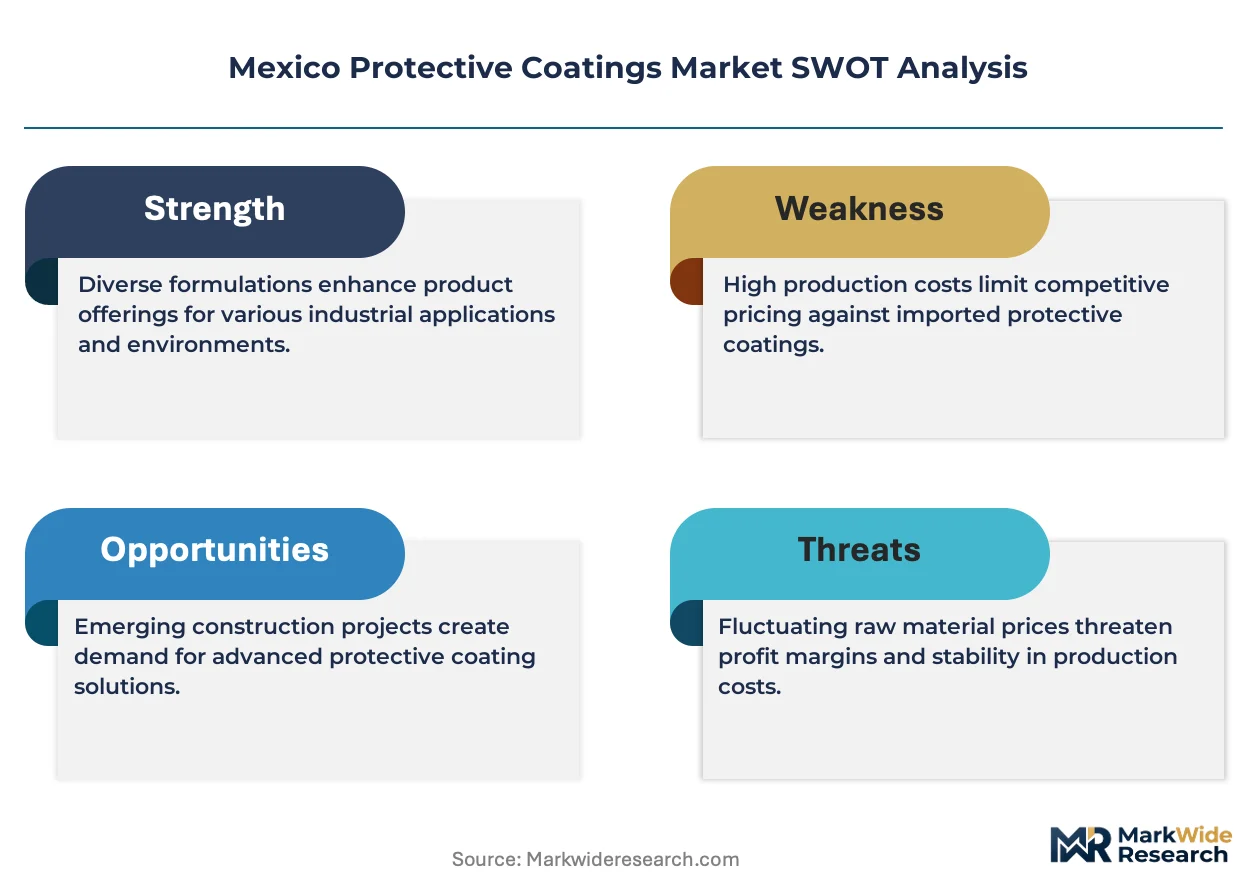
Mexico's energy infrastructure buildout is recalibrating protective coatings procurement patterns across the Gulf Coast. PPG Industries, Inc. leverages its automotive refinish heritage to extend into industrial protective lines for PEMEX contractor networks. Akzo Nobel N.V. anchors its position through marine coating specialization serving Altamira and Veracruz port authorities. Hempel A/S differentiates via high-performance epoxy systems tailored to offshore platform maintenance cycles in Mexican territorial waters.
Protective coatings are engineered barrier systems comprising polymer binders, corrosion inhibitors, and functional pigments applied to metal, concrete, or composite substrates to prevent degradation from chemical, thermal, or environmental exposure. Epoxy formulations dominate heavy industrial applications due to superior chemical resistance and adhesion to prepared steel surfaces. Polyurethane topcoats command premium positioning in automotive and aerospace finishing where UV stability and aesthetic durability define specification requirements. Waterborne technology segments are gaining formulation sophistication as NOM-001-SEMARNAT and PROY-NOM-118-SEMARNAT-2017 tighten volatile organic compound thresholds across manufacturing and application operations.
SEMARNAT enforcement of Mexican Official Standards (NOM) for air quality and hazardous waste management directly shapes product registration and import authorization pathways for coating suppliers. COFEPRIS oversight of industrial chemical safety intersects with workplace exposure limits under STPS regulations, creating multi-agency compliance architecture for formulators and applicators. Stakeholders must monitor pending amendments to NOM-118 that would align Mexican VOC limits more closely with U.S. EPA Method 24 benchmarks, as this convergence would reshape competitive positioning for domestic versus imported coating portfolios.
Market Dynamics
PEMEX infrastructure rehabilitation and private upstream licensing rounds are redirecting protective coatings procurement toward offshore platform maintenance and pipeline integrity programs across the Gulf of Mexico. Formulators face simultaneous pressure from SEMARNAT emission thresholds and contractor demand for extended asset life cycles.
Growth Catalysts
- NOM-118-SEMARNAT alignment:Pending VOC limit convergence with U.S. EPA Method 24 benchmarks is accelerating waterborne formulation R&D investments among domestic suppliers.
- Offshore platform maintenance:Cantarell field aging infrastructure requires cyclical recoating programs every 5-7 years, generating recurring demand for high-build epoxy systems.
- Port modernization:Altamira and Veracruz port authority expansion projects specify marine-grade anti-corrosive coatings for quay walls and cargo handling equipment.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin prices fluctuate with propylene and bisphenol-A supply disruptions from Texas Gulf Coast petrochemical complexes.
- Import dependency:Specialty corrosion inhibitors and zinc dust pigments concentrate sourcing from Chinese and European chemical manufacturers.
- Application labor scarcity:NACE-certified coating inspectors remain concentrated in Veracruz-Tamaulipas corridor, constraining project execution in Pacific Coast states.
Strategic Opportunities
- Yucatan offshore wind:Proyecto Eólico del Sureste preliminary engineering studies specify protective systems for monopile foundations in corrosive marine atmospheres.
- COFEPRIS fast-track registration:Streamlined chemical safety approvals for low-VOC formulations reduce time-to-market for innovative waterborne products.
- Digital coating specification platforms:Contractor networks adopt cloud-based asset management tools that embed coating selection algorithms into maintenance scheduling systems.
Industry Challenges
- Surface preparation standards:SSPC-SP 10 near-white metal blast compliance requires capital-intensive abrasive blasting equipment that smaller applicators struggle to finance.
- Multi-agency compliance coordination:Simultaneous SEMARNAT environmental, STPS workplace exposure, and COFEPRIS chemical safety filings create administrative bottlenecks for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Protective Coatings Market |
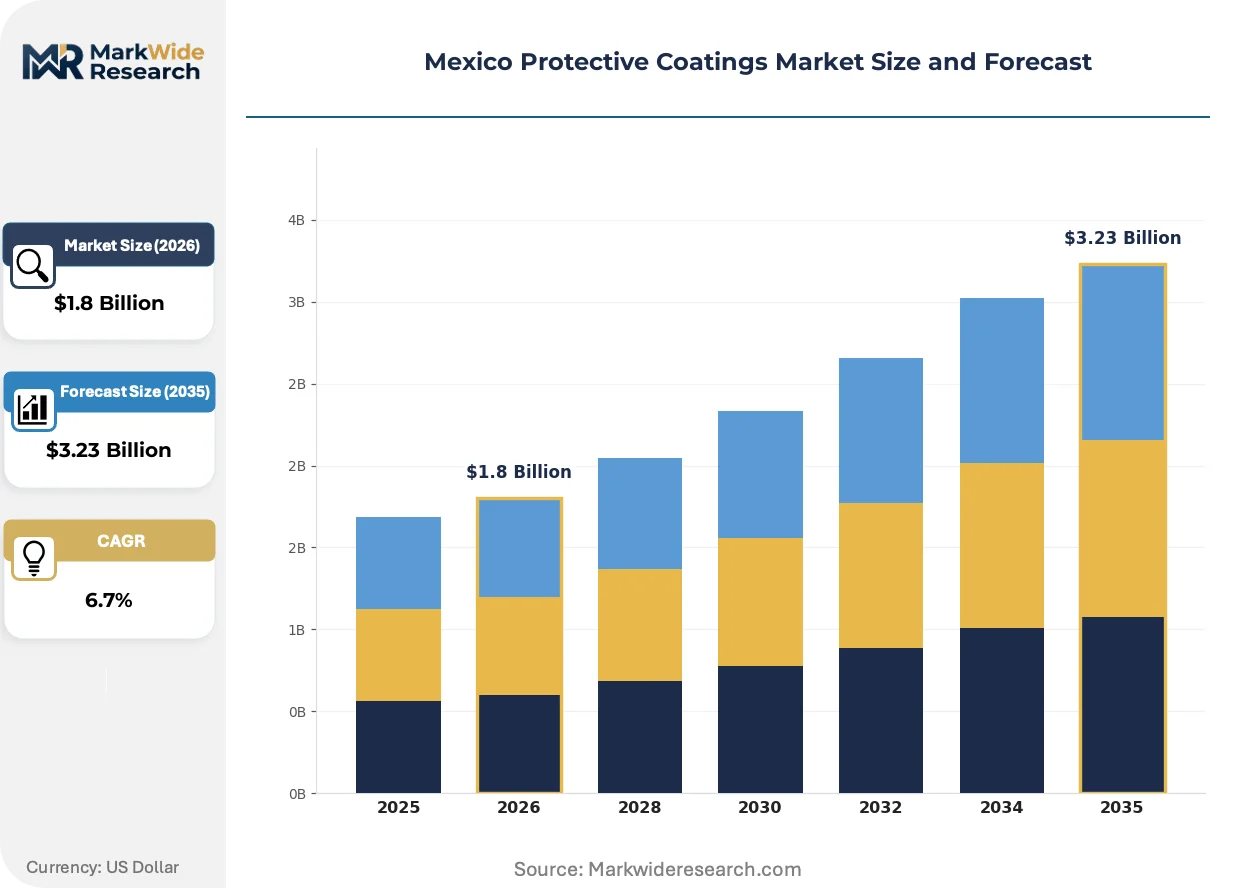
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Zinc-based End Use Industry: Construction, Automotive, Marine, Aerospace Application: Industrial, Commercial, Residential, Automotive Refinishing Technology: Solvent-borne, Waterborne, High Solids, Powder Coating |
| Companies Covered | Axalta Coating Systems, Akzo Nobel N.V., BASF SE, PPG Industries, Inc., The Sherwin-Williams Company, Hempel A/S, Jotun, Pinturas Osel, Pinturas Berel, SA de CV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Protective Coatings Market Shifts & Advancements
Coating chemistry convergence with digital asset monitoring is restructuring how Mexican industrial buyers specify and procure protective systems. Formulators now compete on predictive performance data rather than static warranty terms.
Self-healing microcapsule technology embedded in epoxy primers is rewriting maintenance economics for subsea pipelines and splash zone structures. PEMEX contractors pilot these systems at Ku-Maloob-Zaap field installations, compressing inspection intervals from annual to biennial cycles while reducing dry-docking costs for platform support vessels.
SEMARNAT enforcement of PROY-NOM-118-SEMARNAT-2017 amendments tightens VOC thresholds for industrial maintenance coatings to 340 g/L by 2027. Domestic blenders reformulate solvent-borne alkyds toward high-solids and waterborne alternatives, while importers face product registration suspensions for non-compliant portfolios. Marine and offshore segments absorb compliance costs most acutely given salt-spray performance requirements.
Integrated coating-plus-inspection service contracts displace traditional material-only procurement at major petrochemical complexes. Contractors now bundle surface preparation, application, and drone-enabled film thickness verification into single-source agreements. This consolidation concentrates procurement authority among integrated service providers in Tamaulipas refining corridor, marginalizing standalone coating distributors.
Mexico Protective Coatings Market Segmentation
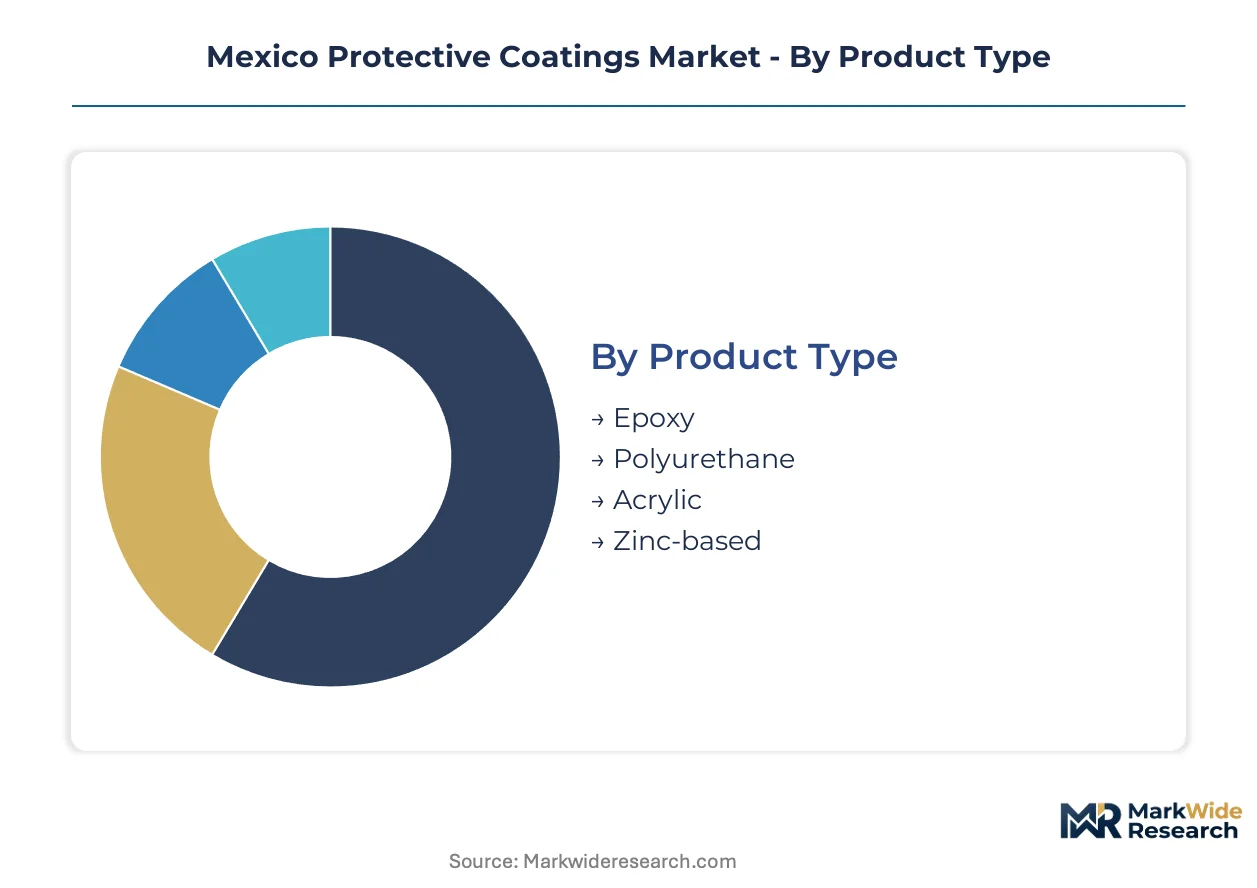
Protective coatings procurement in Mexico stratifies across performance requirements, regulatory compliance tiers, and asset lifecycle stages. Understanding these segment boundaries clarifies where formulation investments concentrate and how specification authority distributes among PEMEX contractors, port authorities, and private industrial operators.
Product Type:
Replacement cycles for protective coatings vary dramatically by chemistry, with offshore platforms demanding complete recoating every 5-7 years while automotive refinishing turns over every 3-5 years.
- Epoxy:Two-part thermosetting systems built from bisphenol-A and epichlorohydrin precursors deliver superior chemical resistance and adhesion to SSPC-SP 10 prepared steel. Demand concentrates in Cantarell and Ku-Maloob-Zaap offshore maintenance programs where high-build formulations withstand continuous salt spray exposure.
- Polyurethane:Aliphatic and aromatic isocyanate-cured topcoats provide UV stability and aesthetic retention for automotive OEM finishing and aerospace applications. Procurement clusters around Puebla automotive assembly corridors and Querétaro aerospace manufacturing parks where color matching and gloss retention define specification requirements.
- Acrylic:Thermoplastic resin systems offer rapid drying and weather resistance for architectural metal finishing and light industrial applications.
- Zinc-based:Inorganic zinc silicate and organic zinc-rich primers deliver sacrificial cathodic protection for structural steel in marine and petrochemical environments.
Epoxy sits at the top of the volume ranking, with polyurethane climbing the fastest as automotive production capacity expands across central Mexico.
End Use Industry:
Cost tier differentiation separates specification-grade marine systems from commodity construction coatings, with price spreads reflecting performance warranty terms and inspection certification requirements.
- Construction:Structural steel protection for commercial buildings, bridges, and infrastructure projects spans waterborne acrylics through high-performance fluoropolymer systems. Demand concentrates in Mexico City metropolitan area and Monterrey industrial corridor where NOM-001-SEMARNAT compliance drives waterborne adoption for interior applications.
- Automotive:OEM electrocoat primers, basecoats, and clearcoats integrate with assembly line curing systems to deliver chip resistance and appearance durability. Procurement flows through Volkswagen, Nissan, and Kia manufacturing complexes in Puebla, Aguascalientes, and Nuevo León where just-in-time delivery contracts dominate supplier relationships.
- Marine:Anti-fouling, anti-corrosive, and deck coating systems protect vessels, port infrastructure, and offshore platforms in Gulf of Mexico operations.
- Aerospace:Chromate-free pretreatments and polyurethane topcoats meet SAE AMS specifications for commercial and military aircraft maintenance.
Construction commands the largest procurement volume, while marine applications are gaining share fastest as port modernization accelerates at Altamira and Veracruz.
Application:
Application environment dictates surface preparation standards, film thickness requirements, and inspection protocols that separate industrial specifications from commercial and residential tiers.
- Industrial:Heavy-duty systems for manufacturing facilities, power generation, and chemical processing plants require abrasive blasting to near-white metal and multi-coat film builds exceeding 250 microns. Demand clusters in Tamaulipas petrochemical corridor and Tabasco refinery complexes where asset integrity programs mandate NACE-certified inspection.
- Commercial:Architectural metal finishing for retail, office, and institutional buildings balances aesthetics with moderate durability requirements.
- Residential:Decorative and protective coatings for metal roofing, fencing, and structural elements emphasize DIY application compatibility and color availability.
- Automotive Refinishing:Collision repair and custom finishing shops in Guanajuato and Jalisco automotive service clusters demand rapid cure systems and factory-match color libraries.
Industrial applications dominate specification complexity, with automotive refinishing expanding most quickly as vehicle fleet age increases repair frequency.
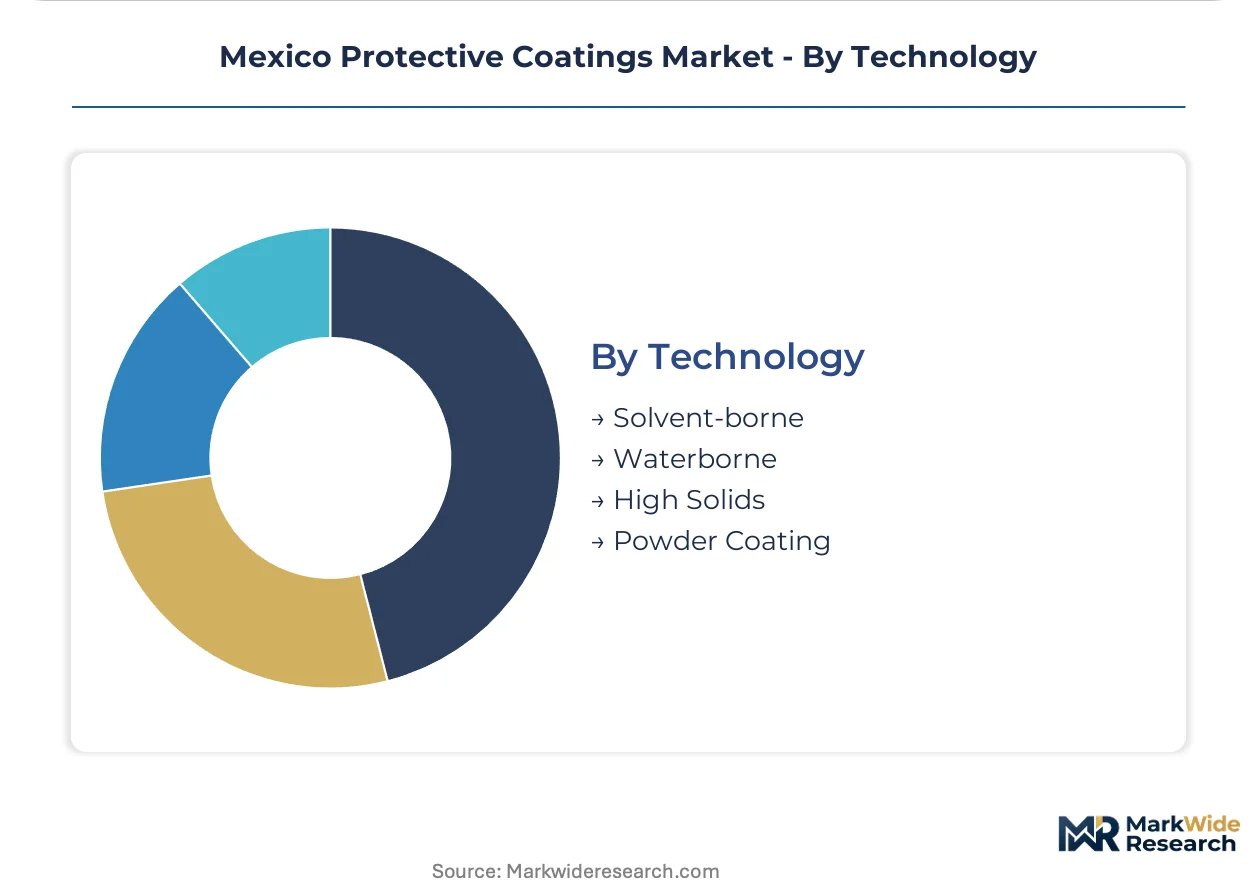
Technology:
Technology selection increasingly hinges on SEMARNAT enforcement trajectories, with pending NOM-118 amendments threatening registration continuity for legacy solvent-borne formulations.
- Solvent-borne:Conventional alkyd, epoxy, and polyurethane systems relying on aromatic and aliphatic hydrocarbon carriers deliver proven performance in humid tropical climates. Formulators face reformulation pressure as VOC thresholds tighten, with marine and offshore segments absorbing steepest compliance costs.
- Waterborne:Acrylic and polyurethane dispersions with reduced volatile content are gaining formulation sophistication for industrial maintenance and architectural applications. COFEPRIS fast-track registration for low-VOC products accelerates domestic blender market entry.
- High Solids:Reduced-solvent formulations maintaining application viscosity through advanced resin architectures bridge performance and compliance requirements.
- Powder Coating:Thermoset epoxy and polyester systems applied electrostatically and cured at elevated temperatures eliminate liquid carrier emissions entirely for metal fabrication and appliance manufacturing.
Solvent-borne technology retains the largest installed base, with waterborne systems gaining share fastest as domestic suppliers scale R&D investment ahead of regulatory deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are concentrating waterborne formulation capacity in Mexican states where SEMARNAT enforcement timelines lag coastal jurisdictions, creating temporary cost-of-compliance advantages for interior blenders serving industrial maintenance markets.
Veracruz
Offshore platform maintenance at Cantarell and Ku-Maloob-Zaap fields drives cyclical demand for high-build epoxy systems. NOM-001-SEMARNAT air quality standards tighten faster here than in Pacific states. The Coatzacoalcos petrochemical corridor anchors procurement for PEMEX contractor networks requiring NACE-certified inspection protocols.
Tamaulipas
Altamira port modernization and refinery complexes generate marine-grade anti-corrosive coating specifications. STPS workplace exposure enforcement intersects with SEMARNAT filings to create multi-agency compliance bottlenecks. The Madero-Altamira industrial zone concentrates integrated coating-plus-inspection service providers.
Nuevo León
Automotive assembly expansion at Kia and Toyota facilities pulls polyurethane topcoat demand from industrial maintenance segments. COFEPRIS chemical safety oversight operates through Monterrey regional offices with faster registration timelines than Gulf Coast jurisdictions. The Apodaca-Santa Catarina supplier park clusters just-in-time coating delivery contracts.
Jalisco
Automotive refinishing shops in Guadalajara metropolitan area absorb waterborne technology migration ahead of federal deadlines. PROY-NOM-118-SEMARNAT-2017 amendments face delayed implementation here relative to Veracruz. The El Salto industrial corridor hosts domestic blenders reformulating solvent-borne alkyds toward high-solids alternatives.
Yucatán Peninsula
Proyecto Eólico del Sureste preliminary engineering studies specify protective systems for monopile foundations in corrosive marine atmospheres. SEMARNAT regional enforcement capacity remains thinner than in established industrial corridors. The Progreso port expansion anchors early procurement for offshore wind supply chain development.
Mexico Protective Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational formulators dominating specification-grade marine and offshore procurement while domestic blenders capture price-sensitive industrial maintenance volumes. Market structure tilts toward consolidation in high-performance epoxy and polyurethane tiers where technical service capabilities determine contractor loyalty. Three archetypes define competitive positioning: integrated coating-plus-inspection service providers, waterborne technology specialists racing regulatory deadlines, and import-dependent distributors of zinc-rich primers and specialty corrosion inhibitors. Dominant competitive moves include backward integration into resin blending capacity and strategic partnerships with PEMEX-approved contractor networks.
Within the multinational specialist tier, Akzo Nobel N.V. and Hempel A/S occupy positions shaped by marine coating heritage and offshore platform maintenance relationships. PPG Industries, Inc. represents the automotive-refinish-to-industrial extension archetype, leveraging color matching capabilities developed in OEM segments. Domestic formulators Pinturas Osel and Pinturas Berel, SA de CV exemplify regional blending operations navigating VOC compliance transitions through reformulation partnerships with resin suppliers.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Akzo Nobel N.V. |
| BASF SE |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Hempel A/S |
| Jotun |
| Pinturas Osel |
| Pinturas Berel, SA de CV |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap blenders concentrated in Jalisco and Nuevo León anchor domestic supply capacity, translating fragmented ownership into pricing discipline that resists margin erosion despite feedstock volatility from Texas Gulf Coast petrochemical complexes. Their localized financing structures limit aggressive discounting, preserving premium positioning for NACE-certified application services while constraining price competition in specification-grade marine segments.
Pricing Analysis
Distributor margin layers absorb 15-25 points between resin manufacturers and applicator networks, compressing as integrated service providers consolidate procurement authority in Tamaulipas. Three-tier pricing structure across specification-grade marine systems, industrial maintenance formulations, and commodity construction coatings reflects certification burden and inspection warranty terms. Cost compression in solvent-borne alkyds intensifies because SEMARNAT registration suspensions threaten non-compliant portfolios. Automotive refinishing shops in Guanajuato exhibit highest price sensitivity, while PEMEX contractor networks prioritize performance guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese zinc dust pigment suppliers and European specialty corrosion inhibitor manufacturers, creating tariff exposure and logistics chokepoints for domestic formulators. Raw material dependencies center on bisphenol-A and epichlorohydrin from Texas, propylene derivatives from Louisiana, and titanium dioxide from Mississippi. Distribution runs through Veracruz-Tamaulipas corridor concentrators serving PEMEX networks, with Pacific Coast states underserved due to NACE inspector scarcity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with pending NOM-118-SEMARNAT amendments accelerating demand migration toward waterborne formulations ahead of VOC limit convergence with U.S. EPA benchmarks.
For Market Incumbents: Lock in PEMEX-approved contractor networks through exclusive coating-plus-inspection service bundling, defending against integrated multinationals expanding from marine specialties. Prioritize backward integration into captive resin blending capacity in Jalisco to hedge propylene price volatility from Texas Gulf Coast disruptions. For New Entrants and Emerging Players: Cloud-based asset management platforms embedding coating selection algorithms offer the most penetrable entry vector, targeting mid-size industrial maintenance operators in Pacific Coast states underserved by NACE-certified inspection infrastructure. White-space concentrates in Yucatán offshore wind supply chain pre-development, where Proyecto Eólico del Sureste engineering studies specify protective systems without established procurement relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic blenders navigating VOC compliance transitions through reformulation partnerships, offering 5-10 year viability windows tied to SEMARNAT enforcement trajectories. Acquisition targets should exhibit captive waterborne R&D pipelines and COFEPRIS fast-track registration capabilities. Monitor NOM-118 implementation delays in interior states as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Blending | Captive bisplorohydrin supply hedges Texas petrochemical price volatility for Jalisco formulators. |
| Waterborne Formulation R&D Scale-Up | Domestic blenders accelerate NOM-118 compliance ahead of SEMARNAT registration deadlines. |
| Integrated Coating-Plus-Inspection Contracts | Drone-enabled film thickness verification consolidates procurement authority in Tamaulipas corridor. |
| COFEPRIS Fast-Track Registration Investment | Streamlined chemical safety approvals reduce time-to-market for low-VOC product launches. |
| Digital Asset Management Platform Partnership | Cloud-based specification tools embed coating algorithms into PEMEX maintenance scheduling systems. |
Research Methodology
Coverage spans Mexico's Gulf Coast industrial corridor, central Mexico automotive clusters, and Yucatán offshore wind pre-development zones, with primary inputs from each. The approach combines interviews with PEMEX procurement officers, NACE-certified coating inspectors, domestic blender plant managers, and port authority engineering directors, validated against secondary sources including SEMARNAT regulatory filings, COFEPRIS chemical safety registrations, and customs trade data for resin and pigment imports. Bottom-up volume estimates from end-use facility audits triangulate with top-down value projections from distributor revenue analysis.
Granularity-level framing models protective coatings demand at product chemistry, end-use industry, application environment, and technology tier dimensions, with additional segmentation by state-level regulatory enforcement intensity. CAGRs derive from asset lifecycle replacement curves for offshore platforms, automotive refinishing frequency, and construction project pipelines across the projection horizon. Forecast inputs incorporate PEMEX capital expenditure disclosures, port modernization tender announcements, and automotive OEM capacity expansion schedules.
The model assumes a particular technology adoption path; alternative pathways for waterborne epoxy marine systems would alter the outlook if salt-spray performance gaps persist against solvent-borne benchmarks. Forecasts reflect assumptions about SEMARNAT enforcement consistency, COFEPRIS registration processing timelines, and petrochemical feedstock price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Corrosion Protection Polymer Coating Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
CVD Coating Technology Market
Coatings
Global Diamond Coatings Market
Coatings
North America Superhydrophobic Coating Market
Coatings
US Industrial Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Topcoat Market
Coatings
Cool Roof Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Pure Epoxy Powder Coatings Market