
 Waterproof Coating Market | 2026-2036
Waterproof Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Waterproof Coating Market Analysis
Modular waterproofing kits that bundle primers, membranes, and topcoats into single-specification systems is shifting how commercial contractors evaluate suppliers. BASF SE leverages its polymer chemistry portfolio to supply integrated acrylic and polyurethane systems across European construction channels. The Sherwin-Williams Company anchors its position through controlled distribution networks that service North American institutional roofing contracts. Sika AG specializes in cementitious and bituminous technologies for tunnel and bridge applications, competing on specification depth rather than price.
Waterproof coatings are film-forming barriers engineered to resist hydrostatic pressure, typically formulated with acrylic, polyurethane, epoxy, or silicone resin bases and applied at dry-film thicknesses of 0.5 mm to 3 mm to prevent substrate degradation. Their primary purpose is to extend structural service life by blocking moisture ingress in concrete, metal, and composite surfaces exposed to weathering or immersion. Acrylic formulations lead residential and light commercial segments due to breathability and ease of application, while polyurethane commands premium positioning in automotive underbody and marine deck protection where elastomeric recovery matters. Epoxy technology occupies industrial flooring and electronics potting niches where chemical resistance and dielectric stability justify higher material costs and specialized spray or dip coating application methods.
EPA VOC regulations in the United States, REACH chemical authorization in Europe, and China's MEE emissions standards collectively constrain solvent-based formulation options and redirect R&D spending toward compliant waterborne and high-solids platforms. The EU Green Deal's embodied carbon tracking for construction materials further tightens specification criteria for publicly funded infrastructure projects. Stakeholders must monitor how building code harmonization between national regulators affects cross-border product certification costs and determine whether regional formulation tailoring or unified platform strategies better preserve margin structures.
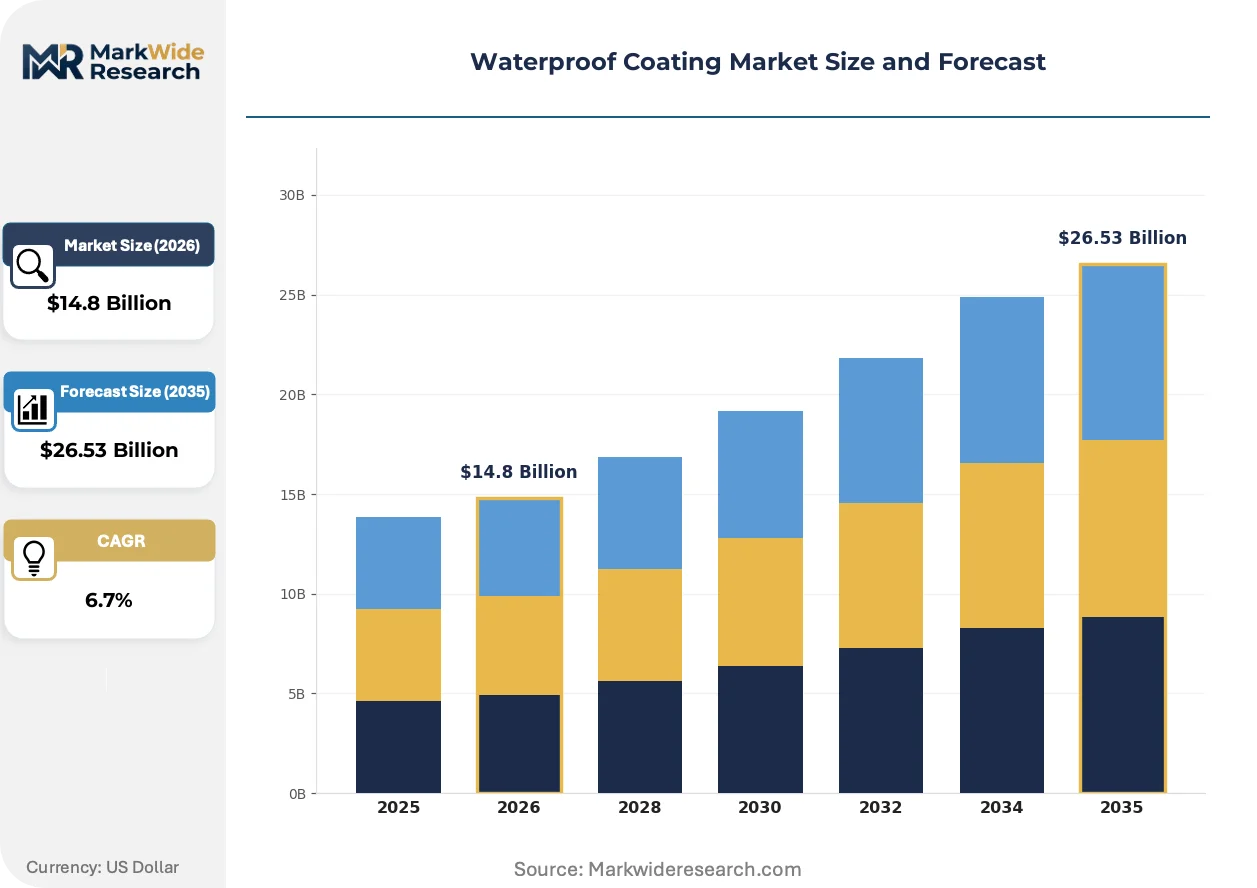
Market Dynamics
The waterproof coating sector faces a structural pivot as waterborne polyurethane and acrylic formulations displace solvent-based systems under tightening VOC mandates across major construction markets.
Growth Catalysts
- Green building envelope codes:Municipalities in Germany and California now mandate moisture barriers for commercial envelope retrofits, pulling cementitious and bitumen-modified systems into specification pipelines.
- REACH chemical authorization:The EU's tightening authorization lists for isocyanates and aromatic solvents are accelerating R&D migration toward compliant waterborne platforms with equivalent hydrostatic resistance.
- Urban renewal in China:Shanghai and Beijing infrastructure waterproofing programs absorb rising bitumen-modified coating volumes for tunnel linings and bridge decks.
Market Restraints
- Petrochemical input volatility:MDI and polyether polyol feedstock costs swing with crude oil indices, compressing margin predictability for polyurethane system manufacturers.
- Application skill concentration:Certified spray applicators for high-build elastomeric membranes cluster in coastal US and German industrial zones, creating service bottlenecks for inland projects.
- Cementitious performance ceiling:Cement-based crystalline systems face crack-bridging limitations below 0.3 mm substrate movement, restricting their specification in seismic zones.
Strategic Opportunities
- Modular kit standardization:Bundled primer-membrane-topcoat systems reduce contractor procurement friction and enable specification lock-in for integrated suppliers.
- India's Smart Cities Mission:Metro rail and underground utility waterproofing in Mumbai and Delhi creates demand for tunnel-grade bituminous membranes.
- EU Green Deal embodied carbon tracking:Public infrastructure tenders now reward low-carbon coating formulations with specification preference points.
Industry Challenges
- Cross-border certification fragmentation:Divergent fire-rating and VOC test methods between US ASTM, European EN, and Chinese GB standards force redundant product qualification cycles.
- Legacy substrate compatibility:New waterborne chemistries require moisture-content thresholds and surface preparation protocols that conflict with aged concrete conditions in renovation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waterproof Coating Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Silicone Application: Construction, Automotive, Marine, Electronics End User: Residential, Commercial, Industrial, Institutional Technology: Spray Application, Brush Application, Roller Application, Dip Coating |
| Companies Covered | BASF SE, The Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., Sika AG, RPM International Inc., Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waterproof Coating Market Emerging Trajectories
Digital formulation tools and on-site quality verification systems are compressing development cycles and reducing application failure rates across commercial roofing and civil infrastructure segments.
Spray-applied polyurea equipment with real-time temperature and pressure monitoring is automating membrane thickness consistency in North American industrial roofing contracts. Facility managers at data centers and logistics warehouses specify these systems for rapid-cure installation windows. The technology is automating quality assurance steps previously requiring manual mil-gauge verification, reducing callback rates and warranty exposure for applicators.
REACH authorization timelines for diisocyanates now require professional training certification for industrial users across EU member states. Coating formulators face reformulation deadlines to exclude restricted substances or document safe-use conditions. Marine and offshore segments in Norway and the Netherlands absorb compliance costs earliest due to stringent national occupational health enforcement.
Specification bundling is consolidating contractor purchasing decisions around single-source membrane systems with integrated warranty coverage. Commercial roofing distributors in Texas and Florida now stock complete acrylic and polyurethane kits rather than component chemicals. This pattern concentrates most visibly in hurricane-prone US Gulf Coast states where wind-uplift certification requirements favor pre-tested system configurations over field-assembled alternatives.
Waterproof Coating Market Segmentation
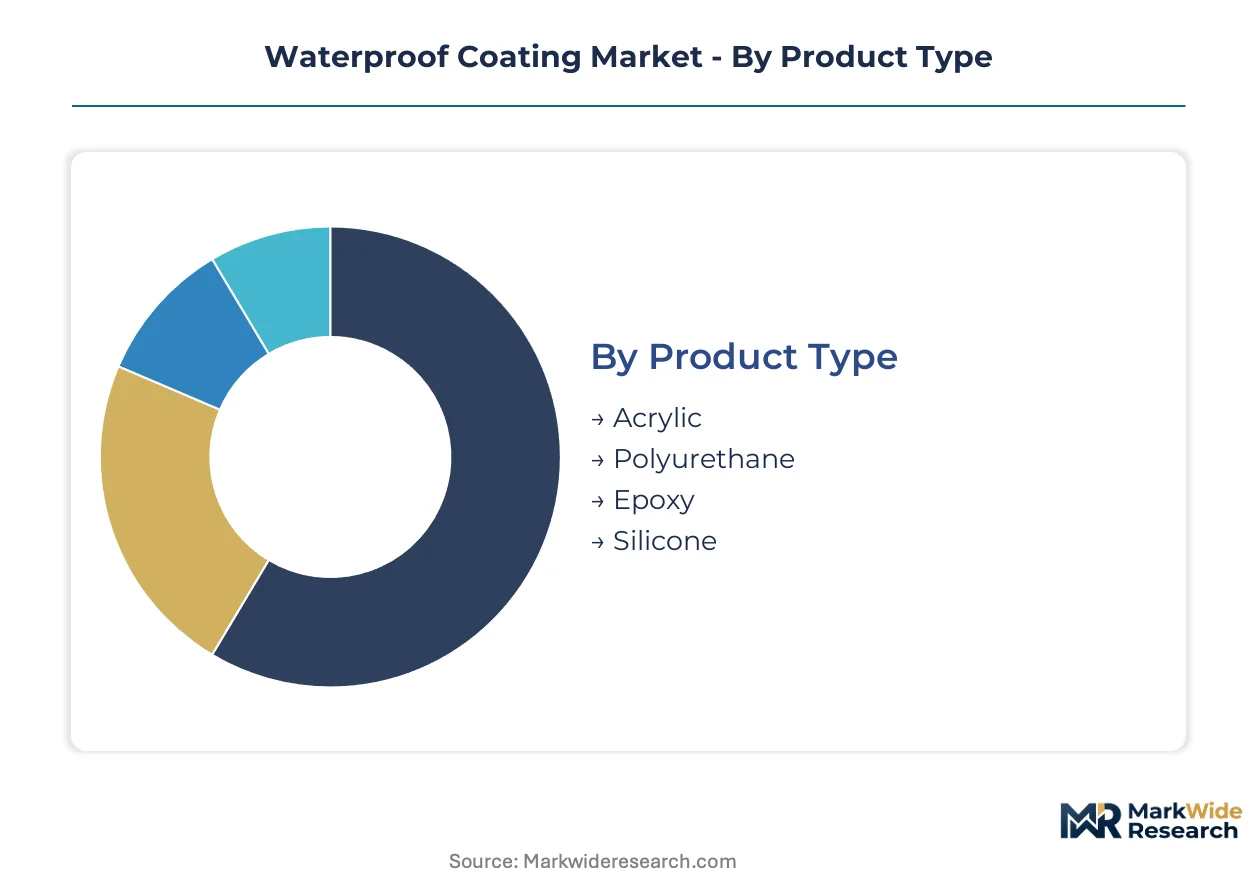
Waterproof coating procurement decisions fragment across resin chemistry, installation environment, and performance specifications. Each segmentation axis carries distinct margin profiles and capital requirements that reshape competitive positioning across construction, automotive, and industrial channels.
Product Type:
Capital intensity varies sharply across resin platforms, with polyurethane and epoxy systems demanding specialized reactor infrastructure and isocyanate handling protocols that acrylic and silicone formulations avoid.
- Acrylic:Waterborne emulsions of polymethyl methacrylate and styrene-acrylic copolymers cure through ambient moisture evaporation. Residential re-roofing in California and Florida absorbs rising volumes as building codes tighten envelope moisture-barrier mandates for energy retrofits.
- Polyurethane:Two-component aromatic and aliphatic systems require precise MDI-to-polyol metering equipment. Marine deck sealing in Hamburg and Rotterdam commands premium elastomeric recovery specifications where thermal cycling resistance justifies material cost premiums.
- Epoxy:Bisphenol-A and novolac resins crosslink with amine hardeners for chemical-resistant industrial flooring.
- Silicone:Moisture-cure alkoxy and acetoxy systems service high-temperature exhaust stack and HVAC duct applications.
Most installed capacity flows through acrylic. Expansion is steepest in polyurethane.
Application:
Application-specific formulation requirements create divergent qualification barriers, with construction and marine segments imposing the most extensive certification protocols for waterproofing performance.
- Construction:Above-grade and below-grade membrane systems for concrete envelopes, plaza decks, and green roofs. Tunnel waterproofing in Shanghai and Beijing infrastructure programs absorbs bitumen-modified and cementitious coating volumes for structural durability.
- Automotive:Underbody chip-resistant coatings and seam sealers requiring stone-impact resistance and cathodic delamination protection. German OEM assembly plants specify polyurethane spray systems for chassis corrosion warranties extending beyond 10 years.
- Marine:Ballast tank and deck coatings for salt-spray immersion environments.
- Electronics:Conformal coatings for printed circuit board moisture and ionic contamination protection.
Construction channels dominate volume throughput. Marine specifications are gaining share fastest.
End User:
End-user procurement sophistication stratifies by project scale and warranty exposure, with institutional buyers leveraging specification bundling that residential contractors rarely access.
- Residential:Single-family and multi-family re-roofing and basement waterproofing. Texas and Florida distributors now stock modular acrylic and polyurethane kits with integrated wind-uplift certification for hurricane-prone coastal zones.
- Commercial:Office, retail, and hospitality envelope retrofits. California Title 24 energy code compliance pulls cementitious and bitumen-modified systems into commercial envelope specifications for moisture-barrier continuity.
- Industrial:Manufacturing facility flooring and secondary containment.
- Institutional:Hospital, school, and government building projects with embodied-carbon tracking requirements under EU Green Deal procurement guidelines.
Commercial projects anchor specification volume. Institutional tenders are expanding most quickly.
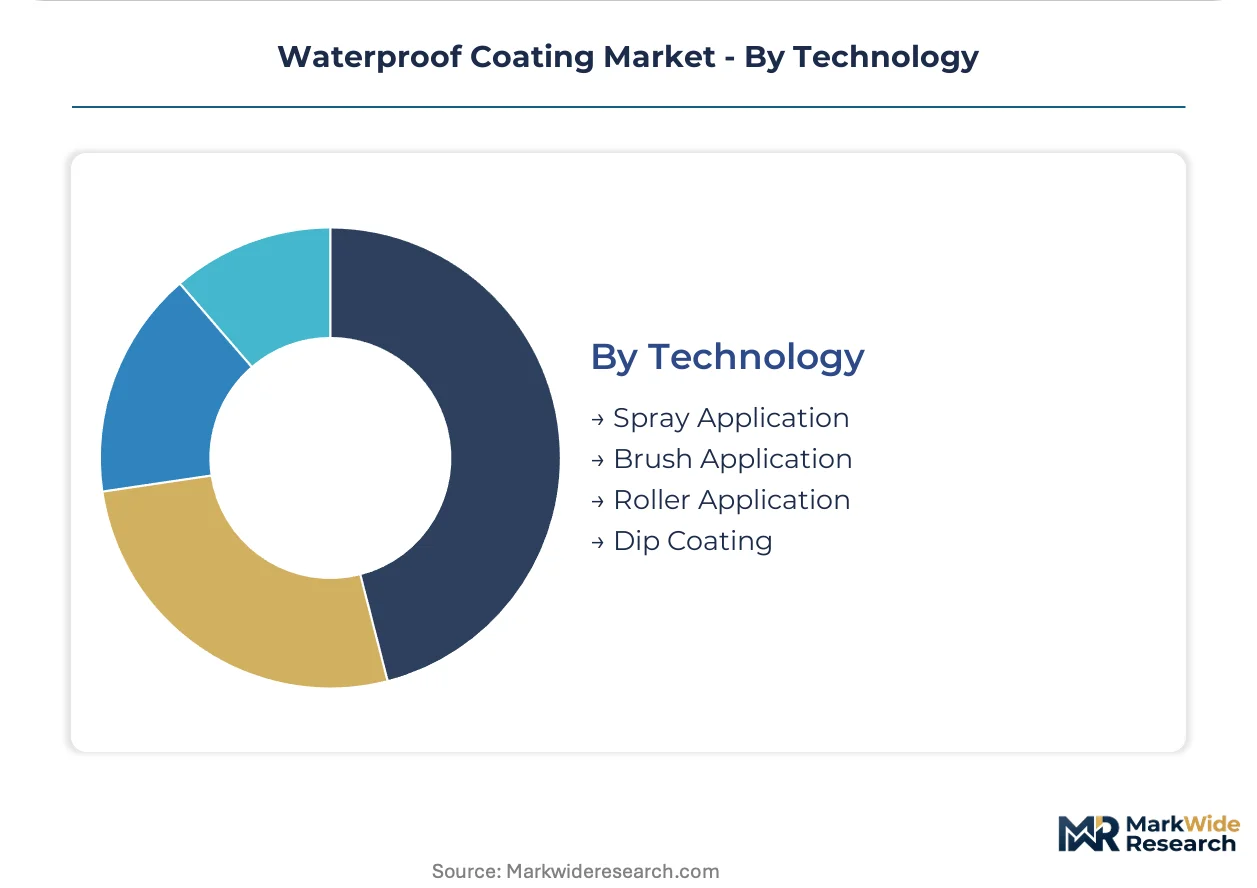
Technology:
Application technology selection constrains achievable film thickness and surface preparation tolerance, with spray systems requiring the steepest capital investment in equipment and certified labor.
- Spray Application:Airless and plural-component equipment for high-build elastomeric membranes. Data center roofing in Virginia and Texas specifies polyurea spray systems with real-time temperature monitoring for rapid-cure installation windows.
- Brush Application:Manual application for detail work and small-area touch-up. Residential basement waterproofing in Germany relies on brush-applied crystalline cementitious coatings for negative-side hydrostatic resistance.
- Roller Application:Medium-build acrylic and polyurethane systems for flat roof restoration.
- Dip Coating:Immersion application for electronics potting and small-component batch processing.
Spray systems carry the heaviest equipment investment. Brush application maintains the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Waterproof coating technology first achieved industrial scale in Germany during the post-war reconstruction era, with bituminous membrane systems developed for tunnel and bridge infrastructure. German chemical engineering expertise subsequently diffused to North American and Asian construction markets through licensing agreements and joint ventures.
United States
Commercial roofing retrofits in California and Texas absorb rising acrylic and polyurethane volumes as Title 24 energy codes tighten envelope moisture-barrier requirements. EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulation options. Houston and Miami distributors now stock modular coating kits with pre-certified wind-uplift ratings for hurricane-prone coastal zones.
Germany
Tunnel waterproofing programs in Hamburg and Munich drive specification of bitumen-modified and cementitious systems for underground infrastructure durability. REACH authorization timelines for diisocyanates mandate professional training certification for industrial coating applicators across EU member states. The Ruhr industrial cluster hosts specialized spray applicator training centers serving Central European civil engineering contractors.
China
Urban renewal initiatives in Shanghai and Beijing infrastructure programs absorb rising volumes of bitumen-modified coatings for bridge deck and tunnel lining applications. MEE emissions standards enforce solvent-content limits that redirect manufacturing investment toward waterborne polyurethane platforms. The Yangtze River Delta concentration of construction chemical production is expanding crystalline cementitious capacity for below-grade waterproofing.
India
Metro rail and underground utility waterproofing in Mumbai and Delhi creates demand for tunnel-grade bituminous membrane systems under the Smart Cities Mission. BIS certification requirements for construction chemicals impose testing protocols that favor established multinationals with in-country laboratory infrastructure. The Gujarat chemical manufacturing belt is attracting joint venture investment for waterborne acrylic production capacity.
Japan
Seismic-resistant infrastructure specifications in Tokyo and Osaka favor polyurethane systems with elastomeric crack-bridging performance above 0.5 mm substrate movement. METI industrial standards for building material durability influence coating procurement criteria for public works tenders. The Kansai industrial region maintains specialized applicator networks for high-build marine deck coatings serving shipbuilding and port maintenance contracts.
Waterproof Coating Market Vendor Landscape
Premium-margin players sit above commodity-margin players across specification depth and integrated system bundling. The vendor base stratifies into three tiers: multinational chemical conglomerates with polymer chemistry portfolios, specialized construction chemical firms with civil infrastructure focus, and regional coating blenders serving price-sensitive residential channels. Consolidation pressure concentrates among mid-scale European and North American players seeking geographic coverage. Dominant competitive moves include modular kit standardization and specification bundling with integrated warranty coverage.
Within the multinational chemical tier, BASF SE and The Sherwin-Williams Company exemplify divergent distribution strategies. BASF SE anchors European construction channels through controlled specification relationships with engineering firms. The Sherwin-Williams Company occupies North American institutional roofing through distributor networks stocking pre-certified system configurations. Sika AG represents the specialized infrastructure archetype, with positioning concentrated on tunnel and bridge applications where technical specification depth outweighs price competition.
| Leading Market Players |
|---|
| BASF SE |
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Sika AG |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Henkel AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon tracking gates qualified supply and premium-tier pricing access for waterproof coating procurement, as public infrastructure tenders now reward low-carbon formulations with specification preference points that commodity blenders cannot meet. REACH authorization timelines for diisocyanates further constrain which manufacturers can service European institutional contracts, concentrating pricing power among integrated suppliers with compliant waterborne platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates waterproof coating procurement, separating specification-grade polyurethane systems from commodity acrylic emulsions and unbranded bitumen-modified alternatives. Price differentiation rests on certification grade—REACH-compliant waterborne platforms command material cost premiums over solvent-based equivalents—and volume scale, with institutional buyers leveraging bundled kit procurement. Cost compression in standard-tier acrylics is intensifying because petrochemical input volatility in MDI and polyether polyol feedstocks squeezes margin predictability. Residential contractors exhibit highest price sensitivity, while data center and hospital procurement teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Shanghai anchor hub-and-spoke patterns that stock modular coating kits with pre-certified wind-uplift and fire-rating documentation. Manufacturing concentrates in Germany, China, and the United States, with the Yangtze River Delta and Ruhr industrial cluster hosting specialized reactor infrastructure for isocyanate handling. Raw material dependencies draw from crude oil-indexed MDI supply, polyether polyol feedstocks, and bitumen derivatives. Single-source vulnerability in certified spray applicator networks creates service bottlenecks for inland projects. Distribution runs through commercial roofing distributors and construction chemical specialists rather than generalist building material merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterproof coating demand compounds as a regulatory function, with California Title 24 energy codes and EU Green Deal procurement guidelines mandating moisture-barrier continuity for commercial envelope retrofits.
For Market Incumbents: Hedge against waterborne formulation margin erosion by securing backward integration into polyether polyol supply and expanding certified applicator training capacity in Texas and Florida hurricane corridors. Lock in specification bundling with integrated warranty coverage to defend against emerging modular kit competitors. For New Entrants and Emerging Players: Begin with India's Smart Cities Mission metro rail waterproofing programs, where BIS certification barriers favor joint venture structures over greenfield investment. Target tunnel-grade bituminous membrane supply to Mumbai and Delhi infrastructure contractors through technical partnership with established German or Japanese formulation licensees. For Investors and Strategic Acquirers: Roll-up economics work for specialized construction chemical firms with civil infrastructure focus because specification depth in tunnel and bridge applications creates durable margin structures resistant to price competition. Monitor REACH authorization timeline acceleration as the inflection signal for waterborne platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Waterborne polyurethane capacity expansion satisfies REACH and EPA VOC mandates while capturing EU Green Deal tender preference points. |
| Backward Integration | In-house MDI and polyether polyol production insulates margin structures from crude oil index volatility. |
| Long-term Supply Agreement | Pre-committed acrylic emulsion offtake secures feedstock allocation for California Title 24 compliance-driven demand surges. |
| Joint Venture | Local formulation partnerships in Gujarat and Maharashtra navigate India's BIS certification requirements for Smart Cities Mission contracts. |
| Capacity Expansion | Crystalline cementitious coating plants in the Yangtze River Delta serve Shanghai and Beijing infrastructure waterproofing programs. |
Methodological Framework
Bottom-up construction channel modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with commercial roofing contractors, civil engineering procurement managers, spray applicator network operators, and construction chemical R&D directors combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings of listed coating manufacturers, and national building code regulatory databases. Triangulation across these sources ensures demand estimates align with verified supply-side capacity.
Historical trendline analysis of resin platform adoption rates and application technology penetration informs the projection framework across the analysis window. Segmentation dimensions include resin chemistry tier, installation environment classification, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to verified baseline volumes, incorporating construction spending forecasts, energy code adoption timelines, and infrastructure program announcements as industry-specific inputs.
Several conditions sit outside the modeled scope, including force majeure disruptions to petrochemical feedstock supply, abrupt regulatory reversals on VOC limits, and technological substitution by membrane alternatives. Forecasts reflect assumptions about continued code harmonization and infrastructure spending continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Egyptian Protective Coatings Market
Coatings
Silicone Coating Market
Coatings
Packaging Coatings Market
Coatings
Wire Enamels Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Clear Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
Marine Nanocoating Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Powder Coating Booth Market
Coatings
Europe Protective Coatings Market