
 Global Anti-Reflective Coatings Market | 2026-2036
Global Anti-Reflective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Reflective Coatings Market Foresight
The capital-intensity divergence between vacuum-deposition specialists and wet-chemical coaters is collapsing as sol-gel and spray-coating equipment costs decline. ZEISS sustains premium positioning through captive ion-beam sputtering systems for ophthalmic lenses. EssilorLuxottica leverages its integrated lens-finishing network to control coating application at scale. PPG Industries anchors industrial anti-reflective supply through automotive and architectural glass channels.
Anti-reflective coatings are thin-film interference structures, typically 100–200 nanometers per layer, engineered to minimize Fresnel reflection at substrate-air interfaces through destructive interference of reflected wavefronts. Physical vapor deposition remains the dominant manufacturing route for precision optics, depositing metal oxide stacks such as magnesium fluoride and silicon dioxide under high-vacuum conditions. Multilayer coatings command the highest value share in optical instruments and aerospace components where broadband suppression below 0.5% reflectance is required. Sol-gel-processed coatings are gaining traction in solar panel applications where large-area, low-temperature processing reduces unit costs.
The EPA regulates hazardous air pollutant emissions from coating operations under National Emission Standards, while REACH restricts perfluorinated substances used in some hydrophobic topcoats. China's GB standards and the EU RoHS directive constrain heavy-metal content in electronics-facing coatings. Stakeholders must monitor evolving substance restrictions and deposition-energy regulations as sustainability criteria penetrate procurement specifications across OEM supply chains.
Market Dynamics
Multilayer vacuum-deposited coatings are ceding ground to sol-gel and spray-applied alternatives as photovoltaic manufacturers prioritize throughput over absolute optical performance, compressing value capture for precision deposition specialists.
Growth Catalysts
- Photovoltaic Deployment:Solar panel manufacturers in China are scaling multilayer coating procurement to match domestic cell production capacity expansion. Utility-scale project pipelines drive coating volume.
- REACH Phase-Down:The European Union's volatile organic compound limits on coating formulations are accelerating waterborne and low-VOC process adoption. Reformulation investments open substitution windows.
- Ion-Beam Sputtering:Captive ion-beam systems for ophthalmic applications enable sub-0.5% reflectance specifications. Premium lens finishing networks leverage this capability for differentiation.
Market Restraints
- Fluoropolymer Feedstock Concentration:Perfluorinated precursor supply concentrates among Japanese and Chinese chemical producers. Hydrophobic topcoat formulation costs track fluorochemical availability.
- Physical Vapor Deposition Scale Limits:Batch vacuum chambers constrain coating throughput for architectural glass. Wet-chemical alternatives sacrifice broadband performance for area coverage.
- EPA Hazardous Air Pollutant Compliance:National Emission Standards for coating operations mandate thermal oxidizer installation. Capital requirements disproportionately burden mid-scale applicators.
Strategic Opportunities
- India Solar Manufacturing:Production-linked incentive schemes for domestic photovoltaic module assembly create coating demand. Imported cell processing equipment requires local AR film supply.
- Automotive HUD Integration:Windshield-embedded augmented reality displays demand angular-selective anti-reflective stacks. Tier-1 glass suppliers are qualifying new coating architectures.
- EU Green Deal Procurement:Public sector buying criteria now weight lifecycle carbon in optical component selection. Low-temperature sol-gel processes qualify for preferential sourcing.
Industry Challenges
- Thin-Film Process Engineering Talent:Vacuum deposition and interference design expertise concentrates among aging specialists. Knowledge transfer gaps threaten process consistency.
- Cross-Border Substance Notification:REACH and GB standard divergence creates dual registration burdens for coating formulators. Harmonized dossier preparation consumes technical resources.
- Legacy Coating Removal:Refurbishment of coated optical assemblies requires compatible stripping chemistries. Damage-free substrate recovery remains technically demanding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Reflective Coatings Market |
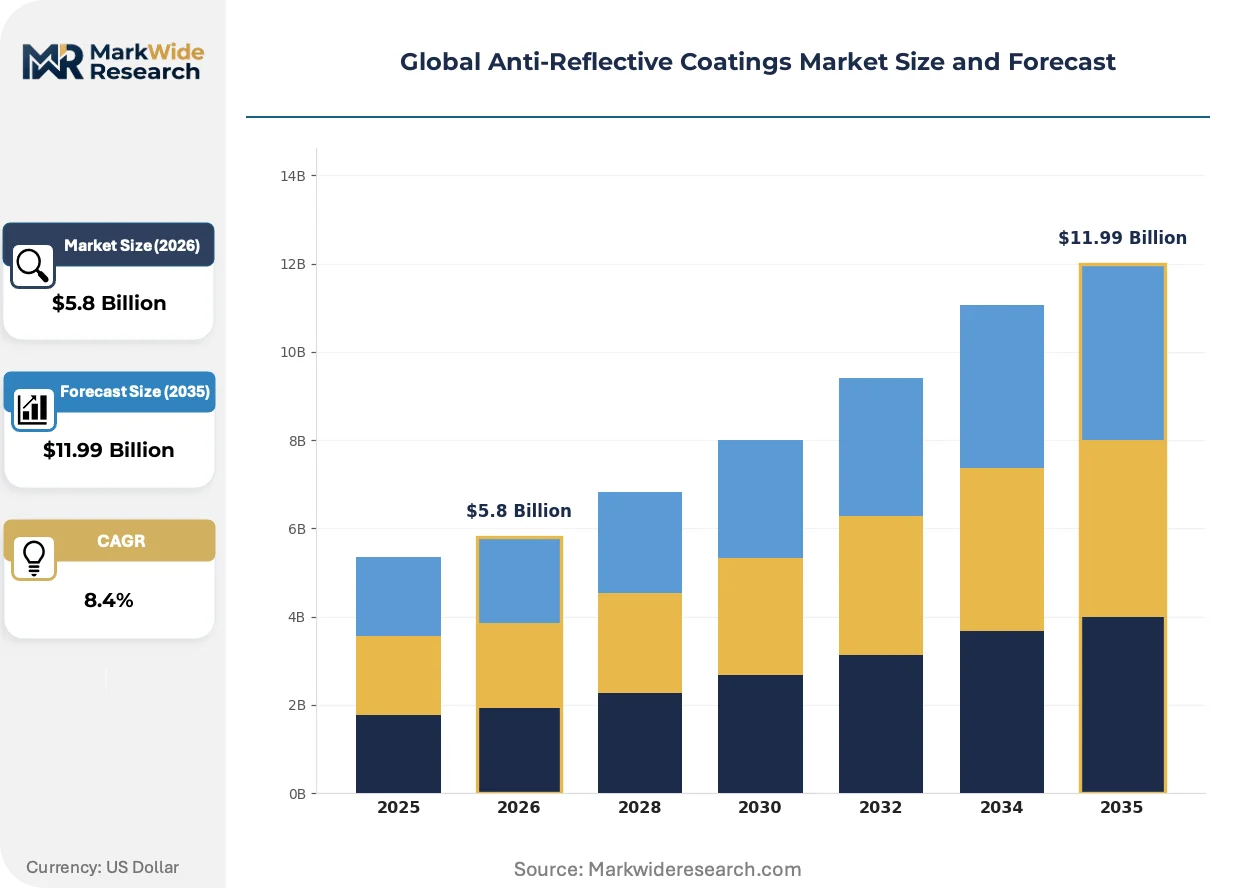
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Single Layer, Multilayer, Gradient Index, Nano-Structured, Hybrid Application: Consumer Electronics, Optical Instruments, Automotive Lighting, Solar Panels, Aerospace Components Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Sol-Gel Process, Spin Coating, Spray Coating End User: OEM Manufacturers, Optical Lens Producers, Solar Power Companies, Aviation Equipment Makers, Electronics Assemblers |
| Companies Covered | ZEISS, EssilorLuxottica, PPG Industries, HOYA Corporation, DuPont, Honeywell International Inc., AGC Inc., Corning Incorporated, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Reflective Coatings Market Shifts & Advancements
Deposition technology convergence and regulatory substance restrictions are compressing traditional process hierarchies while opening entry paths for novel coating architectures.
Sol-gel silica-titania hybrid coatings are displacing electron-beam evaporated magnesium fluoride in solar panel cover glass. Chinese photovoltaic manufacturers now specify spray-applied single-layer treatments that trade marginal reflectance reduction for tenfold throughput gains. This displacement is collapsing the historical premium attached to vacuum-deposited solar coatings.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic topcoats for eyewear and display applications. ECHA substance evaluation timelines are compressing supplier transition windows. European coating houses are accelerating silicone-based water-repellent alternatives to maintain OEM qualification status.
Direct procurement relationships between solar panel assemblers and coating material suppliers are bypassing traditional applicator intermediaries. Chinese cell manufacturers now specify raw sol-gel precursors for in-house coating lines. This channel restructuring concentrates formulation expertise while fragmenting application service revenue pools.
Global Anti-Reflective Coatings Market Segmentation
Anti-reflective coating specifications diverge sharply across end-use requirements, with photovoltaic manufacturers tolerating higher reflectance for throughput gains while aerospace and precision optics demand sub-0.5% performance. Segmentation reveals where sol-gel and spray alternatives displace vacuum-deposited stacks, and which customer types retain premium multilayer procurement.
Coating Type:
Sol-gel spray systems exert the strongest substitution pressure on vacuum-deposited architectures, compressing value capture in segments where absolute optical performance is negotiable.
- Multilayer:Vacuum-deposited metal oxide stacks of magnesium fluoride and silicon dioxide achieve broadband reflectance below 0.5% across visible and near-infrared spectra. Aerospace components and high-end optical instruments in Germany and Japan specify these coatings exclusively, with ion-beam sputtering systems required for qualification.
- Single Layer:Quarter-wave magnesium fluoride films deposited by electron-beam evaporation dominate ophthalmic lens finishing. EssilorLuxottica's captive coating network processes millions of lenses annually at this specification tier.
- Gradient Index:Continuous refractive index variation eliminates discrete layer interfaces for enhanced durability in military optics. Limited commercial deployment restricts this architecture to defense contractor supply chains.
- Nano-Structured:Moth-eye surface textures replicate biological anti-reflective mechanisms without thin-film deposition. Research-stage scalability constraints prevent volume adoption despite exceptional broadband performance.
- Hybrid:Combined sol-gel base layers with vapor-deposited topcoats balance cost and performance for mid-tier display applications. Chinese panel assemblers evaluate this architecture for television cover glass.
Single layer coatings anchor the volume base through eyewear demand while multilayer specifications gain share at the steepest rate in solar and aerospace procurement.
Application:
Cost tier stratification separates commodity cover glass from qualification-intensive optical systems, with automotive HUD integration emerging as a premium growth corridor.
- Solar Panels:Chinese photovoltaic manufacturers specify spray-applied sol-gel silica-titania hybrids that sacrifice marginal reflectance reduction for tenfold throughput gains over electron-beam evaporation. LONGi and Trina Solar have brought coating lines in-house, procuring raw precursors directly.
- Optical Instruments:Microscopy and telescope objectives require sub-0.5% reflectance across 400-1000nm wavelengths. ZEISS maintains captive ion-beam sputtering capacity for this specification tier, with qualification cycles exceeding 18 months.
- Consumer Electronics:Smartphone and tablet cover glass demands scratch-resistant anti-reflective treatments at sub-dollar unit costs. PVD alternatives cede ground to sol-gel spray systems as display sizes exceed 10 inches.
- Automotive Lighting:Headlamp lenses require thermal stability to 150°C for LED proximity. Silicone hardcoat-AR combinations from PPG Industries dominate this specification band.
- Aerospace Components:Satellite optical systems and cockpit displays specify radiation-hardened multilayer stacks. ITAR and EAR export controls constrain supplier pools to cleared U.S. and European coating houses.
Solar panel applications command the largest absolute volume while automotive HUD integration climbs fastest as tier-1 glass suppliers qualify angular-selective stacks.
Technology:
Deposition method selection tracks substrate size and thermal budget, with wet-chemical routes capturing area-intensive applications below 200°C processing temperatures.
- Physical Vapor Deposition:Electron-beam and thermal evaporation of metal fluorides and oxides under high vacuum delivers the densest, most uniform films. Precision optics in Switzerland and Japan rely exclusively on PVD for qualification-critical components.
- Sol-Gel Process:Hydrolysis and condensation of metal alkoxides enables large-area coating at ambient pressure. Chinese solar panel manufacturers have standardized this route for cover glass exceeding 2 square meters.
- Spray Coating:Pneumatic or ultrasonic atomization of sol-gel precursors achieves coating speeds incompatible with vacuum batch processing. Throughput advantages compensate for 0.3-0.5% higher residual reflectance in utility-scale solar.
- Chemical Vapor Deposition:Plasma-enhanced CVD deposits silicon nitride and oxynitride films for display applications requiring conformal coverage on textured substrates. Mid-scale capital requirements limit adoption to dedicated display glass lines.
- Spin Coating:Centrifugal spreading of liquid precursors dominates laboratory and small-batch optical fabrication. Wafer-scale semiconductor optics and research quantities of custom interference filters specify this method.
Sol-gel processing anchors the volume base through photovoltaic adoption while spray coating variants expand most quickly as throughput specifications tighten.
End User:
Customer type determines procurement channel structure, with solar power companies fragmenting applicator revenue through direct precursor purchasing.
- Solar Power Companies:LONGi, Trina Solar, and JinkoSolar have internalized coating application, procuring sol-gel precursors from chemical suppliers rather than finished films. This channel restructuring concentrates formulation expertise with material vendors.
- OEM Manufacturers:Automotive and consumer electronics assemblers specify coating performance while outsourcing application to tier-2 suppliers. PPG Industries and Nippon Paint anchor industrial supply through qualified applicator networks.
- Optical Lens Producers:EssilorLuxottica and Hoya maintain captive coating capacity for prescription lens finishing. Ion-beam sputtering investments differentiate premium product tiers.
- Electronics Assemblers:Foxconn and Luxshare Precision specify anti-reflective treatments for display modules without direct coating ownership. Contract manufacturers rely on qualified glass substrate suppliers.
- Aviation Equipment Makers:Boeing, Airbus, and tier-1 avionics suppliers impose AS9100 quality system requirements on coating vendors. Qualification cycles and traceability documentation favor established PVD specialists.
OEM manufacturers anchor the volume base through diversified industrial demand while solar power companies restructure procurement fastest through in-house coating adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese precision optics clusters while Chinese solar manufacturers compress coating margins through direct precursor procurement. The regional asymmetry reflects divergent end-use demands: qualification-intensive aerospace instruments versus throughput-driven photovoltaic cover glass.
China
Domestic solar cell production and consumer electronics assembly drive coating consumption across the Yangtze River Delta and Pearl River Delta. GB standards constrain heavy-metal content in electronics-facing coatings while MIIT guidelines shape dual carbon compliance timelines. LONGi and Trina Solar operate captive coating lines in Xi'an and Changzhou, procuring sol-gel precursors directly from chemical suppliers.
Germany
ZEISS anchors precision optics demand for ion-beam sputtered multilayer stacks in Oberkochen and Jena. REACH Phase-Down regulations accelerate waterborne process adoption across Baden-Württemberg coating houses. The Stuttgart industrial corridor hosts specialized vacuum deposition equipment fabricators serving aerospace qualification requirements.
United States
Automotive HUD integration and defense optics sustain premium coating procurement through Michigan and Arizona manufacturing clusters. EPA National Emission Standards mandate thermal oxidizer installation for coating operations, burdening mid-scale applicators with capital requirements. Corning Incorporated anchors display glass supply from Kentucky and New York state facilities.
Japan
HOYA Corporation and ophthalmic specialists drive ion-beam sputtering demand for sub-0.5% reflectance specifications. METI industrial policy supports advanced materials R&D in the Nagoya and Osaka manufacturing belts. Fluoropolymer feedstock concentration among domestic chemical producers tracks hydrophobic topcoat formulation costs.
India
Production-linked incentive schemes for domestic photovoltaic module assembly create coating demand across Gujarat and Tamil Nadu solar manufacturing zones. The Central Electricity Authority regulates module efficiency standards that indirectly specify anti-reflective performance tiers. Imported cell processing equipment from China requires local AR film supply chain development.
Global Anti-Reflective Coatings Market Competitive Landscape
Concentration sits with integrated lens-finishing networks and industrial glass suppliers rather than standalone coating specialists. Precision optics maintains oligopolistic structure through qualification barriers and captive ion-beam capacity, while solar-facing supply fragments toward chemical precursor vendors. Three archetypes dominate: ophthalmic captives with in-house finishing, diversified materials conglomerates anchoring industrial channels, and solar chemical suppliers bypassing applicator intermediaries. Competitive moves center on backward integration into precursor manufacturing and geographic expansion through qualified applicator networks.
Among diversified industrial suppliers, PPG Industries anchors automotive and architectural glass channels from its coatings division, while DuPont represents the chemical precursor archetype supplying sol-gel formulations to solar manufacturers. ZEISS exemplifies the captive precision optics model through its integrated ophthalmic and industrial optics businesses. These three occupy positions across distinct value capture tiers: formulation chemistry, application equipment, and finished optical components.
| Leading Market Players |
|---|
| ZEISS |
| EssilorLuxottica |
| PPG Industries |
| HOYA Corporation |
| DuPont |
| Honeywell International Inc. |
| AGC Inc. |
| Corning Incorporated |
| Saint-Gobain |
| Others |
Supply & Pricing Matrix
Long-term precursor supply contracts lock in both sol-gel chemical access and coating price visibility for Chinese solar manufacturers expanding captive coating lines. These arrangements concentrate procurement leverage with DuPont and domestic Chinese chemical suppliers while compressing margin capture for traditional applicator intermediaries.
Pricing Analysis
The customization-premium spread separates ion-beam sputtered multilayer stacks for aerospace qualification from spray-applied sol-gel coatings for utility-scale solar. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with sub-0.5% reflectance specifications commanding substantial premiums. Cost compression in the solar tier is intensifying because LONGi and Trina Solar have internalized application, procuring raw precursors directly. Solar panel assemblers exhibit the highest price sensitivity, while German precision optics buyers prioritize performance over unit cost.
Supply Chain Analysis
Fluoropolymer feedstock concentration in Japan and China creates a chokepoint for hydrophobic topcoat formulation costs across eyewear and display applications. Manufacturing capacity clusters in China, Germany, and Japan, with vacuum deposition equipment fabrication resting on specialized machine builders in Stuttgart and Nagoya. Single-source vulnerability runs through Japanese perfluorinated precursor suppliers facing REACH phase-down pressures. Distribution runs through direct procurement relationships between solar assemblers and chemical suppliers, bypassing traditional applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where solar manufacturers' in-house coating adoption collapses the traditional applicator intermediary layer, reconfiguring value capture toward precursor formulation expertise and equipment supply.
For Market Incumbents: Shield premium positioning in precision optics through captive ion-beam sputtering capacity and AS9100 qualification maintenance against sol-gel substitution threats. Deepen backward integration into metal alkoxide precursor manufacturing to retain formulation control as solar customers bypass applicator services. Anchor channel control through qualified applicator network expansion in India and Southeast Asia where production-linked incentive schemes are localizing demand. For New Entrants and Emerging Players: Differentiate on low-temperature sol-gel process architectures that qualify for EU Green Deal preferential procurement criteria. Target automotive HUD integration as the most penetrable premium segment, where angular-selective stack specifications remain underdeveloped and tier-1 glass suppliers are actively qualifying new coating architectures. Pursue equipment-plus-chemistry bundling as the go-to-market angle, selling integrated spray-coating lines with proprietary silica-titania formulations to Indian solar manufacturers. For Investors and Strategic Acquirers: Capital is best deployed toward chemical precursor specialists with established REACH-compliant formulations and solar customer relationships, positioned for volume scaling as in-house coating adoption accelerates. The long-term viability window favors suppliers who control formulation IP rather than application service revenue pools. Watch ECHA substance evaluation timelines as the critical inflection signal, as accelerated PFAS restrictions would force rapid reformulation investments and consolidate advantage among prepared suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | DuPont's sol-gel chemistry expertise captures value as solar manufacturers internalize coating application. |
| Capacity Expansion in India | Production-linked incentive schemes for photovoltaic module assembly create localized coating demand in Gujarat and Tamil Nadu. |
| REACH-Compliant Reformulation Program | European coating houses accelerate silicone-based water-repellent alternatives to maintain OEM qualification status. |
| Ion-Beam Sputtering Capacity Addition | ZEISS sustains premium positioning through captive systems for sub-0.5% reflectance ophthalmic specifications. |
| Automotive HUD Qualification Partnership | Tier-1 glass suppliers embed angular-selective anti-reflective stacks for windshield-embedded augmented reality displays. |
Research Methodology
The analysis maps vacuum-deposited multilayer, sol-gel spray, and hybrid coating architectures, each validated through technical directors at precision optics manufacturers, procurement leads at solar panel assemblers, and regulatory affairs specialists at chemical suppliers. Primary interviews with coating equipment fabricators, ophthalmic lens finishers, and aerospace component suppliers combined with secondary validation through SEC filings of diversified materials conglomerates, ECHA substance evaluation databases, and MIIT dual carbon policy documents. Bottom-up and top-down triangulation cross-checked installed coating capacity against end-use demand projections.
Consistency checks validated volume and value outputs against customs trade data for metal alkoxide precursor flows, photovoltaic module production statistics from the Central Electricity Authority, and ophthalmic lens shipment data from Japanese industry associations. Segmentation dimensions modeled include coating type, deposition technology, application sector, and end-user procurement channel across the analysis window. CAGRs derived from regression analysis of historical capacity expansion correlated with solar deployment pipelines and automotive HUD adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained photovoltaic deployment rates and stable fluoropolymer feedstock availability would require recalibration. Forecasts reflect assumptions regarding REACH implementation timelines and Chinese solar manufacturing capacity expansion. Practitioners should keep alternative scenarios live as ECHA substance evaluation schedules and India PLI scheme disbursement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Canada Floor Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Coatings Raw Materials Market
Coatings
Concrete Floor Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Packaging Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
In-Mold Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Mold Release Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
OEM Coatings Market
Coatings
United Arab Emirates Floor Coatings Market