
 High Build Rust Stabilizer with Reinforced Glass Flake Coating Market | 2026-2036
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market Size, Share, and Industry Trends Forecast 2026-2036
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market Foresight
The EU Green Deal is broadening the addressable market for high-performance anti-corrosion coatings by mandating lower-VOC formulations across marine and industrial applications. Akzo Nobel leverages its European manufacturing footprint to supply compliant epoxy systems to North Sea offshore operators. Jotun anchors its position through specialized R&D on glass flake reinforcement ratios that meet NORSOK M-501 standards. Hempel competes by controlling distribution channels across Nordic shipyards where environmental compliance carries premium pricing power.
High build rust stabilizer with reinforced glass flake coating is a multi-layer protective system incorporating oriented borosilicate glass flakes within an epoxy or urethane binder, applied at dry film thicknesses exceeding 500 microns to arrest substrate corrosion under immersion or chemical exposure. The marine application segment dominates volume due to classification society mandates for ballast tank and hull protection, while the infrastructure segment represents the fastest-growing margin pool as bridge and wastewater asset owners adopt life-cycle coating specifications. Epoxy formulations occupy the largest product type share given their adhesion strength and chemical resistance, though urethane variants are gaining specification in automotive underbody applications where flexibility and impact resistance outweigh pure corrosion barrier performance.
REACH compliance through ECHA governs raw material selection and restricts certain chromate-based corrosion inhibitors, while ISO 12944 provides the performance-based framework that end users reference in procurement specifications. The US EPA's NESHAP standards for surface coating operations impose capture and control requirements that favor high-solids systems with reduced application passes. Stakeholders must monitor evolving MEE enforcement in China, where provincial environmental inspections are tightening VOC emission limits at coating application facilities and reshaping supplier qualification criteria.
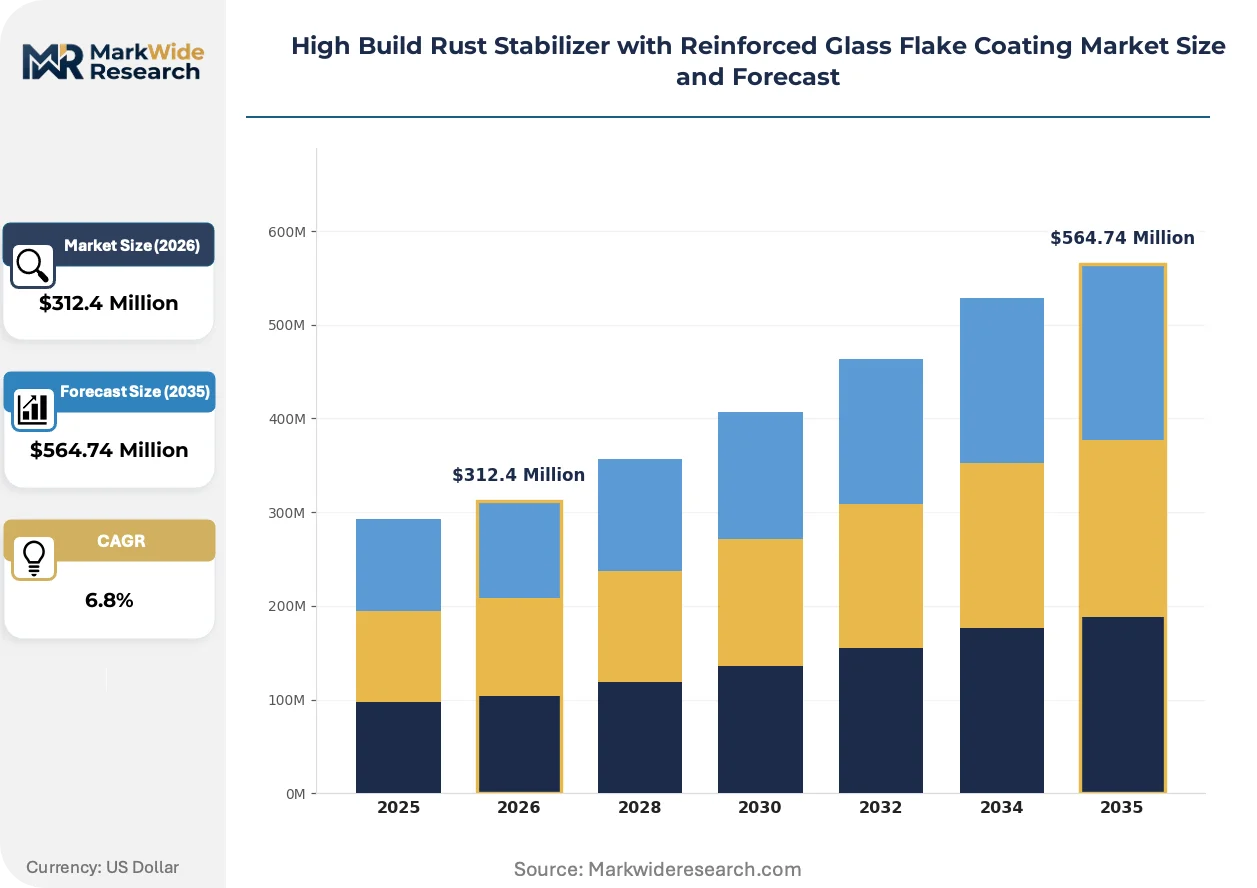
Market Dynamics
EU Green Deal chemical sustainability criteria are forcing reformulation across marine coating supply chains, compressing VOC thresholds and rewiring raw material sourcing toward bio-based epoxy precursors.
Growth Catalysts
- Ballast tank mandates:Classification societies now require glass flake reinforced systems for double-hull protection, pulling specification upgrades across fleet renewal programs.
- REACH chromate restrictions:ECHA prohibitions on hexavalent chromium corrosion inhibitors are redirecting formulation spend toward glass flake barrier technologies.
- China coastal shipbuilding:State-owned yards in Jiangsu and Zhejiang provinces are modernizing fleet protection standards, concentrating demand in eastern coastal manufacturing clusters.
Market Restraints
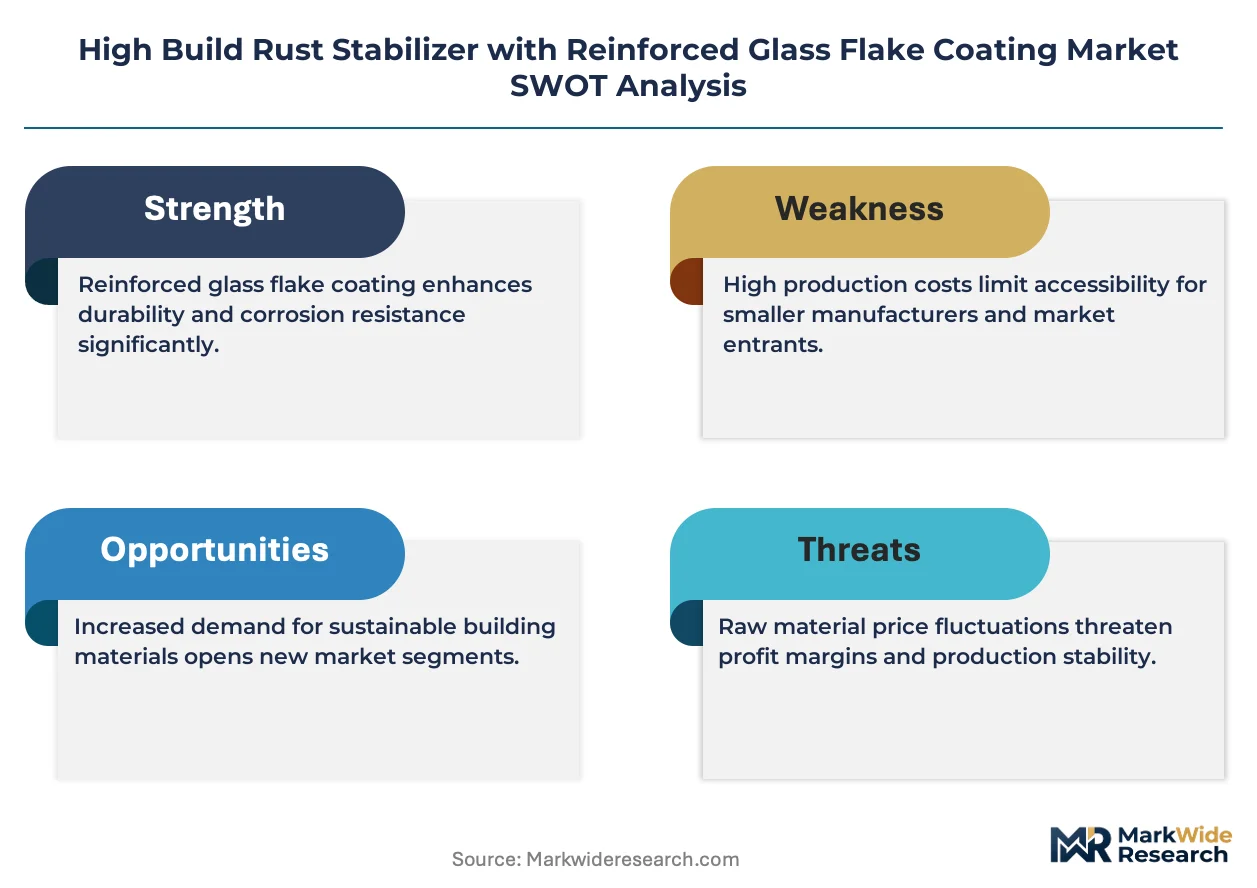
- Epoxy resin volatility:Bisphenol-A and epichlorohydrin feedstock costs swing with crude oil and chlorine capacity, squeezing margin predictability for high-build applicators.
- MEE enforcement tightening:China's Ministry of Ecology and Environment provincial inspections are disqualifying smaller coating facilities, concentrating supply among state-qualified producers.
- Application complexity:500+ micron dry film thickness requirements demand specialized spray equipment and climate-controlled environments, limiting contractor pool depth.
Strategic Opportunities
- Wastewater infrastructure:Municipal asset owners in Germany and the Netherlands are adopting life-cycle coating specifications for anaerobic digester tanks and clarifier structures.
- Automotive underbody:Urethane glass flake variants are penetrating electric vehicle battery tray protection where impact resistance and thermal cycling durability outweigh pure barrier performance.
- North Sea decommissioning:UK and Norwegian offshore operators are specifying high-build systems for extended-life asset management rather than full platform replacement.
Industry Challenges
- Applicator certification gaps:NORSOK M-501 and ISO 12944 compliance training lags demand, constraining qualified installation capacity for offshore projects.
- Substrate preparation standards:Sa 2.5 blast cleaning requirements for high-build adhesion consume 40% of project labor hours, creating scheduling bottlenecks at yard facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Build Rust Stabilizer with Reinforced Glass Flake Coating Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Urethane, Alkyd, Acrylic Application: Marine, Industrial, Automotive, Infrastructure End User: Manufacturers, Contractors, OEMs, Distributors Coating Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Nippon Paint Holdings, Kansai Paint, Akzo Nobel, Dulux, Chugoku Marine Paints, Jotun, Sherwin-Williams, Chemco International, Hempel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market Shifts & Advancements
Formulation chemistry and application methodology are converging around sustainability mandates and performance verification, compressing development cycles and rewiring supplier-buyer technical collaboration.
Waterborne epoxy glass flake systems are electrifying specification conversations among European shipyards facing EU Green Deal VOC deadlines. Classification societies in Norway and Germany are fast-tracking approval protocols for these formulations. The technology is compressing the window between laboratory validation and yard trials from 18 months to under 8 months.
REACH authorization requirements through ECHA are restricting legacy corrosion inhibitor chemistries across marine and industrial coating portfolios. Formulators are redirecting R&D spend toward borosilicate glass flake orientation optimization and silane coupling agent innovation. Nordic offshore operators are now mandating full material disclosure documentation in procurement tenders, favoring suppliers with transparent supply chain auditing.
Asset owner engineering teams are consolidating coating specifications around life-cycle cost models rather than first-cost procurement. North Sea platform operators and German wastewater utilities are unbundling material supply from application service contracts, creating direct specification relationships with coating manufacturers. This pattern is most visible in the Netherlands, where Rijkswaterstaat bridge maintenance programs now require 25-year performance warranties backed by manufacturer asset integrity monitoring.
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market Segmentation
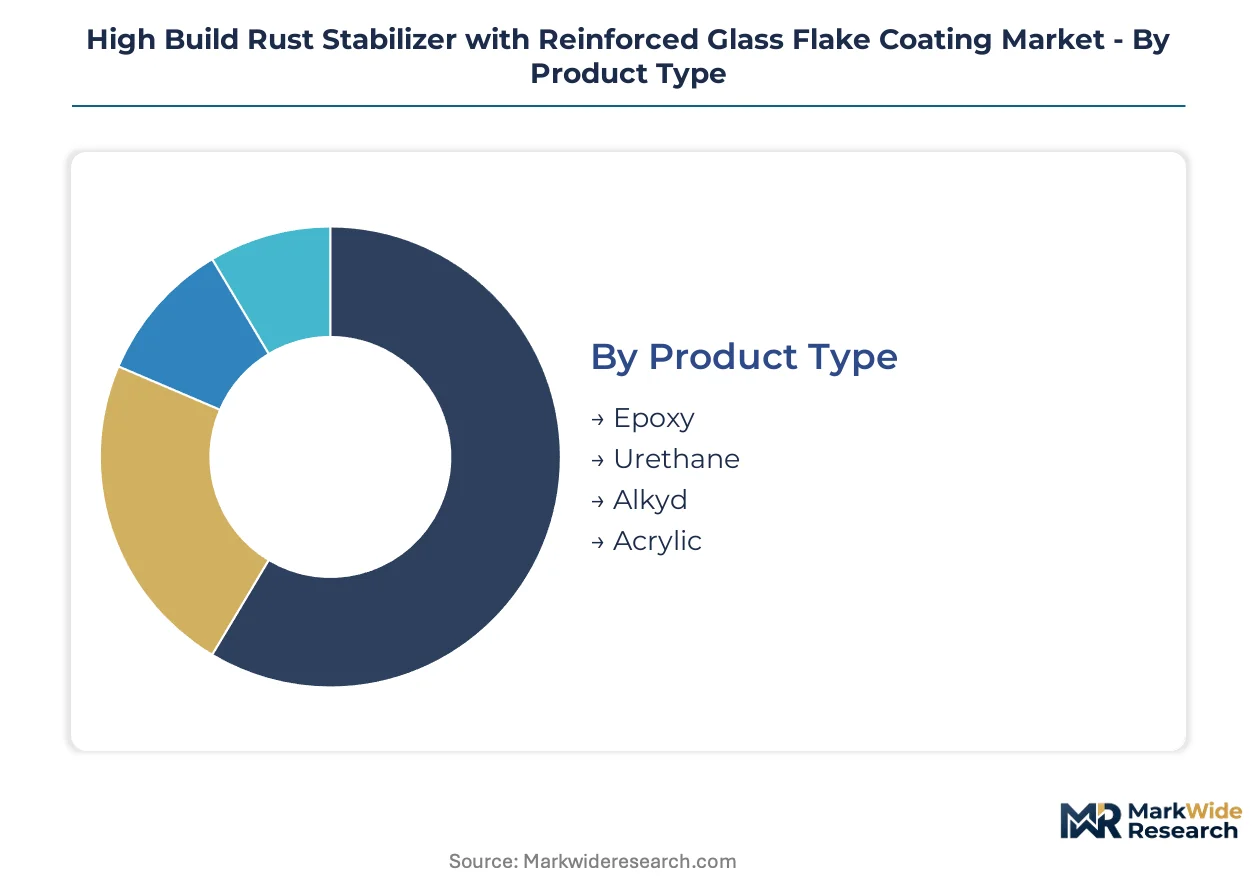
Specification decisions in high-build rust stabilizer coatings pivot on corrosion severity, regulatory exposure, and application economics. Each segmentation dimension reveals distinct procurement patterns across marine yards, infrastructure asset owners, and industrial maintenance teams.
Product Type:
Buyers select binder chemistry based on chemical resistance requirements versus flexibility needs, with VOC compliance thresholds narrowing the viable set in regulated jurisdictions.
- Epoxy:Two-part amine-cured systems incorporating oriented borosilicate glass flakes deliver maximum adhesion strength and chemical resistance for ballast tanks and offshore structures. Demand concentrates in China's Jiangsu shipbuilding cluster where state-owned yards specify high-solids formulations meeting MEE enforcement standards for VOC emissions at application facilities.
- Urethane:Aliphatic polyurethane binders with glass flake reinforcement provide superior UV stability and impact resistance for dynamic substrates. Automotive underbody protection for electric vehicle battery trays in Germany and the Netherlands drives specification, where thermal cycling durability outweighs pure barrier performance.
- Alkyd:Oil-modified polyester binders with lower solids content serve maintenance touch-up applications where spray equipment access is limited and brush/roller application dominates.
- Acrylic:Water-dispersible acrylic systems with glass flake loading address EU Green Deal VOC deadlines in European shipyards, though immersion resistance lags epoxy alternatives.
Volume sits with epoxy formulations; growth tilts toward urethane variants in automotive and infrastructure specifications.
Application:
End-use environments dictate glass flake orientation density, dry film thickness targets, and certification requirements for applicator qualification.
- Marine:Classification society mandates for double-hull ballast tank protection require 500+ micron dry film thickness with NORSOK M-501 compliance. North Sea offshore operators in Norway and the UK specify these systems for extended-life asset management rather than full platform replacement.
- Infrastructure:Bridge maintenance programs and wastewater treatment assets in Germany and the Netherlands adopt life-cycle coating specifications with 25-year performance warranties. Rijkswaterstaat procurement unbundles material supply from application contracts, creating direct manufacturer relationships.
- Industrial:Chemical processing facilities and power generation assets specify high-build systems for tank linings and structural steel under intermittent chemical exposure.
- Automotive:Electric vehicle manufacturers specify urethane glass flake coatings for battery tray protection, where impact resistance and thermal management properties are critical.
Marine commands the largest share of specification volume; infrastructure offers the steepest expansion trajectory as asset owners shift to life-cycle procurement models.
End User:
Procurement authority varies by project structure, with design-build contracts consolidating specification power among contractors while OEM direct sourcing grows in automotive.
- Manufacturers:Coating formulators and raw material suppliers serving as specification gatekeepers for marine and industrial accounts.
- Contractors:Specialized applicators holding NORSOK M-501 and ISO 12944 certification, increasingly unbundled from material supply in European markets.
- OEMs:Automotive and heavy equipment original equipment manufacturers specifying coatings at design stage for corrosion warranty compliance.
- Distributors:Regional stocking distributors serving maintenance, repair, and operations demand with technical support capabilities.
Contractors control the largest volume channel; OEM direct procurement is climbing fastest as automotive electrification reshapes specification timelines.
Coating Thickness:
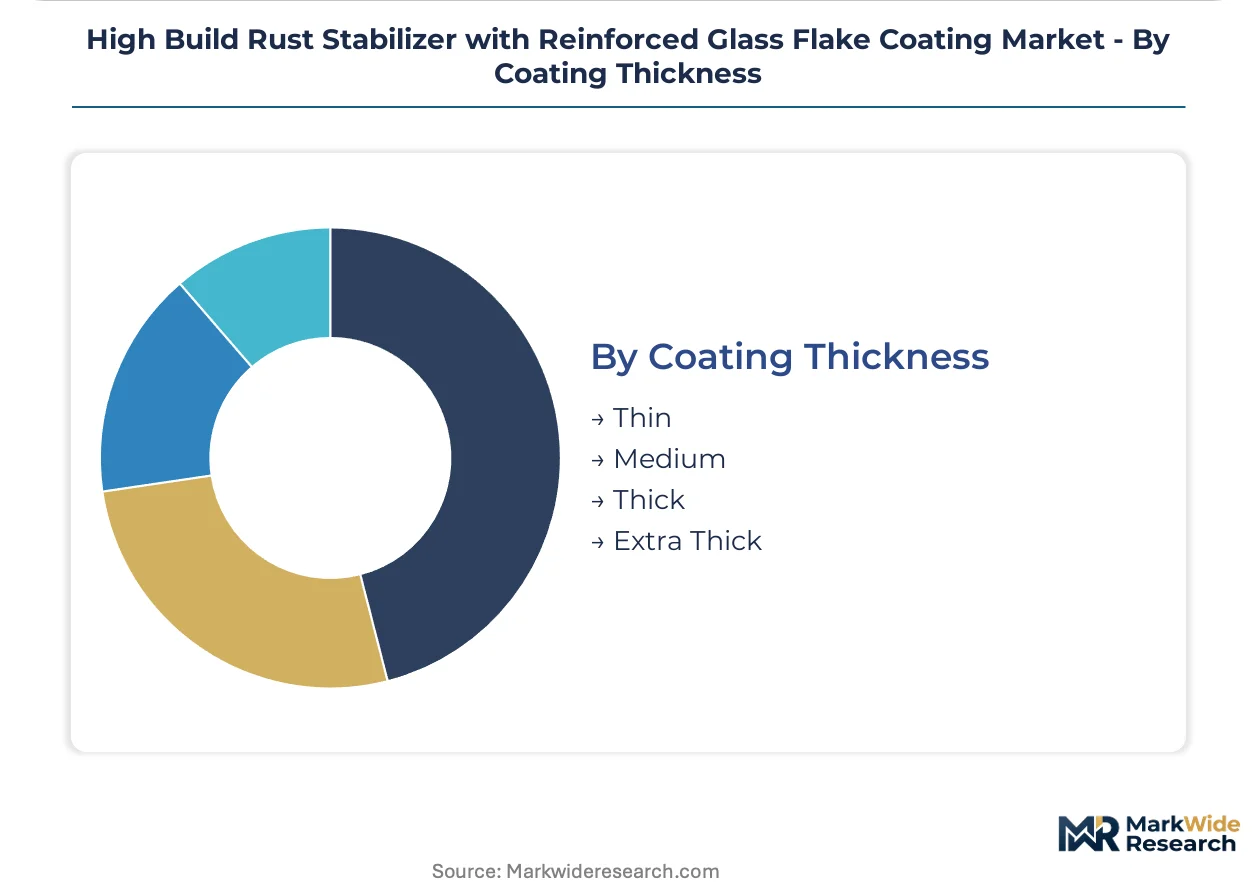
Dry film thickness determines glass flake loading ratios, application pass requirements, and labor cost structure for substrate preparation and spray operations.
- Thin:150-250 micron systems for maintenance touch-up and areas with restricted access, requiring less intensive surface preparation.
- Medium:250-500 micron applications for general industrial structural steel with moderate chemical exposure.
- Thick:500-750 micron specifications meeting classification society mandates for ballast tank and hull protection in marine applications.
- Extra Thick:750+ micron systems for severe chemical immersion environments and extended design life requirements in offshore and wastewater infrastructure.
Thick specifications dominate marine procurement; extra thick systems are expanding most quickly in North Sea decommissioning and German wastewater asset programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors coating demand through its concentration of state-owned shipbuilding yards in Nantong and Yangzhou, where fleet modernization programs are accelerating specification of high-build glass flake systems.
China
State-owned yards in Jiangsu and Zhejiang provinces are modernizing fleet protection standards, concentrating procurement in eastern coastal manufacturing clusters. MEE enforcement is tightening VOC emission limits at coating application facilities, disqualifying smaller facilities and consolidating supply among state-qualified producers. Nantong and Yangzhou shipbuilding corridors now specify high-solids epoxy formulations meeting 500+ micron dry film thickness mandates for ballast tank protection.
Norway
North Sea offshore operators are specifying high-build systems for extended-life asset management rather than full platform replacement. NORSOK M-501 compliance requirements govern procurement specifications, with classification societies fast-tracking approval protocols for lower-VOC formulations. Stavanger and Bergen anchor the supplier ecosystem serving Norwegian continental shelf decommissioning programs.
Germany
Municipal asset owners are adopting life-cycle coating specifications for anaerobic digester tanks and clarifier structures in wastewater infrastructure. EU Green Deal chemical sustainability criteria are compressing VOC thresholds and rewiring raw material sourcing toward bio-based epoxy precursors. The Ruhr industrial corridor and Hamburg port facilities concentrate application contractor capacity certified to ISO 12944 standards.
United States
Offshore oil platform operators in the Gulf of Mexico are expanding specification of glass flake reinforced coatings to extend asset life in corrosive saltwater environments. EPA NESHAP standards for surface coating operations impose capture and control requirements favoring high-solids systems with reduced application passes. Houston and New Orleans anchor the contractor network serving Gulf Coast platform maintenance programs.
Netherlands
Rijkswaterstaat bridge maintenance programs now require 25-year performance warranties backed by manufacturer asset integrity monitoring. Procurement patterns are unbundling material supply from application service contracts, creating direct specification relationships with coating manufacturers. The Rotterdam port complex and Amsterdam-Rijnkanaal industrial corridor concentrate demand for infrastructure protection specifications.
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market Competitive Landscape
The competitive structure tilts toward integrated coating formulators with captive resin supply and established classification society relationships. Three tiers populate the landscape: global marine specialists with NORSOK M-501 certification depth, regional industrial coating houses serving maintenance markets, and automotive-focused urethane innovators penetrating electric vehicle specifications. Dominant competitive moves include backward integration into epoxy resin production and technology licensing partnerships with glass flake substrate suppliers.
Among European-integrated formulators, Akzo Nobel, Jotun, and Hempel occupy positions defined by regulatory compliance capabilities and distribution channel control. Akzo Nobel leverages its manufacturing footprint to supply EU Green Deal-compliant systems. Jotun anchors its position through specialized R&D orientation. Hempel competes by controlling distribution channels across Nordic shipyards where environmental compliance carries premium pricing power.
| Leading Market Players |
|---|
| Nippon Paint Holdings |
| Kansai Paint |
| Akzo Nobel |
| Dulux |
| Chugoku Marine Paints |
| Jotun |
| Sherwin-Williams |
| Chemco International |
| Hempel |
| Others |
Supply & Pricing Matrix
EU Green Deal VOC mandates gate both qualified supply and premium-tier pricing access, compressing formulation options to high-solids epoxy systems that command 15-25% price premiums over legacy alternatives while disqualifying smaller applicators lacking MEE-compliant facilities.
Pricing Analysis
Life-cycle cost guarantees anchor value-based pricing for high-build glass flake systems, with Rijkswaterstaat bridge programs and North Sea operators contracting 25-year performance warranties that bundle material supply with manufacturer asset monitoring. Price differentiation stratifies across NORSOK M-501 certification tiers, with offshore-qualified applicators capturing margin premiums over general industrial contractors. Cost compression in standard-grade epoxy formulations is intensifying as Chinese state-owned yards consolidate procurement volumes. Municipal wastewater asset owners in Germany and the Netherlands exhibit highest price sensitivity due to public budget constraints, while offshore operators prioritize technical compliance over first-cost procurement.
Supply Chain Analysis
Freight costs for borosilicate glass flake substrates from German and Chinese specialty suppliers amplify landed costs for Nordic and North American formulators, favoring regional production footprints. Epoxy resin supply concentrates in China, Germany, and the United States, with bisphenol-A and epichlorohydrin feedstock volatility tethering margin stability to crude oil and chlorine capacity cycles. Single-source vulnerability sits with specialized glass flake orientation equipment manufacturers in Japan and Germany. Distribution runs through certified applicator networks holding NORSOK M-501 and ISO 12944 credentials, increasingly unbundled from material supply in European procurement patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne epoxy glass flake systems are displacing solvent-borne formulations as the dominant technology platform, compressing development cycles and rewiring supplier-buyer technical collaboration protocols.
For Market Incumbents: Lock in NORSOK M-501 certification depth through captive training academy investments, defending against regional industrial coating houses poaching qualified applicators. Backward integration into epoxy resin production secures margin control against bisphenol-A feedstock volatility. Prioritize EU Green Deal compliance roadmapping to maintain specification access in German and Dutch procurement.
For New Entrants and Emerging Players: Enter via automotive underbody protection for electric vehicle battery trays, where urethane glass flake variants face limited incumbent specialization and thermal cycling durability requirements create specification white space. Target Jiangsu province shipbuilding corridors with high-solids epoxy formulations meeting MEE enforcement standards. Lead with application service bundling to bypass entrenched material supply relationships.
For Investors and Strategic Acquirers: ECHA authorization withdrawals for hexavalent chromium corrosion inhibitors are the leading indicator that glass flake barrier technologies will capture redirected formulation spend across marine and industrial portfolios. Five-to-ten-year viability favors integrated formulators with captive resin supply and established classification society relationships. Monitor fast-track approval protocols for waterborne systems at DNV and Germanischer Lloyd as inflection signals for technology-transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Captive bisphenol-A supply secures margin stability against feedstock volatility for high-build formulators. |
| NORSOK M-501 Certification Academy | Qualified applicator pipeline expansion addresses certification gaps constraining offshore project capacity. |
| Waterborne Formulation Fast-Track | EU Green Deal compliance positioning captures specification share at European shipyards facing VOC deadlines. |
| Automotive Urethane Variant Development | Electric vehicle battery tray penetration diversifies revenue beyond marine and infrastructure cyclicality. |
| Life-Cycle Cost Model Partnerships | Direct Rijkswaterstaat and German municipal relationships unbundle material supply from contractor intermediaries. |
Research Methodology
Independent corroboration across classification society technical committees, coating formulator R&D directors, and offshore asset integrity engineers underwrites the qualitative findings. Primary fieldwork encompassed plant managers at Jiangsu shipbuilding facilities, procurement leads at Dutch infrastructure agencies, and distribution channel partners serving Nordic yards. Secondary validation drew from ECHA authorization databases, ISO 12944 maintenance records, and SEC filings of listed coating manufacturers. Bottom-up volume estimates from application facility throughput triangulated against top-down addressable market calculations.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes, normalized for MEE enforcement disruptions and EU Green Deal implementation phases. The analytical framework segmented by binder chemistry, end-use environment, coating thickness tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating fleet renewal timelines and infrastructure asset replacement cycles. Key inputs included ballast tank mandate adoption curves and REACH authorization sunset schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt ECHA restriction accelerations or MEE enforcement suspensions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Marine Anti Fouling Coatings Market
Coatings
Radiation Curable Coatings Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Anti-Friction Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
Global Photocatalytic Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
US Concrete Floor Coatings Market
Coatings
Coating Pigments Market
Coatings
Canada Protective Coatings Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
FBE Coatings Market
Coatings
Europe Anti-Friction Coatings Market