
 Tablet Coatings Market | 2026-2036
Tablet Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Coatings Market Outlook
The EU Green Deal is decoupling European pharmaceutical coating demand from solvent-intensive processes. BASF SE leverages its polymer science depth to sustain leadership in water-dispersible systems. Merck KGaA anchors high-purity excipient supply for regulated markets. Colorcon, Inc. differentiates through color-matching technology and regional technical service centers.
Tablet coatings are thin functional layers applied to solid oral dosage forms, typically comprising polymers, plasticizers, pigments, and solvents or aqueous vehicles, applied via pan coating or fluid-bed spray systems to control drug release, mask taste, improve stability, or enable product identification. Film coatings dominate commercial volume due to their operational efficiency and compatibility with high-speed manufacturing, while enteric coatings command premium positioning for acid-sensitive APIs. Application demand from contract manufacturers is expanding fastest as pharmaceutical companies outsource production to reduce capital intensity.
FDA stability guidelines, EU REACH chemical restrictions, and India's CDSCO manufacturing standards collectively elevate barrier-to-entry for new coating suppliers. These frameworks mandate dissolution profile consistency, residual solvent limits, and excipient traceability that favor established formulators with validated quality systems. Stakeholders must monitor regulatory divergence between US and EU excipient monograph requirements when designing multi-territory supply strategies.
Market Dynamics
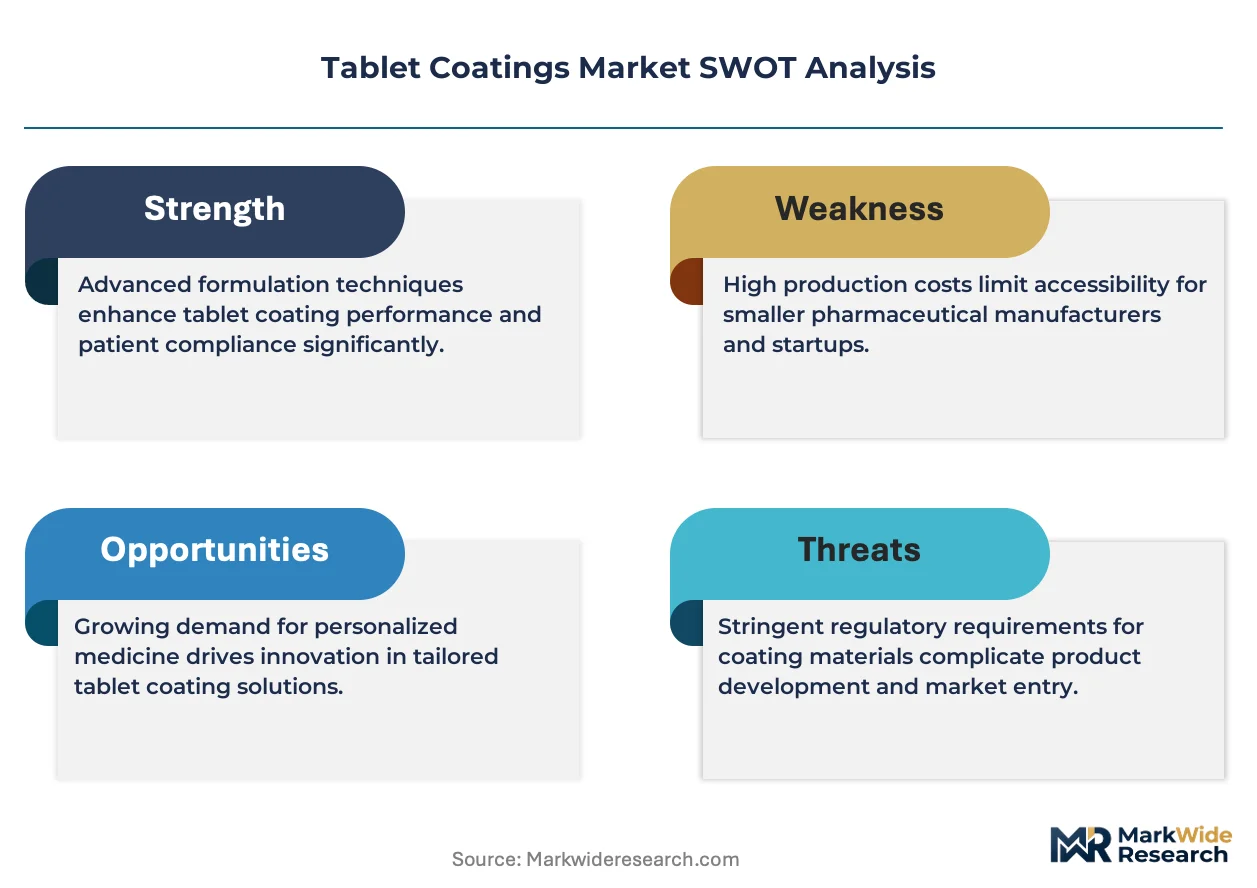
Water-based polymer migration is compressing solvent-dependent coating capacity as REACH enforcement tightens residual solvent limits and generic manufacturers accelerate bioequivalence-compliant output.
Growth Catalysts
- EU REACH solvent restrictions:Chemical registration thresholds are forcing converters toward aqueous dispersion systems, expanding validated water-based formulation demand.
- India CDSCO export standards:Contract manufacturers serving regulated markets are upgrading coating facilities to meet dissolution profile consistency mandates for US and EU shipments.
- High-speed pan coating automation:Equipment throughput improvements are reducing unit coating costs for volume generic tablet production.
Market Restraints
- Acetone and ethanol price volatility:Solvent input cost swings compress margin predictability for hybrid aqueous-solvent operations during transition periods.
- German polymer supplier concentration:Specialty excipient sourcing relies on a narrow base of REACH-compliant chemical producers near Ludwigshafen and Frankfurt clusters.
- Film coating thickness uniformity limits:Current spray deposition control tolerances constrain release profile precision for narrow-therapeutic-index APIs.
Strategic Opportunities
- Brazil ANVISA manufacturing incentives:Local production requirements for government procurement are creating coating facility investment openings in São Paulo and Rio de Janeiro states.
- Functional coating-nutraceutical convergence:Vitamin and probiotic tablet producers are adopting enteric systems previously confined to pharmaceutical applications.
- Continuous manufacturing integration:Real-time coating deposition monitoring is converging with process analytical technology to enable single-pass tablet production.
Industry Challenges
- Process analytical technology skill scarcity:Formulation chemists with PAT implementation experience command premium compensation and extended recruitment timelines.
- Validation protocol capex intensity:New aqueous coating line qualification requires 18-24 month documentation cycles before commercial release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Coatings Market |
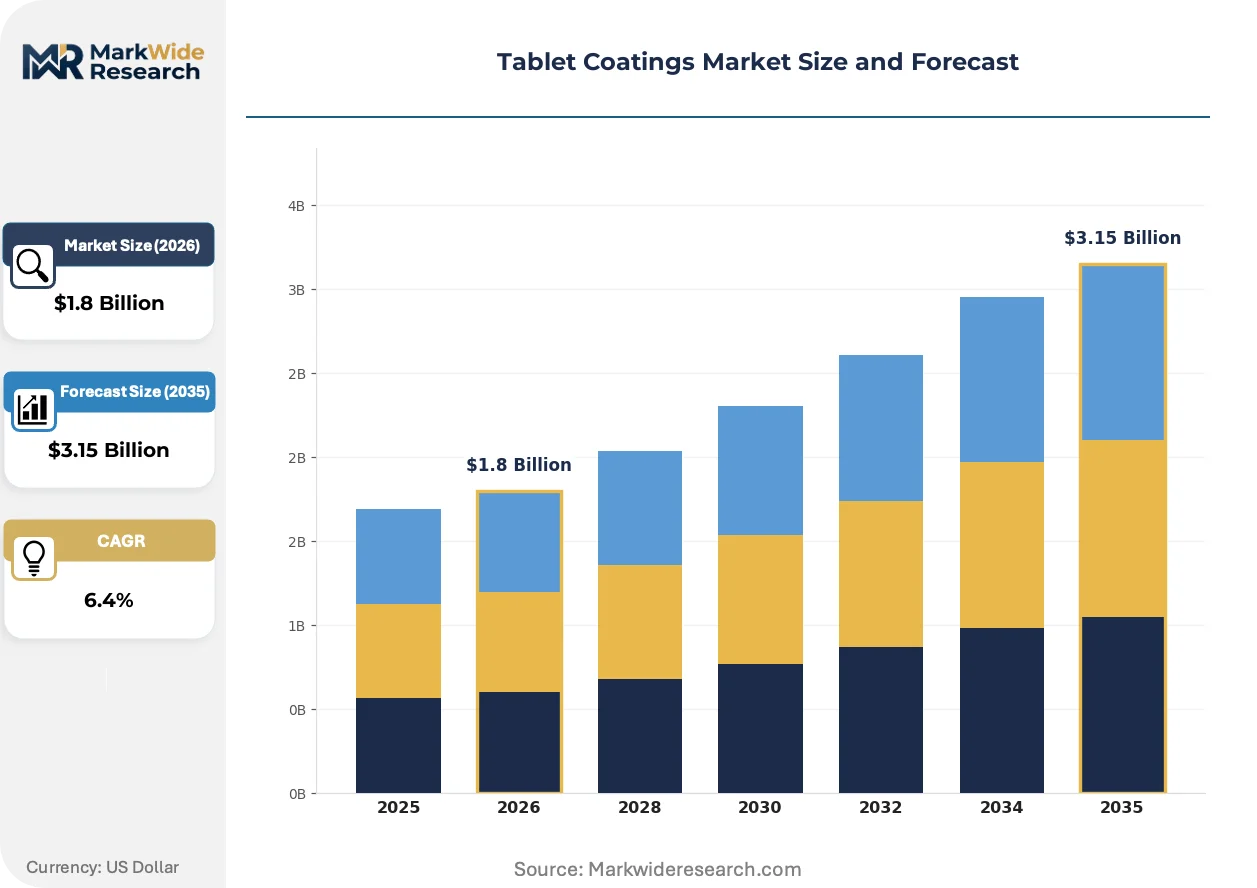
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Sugar Coatings, Film Coatings, Enteric Coatings, Non-functional Coatings Application: Pharmaceuticals, Nutraceuticals, Veterinary Medicine, Dietary Supplements End User: Contract Manufacturers, Pharmaceutical Companies, Research Institutions, Health Care Facilities Formulation: Liquid Formulations, Dry Formulations, Spray-dried Formulations, Coated Granules |
| Companies Covered | BASF SE, Merck KGaA, Colorcon, Inc., Roquette Frères S.A., Eastman Chemical Company, Ashland Global Holdings Inc., DuPont de Nemours, Inc., Sensient Technologies Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Coatings Market Strategic Shifts
Coating technology is pivoting from batch pan systems toward continuous processing architectures as regulatory scrutiny tightens batch-to-batch variability tolerance.
Hot-melt extrusion coating is converging with precision spray deposition to enable solvent-free functional layer application. Generic manufacturers in India and Eastern Europe are piloting these systems to eliminate drying stages and reduce facility footprint. The technology is converging with continuous tablet pressing to create fully integrated oral solid dose lines that compress coating cycle time by 60 percent.
EMA's updated excipient guideline requires enhanced nitrosamine impurity testing for film-forming polymers. Coating formulators are requalifying supply chains and investing in dedicated nitrosamine-free production lines. High-purity excipient demand is concentrating among CDMOs serving EU and Swissmedic-regulated markets, where documentation burden exceeds US FDA requirements.
Pharmaceutical procurement teams are consolidating coating excipient suppliers to reduce audit burden and secure volume pricing. Large generic houses are replacing fragmented regional sourcing with single-source global contracts covering polymer, pigment, and plasticizer bundles. This consolidation is most advanced among US-based manufacturers with centralized supply chain functions, where supplier count has dropped 40 percent since 2022.
Tablet Coatings Market Segmentation
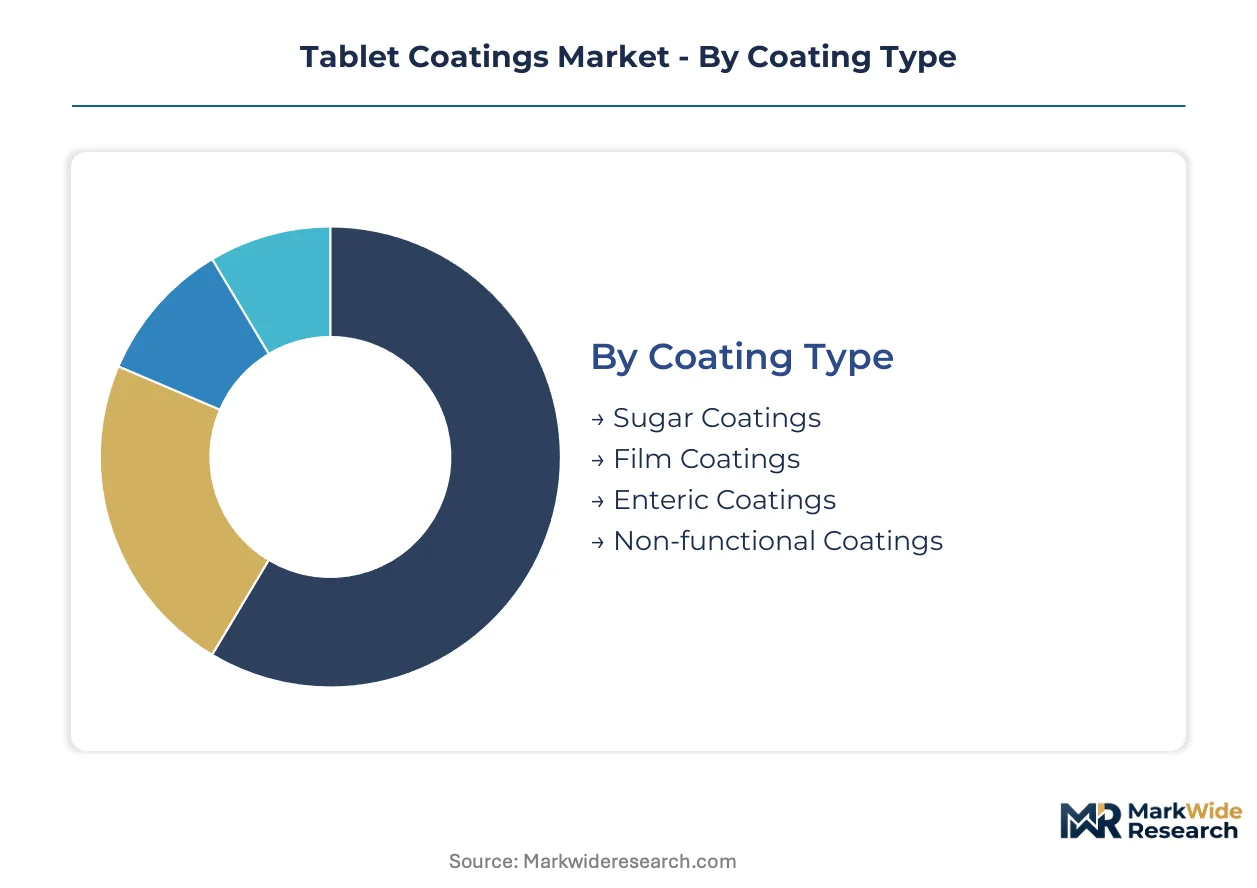
Tablet coatings demand fragments across four structural dimensions that dictate equipment investment, regulatory burden, and margin capture. Coating type determines process complexity and validation protocols, while end-user concentration shapes procurement scale and supplier consolidation patterns.
Coating Type:
Capital intensity peaks with enteric systems requiring specialized spray deposition and extended curing infrastructure; film coatings dominate volume economics through standardized pan-coating lines.
- Film Coatings:Polymer-based aqueous or solvent systems applied as thin functional layers for taste masking, moisture protection, and aesthetic identification. Demand concentrates among high-volume generic manufacturers in India and Eastern Europe where CDSCO and EMA dissolution mandates drive validated formulation upgrades. High-speed automation compatibility sustains operational efficiency leadership.
- Enteric Coatings:pH-responsive polymer systems protecting acid-labile APIs from gastric degradation until intestinal release. Pharmaceutical applications for proton pump inhibitors and enzyme formulations absorb premium capacity in Germany and Switzerland, where EMA nitrosamine testing requirements elevate purity standards and documentation burden.
- Sugar Coatings:Traditional sucrose-based layering for aesthetic finish and taste masking in legacy OTC products. Compact equipment footprint suits smaller batch operations in regional pharmaceutical markets with limited aqueous coating infrastructure.
- Non-functional Coatings:Cosmetic color and branding layers without modified release properties. Nutraceutical producers in Brazil leverage these systems for product differentiation under ANVISA manufacturing incentive programs.
Film coatings absorb the bulk of installed capacity; enteric coatings are expanding most quickly.
Application:
Regulatory tiering separates pharmaceutical-grade validation from dietary supplement flexibility, with nutraceuticals bridging both worlds through enteric adoption.
- Pharmaceuticals:Regulated solid oral dosage forms requiring dissolution profile consistency and excipient traceability per FDA stability guidelines and EU REACH frameworks. Contract manufacturers in India upgrade facilities to serve US and EU export markets under tightening bioequivalence standards.
- Nutraceuticals:Vitamin, mineral, and botanical tablets adopting pharmaceutical-grade enteric and film systems for shelf-life extension and consumer compliance. Functional coating convergence accelerates in North American and European markets where probiotic stability demands pH-protected delivery.
- Veterinary Medicine:Palatability-focused coatings for companion animal and livestock formulations. Taste-masking priorities differ from human pharmaceutical specifications, with regional regulatory variance across USDA and EFSA jurisdictions.
- Dietary Supplements:Less stringent GMP requirements enable faster formulation cycles and color-matching customization. Direct-to-consumer brands drive demand for distinctive visual branding through pigment-intensive non-functional layers.
Pharmaceutical applications command the highest margin tier; nutraceuticals are climbing the fastest as functional coating boundaries dissolve.
End User:
Procurement scale and technical service requirements fragment the customer base between integrated pharmaceutical houses and outsourced manufacturing specialists.
- Contract Manufacturers:CDMOs serving multiple pharmaceutical clients with validated coating lines and dedicated quality systems. Indian and Eastern European facilities expand capacity to capture EU and US generic outsourcing demand under centralized supply chain consolidation trends.
- Pharmaceutical Companies:Integrated manufacturers with captive coating operations and proprietary formulation expertise. Large generic houses in the US have reduced supplier counts substantially since 2022 through bundled excipient contracts.
- Research Institutions:Small-batch coating for clinical trial materials and formulation development. Flexible equipment configurations and rapid changeover capabilities outweigh throughput optimization.
- Health Care Facilities:Limited in-house compounding of specialized coatings for personalized medicine applications. Hospital pharmacy operations represent minimal commercial volume but high technical service intensity.
Contract manufacturers absorb the bulk of capacity expansion; pharmaceutical companies retain strategic coating capabilities for high-value proprietary products.
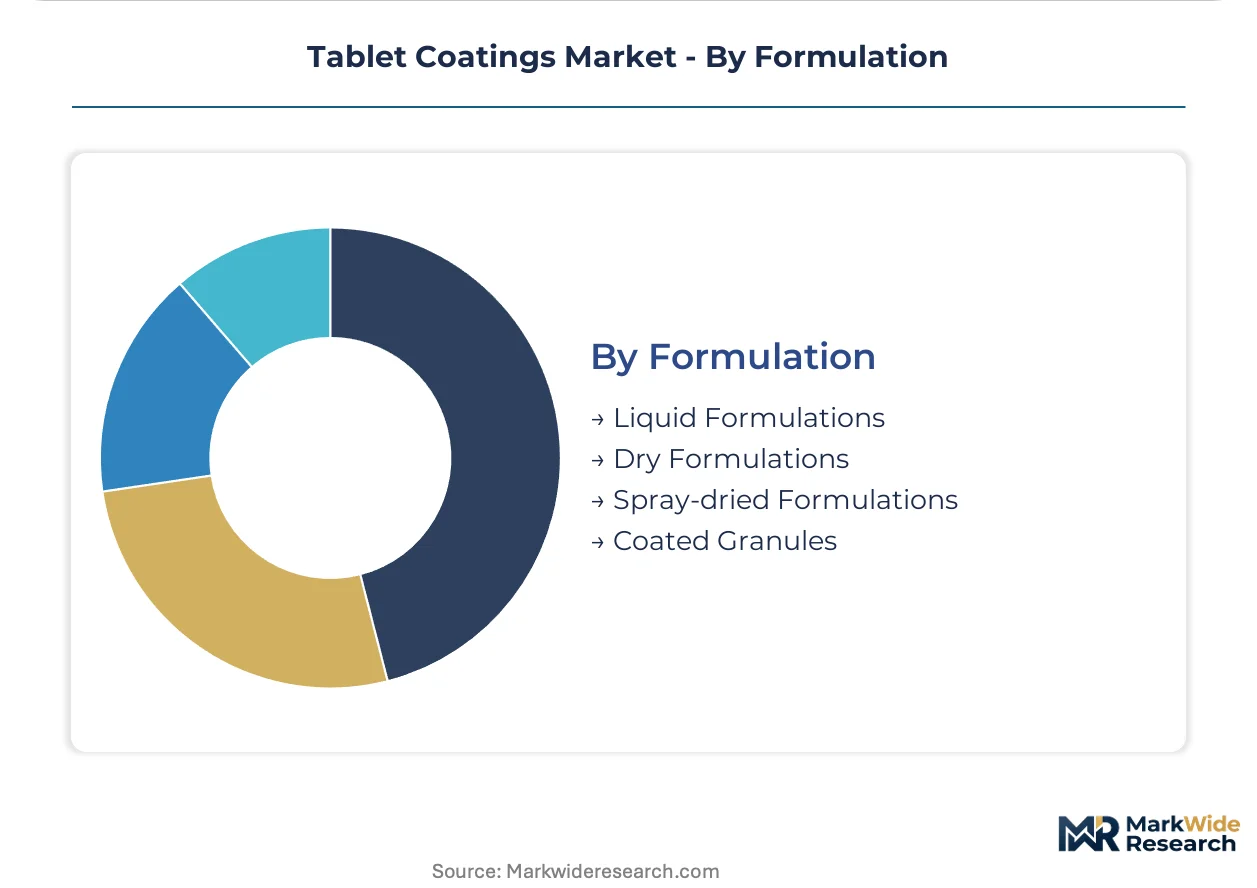
Formulation:
Process technology selection determines solvent exposure, drying energy requirements, and regulatory compliance pathway.
- Liquid Formulations:Aqueous or solvent-based polymer dispersions applied via conventional spray systems. REACH solvent restrictions and EPA residual limits are compressing organic solvent dependency toward water-dispersible alternatives.
- Dry Formulations:Powder polymer systems for direct compression or hot-melt integration. Elimination of drying stages reduces facility footprint and energy intensity, attracting pilot adoption in continuous manufacturing architectures.
- Spray-dried Formulations:Pre-processed polymer particles enabling rapid reconstitution and uniform dispersion. High-purity excipient demand from Swissmedic-regulated markets concentrates supply among specialized German producers.
- Coated Granules:Multi-particulate systems for modified release and dose flexibility. Pediatric and geriatric applications drive demand for titratable dosing formats with consistent coating thickness across particle size distributions.
Liquid formulations retain dominant installed base; dry formulations are gaining share fastest through continuous manufacturing integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European polymer supply for tablet coating systems, with specialty chemical clusters near Frankfurt and Basel feeding REACH-compliant excipient production across the continent.
United States
FDA stability guidelines and centralized procurement by large generic houses are compressing supplier counts by 40 percent since 2022. The EPA enforces residual solvent limits that accelerate aqueous formulation migration. New Jersey and North Carolina pharmaceutical corridors concentrate coating line automation investments for high-throughput generic production.
Germany
EMA nitrosamine testing requirements for film-forming polymers are elevating purity standards and documentation burden. The EU Green Deal decouples coating demand from solvent-intensive processes through REACH enforcement. Ludwigshafen and Frankfurt chemical clusters specialize in water-dispersible polymer systems for regulated export markets.
India
CDSCO export standards for US and EU shipments are driving contract manufacturers to upgrade coating facilities for dissolution profile consistency. The PLI scheme for pharmaceuticals incentivizes domestic excipient production capacity. Hyderabad and Ahmedabad pharmaceutical corridors expand validated coating lines to capture generic outsourcing demand.
Switzerland
Swissmedic documentation requirements exceed US FDA standards, concentrating high-purity excipient demand among specialized suppliers. The country's precision chemical sector supports nitrosamine-free production line investments. Basel anchors pharmaceutical coating innovation for EU-regulated premium formulations.
Brazil
ANVISA manufacturing incentives for government procurement are creating coating facility investment openings in São Paulo and Rio de Janeiro states. Local production requirements favor domestic excipient sourcing for public health programs. São Paulo state's pharmaceutical cluster pilots enteric coating adoption for nutraceutical applications.
Tablet Coatings Market Competitive Environment
The competitive structure tilts toward integrated chemical conglomerates with polymer science depth. Market concentration is moderate, with established European and North American formulators holding validated quality system advantages over regional entrants. Three archetypes dominate: diversified chemical majors with excipient divisions, specialized coating technology firms with color-matching capabilities, and contract manufacturing service providers with captive formulation expertise. Capacity expansion and supply chain consolidation represent the dominant competitive moves, as procurement teams reduce audit burden through bundled global contracts.
Within the diversified chemical major tier, BASF SE and Merck KGaA exemplify integrated polymer science capabilities spanning water-dispersible systems and high-purity excipients. Colorcon, Inc. occupies a specialist position anchored in color-matching technology and regional technical service infrastructure. These three entities represent distinct competitive vectors: polymer innovation leadership, regulatory documentation depth, and application-specific technical support.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Colorcon, Inc. |
| Roquette Frères S.A. |
| Eastman Chemical Company |
| Ashland Global Holdings Inc. |
| DuPont de Nemours, Inc. |
| Sensient Technologies Corporation |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Polymer feedstock costs originating from Ludwigshafen and Frankfurt chemical clusters cascade through three pricing tiers before reaching generic manufacturers in India and CDMOs in Eastern Europe, with REACH compliance premiums separating validated excipient grades from commodity alternatives.
Pricing Analysis
Yield-guaranteed coating throughput anchors value-based pricing for high-speed pan coating lines serving volume generic production. Three-tier pricing structure across premium, standard, and economy levels reflects EMA nitrosamine certification status, polymer purity grades, and bundled technical service availability. Cost compression in standard-tier aqueous formulations is intensifying because Indian contract manufacturers are consolidating supplier counts and demanding volume discounts. Large US generic houses exhibit lowest price sensitivity due to centralized procurement functions, while regional nutraceutical producers in Brazil and Southeast Asia drive hardest bargain on pigment-intensive cosmetic coatings.
Supply Chain Analysis
REACH and FDA qualification gating restricts approved polymer suppliers to a narrow base of German, Swiss, and US producers with validated nitrosamine-free production lines. Specialty excipient manufacturing concentrates in Germany, Switzerland, and India, with Hyderabad and Ahmedabad corridors expanding aqueous dispersion capacity under PLI scheme incentives. Raw material dependencies span cellulose derivatives, titanium dioxide pigments, and phthalate-free plasticizers sourced through long-term offtake agreements. Single-source vulnerability around pH-responsive enteric polymers creates supply risk for acid-labile API formulations. Distribution runs through authorized distributor networks serving CDMO clusters, with direct procurement relationships dominating large pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tablet coatings sector sits in a solvent-to-aqueous technology transition, with hot-melt extrusion and continuous processing architectures displacing legacy batch pan systems. Water-based polymer migration is compressing solvent-dependent capacity as regulatory enforcement tightens.
For Market Incumbents: Anticipate further consolidation in excipient supply by securing backward integration into polymer synthesis or captive nitrosamine-free production lines, as EMA documentation requirements exceed FDA standards and generic manufacturers reduce supplier counts. BASF SE and Merck KGaA already anchor this strategy through Ludwigshafen and Darmstadt chemical clusters. Prioritize certification investment for Swissmedic-regulated markets where purity premiums justify dedicated capacity. For New Entrants and Emerging Players: Capture white-space in Brazilian ANVISA manufacturing incentives and nutraceutical enteric coating adoption, where regulatory barriers remain lower than pharmaceutical-grade validation. São Paulo state offers the most penetrable geography for facility investment under local production requirements. Target direct-to-consumer dietary supplement brands with rapid color-matching customization and shorter qualification cycles than incumbent pharmaceutical suppliers. For Investors and Strategic Acquirers: CDSCO facility upgrade announcements from Indian contract manufacturers are the leading indicator that aqueous coating capacity expansion is accelerating and specialized equipment suppliers will see order book inflection. The 5-10 year viability window favors CDMOs with validated EU and US export capabilities over commodity coating operations. Acquisition target archetype: mid-scale Indian or Eastern European contract manufacturers with underutilized aqueous lines and pending EMA certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Synthesis | Captures REACH compliance premiums and secures nitrosamine-free supply for EMA-regulated markets. |
| Continuous Manufacturing Technology Adoption | Reduces coating cycle time by 60 percent and eliminates solvent drying stages for facility footprint compression. |
| Swissmedic-Grade Certification Investment | Unlocks premium pricing tiers where documentation burden exceeds FDA requirements. |
| Indian PLI Scheme Facility Expansion | Positions CDMOs to capture EU and US generic outsourcing demand under centralized procurement consolidation. |
| Hot-Melt Extrusion Coating Pilot Programs | Enables solvent-free functional layer application for continuous tablet pressing integration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating formulation chemists, CDMO procurement directors, pharmaceutical quality assurance leads, and equipment automation specialists. EMA excipient guideline updates, FDA stability guidance documents, CDSCO manufacturing standard circulars, and REACH substance restriction lists provided regulatory validation. Bottom-up coating line capacity estimates from Indian and German pharmaceutical corridors were triangulated against top-down excipient demand projections.
Data-stream reconciliation across coating type, application, end-user concentration, and formulation technology dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated pharmaceutical versus nutraceutical regulatory tiering, contract manufacturer versus integrated pharmaceutical house procurement patterns, and aqueous versus solvent-based process technology migration. CAGRs were derived from installed base expansion rates, bioequivalence standard tightening timelines, and generic outsourcing intensity indices.
The model holds under sustained REACH enforcement and CDSCO export standard convergence; deviation in solvent price volatility or nitrosamine contamination events would shift capacity expansion timing. Forecasts reflect documented assumptions about regulatory harmonization pace and equipment automation adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Batters and Coatings Market
Coatings
Dispersion Coating Market
Coatings
Europe Coil Coatings Market
Coatings
Gelcoat Market
Coatings
Carbon Fiber Coatings Market
Coatings
Food Grade Ceramic Coatings Market
Coatings
Middle East and Africa Super Hydrophobic Coatings Market
Coatings
UV Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
Coating Pre-Treatment Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Surface Protection Films Market
Coatings
Global Battery Coating Market