
 Intumescent Fire Retardant Coating Market | 2026-2036
Intumescent Fire Retardant Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Intumescent Fire Retardant Coating Market Insights
China's expanding petrochemical manufacturing base is reconfiguring regional supply dynamics for intumescent fire retardant coatings. PPG Industries leverages its automotive coatings expertise to cross-sell fire protection solutions into industrial markets. Akzo Nobel anchors European production capacity with specialized epoxy-based formulations for offshore platforms. Hempel A/S dominates marine application channels through its established shipyard relationships across East Asia.
Intumescent fire retardant coatings are reactive polymer systems that expand into insulating char layers when exposed to temperatures above their activation threshold, typically formulated with expandable graphite, ammonium polyphosphate, and melamine derivatives to achieve fire resistance ratings up to four hours on structural steel. Their primary industrial purpose is passive fire protection that maintains structural integrity during combustion events without compromising load-bearing capacity. Water-based formulations lead volume consumption in commercial construction due to lower VOC profiles and simplified application logistics, while epoxy-based systems command premium positioning in offshore and marine environments where chemical resistance and durability requirements are stringent. Graphite expansion technology occupies the largest share of active protection systems, though cementitious alternatives sustain relevance in heavy industrial settings requiring extreme temperature tolerance.
The EPA's NESHAP standards and OSHA's steel erection regulations shape formulation requirements and contractor certification protocols in the United States, while REACH compliance in Europe restricts certain halogenated flame retardant chemistries and drives substitution toward phosphorus-nitrogen intumescent systems. China's GB standards for fire safety in public buildings mandate specific coating thicknesses and testing certifications that filter market access for imported formulations. Stakeholders must monitor evolving carbon accounting frameworks under the EU Green Deal and China's dual carbon goals, as embodied carbon in coating production becomes a procurement criterion for major construction and energy sector buyers.
Market Dynamics
Water-based formulation technologies are compressing solvent-borne market share as EPA NESHAP enforcement tightens across US commercial construction corridors. This regulatory pressure intersects with contractor certification requirements and raw material supply reconfiguration to reshape competitive positioning.
Growth Catalysts
- EPA NESHAP VOC limits:US commercial construction firms face mandatory emission thresholds that accelerate water-based coating specification. Contractors seeking LEED compliance drive specification toward low-VOC systems.
- China's petrochemical expansion:Industrial corridor cities along the Yangtze River Delta generate concentrated demand for structural steel fireproofing in refinery and chemical processing facilities.
- Epoxy hybrid durability:Offshore platform operators in the North Sea specify advanced formulations combining chemical resistance with four-hour fire ratings for subsea infrastructure.
Market Restraints
- Expandable graphite supply concentration:Chinese processors control approximately three-quarters of refined graphite supply, creating input cost volatility for Western formulators.
- REACH chemical restrictions:ECHA scrutiny of halogenated flame retardants forces European manufacturers toward phosphorus-nitrogen systems with higher raw material costs.
- Cementitious coating substitution:Heavy industrial buyers in steel manufacturing and power generation select spray-applied cementitious systems for extreme temperature tolerance above 1,100°C.
Strategic Opportunities
- India's infrastructure build-out:Smart city mandates and metro rail expansion create underpenetrated specification channels for intumescent systems in commercial high-rise construction.
- EU Green Deal carbon accounting:Embodied carbon scoring in public procurement creates preference for coatings with verified lifecycle emissions data from major construction buyers.
- Digital specification platforms:Building information modeling integration allows coating manufacturers to embed fire resistance data directly into architect workflows, compressing traditional specification cycles.
Industry Challenges
- Applicator certification bottlenecks:OSHA steel erection regulations require specialized spray technician credentials that limit contractor pool expansion in fast-growth markets.
- Multi-standard testing complexity:Manufacturers must navigate divergent UL, BS, and GB fire resistance testing protocols, extending product validation timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intumescent Fire Retardant Coating Market |
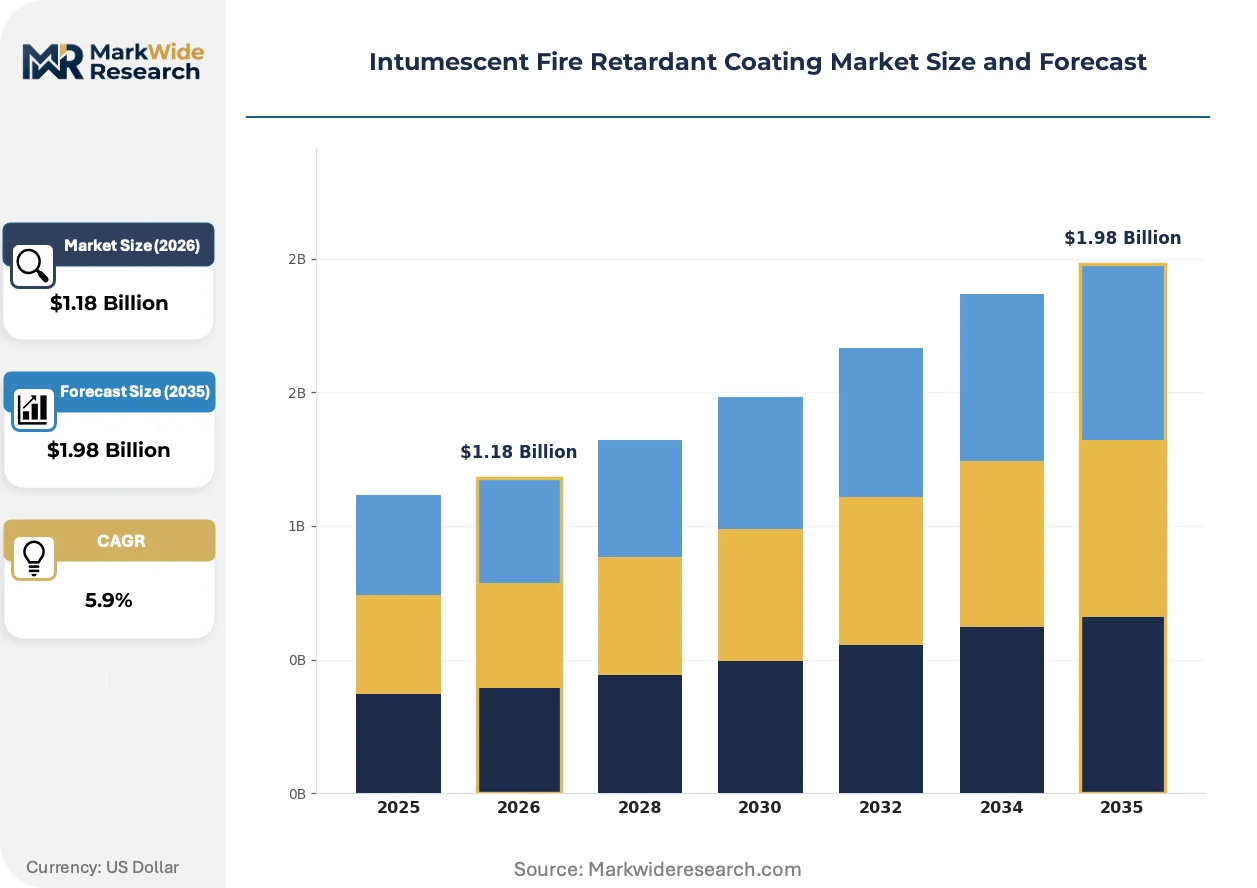
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.98 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy-Based, Acrylic-Based, Silicone-Based, Water-Based, Solvent-Based Technology: Graphite Expansion, Cementitious, Charring, Hydrated, Vermiculite Application: Structural Steel, Equipment Protection, Electrical Panels, Marine Vessels, Aerospace Structures End User: Construction Firms, Shipyards, Aerospace Contractors, Energy Sector Companies, Facility Management |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun, Hempel A/S, BASF, Kansai Paint, Promat International, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intumescent Fire Retardant Coating Market Trends and Innovations
Formulation chemistry is converging with digital specification tools and carbon accounting frameworks to redefine how fire protection systems are selected, validated, and procured across construction and industrial verticals.
Intumescent coating chemistry is hybridizing epoxy and water-based resin platforms to deliver combined chemical resistance and low-VOC profiles. Offshore platform operators in the North Sea and Gulf of Mexico specify these hybrid systems for subsea jacket structures where salt spray and hydrocarbon exposure coincide with fire safety requirements. This convergence is compressing the traditional segmentation between marine-grade epoxy and commercial construction water-based products.
REACH authorization procedures are restricting halogenated flame retardant chemistries across European manufacturing supply chains. ECHA substance evaluation has placed several brominated compounds under sunset clause review, forcing formulators toward phosphorus-nitrogen intumescent systems. German and Dutch industrial buyers now require full material disclosure documentation that filters market access for imported formulations lacking EU-registered chemical portfolios.
Specification workflows are migrating from contractor-driven selection to architect-embedded digital tools. Building information modeling platforms in US and UK commercial construction markets now incorporate fire resistance rating data as parametric inputs, displacing traditional catalog-based product comparison. This shift concentrates influence with design firms and engineering consultants who control model-based specification authority, particularly in London and New York high-rise developments.
Intumescent Fire Retardant Coating Market Segmentation
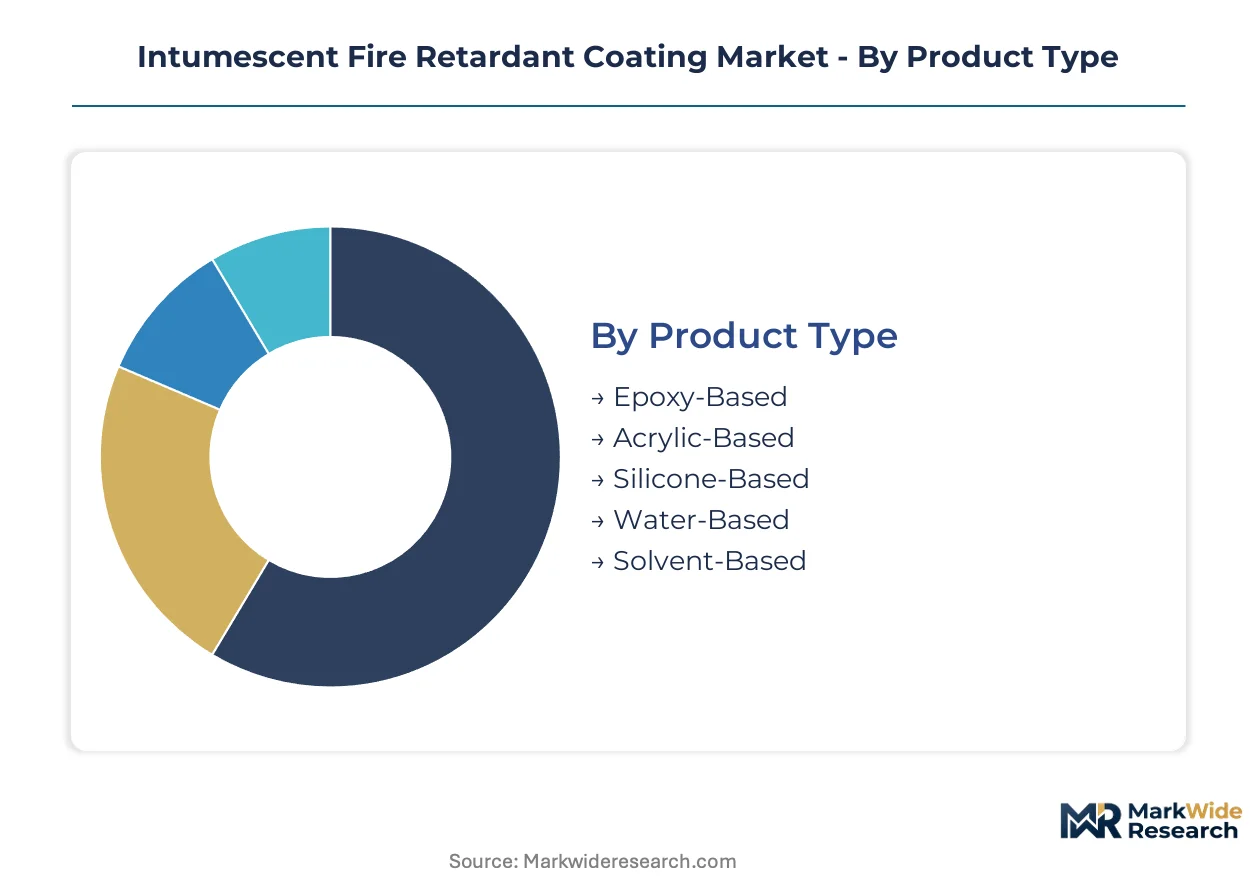
Intumescent coating procurement varies sharply by application environment, with specification cycles, certification requirements, and service intensity differing across marine, commercial construction, and industrial verticals. Understanding segment boundaries clarifies where formulation investments align with buyer willingness to pay for performance guarantees.
Product Type:
After-sales service intensity distinguishes these formulations, with epoxy and water-based systems requiring certified applicator networks and periodic inspection protocols that solvent-borne alternatives rarely demand.
- Water-Based:Acrylic and vinyl-acrylic emulsions dominate commercial construction specification due to sub-100 g/L VOC profiles that satisfy EPA NESHAP thresholds. Demand concentrates in US urban high-rise developments where LEED compliance and simplified cleanup reduce contractor mobilization costs. OSHA steel erection regulations mandate certified spray technicians, creating recurring training revenue streams for manufacturers.
- Epoxy-Based:Two-component systems combining amine-cured epoxies with intumescent fillers deliver chemical resistance and four-hour fire ratings for offshore platforms. North Sea operators specify these for subsea jacket structures where salt spray and hydrocarbon exposure coincide with fire safety requirements. Application requires climate-controlled spray environments and post-cure inspection regimens that anchor long-term service contracts.
- Acrylic-Based:Single-component ambient-cure formulations serve light industrial and commercial retrofit applications with moderate durability requirements.
- Silicone-Based:High-temperature stability above 300°C suits aerospace engine compartment specifications and specialized industrial exhaust systems.
- Solvent-Based:Declining specification in regulated markets persists in legacy industrial maintenance where rapid cure times outweigh emission concerns.
Water-based formulations hold the largest share; momentum sits with epoxy hybrids that bridge commercial and marine performance requirements.
Technology:
Raw material sourcing geography shapes competitive positioning across these activation mechanisms, with graphite supply concentration in China creating divergent cost structures for Western versus Asian formulators.
- Graphite Expansion:Intercalated graphite particles exfoliate into voluminous insulating char when heated above 200°C, forming the dominant activation chemistry for structural steel protection. Yangtze River Delta processors control refined graphite supply, concentrating input cost leverage with Chinese formulators serving domestic infrastructure build-out.
- Cementitious:Portland cement and lightweight aggregate systems withstand temperatures exceeding 1,100°C in steel manufacturing and power generation facilities where extreme thermal tolerance outweighs weight penalties. Heavy industrial buyers in Germany's Ruhr region and China's Hebei province select spray-applied cementitious alternatives for blast furnace proximity applications.
- Charring:Carbonaceous char-forming polymers serve niche electrical enclosure applications where thin-film intumescence balances space constraints with fire resistance.
- Hydrated:Alumina hydrate release chemically bound water for endothermic cooling in specialized cable tray and ductwork protection.
- Vermiculite:Exfoliated mica layers provide lightweight insulation for aerospace weight-critical structures with moderate fire rating requirements.
Graphite expansion dominates volume; cementitious systems are climbing the fastest in heavy industrial substitution patterns.
Application:
Specification authority resides with distinct stakeholder groups across these use cases, from architect-controlled BIM workflows in commercial construction to operator-driven technical standards in marine and aerospace procurement.
- Structural Steel:Column and beam fireproofing in commercial high-rise, industrial, and infrastructure projects constitutes the primary demand center. US commercial construction firms expanding specification of intumescent coatings face mandatory EPA NESHAP compliance that filters contractor qualification and product selection through emission thresholds.
- Marine Vessels:SOLAS convention requirements mandate fire protection for steel bulkheads, decks, and superstructures in commercial shipping. Shipyards across South Korea's Geoje cluster and China's Jiangsu province specify coating systems validated to IMO FTP Code protocols with witnessed factory production control audits.
- Equipment Protection:Skid-mounted processing modules and pressure vessel lagging in petrochemical facilities.
- Electrical Panels:Switchgear and transformer enclosure coatings where thin-film application preserves clearance dimensions.
- Aerospace Structures:Engine nacelle and auxiliary power unit compartment protection meeting FAA flammability standards.
Structural steel commands the largest share; marine vessels are gaining share fastest as shipyard capacity expands in East Asia.
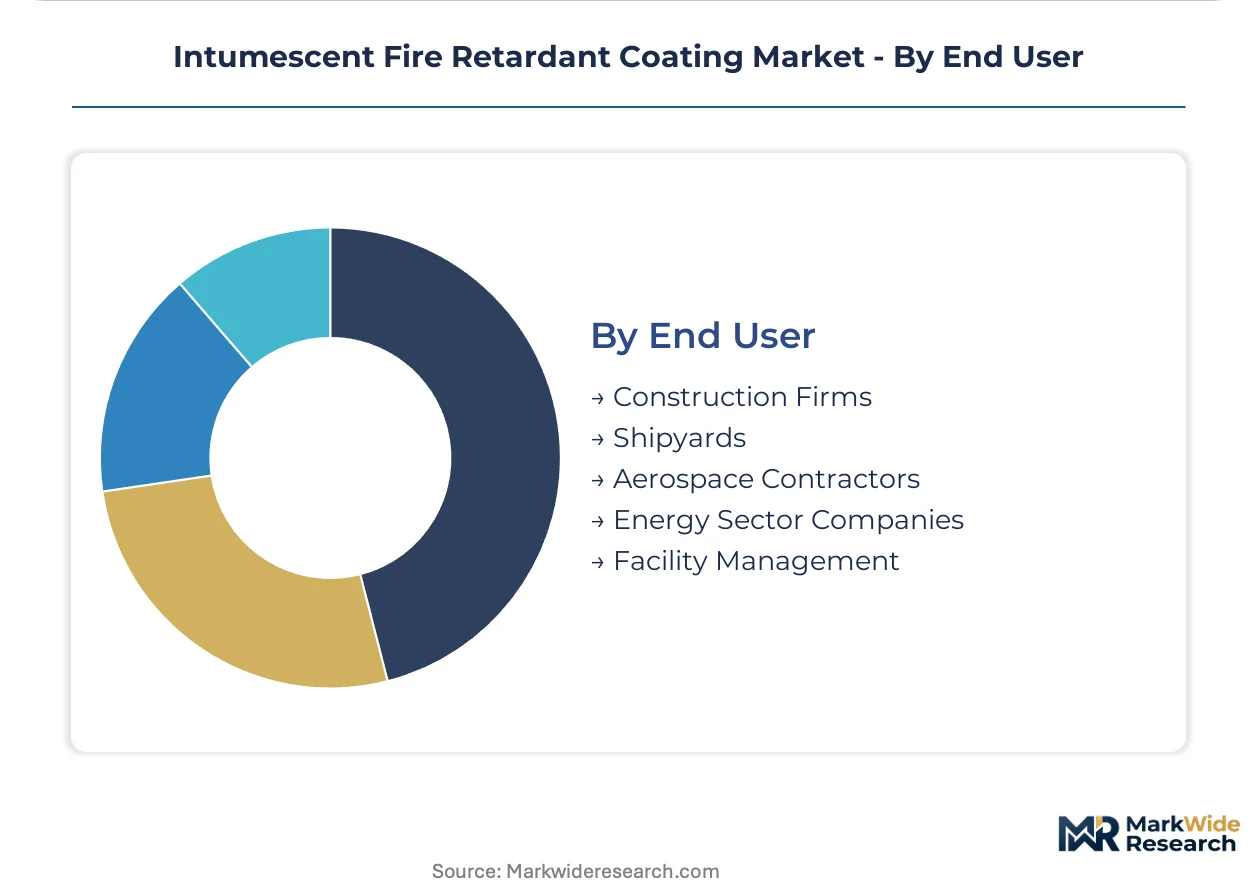
End User:
Procurement sophistication varies from commodity purchasing in facility management to engineered specification in energy sector capital projects, with certification documentation requirements scaling accordingly.
- Construction Firms:General and specialty contractors serving commercial, institutional, and industrial building markets drive specification through design-build and hard-bid procurement channels. China's state-owned construction enterprises in industrial corridor cities along the Yangtze River Delta generate concentrated demand for structural steel fireproofing in refinery and chemical processing facilities.
- Energy Sector Companies:Oil and gas operators, power utilities, and renewable energy developers specify coatings for onshore and offshore infrastructure with combined fire, corrosion, and thermal insulation requirements. North Sea platform operators mandate four-hour fire ratings with subsea durability validation that commands premium formulation pricing.
- Shipyards:Newbuild and repair facilities for commercial and naval vessels.
- Aerospace Contractors:OEM and MRO operations for commercial aviation and defense applications.
- Facility Management:Building owners and operators executing lifecycle maintenance and retrofit programs.
Construction firms hold the largest share; energy sector companies show the steepest expansion trajectory as offshore and petrochemical investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US commercial construction prioritizes low-VOC water-based systems for LEED compliance. Chinese industrial buyers favor graphite-based formulations for petrochemical infrastructure. European procurement embeds carbon accounting into coating selection criteria.
United States
Commercial high-rise development in New York, Chicago, and Los Angeles drives specification of water-based intumescent systems. EPA NESHAP enforcement mandates sub-100 g/L VOC thresholds that filter contractor qualification. Steel erection corridors in Texas and the Southeast generate concentrated demand for certified applicator networks.
China
Petrochemical expansion along the Yangtze River Delta and Bohai Rim creates structural steel fireproofing demand for refinery complexes. GB standards for public building fire safety mandate specific coating thicknesses and testing certifications. Infrastructure build-out in Chengdu-Chongqing and Xi'an anchors regional consumption clusters.
Germany
Industrial facility modernization in the Ruhr region and North Rhine-Westphalia sustains cementitious system demand for extreme temperature tolerance. REACH authorization restricts halogenated flame retardants, forcing substitution toward phosphorus-nitrogen formulations. Offshore wind construction in the North Sea commands epoxy hybrid systems with four-hour ratings.
South Korea
Shipyard capacity at Geoje and Ulsan generates marine vessel fire protection demand validated to IMO FTP Code protocols. Commercial construction in Seoul Capital Area specifies water-based systems for high-rise residential towers. The country's national industrial safety regulator enforces coating certification for public infrastructure projects.
India
Smart city mandates and metro rail expansion in Mumbai, Delhi-NCR, and Bangalore create specification channels for intumescent systems. Bureau of Indian Standards fire safety codes are tightening for commercial high-rise construction. State-owned construction enterprises in Gujarat and Maharashtra drive procurement volume for industrial corridor development.
Intumescent Fire Retardant Coating Market Competitive Landscape
Capability concentration sits with specialized coating formulators; scale advantage sits with diversified chemical conglomerates. The market structures around three tiers: global paint and coatings majors with fire protection divisions, regional specialists with certified applicator networks, and industrial chemical suppliers with intumescent additive portfolios. Dominant competitive moves include strategic partnerships with shipyard operators and capacity expansion into China's industrial corridor cities.
Among diversified coatings majors, Akzo Nobel N.V., PPG Industries, Inc., and Hempel A/S exemplify distinct archetypes. Akzo Nobel anchors European production capacity through its Netherlands-based operations. PPG Industries represents the cross-sector leverage model, extending automotive coatings expertise into adjacent industrial markets. Hempel A/S occupies a position within marine-specialized tier, with its Danish corporate structure reflecting long-standing shipyard channel relationships across East Asia.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun |
| Hempel A/S |
| BASF |
| Kansai Paint |
| Promat International |
| Sika AG |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Yangtze River Delta graphite processors compresses margin flexibility across all formulation tiers while simultaneously dictating where coating manufacturers locate blending capacity. This concentration forces Western formulators to absorb input volatility or cede share to integrated Chinese competitors serving domestic infrastructure build-out.
Pricing Analysis
Epoxy-based systems command 40-60% premia over water-based equivalents in North Sea offshore markets, with price differentiation anchored in IMO FTP Code certification tiers and four-hour fire rating validation. Cost compression in mid-tier commercial construction segments is intensifying because LEED-compliant contractors aggregate demand around sub-100 g/L VOC formulations. Facility management buyers exhibit highest price sensitivity, while energy sector procurement teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing for intumescent coatings concentrates with Akzo Nobel's Netherlands facilities, PPG's automotive-adjacent plants in the US Midwest, and Hempel's Danish marine-specialized operations. Raw material sourcing draws from Chinese graphite intercalation processors, German melamine derivative specialists, and US ammonium polyphosphate manufacturers. Tariff exposure on refined graphite imports threatens Western formulator margins. Distribution runs through certified applicator networks rather than commodity chemical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intumescent fire retardant coating market is recovering from cyclical lows as offshore platform investment and commercial high-rise construction accelerate simultaneously.
For Market Incumbents: Pre-empt cementitious coating substitution in heavy industrial segments by embedding carbon accounting data into specification packages for EU Green Deal procurement. Anchor capacity in China's Yangtze River Delta industrial corridor cities to capture petrochemical infrastructure demand. Deepen applicator certification networks to create switching costs against emerging regional specialists. For New Entrants and Emerging Players: India's smart city mandates and metro rail expansion in Mumbai, Delhi-NCR, and Bangalore represent the most penetrable geography for specification channel entry. Target state-owned construction enterprises in Gujarat and Maharashtra with Bureau of Indian Standards pre-certified formulations. Pursue digital specification platform partnerships to compress traditional architect-driven selection cycles. For Investors and Strategic Acquirers: REACH authorization reshapes the acquisition landscape toward phosphorus-nitrogen formulation specialists with EU-registered chemical portfolios. Five-to-ten year viability favors mid-cap coating formulators with captive applicator networks and verified lifecycle emissions data. Monitor ECHA substance evaluation timelines for brominated compound sunset clauses as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Processing | Yangtze River Delta captive supply secures input cost stability against volatile spot markets. |
| Water-Based Formulation Capacity Expansion | EPA NESHAP compliance positions manufacturers for LEED-driven contractor specification. |
| IMO FTP Code Certification Investment | Shipyard channel access at Geoje and Jiangsu clusters anchors marine revenue streams. |
| Carbon Accounting Platform Integration | EU Green Deal procurement criteria filter market access for verified low-emission coatings. |
| Certified Applicator Network Acquisition | OSHA steel erection compliance creates contractor scarcity value in fast-growth corridors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coating formulator R&D directors, certified applicator network managers, and petrochemical facility procurement leads; and secondary validation through customs trade records, EPA NESHAP enforcement disclosures, and ECHA authorization procedure documentation. Bottom-up volume estimates triangulated against top-down construction spending and offshore platform investment flows.
Forecast inputs considered formulation chemistry segmentation, end-use vertical procurement patterns, and regional regulatory framework evolution across the projection horizon. CAGRs derived from regression analysis against structural steel installation rates, shipyard capacity utilization, and petrochemical capital expenditure cycles. Modeled variables included water-based versus epoxy-based technology mix shifts and graphite expansion versus cementitious technology substitution thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by diversified coatings majors would shift outcomes. Quarterly review of ECHA substance evaluation timelines, EPA enforcement action frequencies, and Chinese industrial corridor construction permit issuances is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Automotive Specialty Coatings Market
Coatings
Global Smart Coating Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Marking Coatings Market
Coatings
Hull Coatings Market
Coatings
Coating Pigments Market
Coatings
North America Thermal Spray Market
Coatings
PACVD-Based Coatings Market
Coatings
2K Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
PU Coatings Market
Coatings
Global Radiation Cured Coatings Market
Coatings
US Industrial Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
United States Industrial Wood Coatings Market