
 Metallic Powder Coating Market | 2026-2036
Metallic Powder Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Metallic Powder Coating Market Analysis
Low-temperature cure chemistry is reshaping metallic powder coating deployment across heat-sensitive substrates like aluminum automotive components and engineered plastics. AkzoNobel Powder Coatings leverages its bonded metallic technology leadership to serve premium architectural and automotive accounts. PPG Industries, Inc. anchors North American supply through integrated resin-to-coating manufacturing. Tiger Coatings GmbH & Co. KG specializes in European decorative metallic finishes for furniture and appliance segments.
Metallic powder coating consists of thermosetting resin matrices—polyester, epoxy, or hybrid systems—loaded with bonded or dry-blend aluminum and mica flake pigments, then applied via electrostatic spray and thermally cured to form a durable, reflective film. The process yields finishes resistant to UV degradation, chemicals, and mechanical wear for exterior architectural cladding, vehicle wheels, and consumer appliances. Polyester-based metallic systems dominate exterior durability applications, while epoxy metallic coatings retain strong positions in functional indoor and corrosion-resistant segments. Hybrid formulations are gaining traction where cost-performance balance matters for appliance and general industrial OEMs.
EPA VOC regulations in the United States and REACH chemical restrictions in Europe constrain solvent-borne alternatives, channeling specification authority toward compliant powder metallic systems. China's GB standards and MEE environmental enforcement tighten emissions controls on coating operations in manufacturing zones. Stakeholders must track evolving cure-temperature thresholds and pigment bonding technologies to capture specification shifts in automotive lightweighting and renewable energy infrastructure.
Market Dynamics
Automotive lightweighting mandates are compressing cure-temperature requirements across metallic powder coating specifications, forcing formulators to reengineer polyester and hybrid chemistries for aluminum substrate compatibility.
Growth Catalysts
- REACH chemical restrictions:European formulators are pivoting from solvent-borne alternatives toward compliant low-VOC metallic powder systems for architectural and industrial applications.
- Aluminum wheel manufacturing:Automotive OEMs in China and Germany are specifying bonded metallic powder coatings for corrosion-resistant lightweight components.
- MEE environmental enforcement:China's tightened emissions controls on coating operations in manufacturing zones are accelerating facility upgrades to powder-based metallic finishing lines.
Market Restraints
- Aluminum flake pigment volatility:Raw material costs for bonded metallic pigments fluctuate with energy-intensive smelting operations concentrated in specific supplier geographies.
- Cure temperature thresholds:Heat-sensitive engineered plastics and composite substrates remain technically incompatible with standard thermosetting metallic powder chemistries.
- Capital equipment requirements:Electrostatic spray lines and thermal curing ovens demand significant upfront investment, constraining adoption among small-batch metal fabricators.
Strategic Opportunities
- Wind turbine tower manufacturing:Renewable energy infrastructure projects in coastal regions are specifying UV-resistant metallic polyester coatings for offshore corrosion protection.
- GB standards alignment:China's national standardization push for green building materials creates specification pathways for certified low-emission metallic finishes.
- UV-curable metallic systems:Convergence of powder coating and radiation-cure technologies enables room-temperature processing for temperature-critical automotive electronics housings.
Industry Challenges
- Formulation chemistry expertise:Shortages of polymer scientists skilled in low-temperature cure kinetics and pigment bonding technology constrain R&D throughput at coating manufacturers.
- Cross-border certification timelines:Obtaining simultaneous EPA VOC compliance and REACH registration for new metallic chemistries extends product launch cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallic Powder Coating Market |
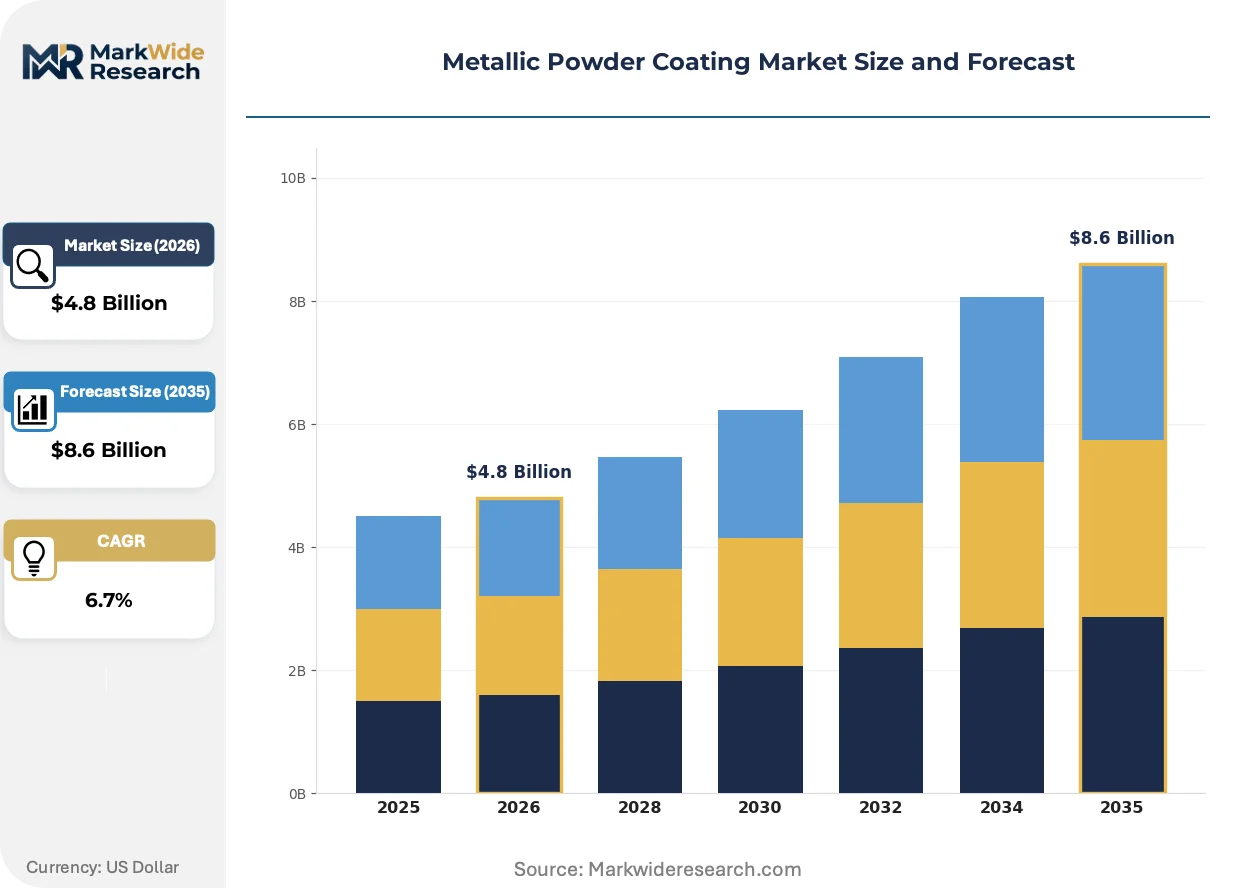
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Epoxy, Polyester, Hybrid Application: Automotive, Furniture, Appliances, Aerospace Technology: Electrostatic Spray, Fluidized Bed, Heat Cure, UV Cure End User: Manufacturers, Contractors, OEMs, Distributors |
| Companies Covered | AkzoNobel Powder Coatings, PPG Industries, Inc., Axalta Coating Systems, The Sherwin-Williams Company, Jotun, Tiger Coatings GmbH & Co. KG, TCI Powder, IGP Pulvertechnik AG, Primatek Coatings OÜ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallic Powder Coating Market Emerging Trajectories
Formulation chemistry is fragmenting across temperature-specific variants as substrate diversity expands beyond traditional steel and aluminum into engineered plastics and composites.
Bonded metallic pigment technology is migrating from dry-blend aluminum flake systems toward encapsulated particle architectures that eliminate dusting hazards and improve color consistency. Tier-one automotive suppliers in Germany and Japan are specifying bonded metallics for Class A surface wheels and trim components. This migration from conventional blending methods is compressing the performance gap between premium and standard metallic finishes.
EPA VOC regulations in the United States are channeling specification authority away from liquid metallic paints toward compliant powder alternatives in appliance and general industrial segments. The regulatory pressure is accelerating capital redeployment from solvent-borne spray booths toward electrostatic powder lines. Metal furniture and shelving manufacturers in the Midwest and Southeast are responding fastest due to proximity to integrated powder coating resin supply.
Consolidated procurement by multinational appliance OEMs is displacing fragmented distributor networks with direct formulator relationships and annual volume agreements. Purchasing departments at major refrigerator and washing machine manufacturers now specify bonded metallic finishes by SKU rather than generic performance criteria. This concentration is most visible in China's Yangtze River Delta appliance manufacturing cluster.
Metallic Powder Coating Market Segmentation
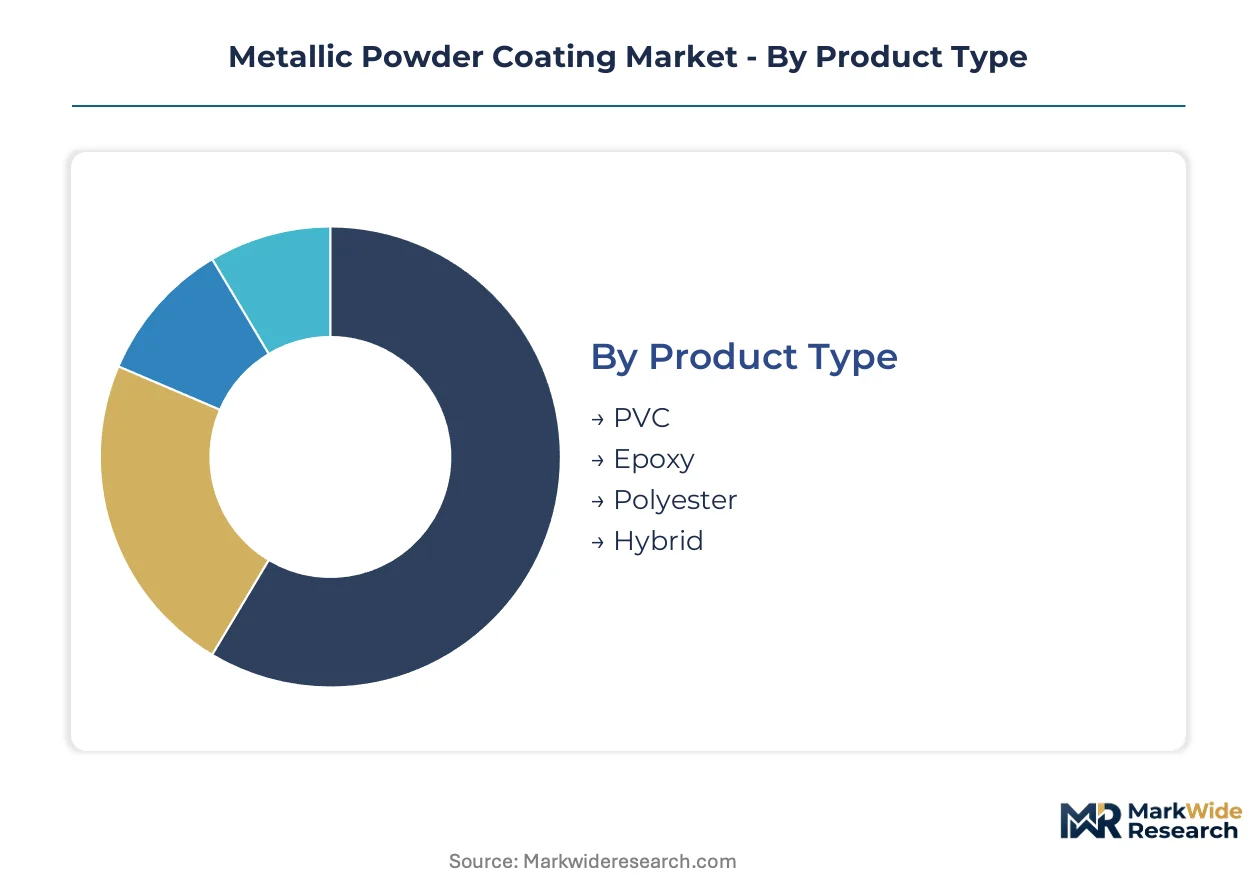
Metallic powder coating segmentation reflects divergent performance requirements across substrate types and curing constraints. Formulators configure resin matrices and application methods to match specific durability, temperature, and aesthetic specifications demanded by end-use industries.
Product Type:
Mature thermosetting chemistries anchor volume production while emerging hybrid formulations capture specification shifts in temperature-sensitive applications.
- Polyester:Exterior-grade thermosetting resin systems dominate architectural cladding and automotive wheel applications where UV resistance and color retention are paramount. Chinese appliance manufacturers in the Yangtze River Delta specify bonded metallic polyesters for refrigerator and washing machine panels.
- Epoxy:These systems deliver superior chemical resistance and adhesion for functional indoor applications. German automotive suppliers specify epoxy metallic coatings for under-hood components and corrosion-protected chassis parts requiring solvent resistance.
- Hybrid:Cost-optimized formulations blend epoxy and polyester chemistries for general industrial OEMs balancing performance and economics. Japanese appliance manufacturers favor hybrids for interior metal shelving and cabinetry.
- PVC:Specialized plastisol-based metallic systems serve niche flexible coating applications in furniture edge banding and decorative trim.
Polyester handles the majority of throughput; hybrid is the fastest mover on share.
Application:
Cost tier stratification separates premium specification markets from high-volume commoditized finishing.
- Automotive:OEM wheel manufacturing and exterior trim components demand Class A surface quality with bonded metallic pigments. German and Japanese tier-one suppliers specify low-temperature cure variants for aluminum lightweighting programs.
- Appliances:Refrigerator, washing machine, and dishwasher panels consume bulk metallic powder volumes through consolidated procurement by multinational OEMs. Chinese production clusters drive bonded metallic specification for premium finish tiers.
- Furniture:Metal shelving, office systems, and residential furniture utilize standard metallic finishes where cost efficiency outweighs extreme durability requirements.
- Aerospace:Specialized high-performance coatings for interior cabin components and non-critical exterior surfaces require stringent flame retardancy and outgassing compliance.
Appliances command the largest volume commitment; automotive is expanding most quickly as lightweighting mandates proliferate.
Technology:
Application method selection depends on substrate geometry complexity and production throughput requirements.
- Electrostatic Spray:The dominant application method deposits charged powder particles onto grounded metal substrates with 95%+ transfer efficiency. US appliance and furniture manufacturers have converted solvent-borne lines to electrostatic spray to meet EPA VOC compliance.
- Heat Cure:Conventional thermal crosslinking remains standard for steel and aluminum substrates tolerating 180-200°C cure cycles. European architectural metal fabricators specify heat-cured metallic polyesters for building cladding systems.
- UV Cure:Emerging radiation-cured powder systems enable room-temperature processing for heat-sensitive engineered plastics and composite automotive components.
- Fluidized Bed:Dip-coating method serves thick-film functional applications such as pipe coatings and electrical insulation where edge coverage is critical.
Electrostatic spray processes the highest substrate throughput; UV cure is gaining specification fastest in temperature-critical segments.
End User:
Customer type determines procurement pattern complexity and technical service intensity.
- OEMs:Integrated manufacturers specify coatings by SKU with direct formulator relationships and annual volume agreements. Major appliance OEMs in China and Germany consolidate metallic powder procurement through centralized purchasing departments.
- Manufacturers:Metal fabricators and component suppliers purchase through distributor networks or direct accounts based on scale and technical support requirements.
- Contractors:Architectural finishing specialists and job shops serve project-based demand with flexible order quantities and color-matching services.
- Distributors:Regional stocking distributors bridge formulators and fragmented small-batch users with inventory and technical support.
OEMs concentrate the largest procurement volumes; manufacturers are shifting fastest toward direct formulator relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs export bonded metallic powder coatings to tier-one suppliers across Eastern Europe and North America, establishing a trade corridor that channels European formulation expertise into foreign assembly plants.
United States
Appliance manufacturers in the Midwest and Southeast drive electrostatic spray line conversions to meet EPA VOC compliance deadlines. Metal furniture fabricators in Ohio and Tennessee consolidate procurement through direct formulator relationships rather than distributor networks. Chicago-area coating operations now specify low-temperature cure variants for aluminum architectural components.
Germany
REACH chemical restrictions force formulators to eliminate solvent-borne alternatives from automotive specification sheets. Tier-one suppliers in Bavaria and Baden-Württemberg specify bonded metallic systems for Class A surface wheels and exterior trim. The Stuttgart automotive cluster anchors European demand for premium metallic polyester formulations.
China
MEE environmental enforcement accelerates facility upgrades from solvent-borne lines to powder-based metallic finishing across manufacturing zones. Yangtze River Delta appliance clusters drive bulk consumption of bonded metallic technologies for refrigerator and washing machine panels. Shanghai-based OEMs now consolidate annual volume agreements with direct formulator accounts.
Japan
METI industrial standards push coating manufacturers toward UV-curable metallic systems for heat-sensitive automotive electronics housings. Kansai-region appliance manufacturers favor hybrid formulations for interior metal shelving and cabinetry. Osaka-based suppliers specify low-temperature cure chemistry for aluminum lightweighting programs.
Metallic Powder Coating Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement authority among consolidated OEMs while fragmenting small-batch demand through regional distributors. The vendor base separates into three strategic archetypes: integrated resin-to-coating manufacturers, bonded metallic technology specialists, and regional electrostatic application service providers. Dominant competitive moves include backward integration into captive resin supply and geographic expansion through direct sales offices in Chinese manufacturing clusters.
Among Netherlands-based chemical conglomerates, AkzoNobel Powder Coatings occupies a position exemplifying bonded metallic technology leadership. PPG Industries, Inc. anchors the North American supply vector through integrated manufacturing structures. Tiger Coatings GmbH & Co. KG represents the European decorative finishes specialist archetype within furniture and appliance segments.
| Leading Market Players |
|---|
| AkzoNobel Powder Coatings |
| PPG Industries, Inc. |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Jotun |
| Tiger Coatings GmbH & Co. KG |
| TCI Powder |
| IGP Pulvertechnik AG |
| Primatek Coatings OÜ |
| Others |
Supply Flow & Price Mechanics
Aluminum smelting capacity concentration in China and Russia funnels pigment cost volatility directly into bonded metallic powder coating margins, compressing formulator pricing power while concentrating margin pools with resin suppliers possessing captive petrochemical feedstocks.
Pricing Analysis
Low-temperature cure chemistry commands premium positioning over standard heat-cured systems, with UV-curable metallic formulations emerging at the frontier tier. Three-tier pricing structure across premium bonded metallic, standard dry-blend, and economy hybrid systems stratifies by pigment bonding technology and cure temperature capability. Cost compression in economy tiers is intensifying because Chinese appliance OEMs consolidate procurement through annual volume agreements. Contract manufacturers exhibit highest price sensitivity; automotive tier-one suppliers prioritize surface quality over unit cost.
Supply Chain Analysis
Tariff exposure between China and Western automotive markets dominates supply chain risk planning for bonded metallic pigment sourcing. Resin production concentrates in Germany, China, and the United States; aluminum flake pigment supply draws from Chinese smelters and Russian metal traders. Single-source vulnerability persists for encapsulated metallic pigment technologies held by limited European specialists. Distribution runs through direct formulator relationships with multinational OEMs and regional stocking distributors serving fragmented metal fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metallic powder coating chemistry is shifting toward platform-standardized low-temperature systems, with interoperability between polyester, hybrid, and UV-curable formulations creating ecosystem lock-in for first-mover formulators.
For Market Incumbents: Entrench bonded metallic technology leadership through backward integration into captive resin supply and certification investment for REACH-compliant low-VOC systems. UV-curable metallic entrants threaten premium positioning; defend through exclusive supply agreements with German automotive tier-ones specifying Class A surface wheels.
For New Entrants and Emerging Players: Build out UV-curable metallic production capacity targeting Japanese automotive electronics housings and heat-sensitive engineered plastics. White-space concentration sits with temperature-critical substrates incompatible with standard thermosetting chemistries. Go-to-market leverage rests on direct technical service partnerships with Osaka-based OEMs.
For Investors and Strategic Acquirers: Capital is best deployed toward bonded metallic technology specialists with encapsulated pigment IP and established automotive qualification pathways. Long-term viability favors formulators positioned for aluminum lightweighting mandates and renewable energy infrastructure coating specifications. Monitor UV-curable metallic adoption rates in Japanese automotive electronics as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyester production insulates AkzoNobel and PPG from petrochemical feedstock volatility. |
| Low-Temperature Cure R&D Investment | PPG's Chicago-area operations now specify sub-160°C variants for aluminum architectural components. |
| Bonded Metallic Pigment Capacity Expansion | Tiger Coatings scales encapsulated particle output to serve German furniture OEM consolidation. |
| Direct Formulator Relationship Programs | Yangtze River Delta appliance clusters bypass distributors for annual volume agreements with resin-to-coating manufacturers. |
| UV-Curable Metallic Technology Licensing | Japanese METI standards push Osaka suppliers toward radiation-cure partnerships for automotive electronics. |
Methodological Framework
Operator-level perspectives from coating plant managers, automotive OEM procurement leads, appliance manufacturing engineers, and resin R&D directors anchored the qualitative base. Primary interview data combined with secondary validation from customs/trade databases, SEC 10-K filings, and Cefic industry reports. Bottom-up volume modeling triangulated against top-down market sizing across resin type, cure technology, and end-use application.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory enforcement pathways over the projection horizon. Segmentation dimensions modeled include resin chemistry tier, cure temperature threshold, substrate material class, and regional production cluster. CAGRs derived from fitted growth curves incorporating automotive lightweighting program timelines and MEE environmental enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed resin producers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Clear Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Yacht Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Coating Binders Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Epoxy Surface Coatings Market
Coatings
Compound Coating Market
Coatings
Global Polyurea Coating Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Coating Pigments Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Canada Floor Coatings Market