
 Electrical Appliance Coatings Market | 2026-2036
Electrical Appliance Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Appliance Coatings Market Intelligence
The capital-intensity gap between integrated resin producers and regional blenders is collapsing as electrodeposition lines require dedicated pretreatment chemistry and captive supply chains. Henkel AG & Co. KGaA leverages its adhesive and sealant infrastructure to cross-sell integrated coating systems into appliance OEM accounts. Evonik Industries AG sustains R&D intensity in specialty acrylic monomers that anchor premium refrigerator liner formulations. PPG Industries competes through powder coating technology leadership in washing machine drum applications across North American assembly plants.
Electrical appliance coatings comprise thermoset and thermoplastic film-forming systems applied to metal, glass, and polymer substrates to provide corrosion resistance, dielectric insulation, and aesthetic finish in consumer and commercial equipment. Epoxy formulations dominate water heater and dishwasher interiors due to cathodic disbondment resistance in hot aqueous environments. Powder coating technology leads volume in refrigerator and air conditioner cabinets where zero-VOC compliance and thick-film edge coverage offset higher capital requirements. Fluoropolymer segments occupy premium niches in microwave cavity coatings where non-stick performance and thermal cycling durability command price premiums over standard polyester alternatives.
EPA emission standards and REACH chemical registration frameworks restrict solvent-borne coating formulations while accelerating waterborne and powder system adoption across appliance manufacturing bases. CE marking under the EU Ecodesign Directive mandates recoverable and recyclable material content, directly influencing coating selection for appliances sold into European markets. FDA indirect food-contact regulations govern interior coatings for refrigerators and dishwashers in the United States, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as fluoropolymer coatings face prospective substitution pressure from silicone and hybrid ceramic alternatives.
Market Dynamics
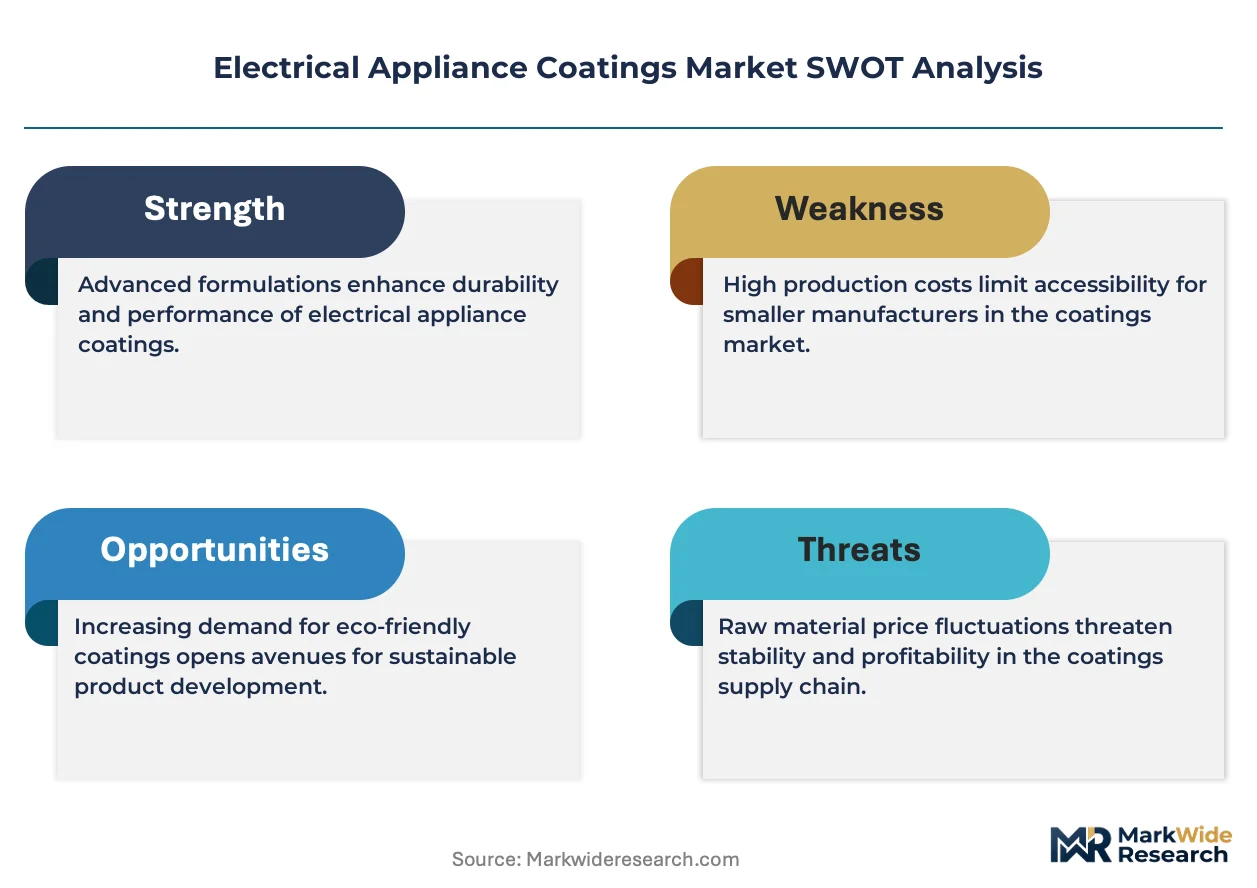
Waterborne polyurethane systems are compressing the capital barrier between integrated resin producers and regional blenders as electrodeposition lines demand dedicated pretreatment chemistry and captive supply chains. This structural shift is reshaping vendor economics across refrigerator and air conditioner coating procurement.
Growth Catalysts
- REACH chemical registration frameworks:These EU protocols restrict solvent-borne formulations while accelerating waterborne and powder system adoption across appliance manufacturing bases in Germany and neighboring jurisdictions.
- Refrigerator liner formulations:Specialty acrylic monomers anchor premium dielectric insulation performance as OEMs scale orders for high-durability coatings under tightening energy-efficiency regulations.
- Washing machine drum applications:Powder coating technology leads volume in North American assembly plants where zero-VOC compliance and thick-film edge coverage offset higher capital requirements.
Market Restraints
- Fluoropolymer feedstock concentration:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions create substitution pressure from silicone and hybrid ceramic alternatives.
- Hot aqueous environment limitations:Epoxy formulations dominate water heater and dishwasher interiors, but cathodic disbondment resistance requirements limit material flexibility in these segments.
- CE marking compliance costs:The EU Ecodesign Directive mandates recoverable and recyclable material content, creating certification barriers for non-compliant suppliers targeting European markets.
Strategic Opportunities
- China appliance production clusters:Coating innovation centers overlap with manufacturing gravity in coastal provinces, creating localized supply chain integration potential for waterborne system providers.
- Microwave cavity premium niches:Non-stick performance and thermal cycling durability command price premiums over standard polyester alternatives in this underpenetrated application segment.
- FDA indirect food-contact tailwinds:Interior coatings for refrigerators and dishwashers in the United States face compliance barriers that certified suppliers can leverage for margin expansion.
Industry Challenges
- Electrodeposition line capex intensity:Dedicated pretreatment chemistry requirements demand significant capital deployment, compressing returns for mid-scale regional blenders.
- Cross-jurisdictional PFAS harmonization:Evolving per- and polyfluoroalkyl substance restrictions lack alignment between EPA protocols and REACH frameworks, complicating formulation standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Appliance Coatings Market |
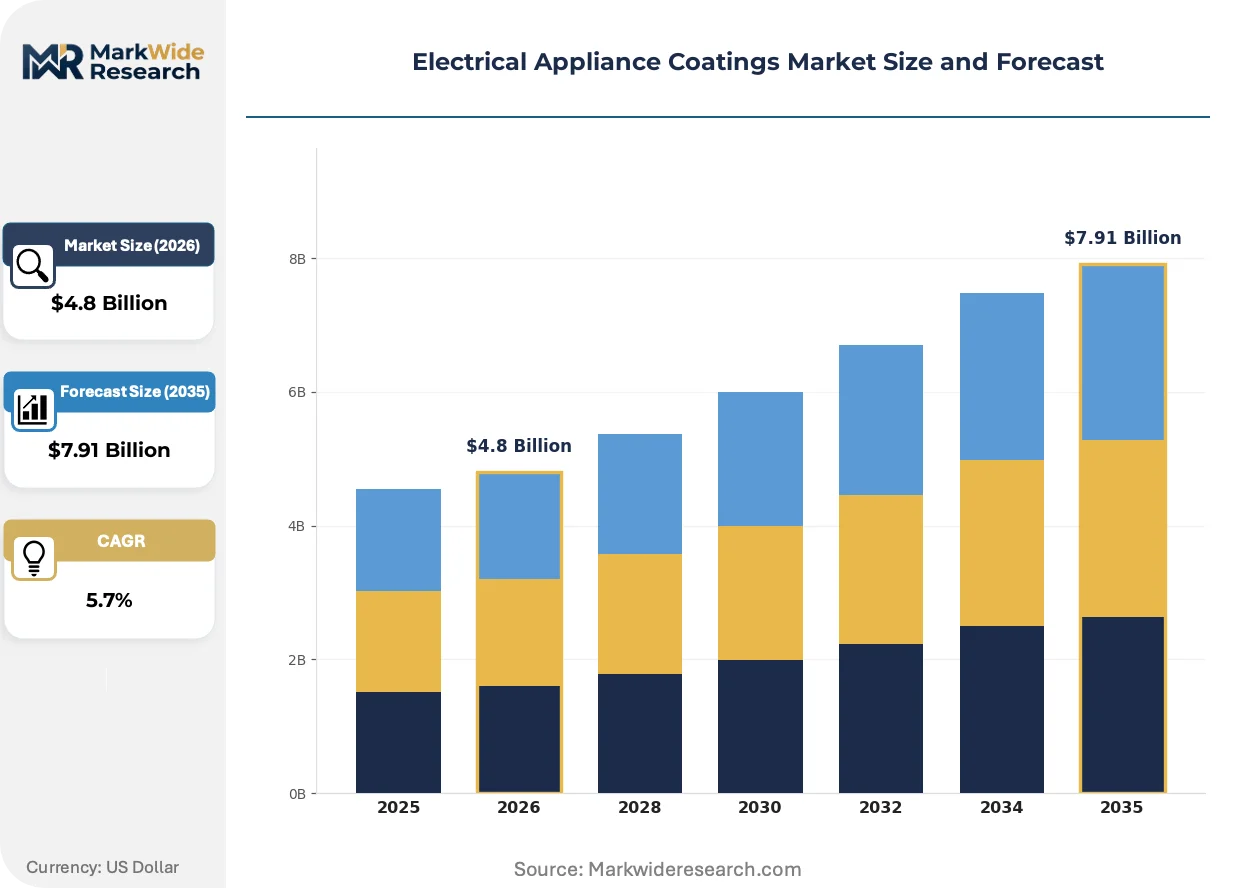
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Acrylic, Polyurethane, Polyester, Silicone, Fluoropolymer Technology: Spray Coating, Powder Coating, Dip Coating, Roll Coating, Brush Coating, Electrodeposition Application: Refrigerators, Washing Machines, Air Conditioners, Microwaves, Dishwashers, Water Heaters End User: OEMs, Aftermarket Suppliers, Contract Manufacturers, Appliance Retailers |
| Companies Covered | Henkel AG & Co. KGaA, Koninklijke DSM N.V., Evonik Industries AG, Elantas GmbH, Nippon Electric Glass Co., Ltd., Axalta Coating Systems Ltd., AGC Chemicals Europe Ltd., CEKO Inc., PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Appliance Coatings Market Strategic Shifts & Innovations
Formulation chemistry and application technology are converging to eliminate solvent-borne systems from major appliance categories. Three developments are compressing incumbent positions.
Waterborne polyurethane is supplanting solvent-based epoxy primers in refrigerator cabinet production. Major OEMs in Germany and the United States are converting spray lines to accommodate these lower-VOC systems. The technology is supplanting conventional solvent platforms by enabling compliance with EPA emission standards without sacrificing film-build performance on complex geometries.
REACH authorization procedures for chromium trioxide in passivation layers are forcing appliance manufacturers toward trivalent chrome and chrome-free pretreatments. This regulatory shift elevates capital requirements for coating lines serving European markets. Dishwasher interior segments face the steepest reformulation timelines as hexavalent chrome restrictions tighten under ECHA sunset date pressures.
Integrated coating-adhesive-sealant procurement bundles are consolidating vendor relationships at major OEM accounts. Henkel's cross-selling infrastructure exemplifies this pattern, displacing standalone coating suppliers in refrigerator and air conditioner assembly contracts. China-based manufacturers show the fastest adoption of bundled supply agreements, compressing margins for pure-play coating specialists.
Electrical Appliance Coatings Market Segmentation
Coating procurement channels in appliance manufacturing diverge sharply by application scale and regulatory exposure. Understanding these pathways reveals where formulation premiums concentrate and where commodity substitution pressure intensifies.
Product Type:
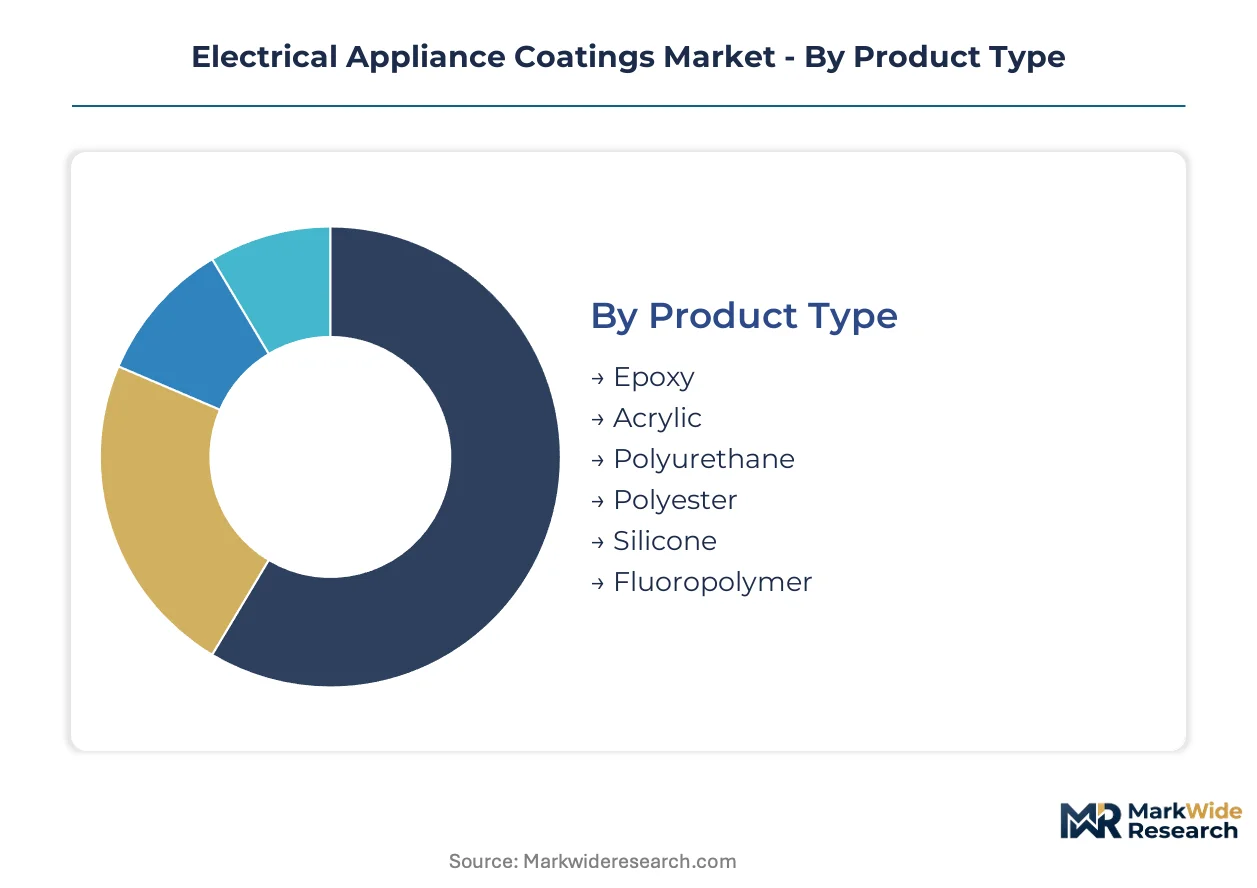
Channel flows split between captive resin production for high-volume OEMs and third-party supply for specialized formulations. Epoxy and polyurethane dominate direct procurement channels serving water heater and refrigerator liner applications.
- Epoxy:Thermoset polymer systems deliver cathodic disbondment resistance in hot aqueous environments. Demand concentrates in water heater and dishwasher interior coatings under FDA indirect food-contact compliance requirements in the United States.
- Polyurethane:Waterborne formulations displace solvent-based systems under EPA emission protocols and REACH frameworks. OEM procurement in Germany and the United States is scaling orders for refrigerator cabinet applications where energy-efficiency regulations tighten film-build specifications.
- Acrylic:Specialty monomer formulations anchor dielectric insulation performance in premium refrigerator liner systems.
- Polyester:Standard thermoset films serve commodity refrigerator and air conditioner cabinets with cost-optimized edge coverage.
- Silicone:Hybrid ceramic alternatives gain substitution traction as fluoropolymer feedstock faces prospective PFAS restrictions.
- Fluoropolymer:Non-stick thermal cycling durability commands price premiums in microwave cavity coatings.
Epoxy dominates installed base. Polyurethane is where expansion concentrates.
Technology:
Capital intensity separates electrodeposition and powder coating lines serving tier-one OEMs from spray and dip systems used by contract manufacturers and aftermarket channels.
- Powder Coating:Zero-VOC compliance and thick-film edge coverage offset higher capital requirements in refrigerator and air conditioner cabinet production. North American assembly plants lead procurement volume for washing machine drum applications.
- Electrodeposition:Cathodic electrodeposition lines demand dedicated pretreatment chemistry and captive supply chains, collapsing the capital-intensity gap between integrated resin producers and regional blenders. China-based appliance clusters show fastest adoption of integrated coating-adhesive-sealant procurement bundles.
- Spray Coating:Flexible application systems serve aftermarket suppliers and lower-volume contract manufacturers.
- Dip Coating:Batch processing accommodates irregular geometries in water heater tank interiors.
- Roll Coating:Continuous film application serves flat panel refrigerator cabinet production.
- Brush Coating:Manual touch-up and repair applications serve appliance retailer service channels.
Electrodeposition commands the highest capital deployment per line. Powder coating is climbing the fastest in new installation permits.
Application:
Regulatory exposure varies by appliance category, with food-contact and energy-efficiency mandates driving specification divergence across end-use procurement.
- Refrigerators:Liner and cabinet coatings face dual pressure from FDA indirect food-contact regulations and tightening energy-efficiency standards. Dielectric insulation performance requirements favor specialty acrylic and polyurethane formulations.
- Air Conditioners:Exterior cabinet durability demands balance UV resistance with zero-VOC compliance under EPA emission protocols.
- Washing Machines:Drum coatings prioritize abrasion resistance and thick-film coverage where powder technology leads.
- Microwaves:Cavity coatings occupy a premium niche where fluoropolymer non-stick performance commands price differentiation.
- Dishwashers:Hot aqueous environment exposure drives epoxy specification for interior surfaces.
- Water Heaters:Cathodic disbondment resistance requirements limit material flexibility to epoxy-dominant formulations.
Refrigerators anchor coating volume procurement. Microwave cavity coatings show the steepest expansion trajectory in premium formulation demand.
End User:
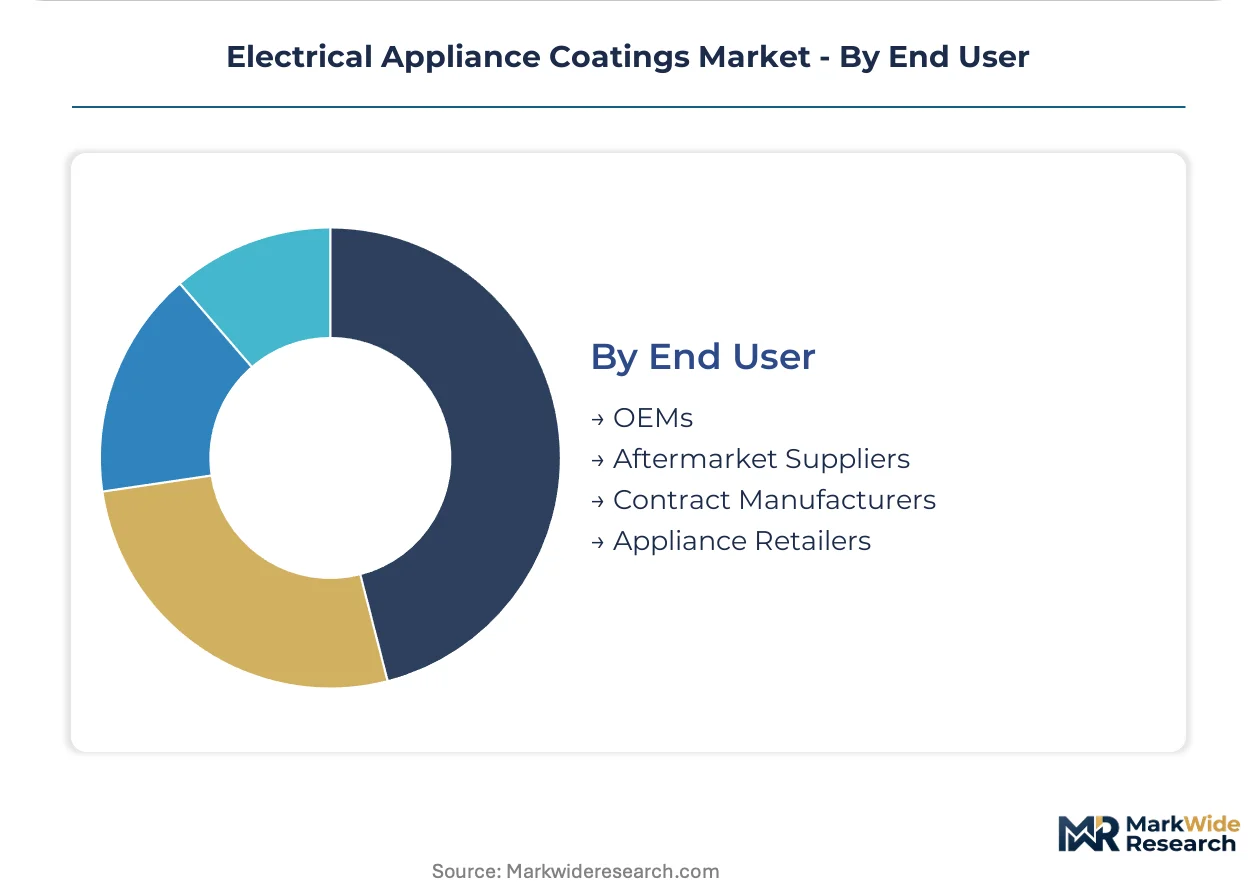
Procurement authority concentrates with OEMs specifying integrated coating systems, while aftermarket and retail channels fragment across regional blenders and service networks.
- OEMs:Integrated appliance manufacturers scale orders for high-durability formulations with direct resin producer relationships. Bundled coating-adhesive-sealant procurement is displacing standalone coating suppliers in major assembly contracts.
- Contract Manufacturers:Assembly outsourcing in China coastal provinces creates localized supply chain integration potential for waterborne system providers.
- Aftermarket Suppliers:Repair and refurbishment channels favor spray and brush application flexibility over capital-intensive line technologies.
- Appliance Retailers:Service network coating procurement concentrates in touch-up and warranty repair volumes with limited formulation specification authority.
OEMs dominate specification authority. Contract manufacturers are gaining share fastest in coastal China production clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for premium refrigerator liner formulations, while contract manufacturers in coastal China prioritize cost-optimized waterborne systems. This demand-elasticity contrast shapes regional procurement patterns and supplier margin structures across the forecast horizon.
China
Appliance production clusters in Guangdong and Zhejiang provinces drive concentrated coating demand from Haier, Midea, and Gree assembly facilities. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate waterborne polyurethane adoption in refrigerator cabinet manufacturing. Qingdao and Ningbo coating innovation centers are integrating electrodeposition lines with captive adhesive supply chains to serve expanding OEM procurement bundles.
Germany
Bosch and Miele production facilities in Bavaria and North Rhine-Westphalia specify high-durability formulations for export-oriented appliance lines. REACH authorization procedures for chromium trioxide force rapid conversion to trivalent chrome and chrome-free pretreatments under ECHA sunset date pressures. Stuttgart and Munich industrial corridors host integrated resin producers collapsing the capital-intensity gap with regional blenders through dedicated supply chain investments.
United States
Whirlpool and GE Appliance assembly plants in Ohio, Tennessee, and South Carolina scale orders for energy-efficient refrigerator coatings under tightening federal efficiency standards. EPA emission protocols restrict solvent-borne formulations while accelerating powder coating adoption in washing machine drum applications. The FDA indirect food-contact regulatory framework creates compliance barriers that certified suppliers leverage for margin expansion in interior coating segments.
Japan
Panasonic and Hitachi manufacturing bases in the Kanto and Kansai regions demand fluoropolymer cavity coatings for premium microwave production targeting export markets. METI energy-efficiency standards drive specification upgrades in refrigerator liner formulations with enhanced dielectric insulation performance. Osaka chemical industry clusters sustain specialty acrylic monomer production anchoring premium appliance coating supply chains.
South Korea
Samsung and LG production complexes in Gyeonggi-do and Gwangju prioritize powder coating technology for air conditioner cabinets serving Southeast Asian export markets. MFDS food-contact material regulations align with FDA frameworks, creating parallel compliance requirements for refrigerator interior coatings. The Busan-Ulsan industrial corridor concentrates electrodeposition line investments with integrated pretreatment chemistry capabilities.
Electrical Appliance Coatings Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the electrical appliance coatings market. Integrated resin producers with captive adhesive and sealant infrastructure command premium positioning in bundled procurement contracts, while regional blenders compete on formulation flexibility and localized service. Three archetypes dominate competitive dynamics: diversified chemical conglomerates with cross-selling capabilities, specialty monomer specialists anchoring premium dielectric formulations, and powder coating technology leaders in high-volume cabinet applications. M&A activity concentrates on adhesive-coating integration plays, while capacity expansion focuses on waterborne polyurethane lines in China and Germany.
Within the diversified chemical conglomerate tier, Henkel AG & Co. KGaA and Evonik Industries AG exemplify archetypes leveraging cross-infrastructure advantages. Henkel's adhesive and sealant footprint supports integrated coating system penetration at major OEM accounts. Evonik occupies a position in specialty acrylic monomer supply chains that anchor premium refrigerator liner formulations. Among coating technology specialists, PPG Industries represents the powder coating leadership archetype in North American washing machine drum applications.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Koninklijke DSM N.V. |
| Evonik Industries AG |
| Elantas GmbH |
| Nippon Electric Glass Co., Ltd. |
| Axalta Coating Systems Ltd. |
| AGC Chemicals Europe Ltd. |
| CEKO Inc. |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day resin inventory cycles concentrate purchasing power among integrated producers while compressing margin capture for regional blenders serving appliance OEMs in Germany and the United States. This lead-time band tightens further under REACH and EPA emission protocols that disqualify non-compliant suppliers from specification lists.
Pricing Analysis
After-sales service and warranty repair revenue anchors lifetime value for coating suppliers embedded in OEM maintenance networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified food-contact formulations from commodity cabinet coatings. Cost compression in waterborne polyurethane feedstocks is intensifying because electrodeposition line investments demand captive supply chain commitments. Contract manufacturers in coastal China exhibit highest price sensitivity, while German OEMs demonstrate lowest elasticity for REACH-compliant specialty acrylics.
Supply Chain Analysis
Strait of Malacca transit underwrites epoxy resin flows from Singapore petrochemical hubs to Guangdong appliance clusters. China, Germany, and the United States anchor global resin production, drawing from acrylic monomer, isocyanate, and fluoropolymer feedstock streams. Single-source vulnerability concentrates in specialty acrylic monomer supply chains tethered to Osaka and Stuttgart chemical corridors. Distribution runs through integrated coating-adhesive-sealant procurement bundles at major OEM accounts, displacing standalone coating specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as integrated coating-adhesive-sealant bundles consolidate vendor relationships at major appliance OEMs, mirroring interoperability shifts seen in automotive Tier 1 supply restructuring.
For Market Incumbents: Shield specification authority by deepening captive supply of specialty acrylic monomers and securing FDA food-contact certifications ahead of PFAS restriction expansion. Prioritize electrodeposition line partnerships in China to defend against regional blender consolidation. Cross-sell integrated bundles to compress pure-play coating specialists out of refrigerator and air conditioner assembly contracts.
For New Entrants and Emerging Players: FDA indirect food-contact certification fast-tracks open margin expansion in US refrigerator interior coatings where compliance barriers exclude non-certified suppliers. Target microwave cavity fluoropolymer alternatives as silicone and hybrid ceramic substitution gains regulatory tailwinds. Enter through contract manufacturing partnerships in Zhejiang and Guangdong provinces where localized waterborne system demand outpaces integrated producer capacity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across electrodeposition-served segments as pretreatment chemistry integration collapses returns for mid-scale regional blenders. Five-to-ten-year viability favors diversified chemical conglomerates with backward integration into resin production and captive adhesive infrastructure. Monitor ECHA sunset date enforcement for chromium trioxide as signal for trivalent chrome and chrome-free pretreatment acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Production | Secures supply chain control for premium refrigerator liner formulations under tightening energy-efficiency regulations. |
| Waterborne Polyurethane Line Capacity Expansion | Captures OEM procurement shifting from solvent-based systems under EPA and REACH emission protocols. |
| Integrated Coating-Adhesive-Sealant Bundle Launch | Mirrors Henkel's cross-selling pattern to displace standalone suppliers in major appliance assembly contracts. |
| Chrome-Free Pretreatment Certification Investment | Positions for ECHA sunset date enforcement on hexavalent chrome in European dishwasher interior segments. |
| PFAS-Alternative Formulation Partnership | Accelerates silicone and hybrid ceramic development ahead of prospective fluoropolymer restrictions across multiple jurisdictions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic industry reports to validate coating procurement patterns across appliance manufacturing bases. Plant managers at electrodeposition facilities, procurement leads at Whirlpool and Haier, distribution channel partners in Ningbo and Stuttgart, and technical R&D directors at resin producers contributed stakeholder perspectives. Bottom-up volume modeling triangulates against top-down value estimates derived from trade flow analysis.
Segmentation dimensions modeled span coating chemistry type, application technology, appliance category, and end-user procurement channel across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating regulatory phase-in timelines for emission standards and food-contact compliance. Forecast inputs include OEM production schedules for energy-efficient appliances and electrodeposition line installation permits in China and Germany.
Decision-makers should treat outputs as directional under assumptions of sustained REACH and EPA enforcement continuity; material deviation in regulatory timelines or PFAS restriction scope would warrant model refresh. Practitioners should keep alternative scenarios live as dual carbon goal implementation pace in China and ECHA authorization procedures for chromium trioxide evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Process Pipe Coating Market
Coatings
Europe Thermal Spray Market
Coatings
Extrusion Coating Market
Coatings
Waterborne Wood Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Marine Coatings Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Mold Release Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
Thermal Insulation Coating Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Global PET Film Coated Steel Coil Market