
 Polishing Chemicals Market | 2026-2036
Polishing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Polishing Chemicals Market Analytics
Modular slurry-delivery systems is rebalancing procurement patterns among semiconductor foundries and automotive coating shops. Cabot Microelectronics Corporation leverages its captive ceria supply chain to secure pricing leverage in oxide polishing applications. Fujimi Incorporated anchors its position through synthetic colloidal silica R&D intensity for sub-7nm nodes. DuPont de Nemours Inc competes via differentiated pad-and-slurry bundled offerings that reduce customer process-integration costs.
Polishing chemicals are formulated suspensions of abrasive particles—typically alumina, ceria, silica, or diamond in the 10-500 nanometer range—dispersed in aqueous or solvent carriers with pH buffers and surfactants, engineered to remove material at controlled rates while minimizing surface defects. Their primary purpose spans wafer planarization in semiconductor fabrication, precision optics finishing, and automotive clear-coat restoration. Liquid polishes dominate electronics applications where continuous-flow chemical mechanical planarization systems require consistent particle distribution and contamination control. Powder polishes retain cost advantages in furniture and metal restoration segments where users mix concentrates on-site. Cream and paste formats sustain margin pools in automotive detailing and aerospace MRO channels where viscosity and dwell time determine finish quality.
EPA regulations on per- and polyfluoroalkyl substances constrain fluorinated surfactant use in North American formulations, while REACH authorization requirements in Europe push suppliers toward biodegradable chelating agents. OSHA permissible exposure limits for respirable crystalline silica reshape workplace handling protocols for powder polish users. Semiconductor manufacturers must monitor how dual-use export controls on advanced polishing technologies affect supply security for sub-5nm production nodes.
Market Dynamics
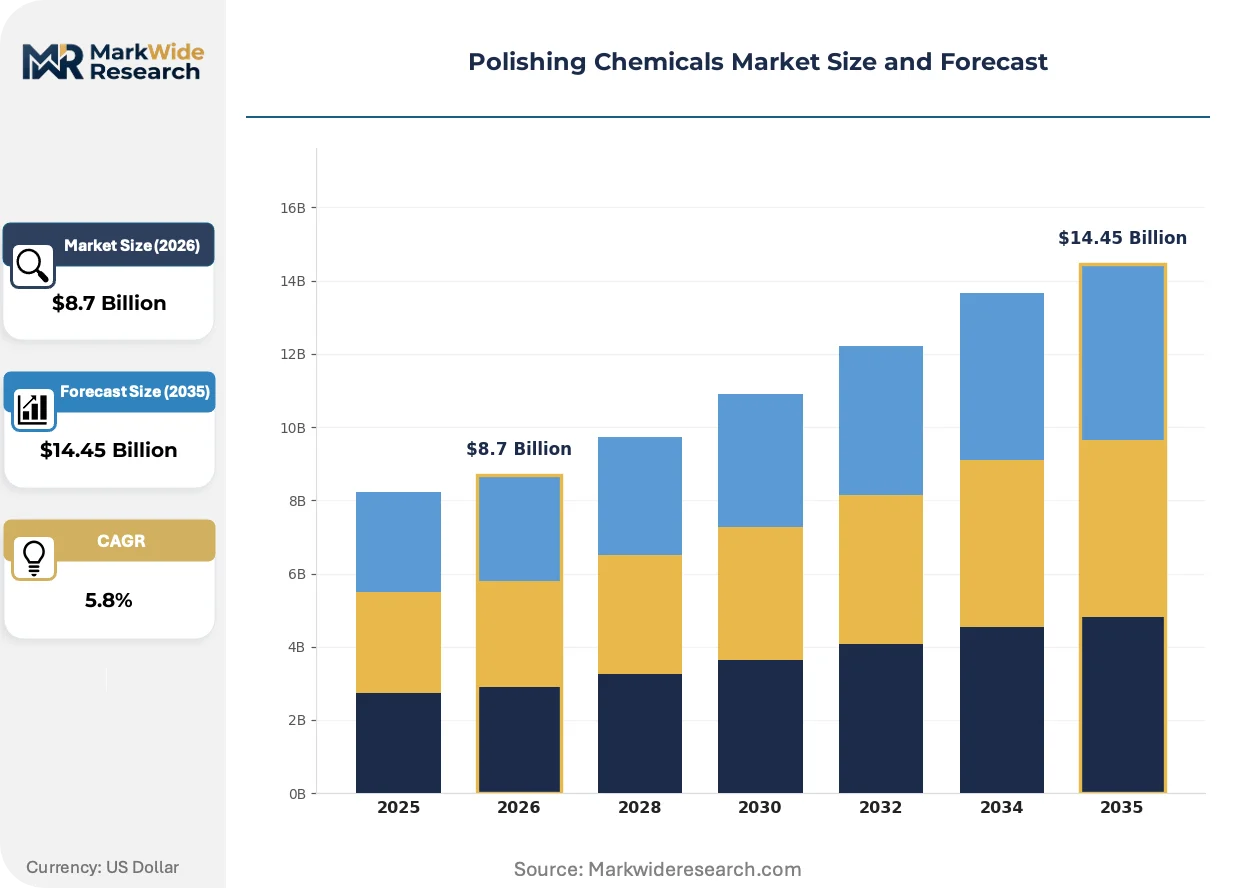
Semiconductor fabrication facilities in Taiwan and South Korea are expanding consumption of chemical mechanical planarization slurries as advanced node production requires ultra-high-purity polishing compounds, while REACH compliance in Europe and stricter volatile organic compound limits in California force reformulation of product chemistries across the supply base.
Growth Catalysts
- Sub-7nm node proliferation:Taiwan and South Korea semiconductor foundries consume specialized colloidal silica formulations for atomic-scale planarization. Advanced logic and memory fabs drive volume pull for contamination-controlled slurry systems.
- Automotive coating restoration:North American and European collision repair shops expand use of cream and paste polishes for clear-coat defect removal. Electric vehicle paint systems with specialized ceramic coatings require adapted abrasive chemistries.
- REACH authorization timelines:European ECHA deadlines for biodegradable chelating agents accelerate supplier R&D investment. Reformulation mandates create first-mover advantage for compliant product portfolios.
Market Restraints
- High-purity ceria supply concentration:Captive mining and refining operations in China dominate rare earth abrasive feedstock. Non-integrated polish compound manufacturers face input cost volatility and security-of-supply risk.
- Dual-use export control complexity:US Bureau of Industry and Security restrictions on sub-5nm polishing technology complicate equipment and formulation transfers. Semiconductor manufacturers in targeted jurisdictions face supply security uncertainty.
- Respirable crystalline silica exposure limits:OSHA permissible exposure standards reshape powder polish handling protocols. Metal restoration and furniture finishing shops incur ventilation and PPE compliance costs that erode format economics.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor assembly and test facilities create greenfield demand for CMP slurry infrastructure. Domestic formulators can anchor supply relationships before foundry ecosystems mature.
- Precision optics for augmented reality waveguides:Synthetic diamond and alumina nanoparticle suspensions enable sub-nanometer surface finishes on glass and silicon carbide substrates. AR headset manufacturers represent emerging volume buyers.
- California CARB VOC regulations:Stricter volatile organic compound limits for automotive refinish products accelerate water-based polish adoption. Compliant formulation specialists capture share from solvent-dependent incumbents.
Industry Challenges
- Contamination control technician scarcity:Semiconductor fabs require specialists capable of maintaining parts-per-billion purity in slurry distribution systems. Training pipelines lag fab construction timelines in emerging manufacturing clusters.
- Legacy powder polish customer transition:Metal restoration and furniture finishing shops accustomed to on-site mixing resist format shifts to pre-mixed liquids. Distribution channels face customer education and equipment retrofit friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polishing Chemicals Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Polishes, Powder Polishes, Cream Polishes, Paste Polishes Material: Metal, Plastic, Glass, Wood Application: Automotive, Electronics, Aerospace, Furniture End User: Manufacturers, Retailers, Service Providers, Individuals |
| Companies Covered | Cabot Microelectronics Corporation, Fujimi Incorporated, DuPont de Nemours Inc, BASF SE, Dow Chemical Company, Evonik Industries AG, Hitachi Chemical Company Ltd, Saint-Gobain S.A., Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polishing Chemicals Market Evolving Landscape
Modular slurry-delivery systems are rebalancing procurement patterns among semiconductor foundries and automotive coating shops, while regulatory pressure on fluorinated surfactants and biodegradable chelating agents forces molecular redesign of established formulations.
Recirculating slurry loops with real-time particle-size monitoring are modularizing chemical mechanical planarization process architecture. Taiwan and South Korea foundries adopt these systems to reduce per-wafer chemical consumption and extend pad life. Equipment-agnostic module designs enable fabs to switch slurry suppliers without retooling distribution infrastructure, compressing supplier switching costs.
EPA regulations on per- and polyfluoroalkyl substances constrain fluorinated surfactant use in North American polishing formulations. Compound manufacturers substitute bio-based dispersants and reformulate pH stability without perfluorinated chemistry. Automotive clear-coat and precision optics segments face the steepest adaptation curves due to surface-energy performance requirements.
Integrated pad-and-slurry procurement contracts disaggregate in semiconductor foundry supply chains. Buyers unbundle consumables to optimize total cost of ownership across multiple process steps. This pattern concentrates in East Asian electronics manufacturing clusters where foundry margin pressure drives granular spend analysis.
Polishing Chemicals Market Segmentation
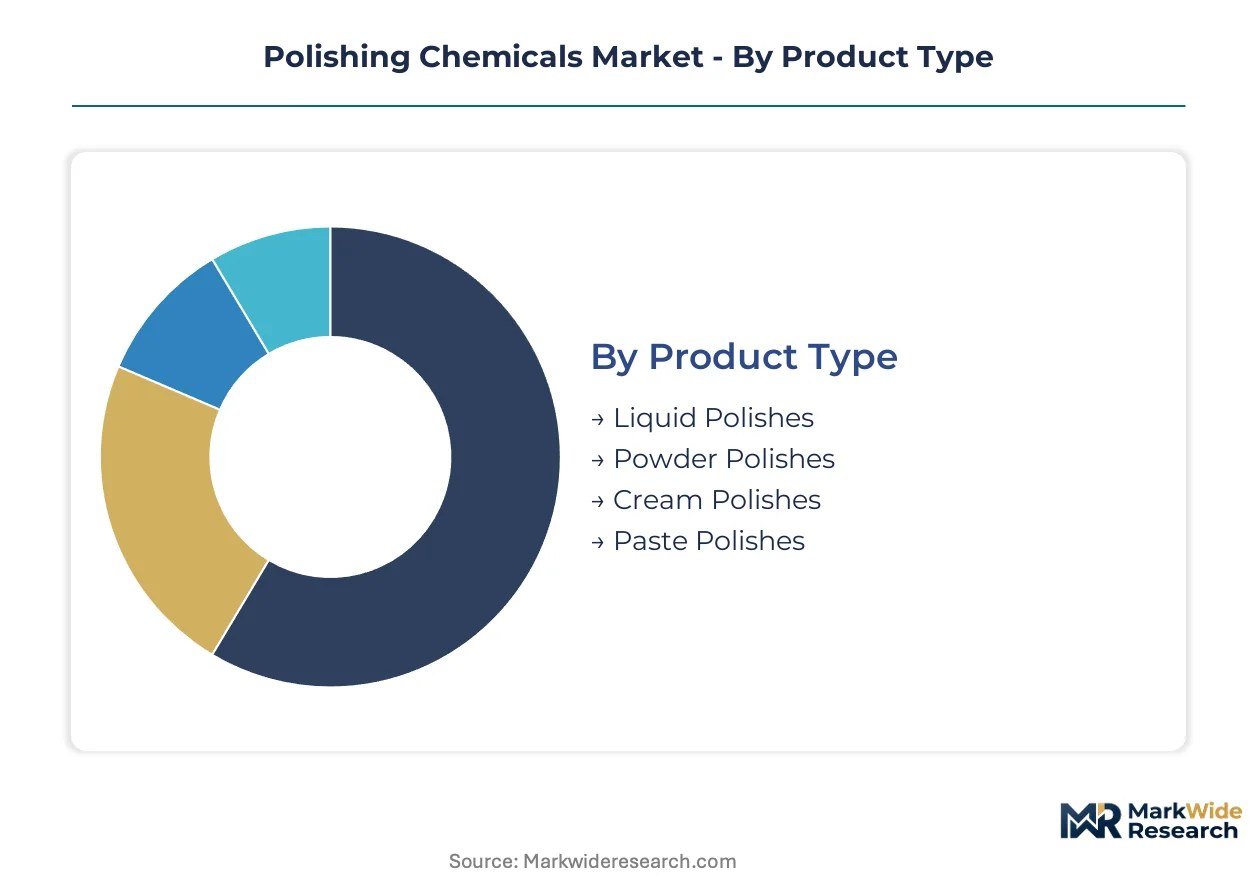
Segmentation in polishing chemicals reveals how formulation chemistry, substrate compatibility, and buyer sophistication split procurement patterns. Semiconductor fabs, collision repair chains, and furniture restorers each demand radically different performance specifications and contamination controls.
Product Type:
Buyers select format based on process automation level and surface finish precision requirements.
- Liquid Polishes:Aqueous suspensions of 10-500 nanometer abrasive particles—alumina, ceria, silica, or diamond—dispersed with pH buffers and surfactants for continuous-flow chemical mechanical planarization systems. Taiwan and South Korea semiconductor foundries drive volume pull for contamination-controlled slurry systems where parts-per-billion purity governs yield.
- Powder Polishes:Dry concentrates of abrasive grit mixed on-site with water or solvent carriers, retaining cost advantages in low-automation environments. OSHA permissible exposure limits for respirable crystalline silica reshape workplace handling protocols and erode format economics in metal restoration and furniture finishing shops.
- Cream Polishes:Viscous emulsions with controlled dwell time for automotive clear-coat defect removal. Electric vehicle paint systems with specialized ceramic coatings require adapted abrasive chemistries.
- Paste Polishes:High-viscosity compounds for aerospace MRO channels where finish quality determines component airworthiness certification.
Volume sits with liquid polishes; growth tilts toward cream polishes.
Material:
Substrate hardness and thermal sensitivity dictate abrasive selection and process parameters.
- Metal:Aluminum oxide and silicon carbide formulations dominate precision finishing of automotive body panels and aerospace structural components. Collision repair shops in Germany and the United States expand consumption of specialized compounds for electric vehicle aluminum-intensive architectures.
- Glass:Synthetic colloidal silica and ceria suspensions enable sub-nanometer surface finishes on precision optics and augmented reality waveguides. AR headset manufacturers represent emerging volume buyers for synthetic diamond and alumina nanoparticle suspensions.
- Plastic:Low-abrasion, heat-dissipating formulations for polycarbonate and acrylic substrates in automotive lighting and consumer electronics housings.
- Wood:Traditional wax-abrasive blends for furniture restoration where aesthetic finish supersedes dimensional precision.
Glass commands premium pricing; plastic applications expand most quickly.
Application:
End-use sector determines purity grade, regulatory compliance burden, and supplier qualification rigor.
- Electronics:Ultra-high-purity CMP slurries for semiconductor wafer planarization at sub-7nm nodes. Advanced logic and memory fabs in Taiwan and South Korea anchor demand for specialized colloidal silica formulations.
- Automotive:Clear-coat restoration compounds and electric vehicle paint system polishes. California CARB VOC regulations accelerate water-based polish adoption in refinish channels.
- Aerospace:MIL-SPEC compliant pastes for turbine blade and airframe component finishing. Surface finish quality links directly to fatigue life certification.
- Furniture:Cost-optimized powder and cream formats for residential and commercial restoration. Distribution channels face customer education friction as legacy users resist format shifts to pre-mixed liquids.
Electronics captures value concentration; automotive shows steepest expansion trajectory.
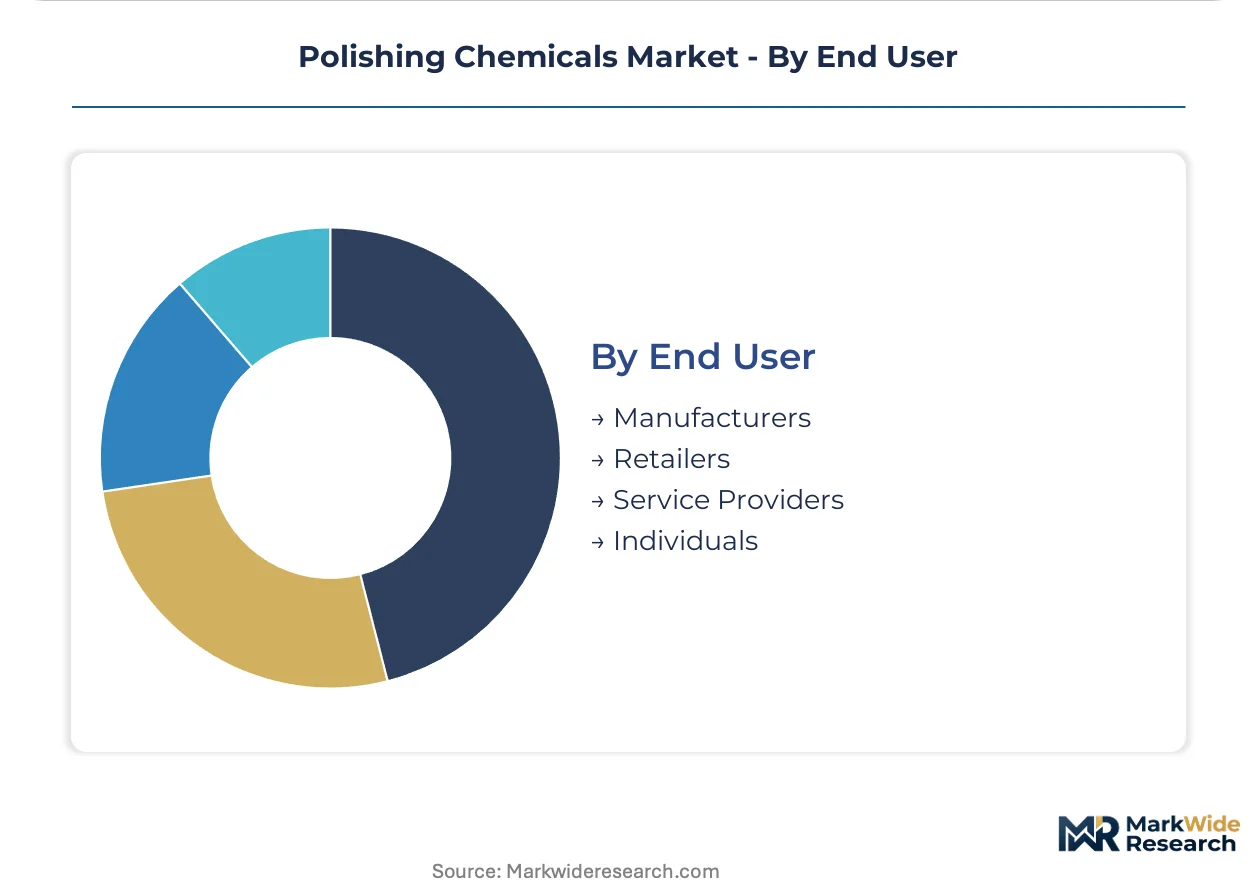
End User:
Procurement sophistication spans automated consumption tracking to informal spot purchasing.
- Manufacturers:Semiconductor fabs and automotive OEMs with integrated process engineering teams specifying slurry chemistry at the atomic scale. Recirculating slurry loops with real-time particle-size monitoring reduce per-wafer chemical consumption.
- Service Providers:Collision repair chains and aerospace MRO facilities with certified technicians and standardized process documentation. Training pipelines lag fab construction timelines in emerging manufacturing clusters.
- Retailers:Automotive parts distributors and woodworking supply houses managing inventory turnover of commodity polish SKUs.
- Individuals:Hobbyist and professional craftspeople mixing powder concentrates on-site with variable results.
Manufacturers dominate volume; service providers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian chemical clusters while consumption splits between semiconductor fabrication centers and automotive refinishing markets. Taiwan and South Korea fabs drive ultra-high-purity slurry demand. California collision repair chains and German OEM paint shops anchor Western consumption.
Taiwan
TSMC and United Microelectronics Corporation fabs in Hsinchu and Tainan Science Parks consume specialized colloidal silica formulations for sub-3nm node production. The island's EPA enforces wastewater discharge standards for semiconductor chemical processing that exceed baseline requirements. Kaohsiung's emerging 2nm fabrication complex anchors the fastest capacity expansion in the global polishing chemicals procurement base.
South Korea
Samsung Electronics and SK Hynix memory fabs in Pyeongtaek and Icheon drive ceria and alumina nanoparticle suspension volumes for 3D NAND stacking processes. MFDS regulates occupational exposure limits for semiconductor process chemicals under the Industrial Safety and Health Act. Seoul Capital Area foundry clusters represent the densest concentration of chemical mechanical planarization consumption outside Taiwan.
United States
Intel's Arizona and Ohio fabs plus GlobalFoundries' New York operations import high-purity slurries for advanced logic production. EPA regulations on per- and polyfluoroalkyl substances constrain fluorinated surfactant formulations in North American polishing compounds. California's CARB VOC limits for automotive refinish products accelerate water-based polish adoption in Los Angeles and Bay Area collision repair chains.
Germany
BMW and Mercedes-Benz electric vehicle paint shops in Bavaria and Baden-Württemberg consume cream and paste polishes for aluminum-intensive body panel finishing. REACH authorization requirements through ECHA push suppliers toward biodegradable chelating agents by specified deadlines. Stuttgart's automotive engineering corridor represents Europe's most sophisticated demand for ceramic-coating-compatible abrasive chemistries.
China
Domestic semiconductor foundries in Shanghai and Beijing source polishing chemicals for mature-node production while importing sub-7nm formulations. MIIT standards govern rare earth abrasive processing under national strategic resource regulations. Yangtze River Delta chemical parks house captive ceria refining operations that supply both domestic polish compound manufacturers and export markets.
Polishing Chemicals Market Competitive Landscape
The competitive structure tilts toward integrated material suppliers with captive abrasive feedstock control. Three to five multinational chemical conglomerates dominate volume in semiconductor-grade formulations while regional specialists capture automotive and industrial restoration segments. Strategic archetypes split between rare earth-integrated compounders, synthetic colloidal silica specialists, and diversified pad-and-slurry bundlers. Capacity expansion in East Asian chemical parks and strategic partnerships with foundry equipment vendors constitute the dominant competitive moves.
Within the integrated feedstock tier, Cabot Microelectronics Corporation and Fujimi Incorporated exemplify archetypes built on upstream abrasive control and synthetic particle R&D intensity respectively. DuPont de Nemours Inc occupies a differentiated position through consumables bundling that reduces customer process integration costs. BASF SE and Evonik Industries AG represent diversified chemical conglomerates leveraging formulation science across multiple industrial polish applications. Hitachi Chemical Company Ltd anchors Japanese supply relationships with domestic electronics manufacturers. Saint-Gobain S.A. and Dow Chemical Company exemplify materials science multinationals with cross-segment abrasive technology portfolios. Ecolab Inc sits within the industrial hygiene and process chemicals service model.
| Leading Market Players |
|---|
| Cabot Microelectronics Corporation |
| Fujimi Incorporated |
| DuPont de Nemours Inc |
| BASF SE |
| Dow Chemical Company |
| Evonik Industries AG |
| Hitachi Chemical Company Ltd |
| Saint-Gobain S.A. |
| Ecolab Inc. |
| Others |
Value Network & Pricing Analysis
Rare earth abrasive feedstock costs cascade through three pricing strata, with Chinese ceria refining concentration forcing semiconductor-grade slurry premiums while powder polish margins compress under OSHA silica compliance burdens.
Pricing Analysis
Margin tightening in economy-tier powder polishes reflects respirable crystalline silica exposure compliance costs that erode on-site mixing economics. Three-tier pricing structure across semiconductor-grade, automotive-refinish, and industrial-restoration levels separates contamination-controlled slurries from commodity compounds. Price differentiation hinges on purity certification grade and captive upstream integration. Foundry procurement teams exhibit lowest price sensitivity due to yield-risk calculus, while furniture restoration shops face acute cost pressure.
Supply Chain Analysis
Reverse-logistics flows for spent CMP slurries remain underdeveloped, creating hazardous waste disposal bottlenecks that constrain fab expansion timelines. Supply concentrates in China for rare earth refining, Taiwan and South Korea for formulation, and Germany for automotive specialty compounds. Raw material dependencies center on Mongolian ceria ore, synthetic colloidal silica precursors, and bio-based surfactant feedstocks. Single-source vulnerability pervades sub-7nm nanoparticle supply. Distribution runs through equipment vendor bundling contracts and direct foundry technical service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
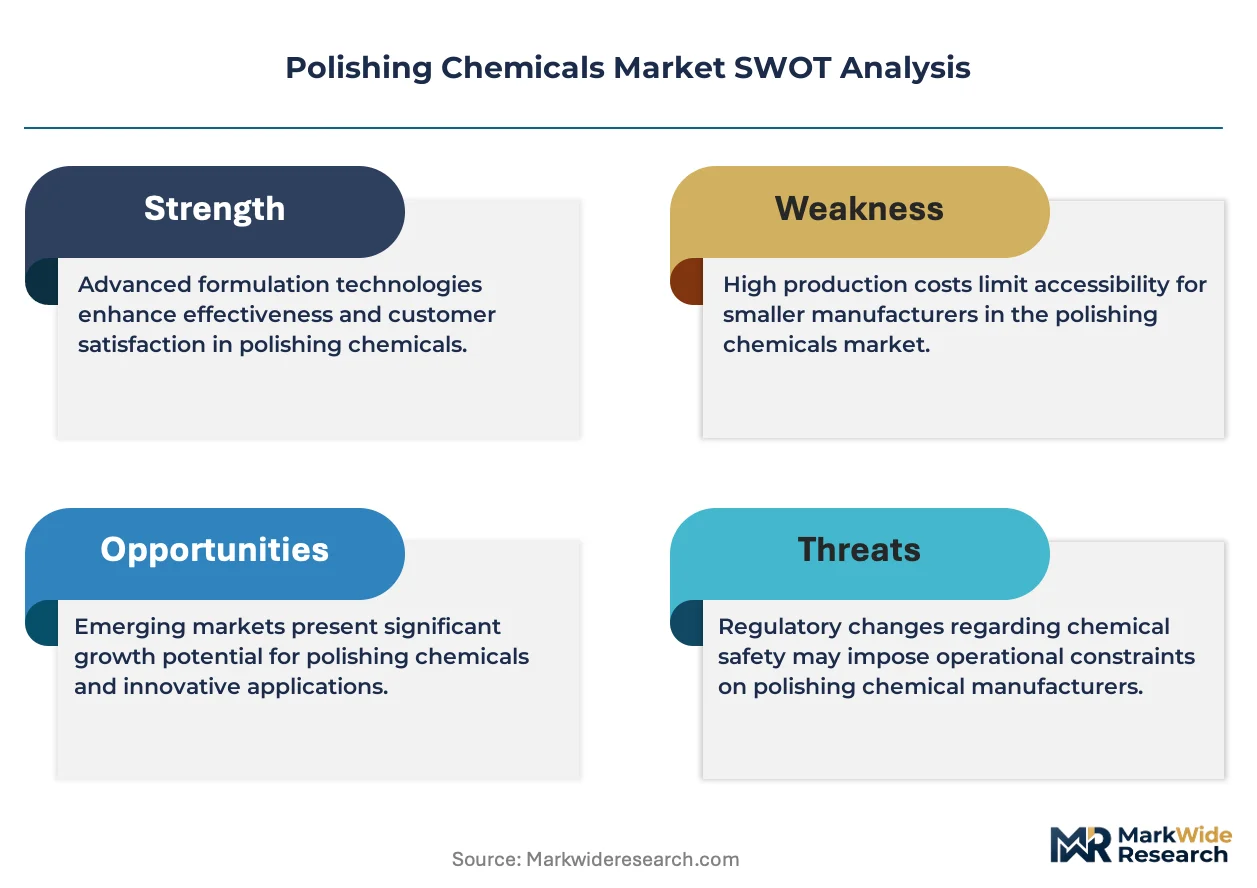
This market functions as a cost-of-compliance arena where REACH authorization deadlines and EPA PFAS restrictions erect formulation barriers that reward pre-positioned compliant portfolios.
For Market Incumbents: Lock in captive ceria supply through offtake agreements with Yangtze River Delta refiners before export control tightening. Deepen synthetic colloidal silica R&D partnerships with Taiwan foundry equipment vendors to embed switching costs. Defend against modular slurry-delivery system disintermediation by unbundling pad-and-slurry contracts.
For New Entrants and Emerging Players: Enter via India's PLI-subsidized semiconductor assembly and test facilities before domestic slurry infrastructure matures. Target water-based automotive refinish formulations for California CARB compliance capture. Pursue precision optics for augmented reality waveguides as the most penetrable premium segment.
For Investors and Strategic Acquirers: ECHA REACH authorization timeline acceleration is the leading indicator that biodegradable chelating agent R&D intensity will separate viable acquisition targets from stranded formulation assets. Five-to-ten year viability favors rare earth-integrated compounders with foundry qualification track records. Monitor dual-use export control list expansions for supply security inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceria Refining | Captive rare earth supply secures pricing leverage against Chinese export quota volatility. |
| Synthetic Colloidal silica R&D Scale-Up | Sub-5nm particle uniformity qualifies suppliers for TSMC and Samsung advanced node procurement. |
| Biodegradable Chelating Agent Reformulation | ECHA REACH compliance creates first-mover advantage in European semiconductor foundry channels. |
| Modular Slurry-Delivery System Deployment | Equipment-agnostic designs compress customer switching costs and expand addressable fab base. |
| Water-Based Automotive Refinish Launch | California CARB VOC alignment captures collision repair chain consolidation procurement. |
Research Methodology
Multi-period observation of slurry consumption patterns at Taiwan and South Korea foundry clusters anchored the trend analysis, supplemented by interviews with semiconductor process engineers, CMP equipment specialists, automotive refinish procurement managers, and rare earth trading desk analysts. Secondary validation drew from SEC 10-K filings of listed chemical companies, Korean customs export data, ECHA authorization timelines, and SEMI materials market databases. Bottom-up wafer throughput modeling and top-down chemical spend analysis were triangulated against foundry capex disclosures.
Segment-weighting across product format, abrasive material, substrate application, and end-user procurement sophistication shaped the analytical framework. CAGRs were derived from supply-side capacity buildouts and demand-side node migration patterns. Forecast inputs incorporated fab construction timelines, REACH authorization phase-in schedules, and electric vehicle paint system specification evolution.
Revisions become necessary when dual-use export control expansions, rare earth supply disruptions, or sub-3nm yield breakthroughs materialize outside baseline assumptions. Practitioners should monitor Bureau of Industry and Security rulemaking, Chinese environmental inspections affecting ceria output, and foundry equipment vendor slurry partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
North America Abrasives Market
Abrasives
Calcined Shale Market
Abrasives
Chemical Deflasher Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Abrasive Tools Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Abrasive Grains Market
Abrasives
Carbide Grinding Wheel Market
Abrasives
New Zealand Abrasives Market
Abrasives
Global Abrasives Market
Abrasives
Sandblaster Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Europe Abrasives Market
Abrasives
Artificial Abrasives Market
Abrasives
Carbide Tools Market