
 Can Coatings Market | 2026-2036
Can Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Can Coatings Market Intelligence
Specialty chemical producers' can coating capacity is decoupling from traditional petrochemical feedstock volatility through bio-based resin development. The Sherwin-Williams Company leverages its extensive distribution network to serve both large beverage manufacturers and smaller craft producers. PPG Industries, Inc. specializes in high-performance coatings for demanding applications like aerosol containers. Akzo Nobel N.V. competes on sustainable formulations, aligning with consumer and regulatory pressures for safer materials.
Can coatings are thin organic polymer films applied to the interior surface of metal containers, designed to prevent interaction between the can and its contents. These formulations, often based on epoxy or polyester resins, provide a barrier against corrosion to preserve flavor and ensure safety. Epoxy coatings maintain a significant share, but polyester and acrylic types are expanding due to regulatory pressures. The beverage packaging application commands the largest volume, particularly for aluminum cans.
Food contact material regulations from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) heavily influence formulation choices. In China, GB standards for food packaging materials set stringent requirements for chemical migration and material composition. Formulators must now balance the technical demands of high-speed application lines with the accelerating development of non-BPA and next-generation barrier technologies.
Market Dynamics
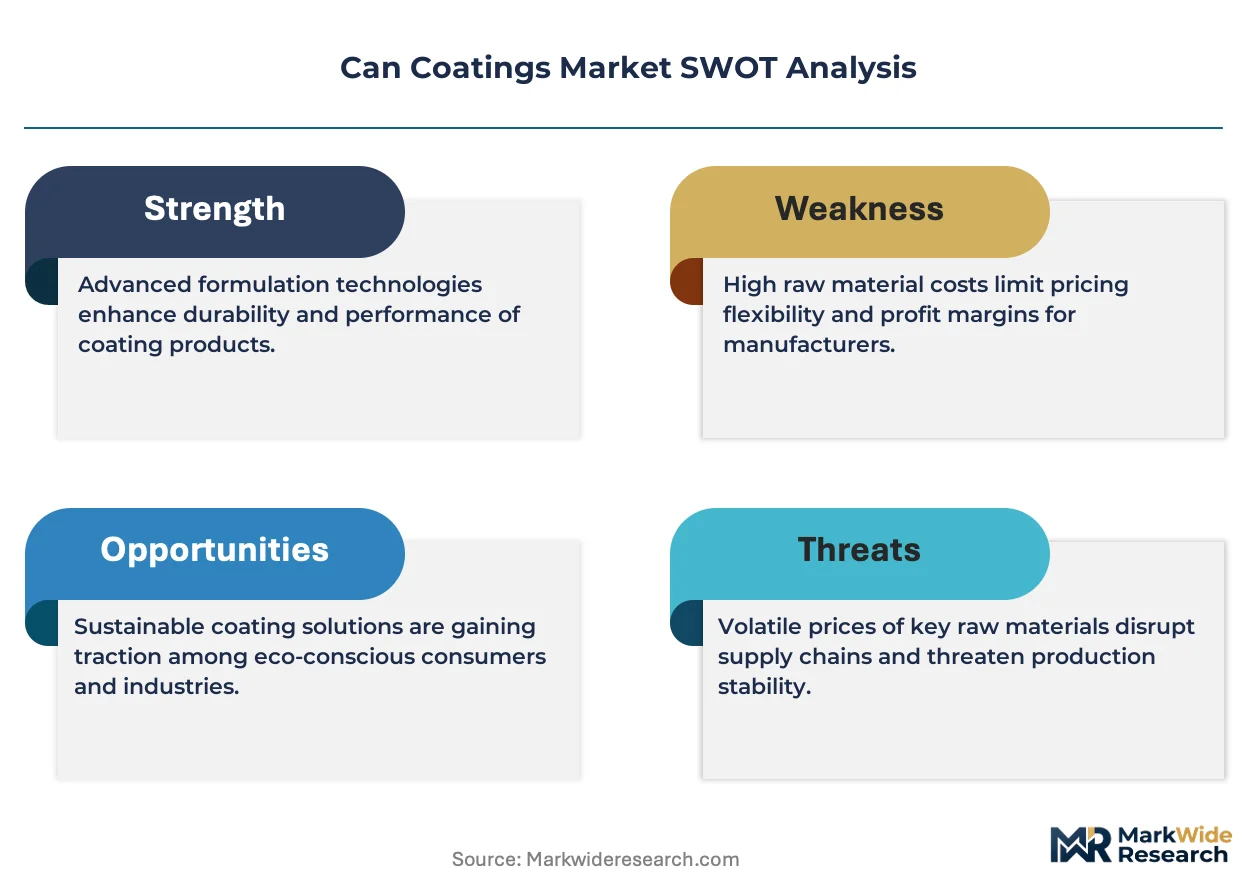
The transition away from bisphenol A (BPA) acts as the central structural force in the can coatings market. This shift, driven by regulatory actions from the US FDA and Europe's EFSA, compels material reformulation across the entire industry.
Growth Catalysts
- Beverage Sector Expansion:Growth in ready-to-drink teas, coffees, and functional beverages escalates the need for high-performance interior coatings that preserve complex flavor profiles.
- Southeast Asian Industrialization:Rapid expansion of food and beverage processing industries in Vietnam and Thailand creates concentrated geographic demand for advanced can coating formulations.
- Bio-Based Resin Development:Innovation in bio-based polymers offers a pathway to decouple from volatile petrochemical feedstocks while meeting sustainability goals for brand owners.
Market Restraints
- Petrochemical Feedstock Volatility:The cost of key precursors for epoxy and polyester resins remains tied to volatile oil and gas markets, creating pricing instability for coating manufacturers.
- Stringent Regulatory Hurdles:Adhering to evolving food contact regulations from bodies like the FDA and EFSA requires costly, long-term testing for new materials, slowing innovation.
- High-Speed Application Demands:New coating formulations must match the rheological and curing properties of legacy systems to avoid disrupting high-speed can manufacturing lines.
Strategic Opportunities
- Aerosol and Monobloc Cans:Developing specialized coatings for complex shapes and demanding chemical resistance requirements in aerosol containers for personal care and pharmaceuticals presents a value-added opportunity.
- Next-Generation Barrier Technologies:Integrating active scavenger technologies or advanced polymers into coating systems can create superior barriers, enabling longer shelf life for sensitive products.
- Sustainable Formulations:Formulating coatings with higher bio-based content or those designed for improved recyclability aligns with corporate sustainability mandates from major brand owners.
Industry Challenges
- Compliance Certification Delays:The extensive validation process required to achieve food contact approval under standards like China's GB framework creates significant operational bottlenecks for market entry.
- Supply Chain Reconfiguration:Shifting production from established BPA-based material streams to new non-BPA alternatives requires significant capital investment and qualification of new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Can Coatings Market |
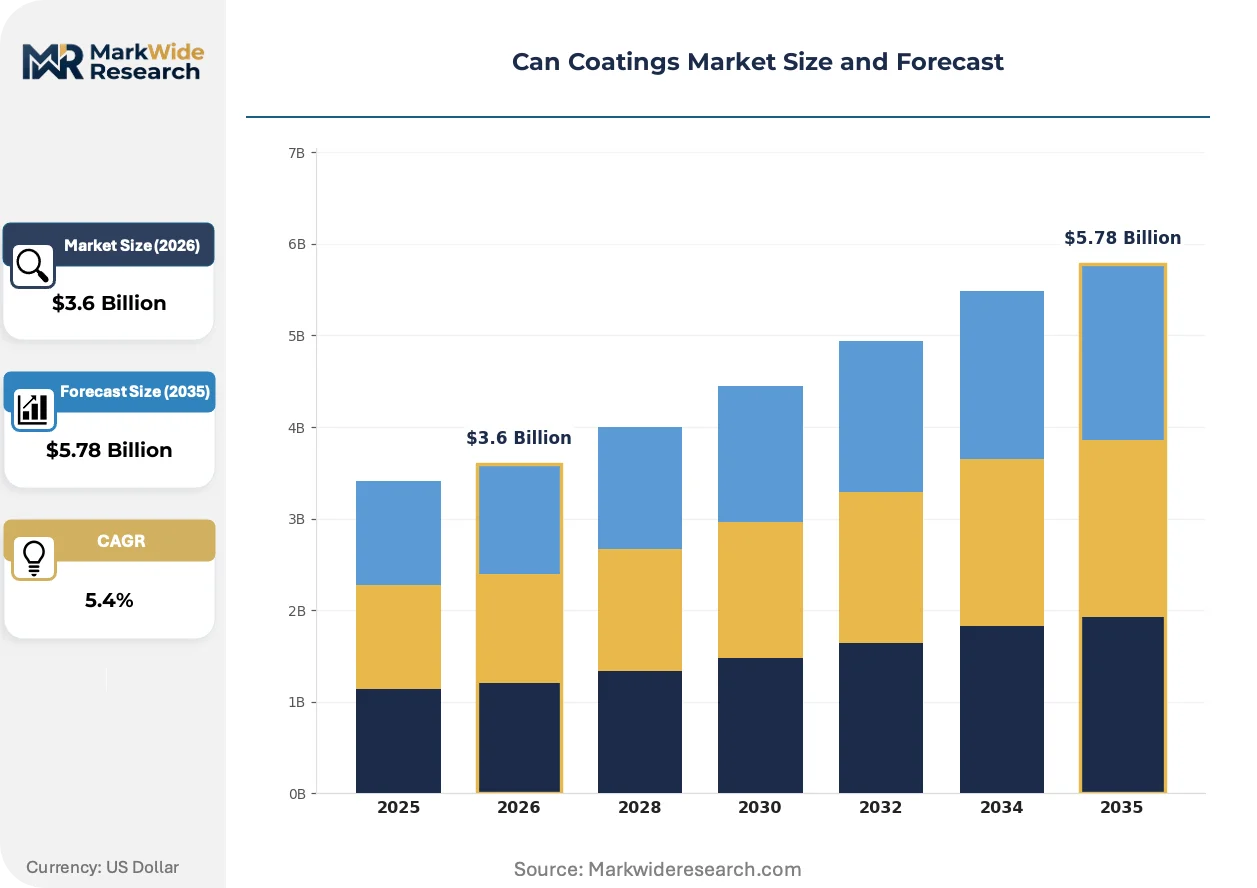
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Epoxy, Polyester, Acrylic, Polyvinyl, UV Cure, Phenolic Application: Beverage Packaging, Food Packaging, Aerosol Containers, Industrial Cans, Paint Cans Can Material: Tinplate Steel, Aluminum, Tin-Free Steel, Composite, Plastic Cans End User Industry: Beverage Manufacturers, Food Processing, Chemical Producers, Paint Manufacturers |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., Kansai Paint Co., Ltd., ALTANA AG, Toyo Ink Group, Ball Corporation, Axalta Coating Systems, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Can Coatings Market Strategic Shifts & Innovations
Material science innovation is accelerating, driven by the dual imperatives of regulatory compliance and enhanced product protection. The industry is moving beyond simple substitution toward next-generation barrier solutions that redefine performance and safety.
Polyester coatings offer a primary non-BPA alternative to traditional epoxy systems for can interiors. Beverage can manufacturers are adopting these formulations to meet evolving food contact safety standards. Consequently, polyester technology is consolidating its position as the successor to epoxy resins for many mainstream beverage applications, especially in aluminum cans.
European Food Safety Authority (EFSA) opinions on bisphenols in food contact materials are forcing stricter controls and lower migration limits. This regulatory pressure compels formulators to invest heavily in non-BPA material science and exhaustive migration testing protocols. The beverage sector is most affected, proactively adopting compliant coatings to secure continuous access to the European market.
A clear shift in procurement criteria prioritizes coatings with documented sustainable attributes, such as bio-based content or enhanced recyclability. This change elevates sourcing decisions beyond traditional metrics of cost and technical performance for brand owners and can makers. The trend is most pronounced in North American and European markets where brands use supply chain sustainability as a differentiator.
Can Coatings Market Segmentation
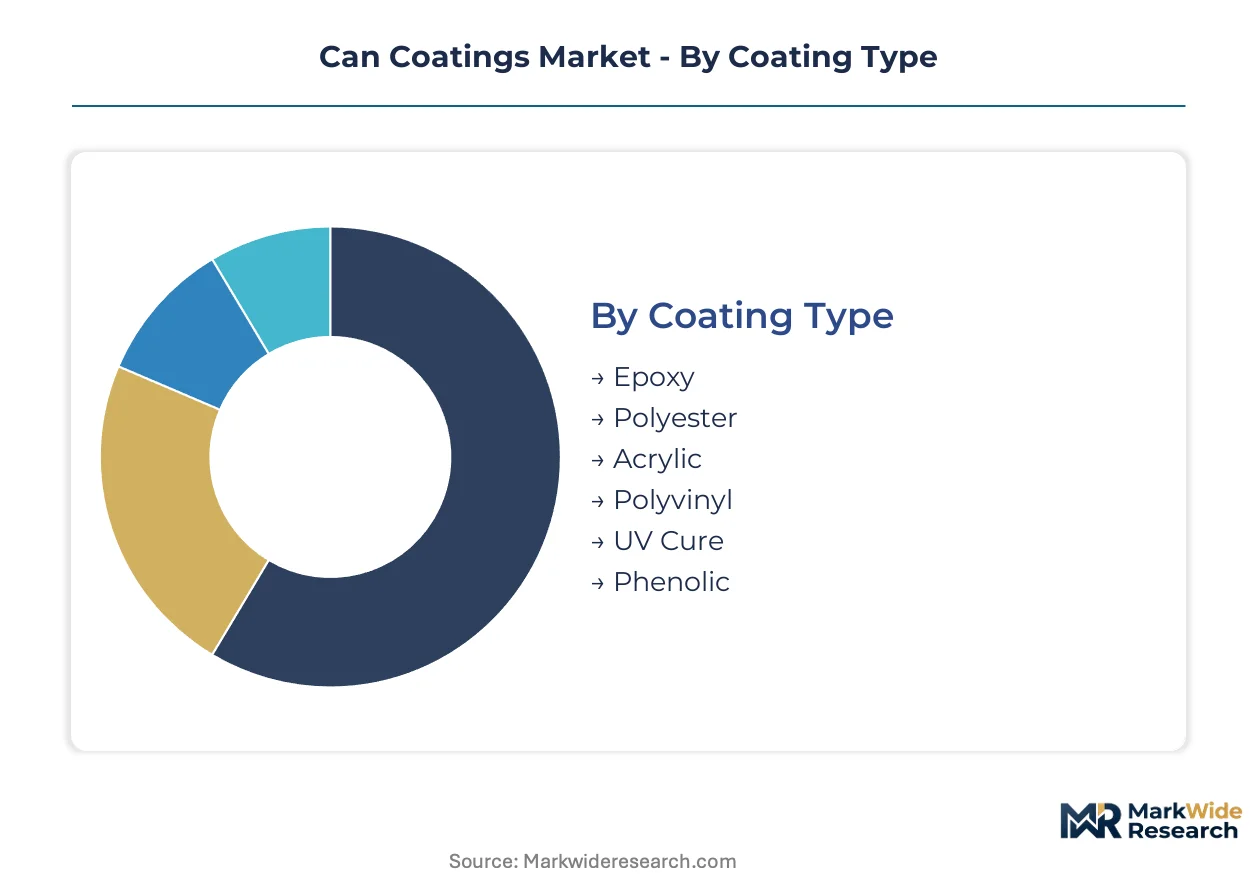
The can coatings market exhibits varied demands across its value chain, driven by diverse packaging formats and end-user specifications. Segmentation clarifies how different coating types address specific material needs and evolving regulatory mandates. This analysis provides a granular view of market dynamics influenced by material, application, and end-user distinctions.
Coating Type:
Can coating formulations are either foundational systems integrated across diverse packaging types or specialized materials designed for niche performance requirements.
- Epoxy:Bisphenol A-based or non-BPA epoxy systems form a robust barrier against corrosion and chemical interaction with container contents. Epoxy coatings maintain a significant share in food and beverage packaging due to their proven performance and adhesion properties.
- Polyester:Polyester resins provide a non-BPA alternative, offering flexibility and resistance to various food and beverage contents. Beverage can manufacturers in Europe are rapidly adopting polyester formulations to comply with EFSA regulations and satisfy consumer demand for safer materials.
- Acrylic:Acrylic coatings offer good clarity and flexibility, finding use in specific food and personal care applications.
- Polyvinyl:Polyvinyl chloride (PVC) based coatings provide excellent chemical resistance for industrial containers.
- UV Cure:UV curable coatings enable rapid processing speeds for specialized can and closure applications.
- Phenolic:Phenolic resins offer high heat and chemical resistance, commonly used in industrial can linings.
Epoxy coatings lead volumes today; polyester formulations are gaining share fastest.
Application:
The volume demands for can coatings vary significantly, from high-speed beverage lines to specialized industrial container requirements.
- Beverage Packaging:Interior coatings for beverage cans prevent metal interaction, preserving flavor and product integrity for drinks like sodas and ready-to-drink teas. This application commands the largest volume, driven by the expansion of ready-to-drink products in Southeast Asian markets.
- Food Packaging:Coatings for food cans provide a barrier against corrosion, extending shelf life for processed foods.
- Aerosol Containers:Specialized coatings for aerosol cans protect against aggressive propellants and product formulations, ensuring container integrity and user safety. Demand for high-performance coatings in this segment is driven by personal care and pharmaceutical products requiring chemical resistance.
- Industrial Cans:These coatings protect metal containers from harsh chemicals and solvents in industrial applications.
- Paint Cans:Coatings for paint cans ensure product stability and prevent rust formation on container interiors.
Volume concentrates in beverage packaging; aerosol containers exhibit the steepest expansion trajectory.
Can Material:
Can coating performance is intrinsically linked to the underlying metal substrate, requiring formulations tailored to specific material properties.
- Tinplate Steel:Coatings on tinplate steel provide corrosion resistance for food cans, protecting contents from metal interaction. This material remains a staple for processed food packaging, requiring robust interior and exterior protective layers.
- Aluminum:Coatings for aluminum cans must adhere well to the lightweight substrate and withstand high-speed manufacturing processes. Aluminum cans dominate the beverage sector, driving demand for coatings that preserve flavor and enable efficient recycling.
- Tin-Free Steel:Coatings for tin-free steel offer an economical option for food and general line cans.
- Composite:Coatings for composite cans protect multi-layer structures, often used for snacks and powdered products.
- Plastic Cans:Coatings on plastic cans enhance barrier properties and improve product presentation for various goods.
Market share is primarily held by aluminum and tinplate steel; composite cans are seeing renewed interest for specialized products.
End User Industry:
End-user industries dictate specific performance requirements and regulatory compliance standards for can coatings, reflecting diverse product formulations.
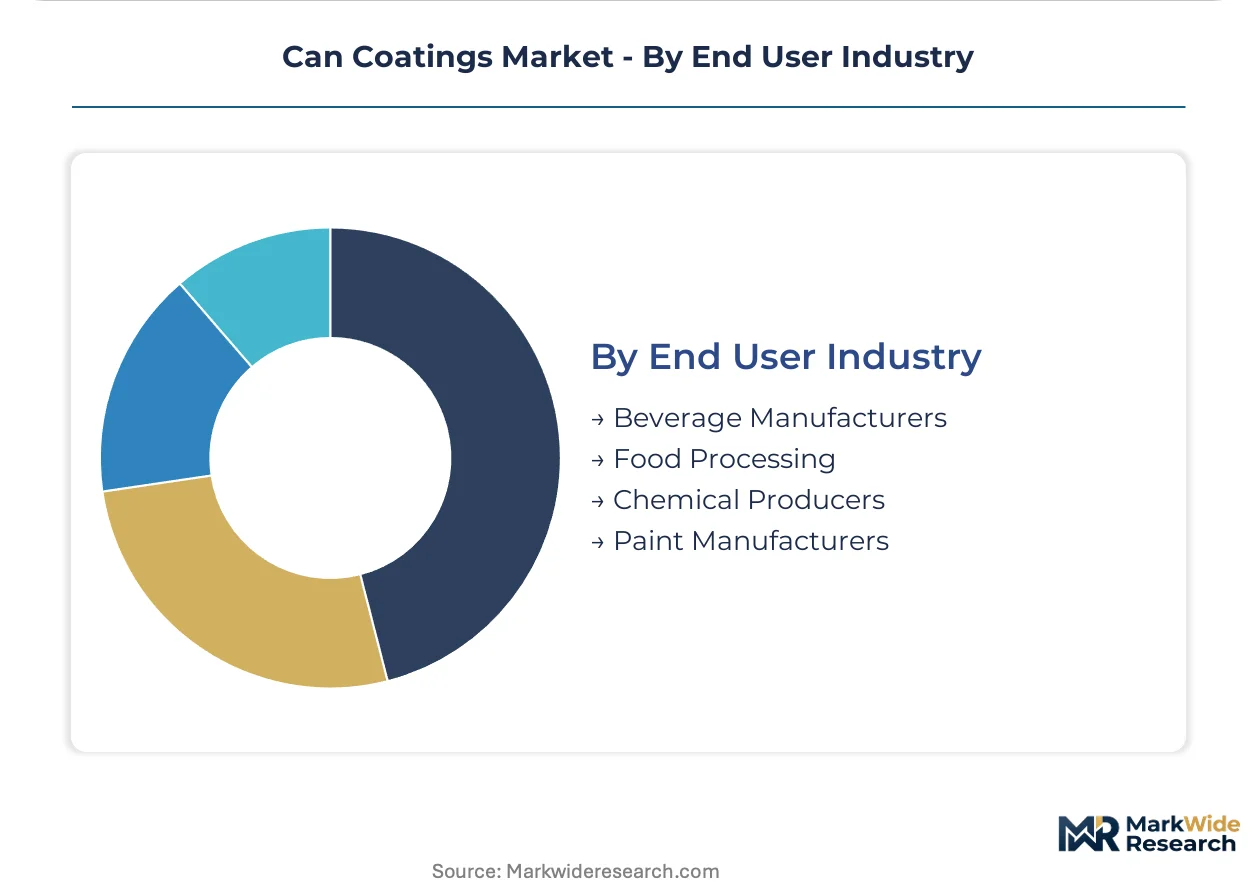
- Beverage Manufacturers:These companies require coatings that prevent flavor scalping and maintain product integrity for carbonated soft drinks, beers, and energy drinks. Beverage manufacturers drive innovation in non-BPA and high-performance coatings due to strict food contact regulations and high-speed filling lines.
- Food Processing:Food processors utilize coatings to protect a wide array of products, from vegetables and fruits to prepared meals, ensuring long shelf life. Stringent food contact material regulations from bodies like the US FDA and EFSA compel continuous material reformulation for this sector.
- Chemical Producers:Chemical producers need coatings resistant to aggressive chemicals for safe storage and transport.
- Paint Manufacturers:Paint manufacturers use coatings to protect their products from rust and ensure container integrity.
The largest segment is beverage manufacturers; chemical producers require highly specialized coating solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States market navigates a complex regulatory landscape for can coatings, Southeast Asian nations like Vietnam and Thailand are experiencing rapid industrial growth. This regional disparity in market drivers shapes both material innovation and investment strategies for coating manufacturers globally.
United States
Demand for non-BPA internal coatings for beverage cans drives significant formulation development in the United States. The US Food and Drug Administration (FDA) guidelines on food contact materials compel manufacturers to reformulate existing products. Major beverage producers in the Midwest and Southeast regions proactively adopt these compliant coating systems.
Germany
Germany's can coatings market prioritizes sustainable formulations and high-performance barriers for diverse applications. European Food Safety Authority (EFSA) opinions on bisphenols influence material choices across the food and beverage sector. Chemical producers in the Rhine-Main region develop advanced polyester and acrylic systems to meet these stringent requirements.
China
China's robust food and beverage processing industry creates substantial demand for interior can coatings. GB standards for food packaging materials set strict requirements for chemical migration and material composition. Manufacturing hubs in the Yangtze River Delta region focus on high-speed application lines for both aluminum and tinplate cans.
Vietnam
Vietnam's expanding ready-to-drink beverage sector fuels the need for specialized can coating formulations. Government initiatives supporting the food and beverage industry encourage investment in modern packaging solutions. Industrial zones around Ho Chi Minh City attract can manufacturers and coating suppliers to serve this growing demand.
Brazil
Brazil's large domestic beverage market, particularly for soft drinks and beer, requires high-performance interior can coatings. The country's national food safety regulations, similar to ANVISA guidelines, influence material selection for food contact applications. Packaging clusters in the São Paulo state drive innovation for efficient coating processes.
Can Coatings Market Key Industry Players
North American producers anchor one tier of the can coatings market, while European specialists hold strong positions in sustainable formulations. The industry structure shows a tiered landscape with global chemical conglomerates, regional coating manufacturers, and specialized material science firms. Competitive dynamics involve strategic partnerships for technology development and targeted capacity expansions to meet regional demand surges.
Global diversified chemical companies, such as The Sherwin-Williams Company, leverage extensive distribution networks to serve a broad customer base. PPG Industries, Inc. occupies a position as a specialist in high-performance coatings for demanding applications like aerosol containers. Akzo Nobel N.V. exemplifies a focus on sustainable formulations, aligning with evolving regulatory and consumer preferences for safer materials.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Kansai Paint Co., Ltd. |
| ALTANA AG |
| Toyo Ink Group |
| Ball Corporation |
| Axalta Coating Systems |
| RPM International Inc. |
| Others |
Cost & Logistics Intelligence
Large beverage manufacturers, particularly those with global operations, drive contract-based pricing for can coatings. Their volume commitments stabilize pricing for critical non-BPA formulations.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for commodity can coatings. The dominant pricing model remains contract-based long-term offtake for major players, with spot market dynamics influencing smaller producers. Price differentiation stems from non-BPA certification levels, high-speed application compatibility, and specific product customization. Pricing pressure stems from petrochemical feedstock volatility and continuous regulatory compliance investments. Large beverage manufacturers prioritize performance, while smaller craft producers exhibit higher price sensitivity.
Supply Chain Analysis
Compliance certification for food contact materials acts as a significant gatekeeper in the can coatings supply chain. Raw material sourcing relies heavily on petrochemical feedstocks from global suppliers, with key resin production concentrated in China and Germany. The supply chain faces structural risk from petrochemical feedstock volatility, impacting overall cost stability for coating manufacturers. Distribution runs through direct sales channels to major can makers, supplemented by specialized chemical distributors serving regional and craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The can coatings market functions as a regulatory compounder, where evolving food contact material guidelines continuously reshape product demand. European Food Safety Authority (EFSA) opinions on bisphenols specifically drive significant reformulation efforts.
For Market Incumbents: Hedge against petrochemical feedstock volatility by accelerating bio-based resin development and securing long-term supply agreements for key monomers. Leverage existing global distribution networks to rapidly deploy new non-BPA compliant formulations across diverse markets. Invest heavily in certification processes for next-generation barrier technologies to maintain regulatory leadership and counter emerging material innovation threats.
For New Entrants and Emerging Players: Advanced polymer science creates a technology-first wedge for new entrants focusing on next-generation barrier solutions. Target the aerosol container segment and specialized food applications requiring unique chemical resistance properties. Penetrate the market by offering sustainable formulations with higher bio-based content, appealing to brand owners in North America and Europe. Focus on rapid customization and rigorous compliance testing as a go-to-market differentiator.
For Investors and Strategic Acquirers: Global chemical conglomerates are the most active acquirers in this space, seeking to consolidate non-BPA technology and expand geographic reach. The long-term viability of the market remains strong, propelled by expanding beverage consumption and stringent food contact regulations. Target specialized material science firms with validated next-generation barrier technologies or regional manufacturers with strong footholds in Southeast Asia. The speed of regulatory approval for novel non-BPA systems is the key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increase production of non-BPA polyester resins in Vietnam to serve growing beverage demand. |
| Green Manufacturing Transition | Invest in bio-based feedstock processing to reduce reliance on volatile petrochemicals. |
| Long-term Supply Agreement | Secure critical monomer supplies to stabilize production costs for can coating formulations. |
| Joint Venture | Partner with a regional can manufacturer in Thailand to co-develop specialized coating solutions. |
| Backward Integration | Develop in-house resin synthesis capabilities to gain greater control over material quality. |
Research Approach
Bottom-up beverage packaging end-use modeling reconciled against top-down specialty chemical supply-side tracking forms the analytical core of this study. The approach integrated primary interviews with R&D directors, procurement leads at can manufacturers, and regulatory compliance officers. Secondary validation utilized US FDA guidelines, EFSA opinions, China GB standards, and industry association reports. This triangulation ensured robust data interpretation.
An input-output matrix framework projected market dynamics across the analysis window. Segmentation dimensions modeled included coating type, application, can material, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from historical trend analysis and future projections based on market dynamics. Non-BPA conversion rates and ready-to-drink beverage consumption growth served as key forecast inputs.
The model holds under current regulatory environments and stable petrochemical feedstock prices; deviation in food safety regulations or raw material costs would shift projections. Forecasts reflect assumptions regarding non-BPA adoption rates and regional industrialization trends. A model refresh is warranted upon material change in global food contact material legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Dispersion Coating Market
Coatings
Stealth Coating Material Market
Coatings
Carbon Fiber Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Clear Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Wire Enamels Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
High Performance Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Packaging Coatings Market