
 Pyrophyllite Powder Market | 2026-2036
Pyrophyllite Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrophyllite Powder Market Analytics
A shift from single-source to multi-source procurement is rebalancing supply security for downstream ceramic and refractory manufacturers. Vanderbilt Minerals, LLC leverages its North American deposit base to sustain consistent feedstock quality for high-temperature applications. Ashapura Minechem Limited anchors its position through integrated mining and processing infrastructure across western India. Trinity Resources Ltd. competes on specialty grades for the North American paints and coatings sector.
Pyrophyllite powder is a hydrated aluminum silicate mineral with a Mohs hardness of 1-2 and a chemical composition of Al₂Si₄O₁₀(OH)₂, processed through crushing, milling, and classification to achieve particle sizes ranging from coarse grit to sub-10-micron powders for industrial applications. Milled pyrophyllite dominates volume flows into plastics compounding where its platy structure enhances dimensional stability and surface finish. Calcined pyrophyllite commands premium positioning in ceramics and refractories where low iron content and controlled shrinkage properties justify higher unit economics. Microfine grades are gaining traction in pharmaceutical and advanced electronics applications where ultra-low contamination thresholds apply.
The US EPA and OSHA frameworks govern workplace exposure limits and particulate emissions in pyrophyllite mining and milling operations, while India's BIS standards prescribe chemical purity benchmarks for construction-grade material. REACH compliance in Europe restricts heavy metal content in pyrophyllite destined for consumer goods and food-contact applications, redirecting trade flows toward certified supply chains. Stakeholders must monitor evolving tailings management regulations and carbon accounting requirements that will increasingly determine which producers retain market access across major consuming regions.
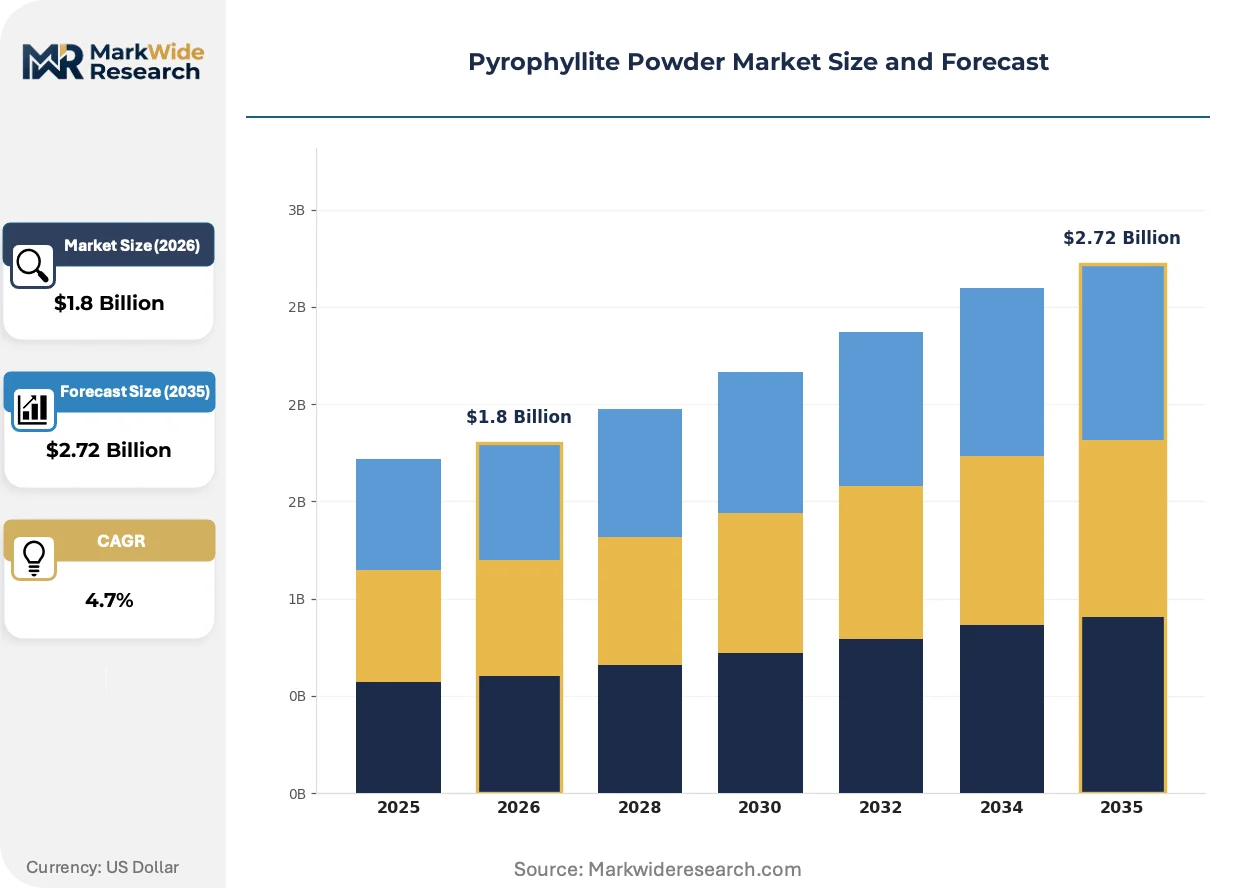
Market Dynamics
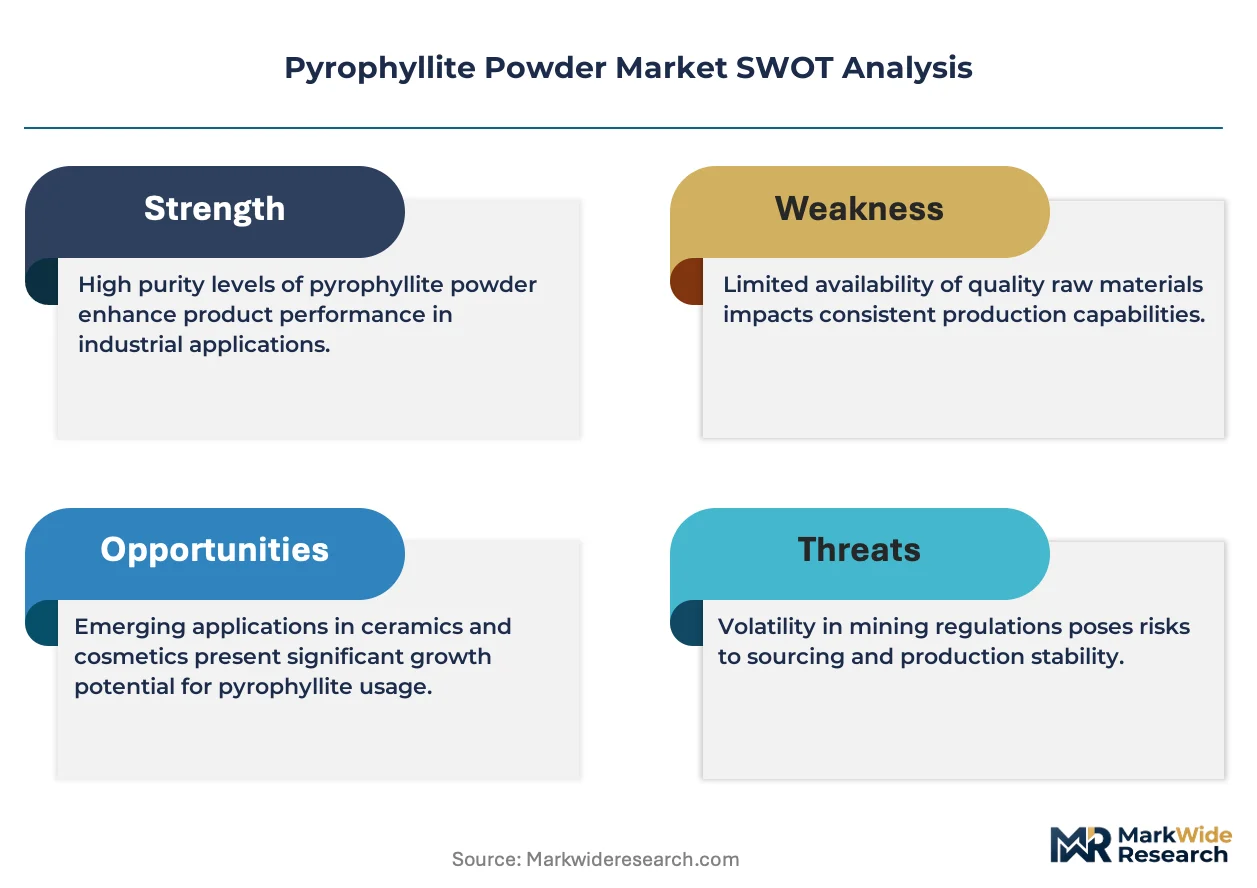
China's MEE environmental compliance tightening is forcing pyrophyllite miners to retrofit tailings systems and relocate processing capacity, redistributing supply leverage toward certified producers in India and North America.
Growth Catalysts
- REACH heavy-metal limits:European consumer goods and food-contact mandates redirect trade flows toward certified supply chains with documented purity thresholds.
- Steel and cement refractory demand:India's infrastructure buildout concentrates consumption of high-alumina grades for furnace linings and kiln bricks.
- Plastics compounding:Milled pyrophyllite's platy structure enhances dimensional stability in automotive and packaging polymers.
Market Restraints
- Energy cost volatility:Calcination requires sustained high-temperature firing, exposing margins to natural gas and electricity price swings.
- Deposit concentration:Premium low-iron ore bodies cluster in specific Chinese provinces and select Appalachian formations.
- Kaolin substitution:Paper coatings and some ceramic bodies accept lower-cost aluminosilicate alternatives with comparable brightness.
Strategic Opportunities
- Microfine pharmaceutical grades:Ultra-low contamination thresholds open entry into excipient and advanced electronics applications.
- North American nearshoring:US EPA and OSHA frameworks favor domestic sourcing for defense and critical mineral stockpiles.
- Digital mineral traceability:Blockchain-linked custody records command premium positioning in European and Japanese supply chains.
Industry Challenges
- Process engineering talent scarcity:Specialized knowledge in controlled calcination and particle classification resides with aging workforces at established operations.
- BIS certification timelines:India's construction-grade purity benchmarks require extended laboratory validation before market access.
- Legacy equipment retrofit costs:Dust collection and effluent treatment upgrades strain mid-scale producers with dated milling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrophyllite Powder Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Pyrophyllite, Milled Pyrophyllite, Calcined Pyrophyllite, Microfine Pyrophyllite Application: Plastics, Ceramics, Paints, Pharmaceuticals End User: Construction, Automotive, Electronics, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Trinity Resources Ltd., Khajuraho Minerals Pvt Ltd, Shibang Industry & Technology Group Co., Ltd., Vanderbilt Minerals, LLC, Wonderstone Ltd, Ashapura Minechem Limited, Jushi Group, Rio Tinto, Imerys Ceramic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrophyllite Powder Market Evolving Landscape
Processing technology and supply chain verification protocols are compressing quality differentiation and reshaping how buyers assess mineral provenance.
Dry milling with integrated air classification is overtaking wet processing for sub-20-micron grades. Ceramic and plastics compounders in Germany and Japan adopt these systems to eliminate drying stages and reduce moisture-related defects. The technology is overtaking traditional ball-mill circuits by cutting energy intensity and enabling real-time particle size distribution control.
EU CSRD sustainability reporting mandates now cover mineral supply chain emissions and tailings management disclosures. Downstream ceramic manufacturers face audit requirements for Scope 3 upstream impacts. Italian and Spanish tile producers are consolidating supplier bases to reduce documentation complexity and ensure audit-ready traceability.
Multi-year offtake agreements with embedded quality bands are replacing spot-market purchasing for refractory-grade material. Indian steel mills and cement kiln operators now contract directly with mine-mouth processors, bypassing traditional trading intermediaries. This pattern is most visible in Maharashtra and Karnataka, where integrated mining-processing complexes anchor supply security.
Pyrophyllite Powder Market Segmentation
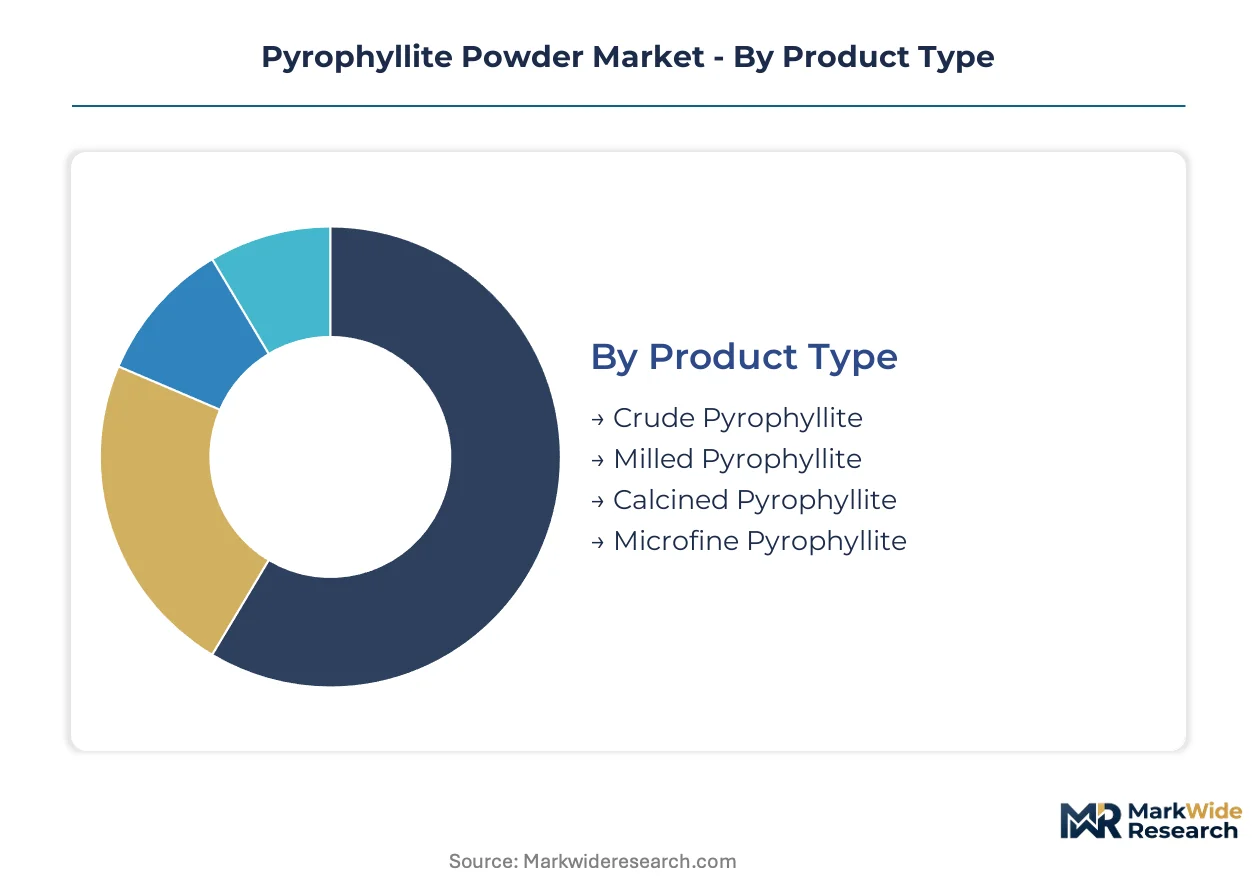
Pyrophyllite powder segmentation reveals how processing intensity and purity thresholds partition value capture across industrial supply chains. Buyers select grades based on thermal performance requirements, contamination limits, and downstream formulation compatibility.
Product Type:
Supply concentration in calcination capacity and micronization infrastructure determines competitive positioning across product tiers.
- Crude Pyrophyllite:Run-of-mine material with minimal processing, typically 1-2 inch lumps for direct refractory brick manufacturing or export to grinding facilities. Indian mine-mouth processors in Rajasthan and Madhya Pradesh dominate volume flows to domestic steel and cement kiln operators seeking cost-effective alumina-silicate feedstock.
- Milled Pyrophyllite:Finely ground material with particle sizes ranging from 45 to 200 mesh, processed through dry ball milling or air classification systems. Demand concentrates in automotive plastics compounding where its platy structure enhances dimensional stability in polypropylene and nylon formulations for under-hood components.
- Calcined Pyrophyllite:Heat-treated at 800-1000°C to remove hydroxyl groups and reduce shrinkage, commanding premium positioning in technical ceramics and advanced refractories.
- Microfine Pyrophyllite:Sub-10-micron powders produced through jet milling, serving pharmaceutical excipient and advanced electronics applications with ultra-low iron and heavy metal specifications.
Milled pyrophyllite absorbs the bulk of installed capacity; microfine grades are expanding most quickly.
Application:
Cost tier differentiation separates commodity volume applications from specification-driven premium segments.
- Plastics:Functional filler in thermoplastic compounding where platy particle morphology improves stiffness, heat distortion temperature, and surface finish. Automotive under-hood components and appliance housings in Germany and Japan represent concentrated demand for 20-45 micron grades with controlled aspect ratios.
- Ceramics:Body constituent and glaze additive in floor and wall tile manufacturing, leveraging low thermal expansion and controlled shrinkage during firing. Italian and Spanish tile producers prioritize low-iron calcined material for bright white body compositions.
- Paints:Extender pigment providing flatting efficiency and scrub resistance in architectural coatings.
- Pharmaceuticals:Inert excipient and processing aid in tablet formulations, requiring microfine grades with documented heavy metal compliance under REACH and USP standards.
Ceramics absorbs the bulk of installed capacity; pharmaceuticals is climbing the fastest.
End User:
Customer type determines procurement patterns, with integrated manufacturers favoring direct mine-mouth contracts and fragmented processors relying on distributor networks.
- Construction:Refractory linings for cement rotary kilns, lime kilns, and steel ladles, consuming high-alumina grades with specified cold crushing strength. Indian infrastructure buildout concentrates demand among UltraTech Cement, JSW Steel, and similar integrated producers.
- Automotive:Under-hood plastics, brake linings, and sealant formulations requiring consistent particle size distribution and thermal stability.
- Electronics:Ceramic substrates, insulators, and semiconductor processing equipment components demanding ultra-low alkali and iron content.
- Consumer Goods:Personal care products, food-grade packaging, and household ceramics subject to REACH and FDA migration limits.
Construction commands the dominant share of volume; electronics is gaining share fastest.
Distribution Channel:
Geography shapes channel selection, with bulk mineral logistics favoring direct rail and vessel shipments while specialty grades move through technical distributors.
- Direct Sales:Long-term offtake agreements between mine-mouth processors and large refractory or ceramic manufacturers, bypassing intermediaries. Indian steel mills in Maharashtra and Karnataka increasingly contract directly with western Indian mining complexes for supply security.
- Distributors:Technical mineral distributors stocking multiple grades for mid-scale compounders and ceramic body suppliers, providing blending and just-in-time delivery services.
- Online Sales:E-procurement platforms for standardized milled grades, primarily serving small-scale plastics processors and research institutions.
- Retail:Packaged microfine and specialty grades for laboratory, artisan ceramic, and pharmaceutical R&D applications.
Direct sales captures the majority of tonnage; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian formations in the eastern United States anchor premium low-iron ore reserves, while Rajasthan's mining belt in western India feeds refractory-grade demand across South Asia. Chinese pyrophyllite deposits in Hunan and Zhejiang provinces face MEE environmental compliance pressures that are redistributing supply leverage toward certified producers elsewhere.
United States
Refractory manufacturers in Pennsylvania and Ohio consume calcined grades for steel furnace linings and cement kiln bricks. EPA workplace exposure limits and OSHA particulate emission standards govern mining operations in North Carolina and Georgia deposits. Vanderbilt Minerals, LLC leverages its North American deposit base to sustain consistent feedstock quality for high-temperature applications serving defense and critical mineral stockpiles.
China
Technical ceramics producers in Guangdong and Fujian provinces drive consumption of low-thermal-expansion material for electronic substrates and insulators. MEE environmental compliance tightening forces miners to retrofit tailings systems and relocate processing capacity from Hunan ore bodies. Zhejiang processing clusters are consolidating toward integrated mining-milling complexes with documented carbon accounting for European export eligibility.
India
UltraTech Cement and JSW Steel anchor refractory-grade consumption for infrastructure buildout across Maharashtra and Karnataka. BIS chemical purity benchmarks prescribe extended laboratory validation timelines for construction-grade material before market access. Rajasthan and Madhya Pradesh mine-mouth processors increasingly contract directly with western Indian steel mills, bypassing traditional trading intermediaries for supply security.
Germany
Automotive plastics compounders in Bavaria and Baden-Württemberg specify 20-45 micron milled grades with controlled aspect ratios for under-hood polypropylene formulations. REACH heavy-metal limits redirect trade flows toward certified supply chains with documented purity thresholds for consumer goods applications. CSRD sustainability reporting mandates now cover mineral supply chain emissions disclosures for downstream ceramic manufacturers.
Italy
Floor and wall tile manufacturers in Sassuolo and Modena prioritize low-iron calcined material for bright white body compositions. EU Green Deal carbon accounting requirements favor suppliers with blockchain-linked custody records for audit-ready traceability. Ceramic producers are consolidating supplier bases to reduce documentation complexity under tightening Scope 3 upstream impact audits.
Pyrophyllite Powder Market Competitive Landscape
Capacity expansion dominates the current landscape as established miners retrofit environmental systems and add micronization infrastructure to capture premium-grade margins. The vendor base stratifies across integrated mining-processing complexes, specialty chemical distributors, and regional trading intermediaries. Three archetypes anchor competitive positioning: deposit-owning integrated producers with captive calcination capacity, toll-processing specialists serving pharmaceutical and electronics grades, and mine-mouth traders linking Chinese and Indian ore to global refractory buyers. M&A activity concentrates on securing Appalachian and Rajasthan deposit access, while strategic partnerships with plastics compounders lock in multi-year offtake volumes.
Among deposit-integrated specialists, Vanderbilt Minerals, LLC and Ashapura Minechem Limited exemplify the integrated mining-processing archetype with captive infrastructure across North America and western India respectively. Trinity Resources Ltd. occupies a position within the specialty-grade tier, serving North American paints and coatings applications where documented provenance commands positioning premiums.
| Leading Market Players |
|---|
| Trinity Resources Ltd. |
| Khajuraho Minerals Pvt Ltd |
| Shibang Industry & Technology Group Co., Ltd. |
| Vanderbilt Minerals, LLC |
| Wonderstone Ltd |
| Ashapura Minechem Limited |
| Jushi Group |
| Rio Tinto |
| Imerys Ceramic |
| Others |
Value Network & Pricing Analysis
Indian steel mills and cement kiln operators now anchor the dominant pricing model through multi-year offtake agreements with embedded quality bands, bypassing volatile spot markets for supply security. This buyer concentration compresses margins for mid-scale traders while rewarding integrated mine-mouth processors with captive calcination capacity.
Pricing Analysis
Service bundling separates contract structures, with technical support and guaranteed assay certificates included in premium calcined grades while crude material trades unbundled. Pricing stratifies across calcined, milled, and crude tiers driven by iron content thresholds and REACH documentation depth. Cost compression in standard milled grades intensifies as kaolin substitution pressures ceramic body formulations. Small-scale plastics compounders exhibit highest price sensitivity, while pharmaceutical and electronics buyers prioritize contamination documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Mumbai handle bulk milled grades before final micronization or blending. Mine-mouth supply concentrates in China's Hunan and Zhejiang provinces, India's Rajasthan and Madhya Pradesh belts, and Appalachian formations in North Carolina. Processing draws from natural gas for calcination, specialized air classification equipment, and laboratory validation services. Single-source vulnerability runs through Chinese environmental compliance retrofits disrupting tailings-permitted capacity. Distribution runs through direct rail and vessel shipments for bulk refractory grades, with specialty microfine material moving via technical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pyrophyllite powder operates as a cost-of-compliance market where REACH heavy-metal limits and China's MEE environmental standards erect barrier-to-entry moats favoring certified integrated producers over trading intermediaries.
For Market Incumbents: Anticipate margin compression from kaolin substitution in ceramic bodies by deepening captive calcination capacity in low-iron Appalachian deposits. Secure BIS certification pipelines for Indian construction-grade access before validation timelines extend. Prioritize blockchain-linked custody records for EU Green Deal audit readiness among Italian and Spanish tile producers. For New Entrants and Emerging Players: Specialty pharmaceutical compounders seeking USP-grade microfine excipients represent the most penetrable buyer archetype given ultra-low contamination thresholds and limited certified supply. Target toll-processing partnerships with established Rajasthan mining complexes to bypass capital-intensive deposit acquisition. Lead with documented heavy metal compliance under REACH rather than price positioning. For Investors and Strategic Acquirers: The window for entry favors deposit-integrated specialists with captive micronization infrastructure serving defense and critical mineral stockpiles. Long-term viability hinges on carbon accounting disclosures under CSRD mandates. Watch for MEE enforcement actions in Hunan as inflection indicator for Chinese supply displacement toward Indian and North American alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcination | Captive high-temperature capacity secures margin capture from steel furnace lining demand. |
| Blockchain Traceability Implementation | EU ceramic manufacturers require audit-ready custody records under Scope 3 disclosure rules. |
| Microfine Jet Milling Expansion | Sub-10-micron capacity opens pharmaceutical excipient and semiconductor equipment markets. |
| Long-term Supply Agreement | Mine-mouth contracts with JSW Steel and UltraTech Cement reduce spot market exposure. |
| Green Manufacturing Transition | Natural gas-to-renewable calcination fuel switching addresses EU carbon border adjustment mechanisms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at calcination facilities, procurement leads at refractory manufacturers, technical R&D directors in plastics compounding, and distribution channel partners in technical minerals. Bottom-up volume estimates from mine-level production data triangulated against top-down consumption patterns from ceramic body and refractory brick output statistics across Germany, Italy, India, China, and the United States.
Data-stream reconciliation aligned production capacity surveys with import-export flows and end-use consumption indices across the projection horizon. Segmentation modeling captured grade tier, end-use industry, and regional production hub dimensions. CAGRs derived from elasticity-adjusted demand projections for steel, cement, and automotive output, incorporating BIS certification timeline assumptions and MEE environmental compliance retrofit schedules as industry-specific inputs.
Revisions become necessary when Chinese environmental enforcement intensity exceeds modeled scenarios or when EU carbon border adjustments accelerate beyond current phase-in schedules. Forecasts reflect documented assumptions regarding calcination energy costs and tailings permitting availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Global Quinine Sulphate Market