
 North America Concrete Floor Coatings Market | 2026-2036
North America Concrete Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concrete Floor Coatings Market Intelligence
Market Context
OSHA's updated workplace safety enforcement is repositioning the cost-of-entry calculus for concrete floor coatings across North American industrial facilities. PPG Industries sustains formidable manufacturing scale across its US coating operations, while BASF SE leverages its epoxy resin vertical integration to secure raw material cost advantages. Tennant Coatings specializes in institutional and healthcare flooring systems, anchoring a defensible niche against broader-spectrum competitors.
Technical Definition and Segment Structure
North America concrete floor coatings comprise polymer-based protective systems—typically epoxy, polyurethane, or polyaspartic formulations applied at 2–20 mils dry film thickness—to seal, harden, and chemically resist concrete substrates in high-traffic environments. Epoxy formulations dominate installed volume across manufacturing floors, though polyaspartic technology commands premium positioning for rapid-return-to-service applications in retail and warehousing. Water-based technology segments are gaining formulation share as EPA VOC regulations tighten solvent-based alternatives, while 100% solids systems capture margin pools in industrial end uses demanding zero-VOC performance.
Regulatory Frame and Outlook
EPA VOC rules, OSHA slip-resistance standards, and state-level California Air Resources Board protocols collectively shape product registration, formulation migration, and contractor certification requirements across the United States and Canada. These frameworks compel manufacturers to reformulate solvent-based portfolios while creating compliance-driven replacement cycles in legacy industrial installations. Stakeholders must monitor evolving state-level air quality mandates and assess whether low-VOC technology investments align with accelerating regulatory timelines.
Market Dynamics
OSHA's intensified slip-resistance enforcement and EPA VOC phase-down schedules are compressing formulation cycles while warehousing automation drives specification upgrades across North American industrial floors.
Growth Catalysts
- Texas warehousing corridor:E-commerce fulfillment centers along the Dallas-Houston axis are specifying 100% solids epoxy systems for rapid-turn installation cycles.
- EPA VOC rules:Federal emissions limits on solvent-based coatings are forcing reformulation investments that create replacement demand in legacy manufacturing facilities.
- Polyaspartic technology:Two-hour return-to-service properties are displacing conventional cure schedules in retail and food-service environments.
Market Restraints
- Epoxy resin supply concentration:Gulf Coast petrochemical disruptions expose formulators to feedstock volatility and force majeure risks.
- Skilled applicator scarcity:Unionized coating contractor pools in the US Midwest and Ontario cannot expand fast enough to match installation demand.
- California Air Resources Board protocols:State-level VOC limits stricter than federal standards fragment product portfolios and raise compliance costs.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring-driven industrial construction in Nuevo León and Baja California creates underpenetrated specification opportunities.
- Healthcare antimicrobial systems:Joint Commission accreditation standards are elevating infection-control flooring requirements in US hospital networks.
- Waterborne-UV hybrid convergence:Low-VOC base coats with ultraviolet-cured topcoats offer compliance-speed combinations for California and Northeast markets.
Industry Challenges
- Moisture vapor transmission testing:ASTM F2170 probe certification delays and interpretive disputes between contractors and owners stall project starts.
- Specification authority fragmentation:Architects, facility engineers, and maintenance directors hold conflicting decision rights across project types.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concrete Floor Coatings Market |
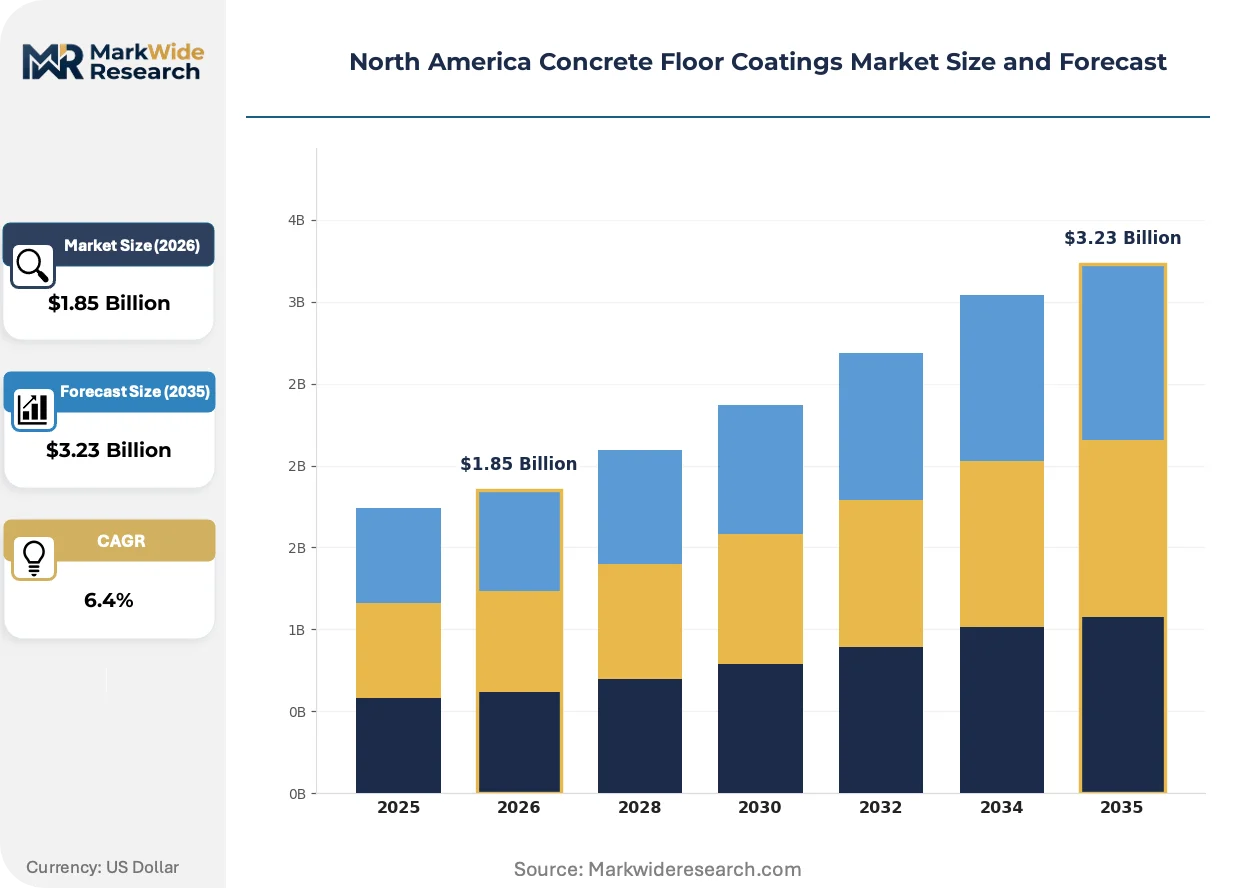
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic Application: Residential, Commercial, Industrial, Institutional Technology: Water-Based, Solvent-Based, 100% Solids, UV-Cured End User: Manufacturing, Retail, Hospitality, Warehousing |
| Companies Covered | The Sherwin-Williams Company, BASF SE, PPG Industries, Inc., Henkel AG & Co. KGaA, Axalta Coating Systems, Jotun, Tennant Coatings, Stonhard, North American Coating Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concrete Floor Coatings Market Strategic Shifts & Innovations
Formulation chemistry, regulatory compliance architecture, and procurement contracting models are simultaneously restructuring how protective floor systems are specified, applied, and maintained across North American industrial and commercial assets.
Decorative flake broadcast systems are integrating metallic pigment and quartz aggregate technologies to deliver showroom-grade aesthetics in automotive service centers and craft brewery taprooms. National retail chains are specifying these systems at scale for brand-standardized environments. The technology is integrating visual performance requirements previously reserved for polished concrete or terrazzo into mid-cost coating specifications.
EPA's National Emission Standards for Hazardous Air Pollutants (NESHAP) for surface coating operations are compelling facility-level emissions tracking and control device investments. Industrial finishers in Ohio, Michigan, and Pennsylvania are consolidating coating operations or outsourcing to compliant job shops. Waterborne and 100% solids formulations are capturing specification share in automotive and aerospace manufacturing floors where solvent-based systems previously dominated.
Facility managers are compressing coating procurement into integrated facility services contracts that bundle surface preparation, application, and multi-year maintenance. Third-party property management firms are displacing direct owner specification in warehouse and distribution portfolios. This pattern is most visible in Texas, Georgia, and the Carolinas where institutional real estate investors concentrate logistics asset ownership.
North America Concrete Floor Coatings Market Segmentation
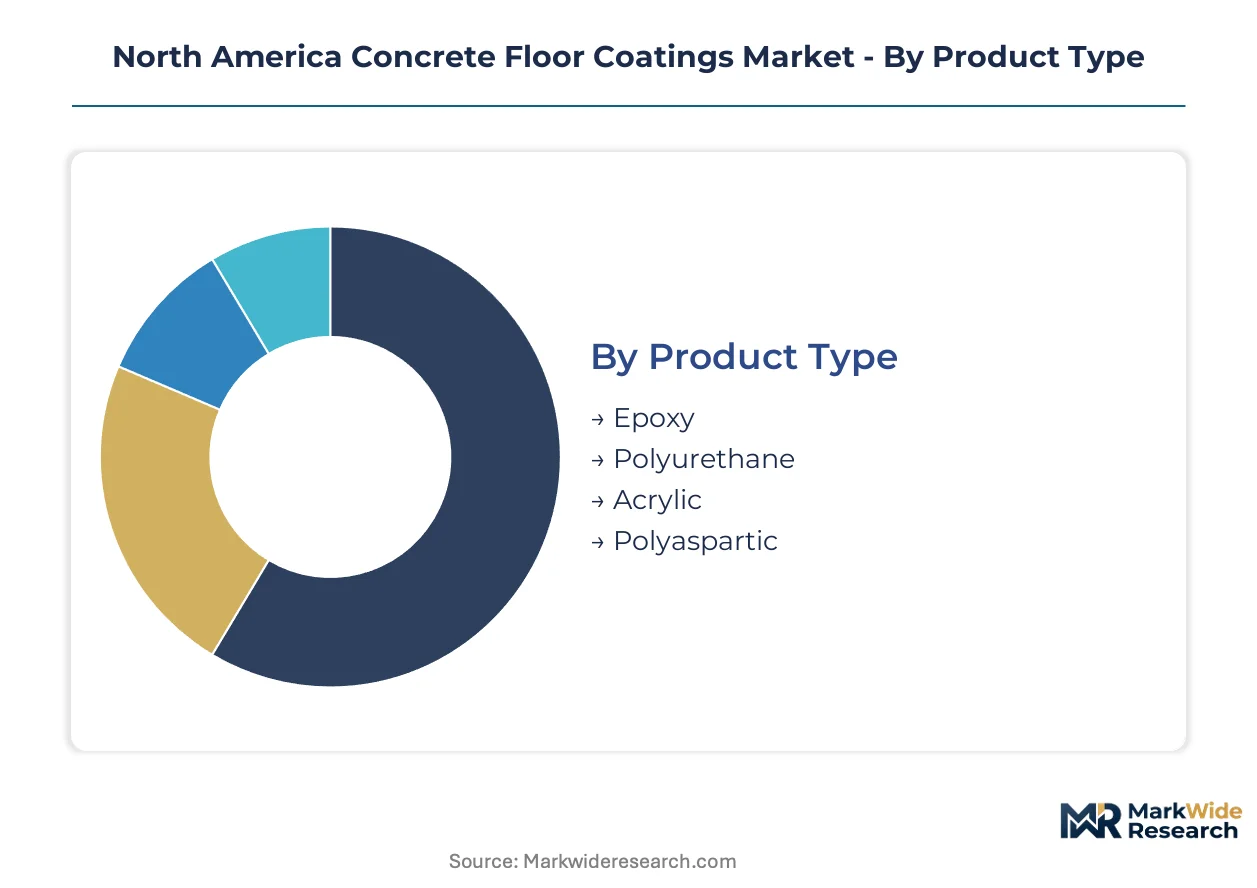
Concrete floor coatings in North America fragment across formulation chemistry, installation environment, and buyer sophistication. Specification authority varies sharply between facility engineers seeking durability metrics and procurement teams optimizing total cost of ownership.
Product Type:
Buyers differentiate primarily by cure speed, chemical resistance, and lifecycle cost rather than upfront material price.
- Epoxy:Two-part thermosetting systems deliver superior compressive strength and chemical resistance for manufacturing floors. Demand concentrates across Ohio and Michigan automotive plants where OSHA chemical spill containment rules mandate impermeable barriers. Gulf Coast petrochemical feedstock concentration exposes formulators to supply volatility.
- Polyaspartic:Aliphatic polyurea technology achieves full cure within two hours, enabling overnight installation in Texas retail and food-service environments. Rapid return-to-service justifies 40-60% material cost premiums over conventional epoxy in high-revenue-per-hour operations.
- Polyurethane:Flexible aliphatic topcoats provide UV stability and abrasion resistance for exterior concrete walkways and parking structures.
- Acrylic:Lower-cost decorative sealers serve residential garages and light commercial showrooms with moderate traffic loads.
Volume sits with epoxy; growth tilts toward polyaspartic.
Application:
Project scale and specification complexity separate buyers, with industrial tenders demanding certified applicator networks unavailable to residential contractors.
- Industrial:Heavy-duty systems withstand forklift traffic, chemical exposure, and thermal shock across manufacturing and processing facilities. Demand clusters along the US Gulf Coast petrochemical corridor and Ontario automotive assembly plants where EPA and Environment Canada emissions rules drive low-VOC specification.
- Commercial:Decorative flake and metallic systems serve retail, restaurant, and automotive showrooms requiring brand-aligned aesthetics. National chains in Texas and Georgia specify standardized finishes across multi-location rollouts.
- Institutional:Healthcare and education facilities prioritize slip resistance and infection control under Joint Commission and CMS accreditation standards.
- Residential:Garage floor coatings and basement sealers represent price-sensitive demand served through big-box retail and direct-to-consumer channels.
Industrial captures the largest project values; commercial applications are expanding most quickly.
Technology:
Regulatory compliance timelines and installation speed requirements push buyers toward specific formulation platforms.
- 100% Solids:Zero-VOC systems deliver maximum film build in single applications, satisfying EPA NESHAP standards for industrial facilities in Pennsylvania and Ohio. High material cost and specialized spray equipment requirements limit contractor participation.
- Water-Based:Reduced-emission formulations penetrate California and Northeast markets where state-level VOC limits exceed federal stringency. Longer cure times restrict deployment in time-critical installations.
- Solvent-Based:Traditional high-performance systems face phasedown pressure under EPA emission schedules, creating replacement demand in legacy manufacturing floors.
- UV-Cured:Instant-cure technology enables thin-film decorative applications with minimal downtime, gaining traction in high-end retail environments.
100% solids dominates industrial value; water-based platforms are gaining share fastest in regulated states.
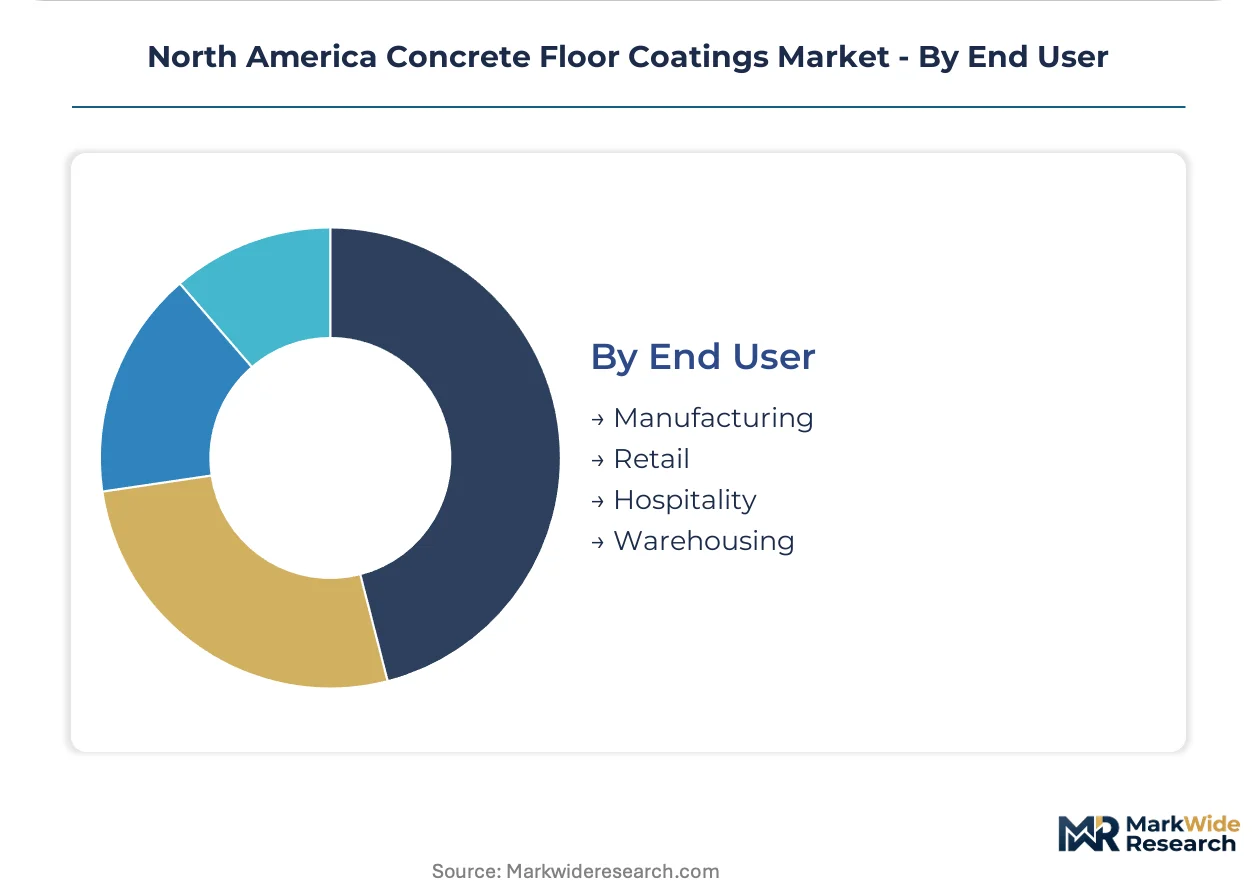
End User:
Operational uptime economics and maintenance budgeting cycles determine specification authority across buyer organizations.
- Warehousing:E-commerce fulfillment centers along the Dallas-Houston corridor specify rapid-cure systems supporting 24-hour operational continuity. Automation-driven facility expansion sustains double-digit specification growth.
- Manufacturing:Process industries demand chemical-resistant, thermally stable floors under FDA food safety and OSHA process safety management rules. Preventive maintenance schedules drive recurring coating replacement cycles.
- Retail:Brand-standardized environments prioritize visual consistency and rapid installation across multi-location portfolios.
- Hospitality:Hotels and restaurants balance aesthetic requirements with slip-resistance liability concerns under premises safety law.
Warehousing commands the steepest expansion trajectory; manufacturing retains the deepest replacement backlog.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zone tax incentives and Foreign Trade Zone designations across the US Gulf Coast and Mexico's northern border states are concentrating industrial floor coating demand in logistics-adjacent corridors. State-level air quality mandates in California and the Northeast create fragmented compliance requirements that reshape product portfolios. Regional specification authority varies between facility engineers, architects, and third-party property managers.
United States
Texas e-commerce fulfillment centers along the Dallas-Houston corridor specify rapid-cure polyaspartic systems supporting 24-hour operational continuity. EPA National Emission Standards for Hazardous Air Pollutants (NESHAP) compel Ohio and Michigan automotive plants to migrate from solvent-based to 100% solids formulations. California Air Resources Board protocols exceed federal VOC limits, forcing dedicated product lines for West Coast distribution.
Canada
Ontario automotive assembly plants under Environment Canada emissions rules drive low-VOC specification in manufacturing floors. Unionized coating contractor pools in the Toronto-Windsor corridor face capacity constraints against installation demand. Quebec's construction sector prioritizes waterborne systems for commercial and institutional projects under provincial air quality guidelines.
Mexico
Nuevo León nearshoring-driven industrial construction creates specification opportunities in Monterrey-area manufacturing campuses. The Secretariat of Environment and Natural Resources (SEMARNAT) implements emissions regulations that elevate compliance requirements for imported coating systems. Baja California maquiladora facilities specify rapid-installation systems to minimize production downtime.
North America Concrete Floor Coatings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and application service tiers. The market structures around three participant categories: multinational chemical conglomerates with captive resin supply, regional coating formulators with specialized applicator networks, and integrated flooring contractors controlling specification-to-installation workflows. Dominant competitive moves include backward integration into epoxy resin production and strategic partnerships with third-party facility management firms.
Among diversified chemical conglomerates, BASF SE and PPG Industries occupy positions anchored by manufacturing scale and raw material access. Tennant Coatings exemplifies the focused specialist archetype, concentrating institutional and healthcare flooring systems. These three entities represent distinct strategic postures: captive supply chain control, broad industrial coating portfolios, and defensible niche segmentation.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| BASF SE |
| PPG Industries, Inc. |
| Henkel AG & Co. KGaA |
| Axalta Coating Systems |
| Jotun |
| Tennant Coatings |
| Stonhard |
| North American Coating Solutions |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up coating specialists have consolidated regional applicator networks across Texas and the US Southeast, tightening supply discipline while extracting pricing power from fragmented facility maintenance budgets. This ownership concentration aligns supply capacity with project bundling economics, compressing spot-market availability and elevating contract premiums for rapid-turn installations.
Pricing Analysis
Short lead-time premiums dominate pricing architecture across the North American concrete floor coatings market, with 24-hour mobilization commands attaching 25-35% uplifts over standard-schedule projects. Three-tier pricing structure across premium, standard, and economy levels separates polyaspartic rapid-cure systems from conventional epoxy and water-based alternatives. Cost compression in solvent-based tiers is intensifying because EPA NESHAP compliance investments are eroding margins without volume offsets. Residential garage coating buyers exhibit highest price sensitivity, while Texas e-commerce fulfillment operators accept material premiums for operational continuity guarantees.
Supply Chain Analysis
Direct-to-facility contractor channels handle hyperscale warehousing demand along the Dallas-Houston corridor, bypassing traditional distribution intermediaries. Epoxy resin production concentrates in Texas, Louisiana, and Ohio, drawing from bisphenol-A and epichlorohydrin feedstocks anchored in Gulf Coast petrochemical complexes. Supply chain risk centers on single-source vulnerability: Hurricane-season disruptions at Houston Ship Channel resin terminals cascade through formulation capacity within 72 hours. Distribution runs through certified applicator networks rather than open-stock retail, with contractor certification requirements limiting downstream participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled applicator scarcity across the US Midwest and Ontario props pricing discipline, constraining installation capacity below demand growth from warehousing automation investments. This bottleneck sustains margin pools for contractors with certified workforces and rapid-cure technology access.
For Market Incumbents: Hedge against resin feedstock volatility through captive supply arrangements or long-term offtake contracts with Gulf Coast petrochemical producers. Expand certified applicator training capacity in Texas and Georgia to capture warehousing specification growth before unionized contractor pools recover. Defensive consolidation of regional formulators with established EPA compliance portfolios mitigates regulatory displacement risk from waterborne technology migration. For New Entrants and Emerging Players: Third-party facility management firms represent the most penetrable channel for specification influence, displacing direct owner procurement in logistics asset portfolios. Target Mexico's Nuevo León manufacturing corridor where nearshoring construction outpaces established coating brand presence. Joint venture structures with Monterrey-area construction contractors accelerate SEMARNAT compliance navigation and local specification authority. For Investors and Strategic Acquirers: Union wage arbitration settlements in Ontario and Michigan are the leading indicator that applicator capacity constraints will persist, sustaining contractor margin premiums. Acquire specialized polyaspartic formulators with rapid-cure IP and established retail food-service reference accounts. Monitor EPA state-level VOC rule harmonization proposals as signal for portfolio consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Captive supply from Gulf Coast petrochemical corridors insulates margin from force majeure disruptions. |
| Certified Applicator Network Expansion | OSHA-compliant training pipelines in Texas and Georgia capture warehousing automation specification demand. |
| Waterborne-UV Hybrid Formulation Development | California Air Resources Board compliance positioning opens Northeast and West Coast specification access. |
| Integrated Facility Services Contracting | Third-party property management bundling displaces direct owner procurement in logistics portfolios. |
| Monterrey-Area Manufacturing Partnership | SEMARNAT-compliant local production navigates Mexico import regulatory complexity for nearshoring demand. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced against primary interviews with coating formulator R&D directors, certified applicator contractors, facility maintenance managers at Texas warehousing operators, and procurement leads at third-party logistics property managers. Bottom-up project pipeline tracking across Dallas-Houston and Detroit-Windsor construction markets combined with top-down chemical industry production data to triangulate volume estimates.
Data-stream reconciliation across formulation chemistry segments, application environment tiers, and end-use operational requirements shaped the analytical framework over the projection horizon. Segmentation modeling incorporated product type, installation speed specifications, technology compliance tiers, and regional regulatory clusters. CAGRs derived from installed base replacement cycles, new construction square footage projections, and formulation migration patterns under EPA emission schedules.
Caveats apply where Gulf Coast hurricane frequency, union labor negotiation outcomes, or state-level VOC rule acceleration could materially shift the outlook. Forecasts reflect assumptions regarding petrochemical feedstock stability and warehousing automation capex continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Antifouling Coatings Market
Coatings
OEM Coatings Market
Coatings
Coating Binders Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Topcoat Market
Coatings
Anti Soiling Coating Market
Coatings
Coating Thickness Gauge Market
Coatings
High Performance Epoxy Coating Market
Coatings
Cool Roof Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Process Pipe Coating Market
Coatings
Global Photocatalytic Coatings Market
Coatings
Global Sputter Coater Market
Coatings
Protective and Marine Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market