
 CMOS X-Ray Detectors Market | 2026-2036
CMOS X-Ray Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
CMOS X-Ray Detectors Market Intelligence
Dental imaging demand is decoupling from hospital-centric procurement as standalone diagnostic imaging centers expand their CMOS detector fleets. Varex Imaging Corporation leverages vertical integration across scintillator materials and readout electronics to sustain pricing power in North America. Hamamatsu Photonics K.K. anchors its position through proprietary photodiode array architectures that dominate high-resolution veterinary diagnostics. Canon Inc. competes by extending its flat panel detector line into portable security scanning systems.
CMOS X-ray detectors are solid-state imaging sensors that convert X-ray photons into digital electrical signals through integrated photodiode arrays and active pixel circuitry, achieving spatial resolutions exceeding 2.5 line pairs per millimeter for real-time fluoroscopy and static radiography. Flat panel detectors occupy the largest revenue pool due to their dominance in human medical imaging, while photodiode arrays represent the fastest-growing product type as industrial inspection services adopt inline defect detection for semiconductor wafers and battery cells. Charge-coupled devices face structural decline as complementary metal-oxide semiconductor technology displaces legacy architectures across dental and non-destructive testing platforms.
FDA 510(k) premarket notification requirements and EU MDR conformity assessment procedures govern product entry into the two largest addressable markets, with ISO 13485 quality management certification now table stakes for supplier qualification by original equipment manufacturers. Japan's PMDA and China's NMPA operate parallel approval tracks that add twelve to eighteen months to market access timelines for foreign manufacturers. Stakeholders must monitor convergence between AI-enabled image reconstruction software and hardware qualification standards, as regulators in multiple jurisdictions draft new frameworks for software-as-medical-device integration.
Market Dynamics
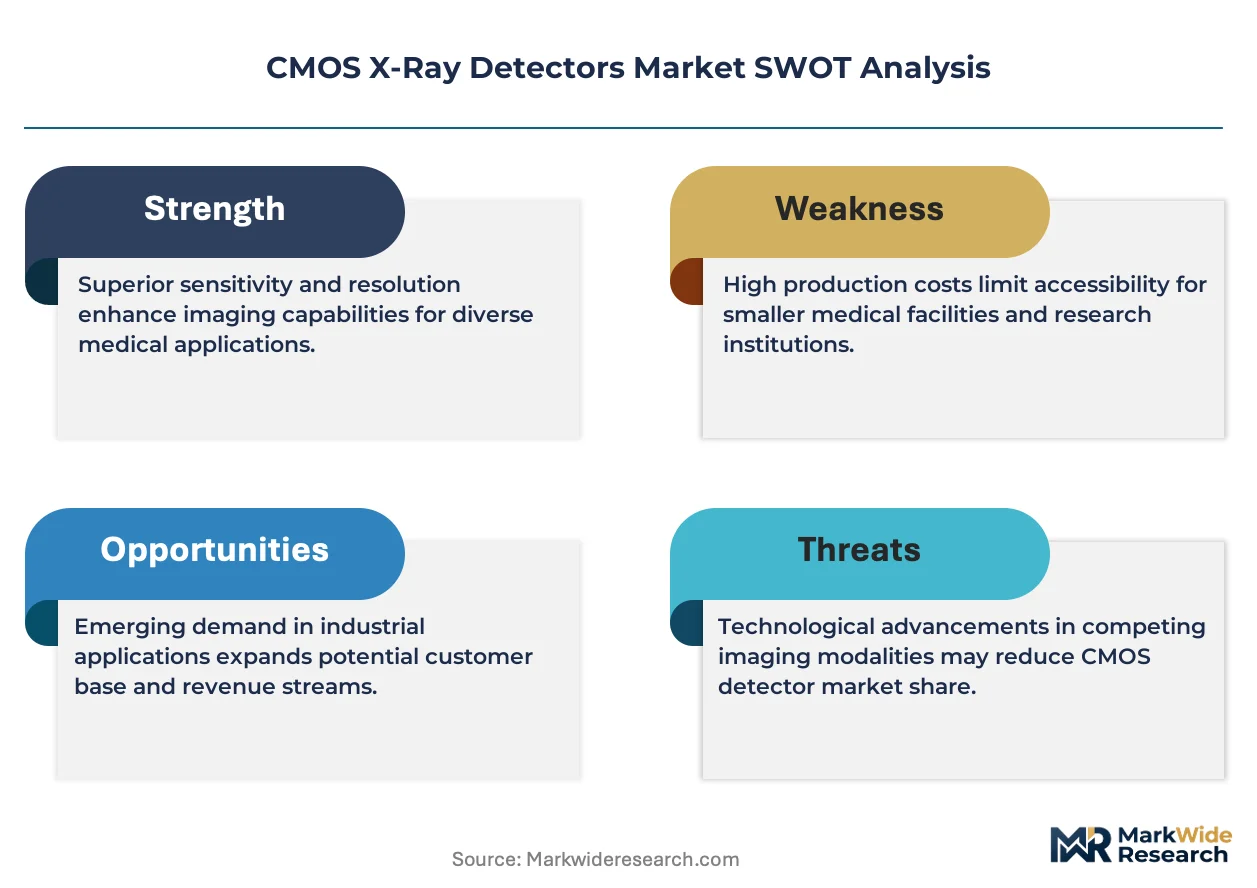
Dental imaging procurement is fragmenting from hospital-centric purchasing toward standalone diagnostic chains, while EU MDR compliance timelines compress product development cycles and force early-stage regulatory investment.
Growth Catalysts
- EU MDR conformity assessment:Manufacturers accelerating certification timelines capture shelf space ahead of competitors facing twelve-to-eighteen-month approval delays. Germany's precision medical device corridor concentrates this demand pull.
- Photodiode array architectures:Industrial inspection services for semiconductor wafers and battery cells drive the fastest-growing product category. Inline defect detection requirements reshape detector specifications.
- AI-enabled image reconstruction:Software-as-medical-device integration creates new qualification frameworks. Regulators in multiple jurisdictions draft hardware-software convergence standards.
Market Restraints
- Scintillator material concentration:Upstream supply of cesium iodide and gadolinium oxysulfide concentrates among limited specialty chemical producers. Price volatility transmits directly to detector manufacturing costs.
- Japan PMDA parallel approval tracks:Foreign manufacturers face extended market access timelines. Domestic incumbents exploit regulatory familiarity to defend installed base positions.
- Charge-coupled device legacy displacement:Dental and non-destructive testing platforms accelerate CMOS migration. CCD equipment depreciation schedules create stranded asset resistance among existing users.
Strategic Opportunities
- Portable security scanning systems:Flat panel detector lines extend beyond medical imaging into customs and border inspection applications. Dual-use certification opens adjacent revenue pools.
- China NMPA localization requirements:Domestic manufacturing partnerships satisfy import substitution policies. Joint ventures with local OEMs accelerate hospital procurement list inclusion.
- Veterinary diagnostic imaging:High-resolution photodiode arrays address underserved companion animal and livestock screening markets. Specialist clinics upgrade from analog film systems.
Industry Challenges
- ISO 13485 quality management implementation:Table-stakes certification demands documented traceability across scintillator sourcing, photodiode fabrication, and final assembly. Auditor capacity constraints extend preparation timelines.
- FDA 510(k) predicate device strategy:Substantial equivalence determinations require careful selection of comparison products. Software-hardware integration complicates traditional clearance pathways.
- Readout electronics integration complexity:Active pixel circuitry design expertise concentrates among specialized semiconductor foundries. Fabless detector developers face foundry capacity allocation competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CMOS X-Ray Detectors Market |
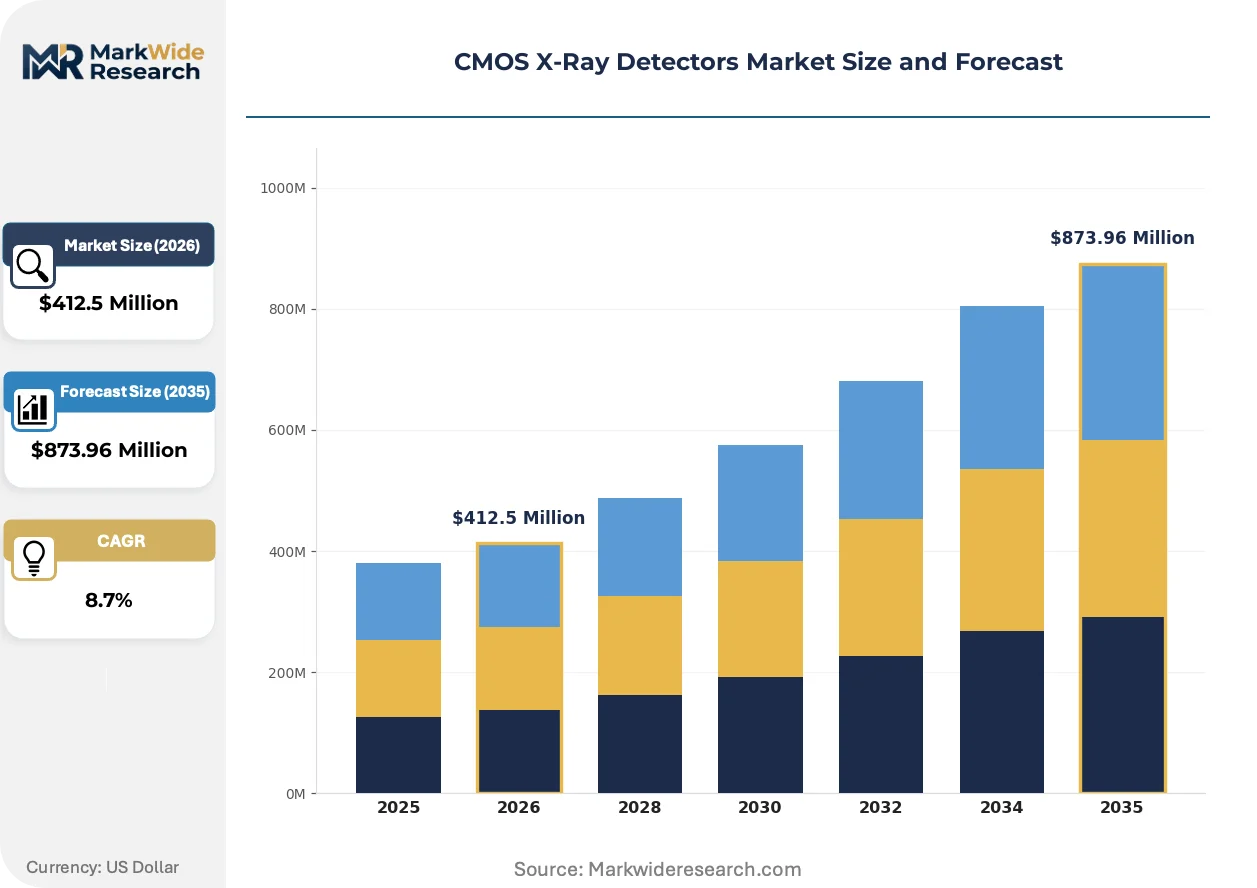
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Image Intensifier Cameras, Charge-Coupled Devices, Photodiode Arrays Technology: Complementary Metal-Oxide Semiconductor, Amorphous Silicon, Indirect Conversion, Direct Conversion Application: Dental Imaging, Non-Destructive Testing, Security Scanning, Veterinary Diagnostics End User: Diagnostic Imaging Centers, Research Laboratories, Industrial Inspection Services, Educational Institutions |
| Companies Covered | Varex Imaging Corporation, Hamamatsu Photonics K.K., Agfa-Gevaert Group, Carestream Dental LLC, Teledyne Digital Imaging Inc., Ziehm Imaging GmbH, Shimadzu Scientific Instruments, Thales Group, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CMOS X-Ray Detectors Market Strategic Shifts & Innovations
Detector architecture convergence and regulatory framework evolution are compressing product lifecycles while expanding addressable applications beyond traditional medical radiography.
Complementary metal-oxide semiconductor active pixel sensor technology is consolidating market position across fluoroscopy and static radiography applications. Dental imaging centers and outpatient diagnostic chains adopt these systems for real-time imaging with spatial resolutions exceeding 2.5 line pairs per millimeter. The technology is consolidating functional boundaries between previously distinct detector categories.
EU MDR technical documentation requirements and post-market surveillance obligations intensify compliance burdens for flat panel detector manufacturers. Clinical evaluation reports now demand systematic literature reviews and equivalence justifications. Human medical imaging OEMs restructure quality management systems ahead of notified body capacity constraints.
Diagnostic imaging centers unbundle equipment procurement from long-term service contracts. Standalone chains negotiate direct detector sourcing while retaining independent maintenance providers. Germany's outpatient network expansion accelerates this purchasing autonomy shift.
CMOS X-Ray Detectors Market Segmentation
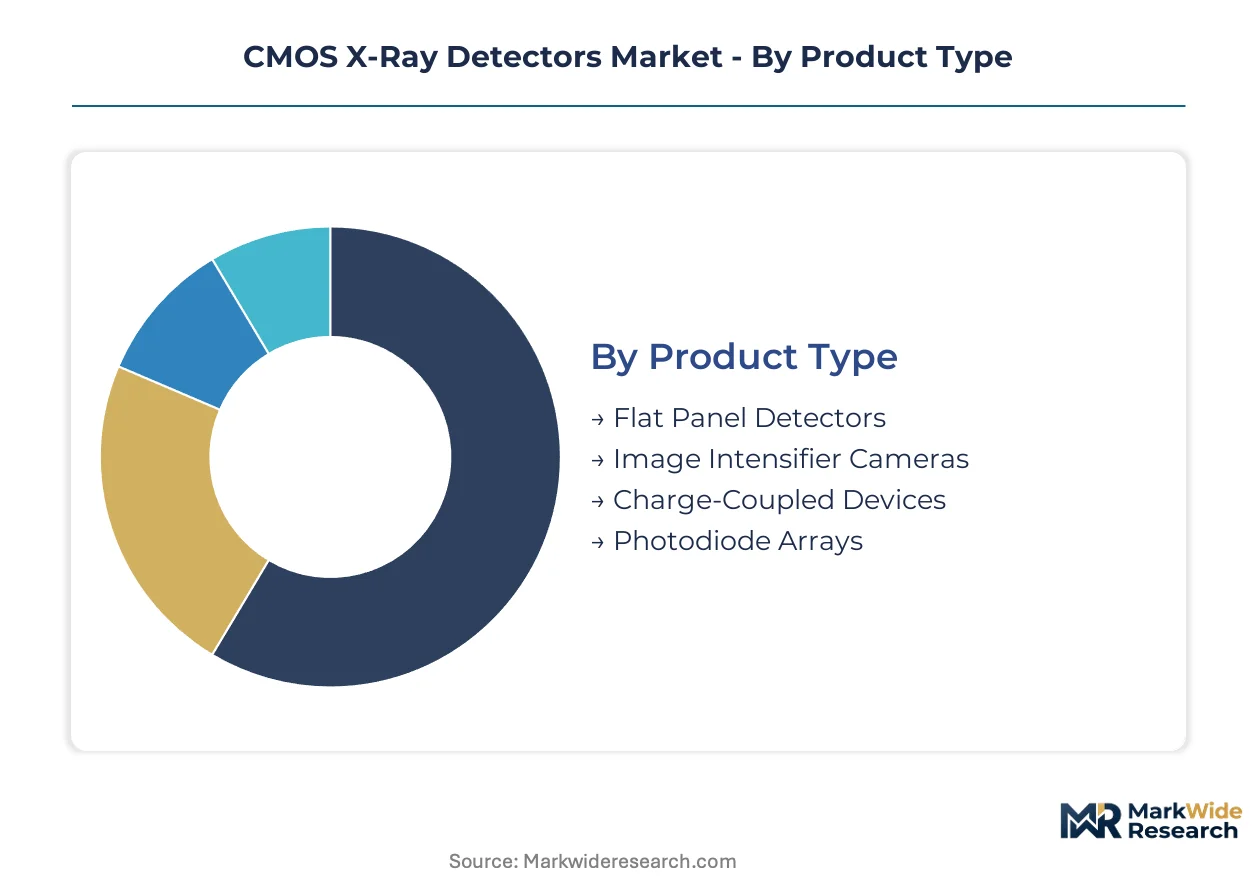
CMOS X-ray detector architectures fragment across competing substrate technologies and conversion mechanisms. Procurement patterns diverge sharply between regulated medical environments and industrial quality control settings. Each segment carries distinct certification burdens and foundry partnerships that reshape competitive access.
Product Type:
Scintillator material sourcing and readout electronics integration concentrate differently across form factors, tilting margin structures toward vertically integrated manufacturers.
- Flat Panel Detectors:Large-area active matrix arrays integrate thin-film transistor backplanes with cesium iodide or gadolinium oxysulfide scintillator layers. Human medical imaging in Germany's outpatient diagnostic chains absorbs the dominant production volumes, though EU MDR technical documentation requirements extend development timelines.
- Photodiode Arrays:Proprietary architectures from Hamamatsu and specialized foundries achieve spatial resolutions exceeding 2.5 line pairs per millimeter for real-time fluoroscopy. Industrial inspection services for semiconductor wafers and battery cells in East Asia drive the steepest expansion trajectory as inline defect detection specifications tighten.
- Image Intensifier Cameras:Vacuum tube-based amplification systems persist in legacy fluoroscopy suites with limited replacement demand.
- Charge-Coupled Devices:Legacy silicon architectures face structural displacement as CMOS active pixel sensors capture dental and veterinary upgrade cycles.
Today's leader: Flat Panel Detectors. Tomorrow's challenger: Photodiode Arrays.
Technology:
Foundry capacity allocation and intellectual property licensing differentiate cost structures across conversion architectures.
- Complementary Metal-Oxide Semiconductor:Active pixel sensor designs consolidate functional boundaries between fluoroscopy and static radiography through integrated analog-to-digital conversion at each pixel site. Dental imaging centers and outpatient chains in North America and Europe prioritize these systems for real-time imaging with reduced dose requirements.
- Direct Conversion:Photon-counting cadmium telluride or cadmium zinc telluride layers eliminate scintillator light conversion losses, enabling spectral imaging with improved contrast-to-noise ratios. Research laboratories and premium diagnostic installations absorb limited production volumes at elevated price points.
- Amorphous Silicon:Thin-film transistor backplanes on glass substrates dominate large-area flat panel manufacturing through mature deposition processes.
- Indirect Conversion:Scintillator-photodiode stacks remain the cost-optimized default for high-volume medical and security applications.
CMOS active pixel architectures command the dominant revenue share. Direct conversion photon-counting systems are gaining share fastest in research and premium clinical segments.
Application:
Regulatory pathway complexity and reimbursement structures fragment addressable margins across use cases.
- Dental Imaging:Intraoral and panoramic systems drive compact detector demand with stringent size and power constraints. Standalone diagnostic chains in Germany and North America unbundle procurement from hospital-centric purchasing, accelerating CMOS displacement of legacy CCD and film systems.
- Security Scanning:Customs and border inspection applications extend flat panel detector lines beyond medical imaging into dual-use certification territories. Portable baggage and cargo screening systems in North America and Middle Eastern hubs absorb specialized ruggedized variants.
- Non-Destructive Testing:Aerospace composite inspection and pipeline integrity assessment deploy high-frame-rate CMOS sensors for computed tomography reconstruction.
- Veterinary Diagnostics:Companion animal and livestock screening markets upgrade from analog film through high-resolution photodiode arrays in specialist clinics.
Dental imaging generates the largest installed base volume. Security scanning applications are expanding most quickly as dual-use certification opens adjacent revenue pools.
End User:
Capital expenditure cycles and maintenance contract structures differentiate customer lifetime values across institutional types.
- Diagnostic Imaging Centers:Outpatient chains negotiate direct detector sourcing while retaining independent maintenance providers, compressing OEM service attach rates. Germany's expanding ambulatory network accelerates this purchasing autonomy shift.
- Industrial Inspection Services:Semiconductor wafer fabrication facilities and battery cell manufacturing lines demand inline defect detection with sub-micron resolution and 24/7 operational reliability.
- Research Laboratories:Synchrotron facilities and materials science departments prioritize photon-counting spectral imaging capabilities at premium price tolerances.
- Educational Institutions:Radiology training programs and veterinary schools absorb refurbished and entry-tier systems with extended depreciation schedules.
Diagnostic imaging centers anchor current revenue concentration. Industrial inspection services are climbing the fastest as manufacturing quality control digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as cost-of-compliance gaps between jurisdictions widen. Manufacturers are relocating assembly operations to exploit faster approval timelines and localized certification support. Production clusters now concentrate where regulatory infrastructure aligns with foundry access and end-market proximity.
United States
FDA 510(k) premarket notification pathways attract manufacturers seeking rapid market access for dental and fluoroscopy systems. The agency's software-as-medical-device guidance creates compliance templates that shorten hardware-software integration timelines. Boston's medical device corridor and Silicon Valley's semiconductor foundry networks host convergent engineering talent pools.
Germany
EU MDR conformity assessment obligations compress product development cycles and force early-stage regulatory investment. Notified body capacity constraints in Munich and Stuttgart drive manufacturers toward pre-certification consulting services. The precision medical device manufacturing corridor between Bavaria and Baden-Württemberg concentrates flat panel detector assembly and scintillator integration expertise.
China
NMPA localization requirements and hospital procurement list inclusion policies favor domestic manufacturing partnerships. Joint ventures with local OEMs accelerate market access beyond standard twelve-to-eighteen-month foreign manufacturer timelines. Yangtze River Delta fabrication clusters in Shanghai and Suzhou supply thin-film transistor backplanes and photodiode arrays to regional detector assemblers.
Japan
PMDA parallel approval tracks extend market access timelines for foreign manufacturers while domestic incumbents exploit regulatory familiarity. Photodiode array fabrication expertise concentrates in Hamamatsu and Nagoya industrial zones. METI industrial standards harmonization initiatives aim to reduce dual certification burdens for export-oriented manufacturers.
South Korea
MFDS medical device approval pathways and domestic semiconductor foundry capacity attract CMOS sensor design houses. Memory and display panel fabrication infrastructure in Gyeonggi Province repurposes deposition equipment for X-ray detector backplane production. Seoul Capital Area diagnostic imaging OEMs source locally to satisfy hospital procurement localization preferences.
CMOS X-Ray Detectors Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers seek to bridge gaps between scintillator sourcing, readout electronics design, and end-market certification. The vendor base stratifies into three tiers: vertically integrated conglomerates with captive foundry capacity, specialized detector developers reliant on fabless manufacturing models, and regional system integrators serving single-country procurement channels. Two archetypes define competitive positioning: technology licensors leveraging proprietary photodiode architectures, and scale-driven assemblers competing on manufacturing cost. Capacity expansion and backward integration into scintillator materials represent the dominant competitive moves.
Among diversified imaging conglomerates, Varex Imaging Corporation and Canon Inc. exemplify scale-driven positioning through multi-segment portfolio breadth. Hamamatsu Photonics K.K. anchors the specialist tier with concentrated expertise in photodiode array architectures. These three entities collectively represent the competitive spectrum from component-level specialization to end-system integration.
| Leading Market Players |
|---|
| Varex Imaging Corporation |
| Hamamatsu Photonics K.K. |
| Agfa-Gevaert Group |
| Carestream Dental LLC |
| Teledyne Digital Imaging Inc. |
| Ziehm Imaging GmbH |
| Shimadzu Scientific Instruments |
| Thales Group |
| Canon Inc. |
| Others |
Cost & Logistics Intelligence
Performance-grade bifurcation between FDA 510(k)-cleared medical systems and uncertified industrial units manifests in divergent margin structures and sourcing strategies across detector architectures. Premium tiers command captive scintillator supply chains while commodity segments face spot-market volatility in cesium iodide procurement.
Pricing Analysis
Distributor margins of 15-25 percent separate direct-to-OEM contract pricing from hospital procurement through group purchasing organizations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status, scintillator material grade, and bundled service attach rates. Pricing pressure stems from outpatient diagnostic chains unbundling equipment from long-term maintenance contracts. Industrial inspection services exhibit highest price sensitivity due to volume procurement and shorter replacement cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Germany's precision medical device corridor and North American hospital networks, while specialized distributors serve veterinary and dental clinic segments. Manufacturing concentrates in Germany, Japan, and China's Yangtze River Delta for thin-film transistor backplanes and photodiode array fabrication. Upstream dependencies include cesium iodide scintillators from specialty chemical producers, cadmium telluride substrates for direct conversion layers, and advanced packaging materials from semiconductor foundries. Single-source vulnerability in scintillator material supply creates cost transmission risk to detector assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are tightening as EU MDR technical documentation requirements and AI-enabled image reconstruction standards elevate performance floors across all detector categories. This late-cycle quality story favors manufacturers with integrated certification capabilities.
For Market Incumbents: Anchor market position through backward integration into scintillator material production and readout electronics design. Varex Imaging Corporation's vertical model across scintillator and photodiode fabrication demonstrates sustainable pricing power. Defend against fabless entrants by accelerating EU MDR certification timelines ahead of notified body capacity constraints. Prioritize capacity expansion in Germany's precision manufacturing corridor to capture outpatient diagnostic chain demand.
For New Entrants and Emerging Players: Capture white-space in veterinary diagnostic imaging and portable security scanning applications where incumbent presence remains limited. Industrial inspection services for semiconductor wafer defect detection offer fastest penetration trajectory due to specification flexibility and shorter qualification cycles. Partner with Yangtze River Delta foundries for thin-film transistor backplane supply to satisfy China NMPA localization requirements through joint venture structures.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification burdens and EU MDR compliance costs exceed standalone profitability thresholds for sub-scale detector developers. Long-term viability hinges on captive foundry access or exclusive scintillator supply agreements. Target acquisition archetype: fabless detector developers with proprietary photodiode architectures and pending FDA 510(k) clearances. Monitor PMDA approval timeline convergence with FDA pathways as inflection signal for Japan market accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Acceleration | Early certification captures shelf space ahead of twelve-to-eighteen-month competitor delays in Germany. |
| Scintillator Backward Integration | In-house cesium iodide production insulates margin structures from specialty chemical price volatility. |
| Photodiode Array Foundry Partnership | Exclusive access to Hamamatsu-class architectures secures high-resolution veterinary and industrial positioning. |
| China NMPA Localization Joint Venture | Domestic manufacturing partnerships accelerate hospital procurement list inclusion beyond standard foreign timelines. |
| AI-Enabled Software Companion Development | Software-as-medical-device integration creates hardware-software bundling opportunities ahead of regulator convergence. |
Research Approach
Bottom-up diagnostic imaging center and industrial inspection service modeling reconciled against top-down scintillator material and readout electronics supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and semiconductor foundry operations directors combined with secondary validation against FDA 510(k) filings, EU MDR notified body databases, NMPA approval registries, and thin-film transistor trade flow data. Triangulation across demand-side procurement patterns and supply-side capacity announcements ensures measurement consistency.
Historical trendline analysis of flat panel detector and photodiode array shipment volumes established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, conversion technology, application category, and end-user institutional type dimensions. CAGR derivation rested on equipment replacement cycle analysis, regulatory approval pipeline assessment, and foundry capacity expansion announcements. Forecast inputs included EU MDR implementation pace, China import substitution policy intensity, and AI software-hardware integration adoption curves.
Underlying measurement precision varies by segment; FDA-cleared medical systems carry tighter precision than emerging industrial inspection applications due to registration database transparency. Forecasts reflect base assumptions regarding regulatory timeline stability, scintillator material supply continuity, and foundry capacity allocation prioritization. Periodic stress-testing of base assumptions is recommended given PMDA approval track unpredictability and potential scintillator supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Middle East and Africa Image Sensors Market
Imaging
Europe IP Camera Market
Imaging
Pico Projector Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Global Digital Photography Market
Imaging
Digital Microscope Market
Imaging
Video Capture Card Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Digitizer Market
Imaging
Ent Cameras Market
Imaging
Global Digital Binoculars Market
Imaging
Computer Aided Detection Market
Imaging
Global AI in Computer Vision Market
Imaging
Global Cell Imagers Market
Imaging
Video Microscopes Market