
 Smart Water Leak Detector Market | 2026-2036
Smart Water Leak Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Leak Detector Market Analysis
UL-certified leak detection sensitivity tiers are redrawing competitive boundaries in the smart water leak detector market. Honeywell International leverages its building automation heritage to dominate commercial-grade installations with BACnet-integrated systems. Moen Incorporated anchors the residential premium segment through Phyn's machine-learning flow analysis technology.
A smart water leak detector is an electromechanical sensing device that monitors moisture, pressure differentials, or flow anomalies to trigger automated shutoff alerts, typically operating within detection thresholds of 0.5 to 2.0 millimeters of standing water. Its primary purpose is to mitigate structural damage, reduce insurance claims, and conserve water in built environments. Wireless sensors lead residential retrofit adoption due to minimal installation disruption and Wi-Fi mesh compatibility, while smart valves command the highest margin pools through their dual function of detection and autonomous water supply interruption. Monitoring systems are gaining fastest in municipal utilities where centralized dashboarding aggregates district-level leak intelligence.
The U.S. EPA WaterSense program and the EU F-Gas Regulation indirectly shape demand by embedding water efficiency into broader building certification schemes, while Japan's METI promotes IoT-enabled home infrastructure through subsidy frameworks. China's GB standards for smart home interoperability and India's BIS certification for electronic safety create divergent compliance pathways for manufacturers. Stakeholders must weigh regional certification fragmentation against the economies of unified product platforms as deployment scales accelerate.
Market Dynamics
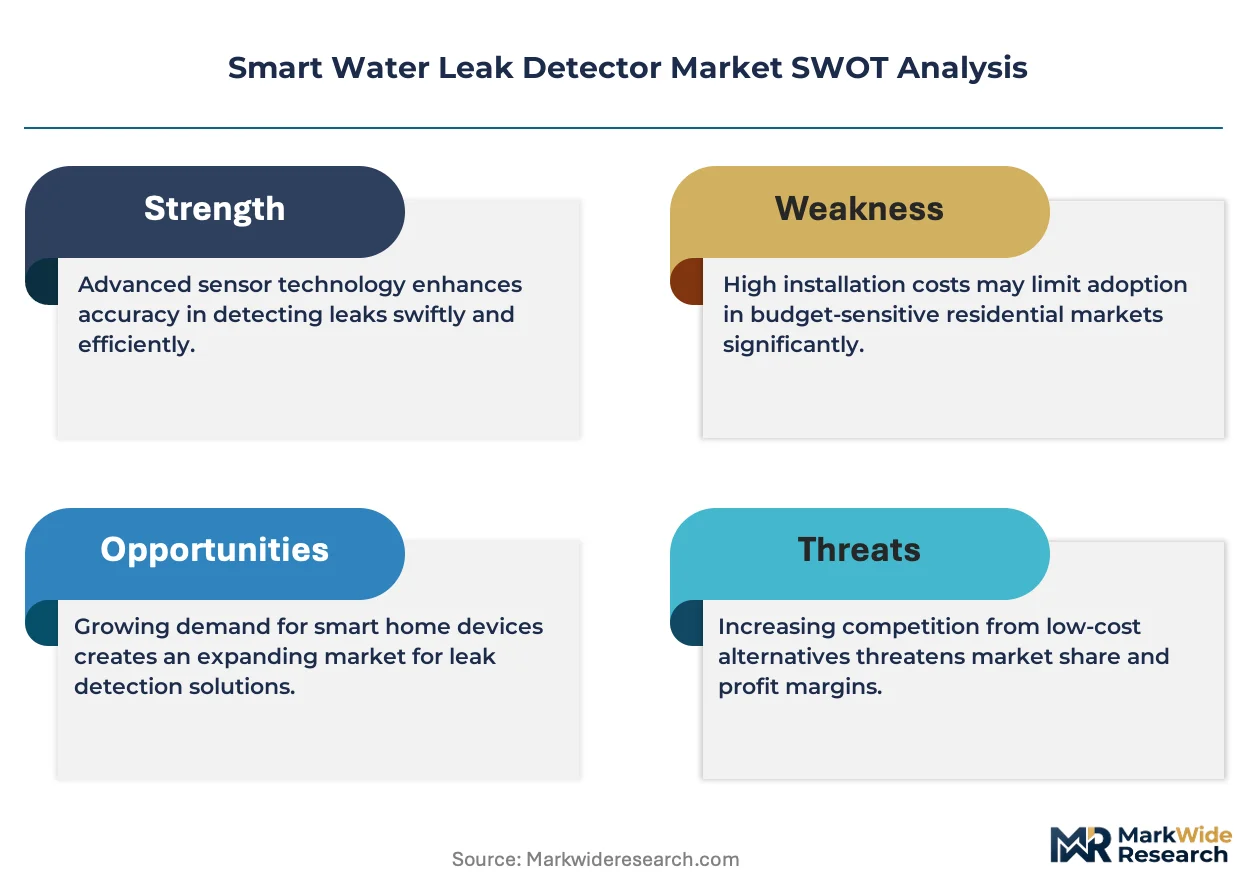
UL-certified detection sensitivity tiers are compressing price premiums as insurers mandate certified installations, forcing manufacturers to absorb certification costs while defending margin pools through autonomous shutoff valve integration.
Growth Catalysts
- EPA WaterSense Mandates:The U.S. EPA WaterSense program embeds leak detection into federal building efficiency standards, compelling new construction and major renovation projects to specify certified systems.
- Machine-Learning Flow Analysis:Advanced algorithms analyzing pressure signatures now distinguish normal usage from micro-leaks, reducing false-positive rates below two percent and accelerating residential retrofit adoption.
- Germany:The EU F-Gas Regulation's building certification requirements are accelerating smart valve installations in commercial properties seeking operational carbon reductions.
Market Restraints
- Semiconductor Component Volatility:MEMS pressure sensors and low-power Wi-Fi chipsets face supply concentration in Taiwan, exposing manufacturers to input cost swings and allocation delays.
- Interoperability Fragmentation:China's GB standards for smart home devices diverge from Thread/Zigbee protocols dominant in North America, forcing dual-SKU strategies that erode scale economies.
- Battery Chemistry Limitations:Lithium-thionyl chloride cells in submersible sensors degrade in high-humidity environments, constraining deployment in tropical climates and requiring premature replacement cycles.
Strategic Opportunities
- India:BIS certification requirements for electronic safety devices are creating first-mover advantages for manufacturers establishing local testing partnerships ahead of enforcement tightening.
- Municipal Utility Aggregation:District-level leak intelligence platforms enable utilities to monetize anonymized flow data, opening recurring revenue streams beyond hardware sales.
- Japan METI Subsidies:IoT-enabled home infrastructure incentives cover thirty to fifty percent of installed costs for elderly households, accelerating penetration in the demographic most vulnerable to water damage.
Industry Challenges
- Legacy Plumbing Integration:Corroded galvanized steel pipes in pre-1980s U.S. housing stock lack standard valve interfaces, requiring costly plumber dispatches that erode direct-to-consumer margin structures.
- Certification Timeline Compression:UL 521 and EN 14604 testing protocols demand six-to-nine month validation cycles, delaying product launches behind competitor announcements and compressing effective sales windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Leak Detector Market |
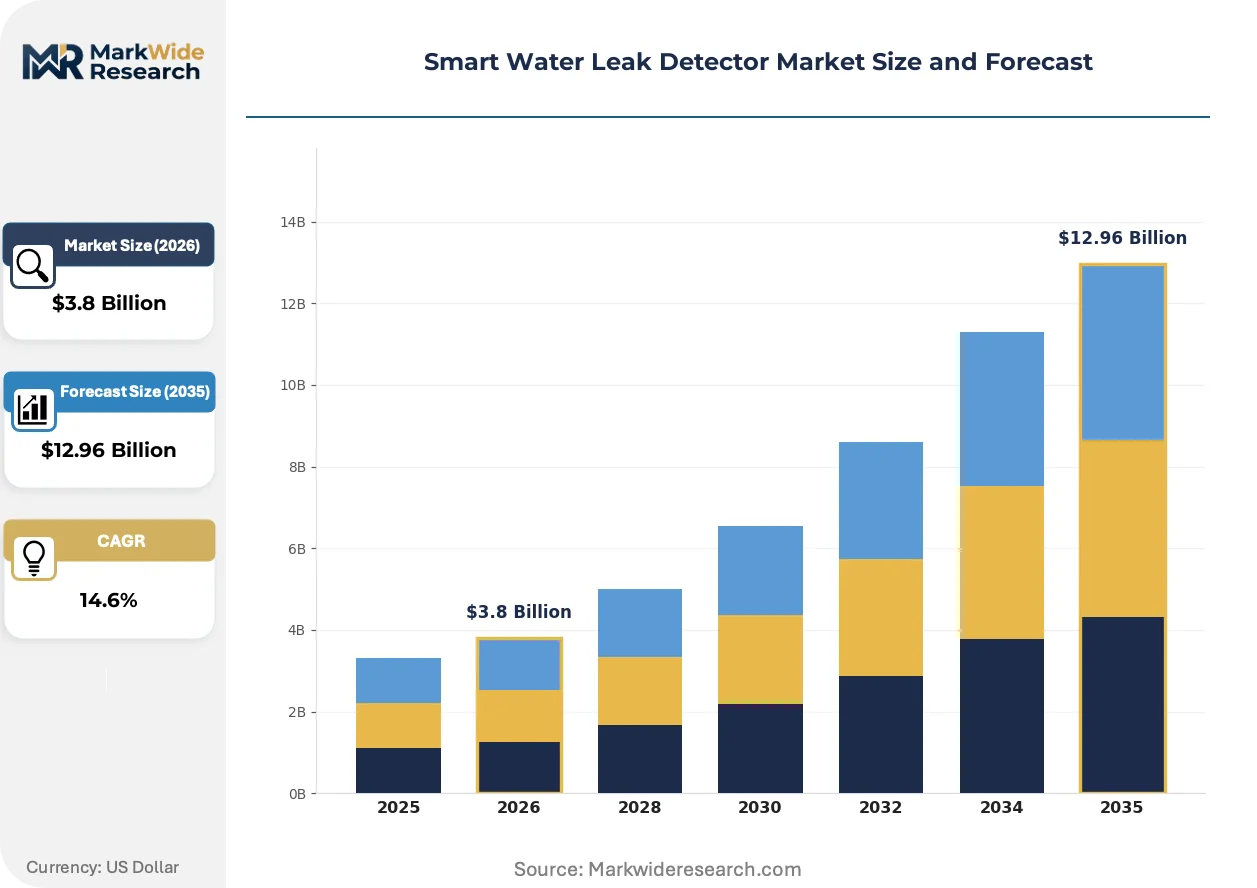
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwired Sensors, Wireless Sensors, Smart Valves, Monitoring Systems Technology: Ultrasonic, Capacitive, Thermal, Optical End User: Residential Buildings, Commercial Spaces, Industrial Facilities, Municipal Utilities Installation Type: Surface Mount, In-wall, Portable, Integrated |
| Companies Covered | Flume, Honeywell International, Moen Incorporated, Ring (Amazon), Wasserstein, Phyn (Kohler), Watts Water Technologies, Govee, Eve Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Leak Detector Market Emerging Trajectories
Acoustic signature analysis is supplanting moisture-contact sensors as the primary detection modality, enabling non-invasive installation and whole-home coverage from single mounting points. This shift is compressing hardware BOM costs while elevating software and cloud analytics as the primary value capture layer.
Ultrasonic flow monitoring is supplanting mechanical turbine meters in premium residential installations. Honeywell and Moen tier suppliers are embedding time-of-flight sensors directly into main shutoff valves, eliminating the need for distributed point sensors. This consolidation is supplanting multi-node wireless mesh architectures with centralized single-point detection, reducing consumer configuration complexity and installer labor hours.
The EU F-Gas Regulation's building performance standards are mandating continuous leak monitoring in commercial refrigeration and HVAC systems. Germany's KBA and France's CNIL are jointly enforcing data localization requirements for flow telemetry, forcing cloud architecture redesigns. Commercial property managers in Düsseldorf and Lyon are responding by specifying on-premise gateway solutions that filter sensitive data before transmission.
Insurance carriers are unbundling leak detection from bundled home policies, creating standalone parametric products that trigger automatic payouts upon verified sensor alerts. This disintermediates traditional claims adjusters and compresses settlement timelines from weeks to hours. The model is gaining traction most visibly in Florida and Texas coastal counties where water damage severity drives premium volatility.
Smart Water Leak Detector Market Segmentation
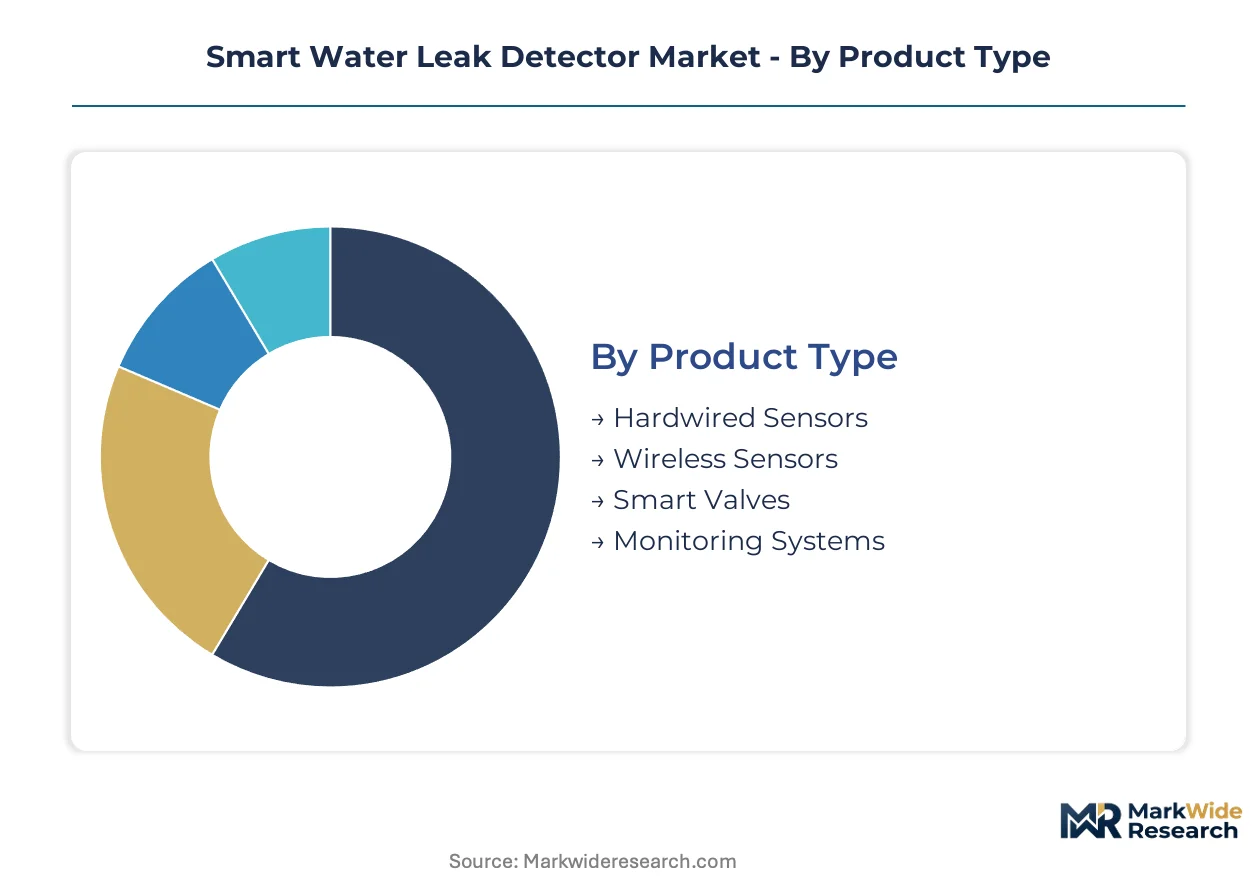
Segmentation in the smart water leak detector market reveals how hardware commoditization and software value capture are splitting margin pools unevenly across product architectures. Manufacturers must align R&D investment with the specific compliance and integration requirements of each segment cluster.
Product Type:
Smart valves command the highest margin pools through their dual function of detection and autonomous water supply interruption, while wireless sensors dominate unit volume in residential retrofit channels.
- Hardwired Sensors:Permanent electrical connections deliver continuous power for high-sensitivity monitoring in commercial basements and mechanical rooms. Demand clusters in Germany and Japan where building codes mandate hardwired fire and leak safety systems in structures above three stories.
- Wireless Sensors:Battery-operated units with Wi-Fi mesh compatibility enable rapid deployment without electrical permits. Residential retrofit adoption in the United States concentrates here as homeowners seek insurance premium reductions with minimal installation disruption.
- Smart Valves:Motorized shutoff mechanisms integrated with flow analysis algorithms.
- Monitoring Systems:Centralized dashboard platforms aggregating multiple sensor inputs.
Wireless sensors hold installed capacity. Smart valves are rotating up the share rankings.
Technology:
Acoustic and ultrasonic modalities are displacing contact-based detection as the primary value layer shifts toward software analytics and cloud telemetry.
- Ultrasonic:Time-of-flight sensors measure water velocity without mechanical intrusion, enabling whole-home coverage from single mounting points. Moen and Honeywell tier suppliers embed these directly into main shutoff valves, eliminating distributed node architectures and reducing installer labor hours in premium residential installations.
- Capacitive:Electrode arrays detect moisture through dielectric constant changes, offering sub-millimeter sensitivity tiers. Industrial facilities in Japan specify capacitive arrays for chemical processing environments where corrosion-resistant housings are mandatory under METI subsidy frameworks.
- Thermal:Infrared temperature differential detection for identifying cold-water line condensation.
- Optical:LED-based refractive index sensing for clear liquid discrimination.
Ultrasonic technology holds installed capacity. Capacitive sensing is rotating up the share rankings.
End User:
Municipal utilities generate the steepest expansion trajectory for monitoring systems as district-level leak intelligence platforms monetize anonymized flow data beyond hardware sales.
- Residential Buildings:Single-family and multi-family dwellings drive volume through insurance-mandated installations and smart home integration. The U.S. EPA WaterSense program embeds leak detection into federal building efficiency standards, compelling new construction specifications in states with aging plumbing infrastructure.
- Commercial Spaces:Office buildings, retail, and hospitality properties prioritize BACnet-integrated systems for facility management consolidation. Germany's EU F-Gas Regulation compliance accelerates smart valve installations in commercial refrigeration and HVAC systems seeking operational carbon reductions.
- Industrial Facilities:Manufacturing plants and chemical processing sites requiring explosion-rated enclosures.
- Municipal Utilities:Water distribution network monitoring with centralized analytics.
Residential buildings hold installed capacity. Municipal utilities are rotating up the share rankings.
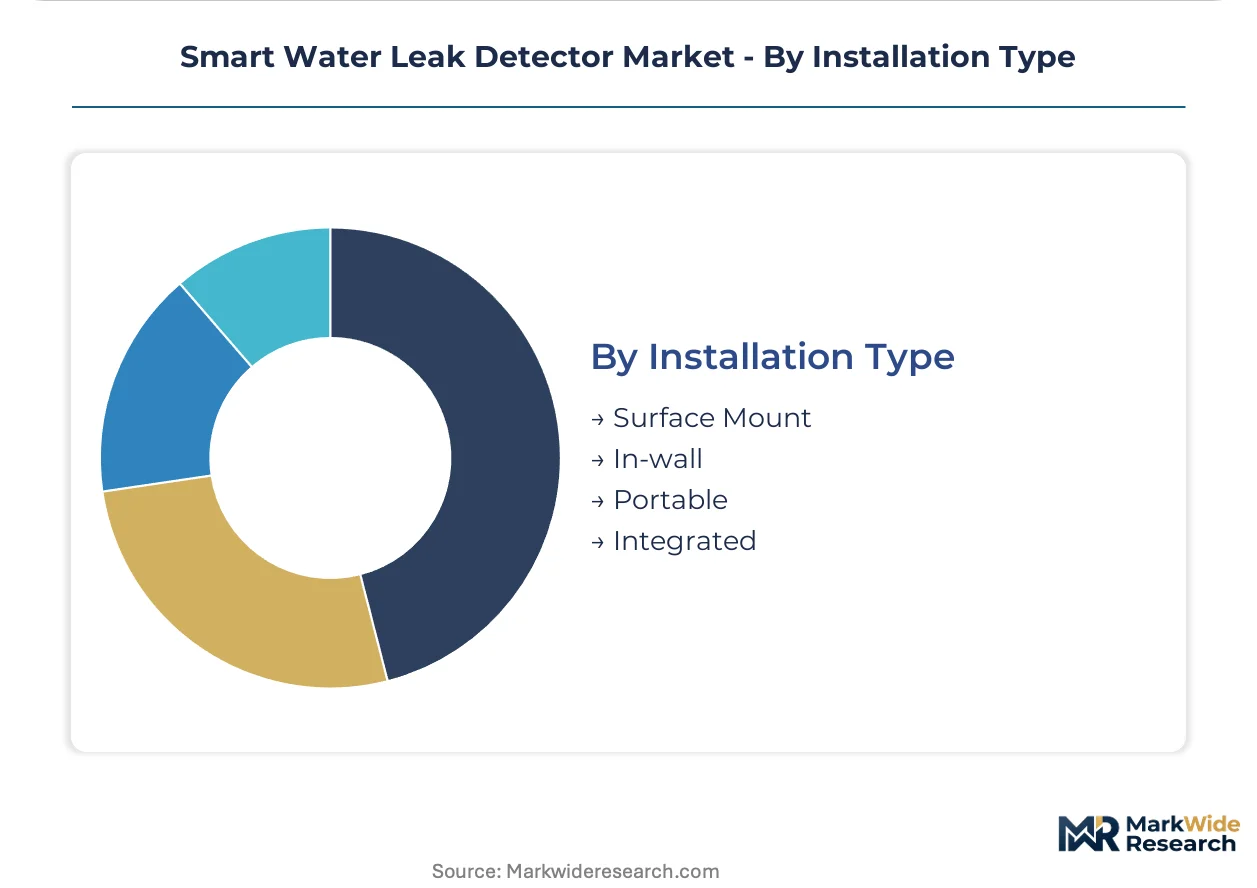
Installation Type:
Surface mount configurations dominate cost-sensitive channels while integrated installations capture premium pricing through invisible aesthetic compliance.
- Surface Mount:Adhesive or screw-fixed placement on floors, walls, or ceilings enables rapid deployment without construction permits. Demand concentrates in the United States for retrofit applications where homeowner self-installation avoids plumber dispatch costs.
- In-wall:Concealed placement during new construction or major renovation integrates sensors permanently into building infrastructure. Japan's METI subsidies for IoT-enabled home infrastructure accelerate in-wall specifications in elderly household renovations where aesthetic discretion is prioritized.
- Portable:Battery-powered standalone units for temporary or rental property applications.
- Integrated:Factory-embedded detection within appliances, fixtures, or building management systems.
Surface mount holds installed capacity. In-wall is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of MEMS pressure sensors and low-power Wi-Fi chipsets concentrates in Taiwan, exposing smart water leak detector producers to input cost volatility and allocation delays. Demand clusters in the United States, Germany, and Japan where aging plumbing infrastructure and smart home penetration converge. Regulatory mandates in each geography are accelerating installation requirements through distinct compliance pathways.
United States
Homeowners seeking insurance premium reductions drive residential retrofit adoption through Wi-Fi mesh-compatible wireless sensors. The EPA WaterSense program embeds leak detection into federal building efficiency standards, compelling new construction specifications. Florida and Texas coastal counties lead parametric insurance product deployment where water damage severity drives premium volatility.
Germany
Commercial properties seeking operational carbon reductions accelerate smart valve installations in refrigeration and HVAC systems. The EU F-Gas Regulation mandates continuous leak monitoring in commercial building certification schemes. Düsseldorf property managers specify on-premise gateway solutions filtering sensitive flow data before cloud transmission under joint KBA and CNIL enforcement.
Japan
Elderly households vulnerable to water damage dominate residential demand through METI subsidy frameworks covering thirty to fifty percent of installed costs. METI promotes IoT-enabled home infrastructure through dedicated subsidy programs. Nagoya industrial clusters specify capacitive sensor arrays for chemical processing environments requiring corrosion-resistant housings.
India
First-mover advantages accrue to manufacturers establishing local testing partnerships ahead of BIS certification enforcement tightening for electronic safety devices. BIS certification requirements create divergent compliance pathways from North American and European standards. Maharashtra and Gujarat industrial corridors concentrate assembly operations for cost-optimized wireless sensor production.
China
Smart home interoperability mandates under GB standards force dual-SKU strategies eroding scale economies for multinational manufacturers. GB standards diverge from Thread/Zigbee protocols dominant in North America, fragmenting product platforms. Yangtze River Delta electronics manufacturing clusters supply MEMS components to regional detector assemblers serving domestic retrofit demand.
Smart Water Leak Detector Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the smart water leak detector market. Premium-tier vendors dominate autonomous shutoff valve integration with machine-learning flow analysis, while mass-market specialists capture wireless sensor volume through Wi-Fi mesh compatibility. Three archetypes define competitive positioning: building automation incumbents with BACnet heritage, residential plumbing brands with consumer channel access, and consumer electronics platforms with smart home ecosystem integration. Dominant competitive moves include strategic partnerships with insurance carriers for certified installation mandates and geographic expansion through regional certification pre-positioning.
Within the building automation tier, Honeywell International exemplifies commercial-grade system integration. Among residential plumbing specialists, Moen Incorporated and Phyn occupy positions anchoring premium flow analysis technology. At the consumer electronics end, Ring represents smart home ecosystem integration through parent-platform distribution scale. These three archetypes illustrate how certification compliance, channel relationships, and software analytics capabilities separate margin capture from hardware commoditization.
| Leading Market Players |
|---|
| Flume |
| Honeywell International |
| Moen Incorporated |
| Ring (Amazon) |
| Wasserstein |
| Phyn (Kohler) |
| Watts Water Technologies |
| Govee |
| Eve Systems |
| Others |
Supply Flow & Price Mechanics
Acoustic signature analysis supplanting moisture-contact sensors simultaneously shifts manufacturing gravity toward Taiwan's MEMS foundries and compresses hardware BOM costs, forcing manufacturers to capture value through software subscriptions rather than component markups.
Pricing Analysis
The EPA WaterSense program dictates the pricing tier structure across the smart water leak detector market, segmenting certified installations from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects UL certification grade and autonomous shutoff valve integration depth. Cost compression in the wireless sensor tier intensifies because insurer-mandated certification absorbs margin, while commercial buyers with BACnet integration needs show lowest price sensitivity.
Supply Chain Analysis
Inventory buffers for MEMS pressure sensors and low-power Wi-Fi chipsets stretch to six months as allocation delays ripple from Taiwan's foundry concentration. Taiwan, South Korea, and China anchor component supply, with lithium-thionyl chloride cells and corrosion-resistant housings feeding from Japanese chemical processors. Single-source vulnerability in MEMS fabrication exposes manufacturers to input cost swings. Distribution runs through building automation integrators in commercial channels and direct-to-consumer platforms in residential retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around insurance carriers and municipal utilities, compressing hardware margins while elevating software analytics and data monetization as sustainable value capture layers.
For Market Incumbents: Secure UL certification pre-positioning ahead of enforcement tightening in India and China, insulating margin pools from emerging entrants lacking testing infrastructure. Deepen upstream control over MEMS sensor supply through exclusive foundry partnerships, countering Taiwan allocation volatility. Anchor recurring revenue through municipal utility data aggregation platforms before competitor dashboard consolidation accelerates. For New Entrants and Emerging Players: Differentiate on acoustic signature analysis algorithms that reduce false-positive rates below incumbent benchmarks, targeting residential retrofit channels where installer labor cost sensitivity runs highest. Exploit white-space in India's pre-enforcement BIS certification window through local testing partnerships. Pursue parametric insurance carrier co-development agreements as primary go-to-market channel, bypassing traditional retail distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building automation specialists seeking platform consolidation to compete with Honeywell's BACnet heritage. Five-to-ten year viability hinges on software analytics capabilities and insurance carrier certification relationships rather than hardware scale. Watch for inflection signals in municipal utility RFP volumes for district-level leak intelligence platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Algorithm Development | Phyn's flow analysis technology demonstrates software value capture supplanting hardware margins in premium residential. |
| Insurance Carrier Partnership | Parametric product unbundling in Florida and Texas coastal counties compresses settlement timelines from weeks to hours. |
| Regional Certification Pre-Positioning | BIS local testing partnerships in Maharashtra and Gujarat secure first-mover advantage ahead of enforcement tightening. |
| Municipal Utility Data Platform | District-level leak intelligence monetizes anonymized flow telemetry beyond hardware sales in Germany and Japan. |
| Acoustic Sensor Architecture Shift | Non-invasive installation from single mounting points reduces consumer configuration complexity and installer labor hours. |
Methodological Framework
A standing panel of smart home platform engineers, insurance risk modelers, municipal utility planning officers, and building automation integrators provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from EPA WaterSense program documentation, METI subsidy framework filings, EU F-Gas Regulation compliance databases, and Taiwan semiconductor trade statistics. Bottom-up sensor shipment aggregation and top-down building stock penetration estimates were triangulated against regulatory mandate timelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture, detection modality, end-user category, and installation type alongside regional regulatory cluster. CAGRs were derived from installed base growth curves and replacement cycle assumptions, with machine-learning adoption rates and insurance mandate penetration serving as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable MEMS supply allocation and continued EPA WaterSense program expansion; material deviation in Taiwan geopolitical conditions or regulatory enforcement timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Gas Sensors Market
Detection and Regulation Devices
Asia-Pacific Trace Detection Screening Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Constant Current Regulator Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Global Inflation Device Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Moisture Detection Stickers Market