
 APAC Die Attach Equipment Market | 2026-2036
APAC Die Attach Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Die Attach Equipment Market Outlook
Copper wire bonding is shifting from gold interconnects across advanced packaging lines, compressing material costs while demanding tighter thermal control in attach equipment. ASM Pacific Technology Limited leverages its integrated equipment portfolio to anchor high-volume OSAT relationships across Southeast Asia. Shinkawa Ltd. specializes in precision bonding heads that sustain sub-micron placement accuracy for stacked die configurations. Panasonic Corporation dominates the flip-chip attach segment through its control of thermal compression platform architectures.
Die attach equipment encompasses precision placement systems that bond semiconductor dies to substrates using force, heat, and sometimes ultrasonic energy, with placement accuracy typically below 10 micrometers and throughput exceeding 10,000 units per hour for high-end systems. These machines serve as the critical bridge between wafer fabrication and final package assembly, determining electrical connectivity, thermal dissipation, and mechanical reliability of finished devices. Automatic attach systems command the largest equipment spend due to labor cost pressures in Taiwan and South Korea, while flip-chip attach platforms represent the fastest-expanding technology category driven by 2.5D and 3D packaging adoption for AI accelerators. Adhesive bonding retains margin strength in automotive radar and power module applications where silver sintering compatibility determines supplier selection.
China's MIIT enforces GB standards on semiconductor equipment energy efficiency that restrict import eligibility for legacy thermal platforms, while Japan's METI coordinates JIS certification pathways that govern equipment acceptance at domestic IDM facilities. South Korea's MFDS-aligned industrial safety frameworks add compliance layers for bonding material handling subsystems, particularly around lead-free solder paste formulations. Stakeholders must weigh regulatory divergence against platform standardization economics when configuring regional service and spare parts networks.
Market Dynamics
Copper wire bonding migration from gold interconnects is compressing material costs while demanding tighter thermal control specifications across attach equipment platforms. This metallurgical shift forces OSATs to recalibrate force-heat-ultrasonic parameters for oxide-free copper interfaces.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's GB energy-efficiency standards restrict import eligibility for legacy thermal platforms, accelerating replacement cycles at Yangtze River Delta packaging facilities.
- AI Accelerator Packaging:2.5D and 3D integration for high-bandwidth memory stacks is pulling flip-chip attach capacity expansion across Taiwan and South Korea.
- Silver Sintering Compatibility:Automotive radar and power module manufacturers specify adhesive bonding platforms capable of high-temperature interconnects for electrified drivetrains.
Market Restraints
- Precision Component Supply Concentration:Sub-micron bonding heads and thermal compression actuators rely heavily on Japanese precision machining supply chains.
- Input Cost Volatility:High-purity silver paste and specialized ceramic substrates for sintering applications face price fluctuations tied to precious metals markets.
- Technical Limitation in Legacy Retrofit:Older epoxy die-attach lines cannot achieve placement accuracy below 15 micrometers required for stacked memory configurations.
Strategic Opportunities
- Vietnam OSAT Greenfield Buildouts:Samsung and Intel supplier ecosystems are establishing captive packaging capacity outside traditional Taiwan-South Korea corridors.
- India PLI Scheme Incentives:Semiconductor manufacturing subsidies under the country's production-linked incentive framework attract attach equipment for domestic assembly-to-test facilities.
- Thermal Compression-Epoxy Hybrid Platforms:Convergence of force-controlled compression with advanced epoxy dispensing addresses heterogeneous integration for chiplets.
Industry Challenges
- Metrology Technician Scarcity:Sub-micron placement verification and thermal profile calibration require specialized skills concentrated in Taiwan and Japan.
- Multi-Jurisdiction Certification Timelines:MFDS-aligned industrial safety frameworks for South Korean facilities add bonding material handling compliance layers distinct from JIS or GB pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Die Attach Equipment Market |
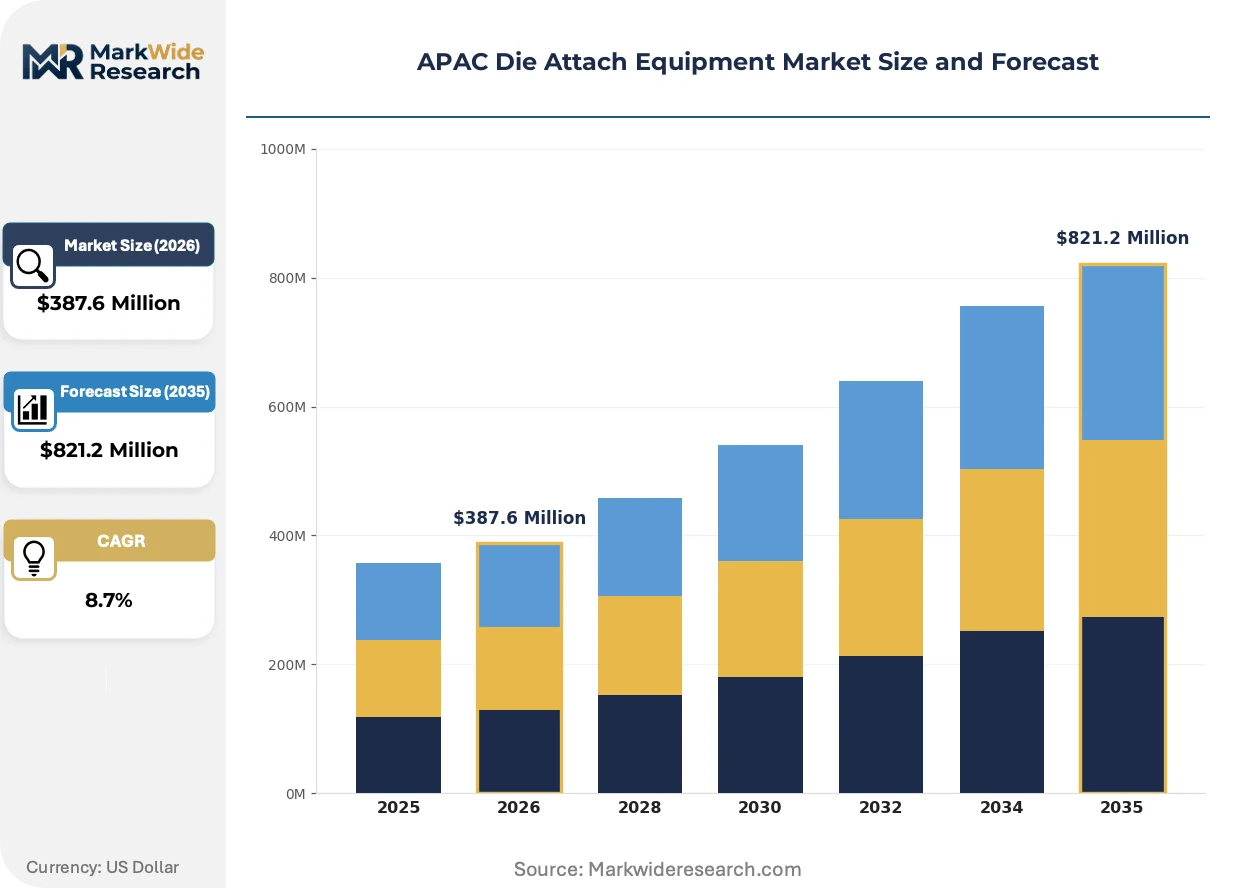
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Attach, Automatic Attach, Semi-Automatic Attach, Flip-Chip Attach Technology: Thermal Compression, Eutectic Bonding, Adhesive Bonding, Laser Bonding End User: Consumer Electronics, Automotive, Telecommunications, Industrial Installation Type: On-Premises, Integrated Solutions, Standalone Systems, Modular Setup |
| Companies Covered | ASM Pacific Technology Limited, Shinkawa Ltd., Palomar Technologies, Inc., Panasonic Corporation, Be Semiconductor Industries N.V., Kulicke and Soffa Industries, Inc., Fasford Technology Co Ltd., Toray Engineering Co. Ltd., MicroAssembly Technologies, Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Die Attach Equipment Market Strategic Shifts
Thermal management architectures and bonding process control systems are converging to address heterogeneous integration complexity. Equipment vendors are reconfiguring platform modularity to serve both high-volume memory packaging and low-mix automotive qualification runs.
Hybrid thermal compression bonding is modularizing around swappable force-heat-ultrasonic subsystems that accommodate both solder and sintering paste chemistries. OSATs in Taiwan are adopting these reconfigurable platforms to compress capital deployment across multiple product generations. The technology is modularizing supplier relationships toward subsystem specialists rather than integrated equipment houses.
China's MIIT GB standards on semiconductor equipment energy efficiency are disqualifying imported legacy thermal platforms from state-backed facility tenders. Domestic packaging houses in the Yangtze River Delta cluster are responding by specifying attach equipment with regenerative thermal systems and variable-frequency drive compressors. South Korean IDM facilities face parallel pressure as METI-coordinated technical dialogues align JIS efficiency benchmarks with Chinese thresholds.
After-sales service unbundling is fragmenting traditional equipment procurement models across Southeast Asian OSATs. Buyers are separating hardware acquisition from multi-year maintenance contracts, instead sourcing spare parts and field engineering through regional third-party service networks. This pattern concentrates most visibly in Malaysia and Vietnam where packaging capacity expansion outruns vendor direct service infrastructure.
APAC Die Attach Equipment Market Segmentation
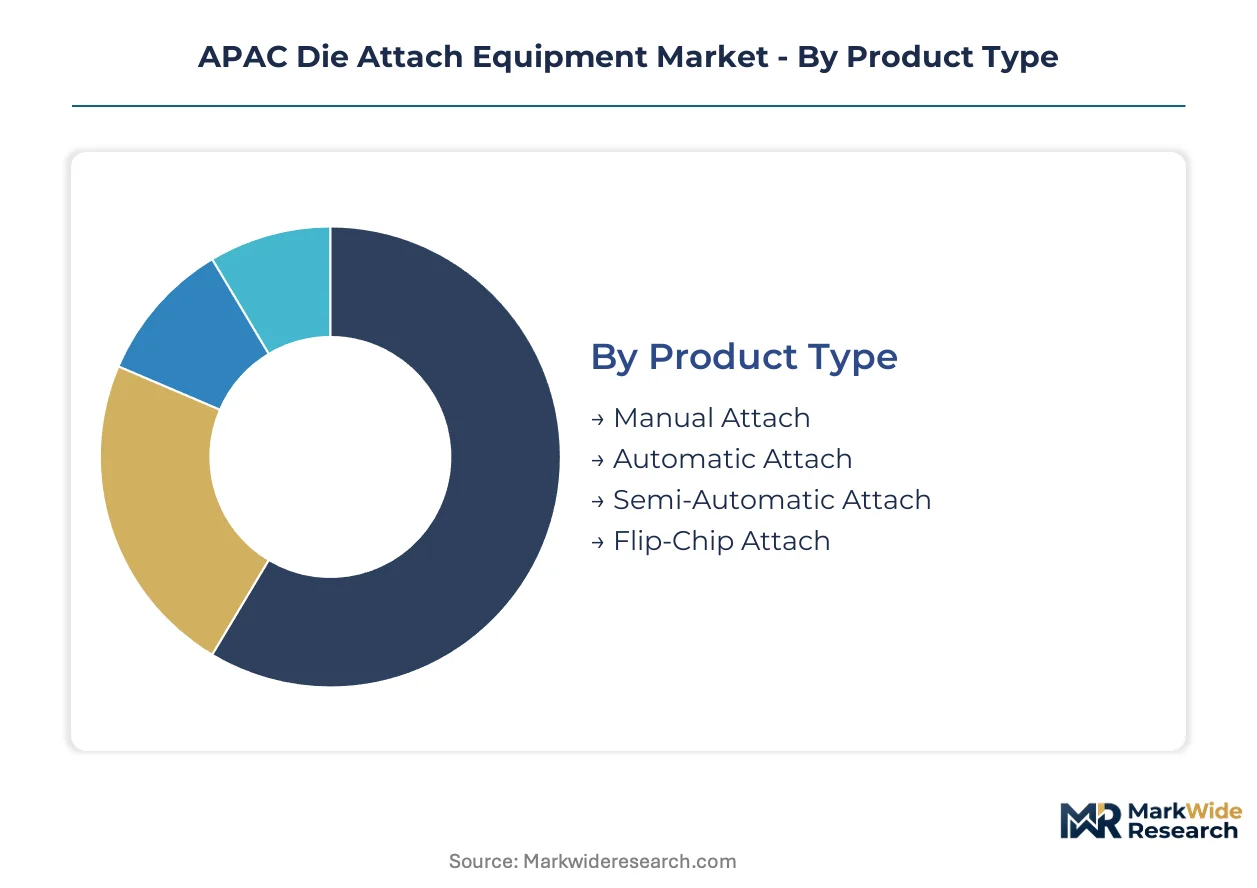
Die attach equipment segmentation in APAC reflects divergent technology maturities across Taiwan's high-volume OSATs and China's emerging packaging clusters. Equipment specifications vary sharply by end-use thermal requirements and regulatory compliance tiers.
Product Type:
Thermal profile precision and throughput specifications differentiate equipment categories across packaging house capital budgets.
- Automatic Attach:Systems achieve placement accuracy below 10 micrometers with throughput exceeding 10,000 units per hour. Taiwan and South Korean OSATs deploy these platforms for memory device packaging where labor cost pressures dominate procurement decisions.
- Flip-Chip Attach:Thermal compression architectures enable 2.5D and 3D integration for AI accelerator packaging. South Korean IDM facilities are expanding capacity for high-bandwidth memory stacks, pulling fastest equipment demand in this category.
- Manual Attach:Low-volume prototyping and legacy line maintenance in smaller Chinese OSATs.
- Semi-Automatic Attach:Mid-tier packaging houses in Vietnam balancing automation investment against product mix volatility.
Mature deployment sits with Automatic Attach platforms. Newer deployment is concentrated in Flip-Chip Attach systems.
Technology:
Process thermal budgets and interconnect material compatibility determine technology selection across automotive and consumer applications.
- Thermal Compression:Force-controlled bonding with precise temperature ramp profiles enables solder and sintering paste chemistries. China's MIIT GB energy-efficiency standards are disqualifying legacy thermal platforms, accelerating replacement demand in Yangtze River Delta facilities.
- Adhesive Bonding:Silver sintering compatibility positions these platforms for automotive radar and power module manufacturers. Japanese precision machining supply chains dominate bonding head subsystems for this technology.
- Eutectic Bonding:Gold-tin and gold-silicon interfaces for high-reliability aerospace and defense packaging in select South Korean facilities.
- Laser Bonding:Emerging localized heating for thermally sensitive heterogeneous integration in Taiwan's advanced packaging R&D lines.
Adhesive Bonding retains margin strength in automotive qualification. Thermal Compression is expanding most quickly under efficiency mandate pressure.
End User:
Application thermal cycling requirements and reliability standards segment demand across equipment specification tiers.
- Consumer Electronics:Smartphone and wearable packaging drives highest equipment volume with compressed placement tolerances. Taiwan OSATs serving Apple and Samsung supplier ecosystems anchor this demand.
- Automotive:Radar module and power electronics packaging specify silver sintering-capable adhesive bonding platforms. China's electrified drivetrain manufacturers are upgrading Yangtze River Delta assembly lines for AEC-Q100 compliance.
- Telecommunications:Baseband processor and optical transceiver packaging in South Korean IDM captive facilities.
- Industrial:Motor drive and power supply module assembly with extended temperature range requirements.
Consumer Electronics absorbs the largest equipment spend. Automotive represents the steepest expansion trajectory as electrification accelerates.
Installation Type:
Capital deployment flexibility and facility integration complexity shape procurement patterns across greenfield and brownfield sites.
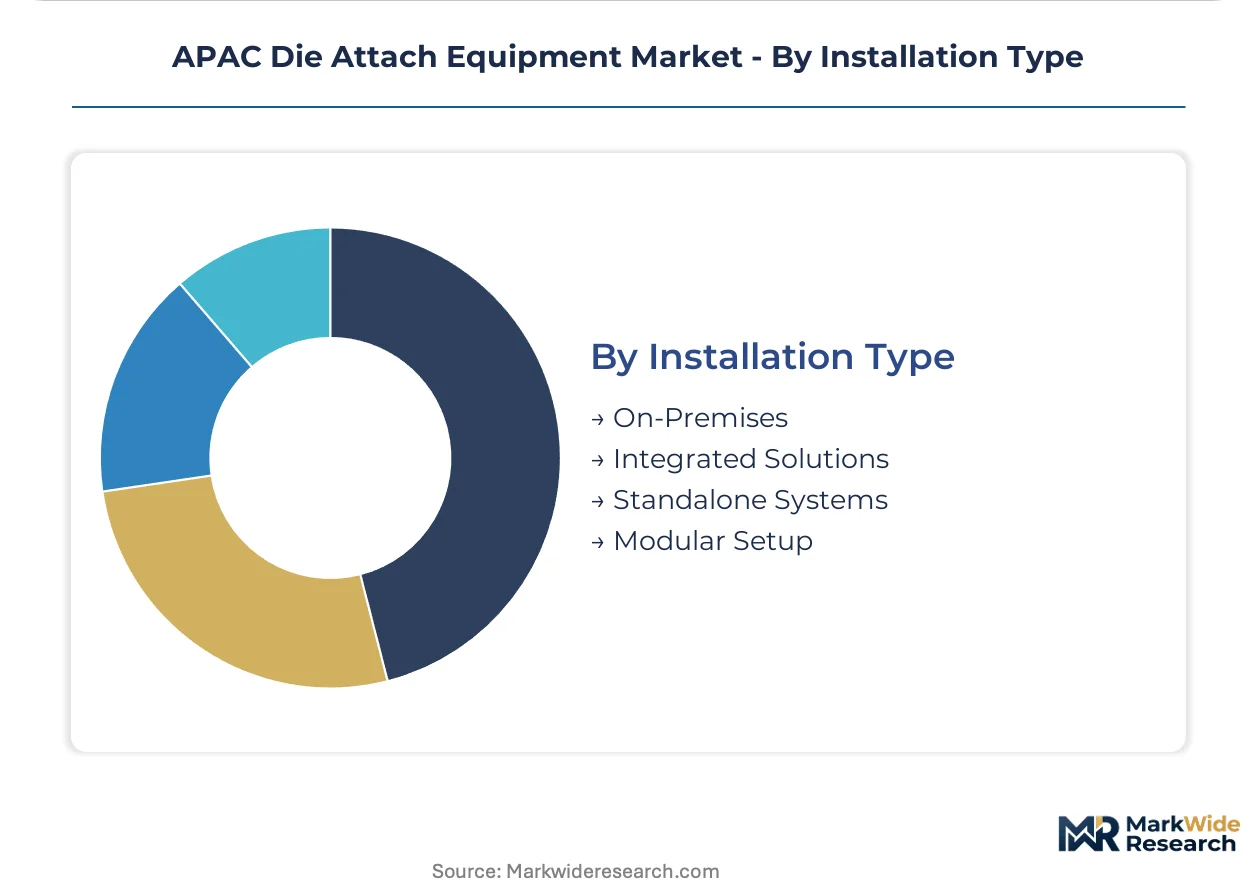
- Standalone Systems:Discrete equipment purchases dominate Vietnam and India greenfield buildouts where OSATs unbundle hardware from service contracts. Malaysia's packaging capacity expansion outruns vendor direct service infrastructure.
- Modular Setup:Swappable force-heat-ultrasonic subsystems accommodate multiple product generations. Taiwan OSATs favor reconfigurable platforms to compress capital deployment across memory and logic packaging.
- On-Premises:Full facility integration with custom environmental controls in South Korean IDM captive packaging.
- Integrated Solutions:Turnkey lines with bundled metrology and material handling in China's state-backed semiconductor projects.
Standalone Systems dominate Southeast Asian expansion. Modular Setup is gaining share fastest as product mix volatility intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most acutely in China's Yangtze River Delta cluster, where domestic OSATs are upgrading legacy lines. Taiwan and South Korea anchor high-volume capacity for advanced logic and memory devices. Southeast Asian greenfield buildouts in Vietnam and Malaysia are diversifying regional supply chains.
China
Domestic packaging houses in the Yangtze River Delta are replacing legacy thermal platforms under MIIT dual carbon mandates. GB energy-efficiency standards restrict import eligibility for equipment lacking regenerative thermal systems. Shanghai and Suzhou clusters drive replacement demand as state-backed facilities specify variable-frequency drive compressors.
Taiwan
OSATs serving Apple and Samsung supplier ecosystems deploy automatic attach systems for smartphone and wearable packaging. Labor cost pressures dominate procurement decisions for memory device lines. Hsinchu Science Park anchors the highest equipment throughput requirements across the region.
South Korea
IDM captive facilities are expanding flip-chip attach capacity for high-bandwidth memory stacks in AI accelerators. MFDS-aligned industrial safety frameworks add compliance layers for bonding material handling subsystems. Pyeongtaek and Hwaseong clusters concentrate the fastest-expanding technology category.
Japan
Precision machining supply chains for sub-micron bonding heads and thermal compression actuators remain concentrated in domestic industrial corridors. METI coordinates JIS certification pathways governing equipment acceptance at IDM facilities. Nagoya and Osaka regions anchor subsystem specialist networks.
Vietnam
Samsung and Intel supplier ecosystems are establishing captive packaging capacity outside traditional Taiwan-South Korea corridors. Standalone system purchases dominate greenfield buildouts where OSATs unbundle hardware from service contracts. Ho Chi Minh City and Bac Ninh provinces concentrate Malaysia-adjacent expansion.
APAC Die Attach Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated equipment houses commanding premium positioning in high-volume OSAT relationships while subsystem specialists capture margin in precision components. The vendor base organizes around three archetypes: integrated platform providers with full equipment portfolios, precision subsystem specialists focused on bonding heads and thermal actuators, and regional fabricators serving emerging Southeast Asian markets. Consolidation pressure operates through technology licensing partnerships and geographic expansion into Vietnam and India greenfield sites.
Within the integrated platform tier, ASM Pacific Technology Limited and Panasonic Corporation exemplify equipment houses anchoring high-volume relationships across Taiwan and South Korea. Shinkawa Ltd. occupies a position among precision subsystem specialists, with bonding head architectures serving stacked die configurations. These three entities represent the dominant competitive anchors across the region's technology segmentation.
| Leading Market Players |
|---|
| ASM Pacific Technology Limited |
| Shinkawa Ltd. |
| Palomar Technologies, Inc. |
| Panasonic Corporation |
| Be Semiconductor Industries N.V. |
| Kulicke and Soffa Industries, Inc. |
| Fasford Technology Co Ltd. |
| Toray Engineering Co. Ltd. |
| MicroAssembly Technologies, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silver paste commodity benchmarks cascade through die attach equipment supply chains into three distinct pricing tiers, with high-purity sintering materials compressing margins at the premium end while Chinese domestic OSATs force cost transparency in economy configurations. Japan's precision machining supply chains anchor bonding head subsystems, creating geographic rent extraction that Taiwanese equipment houses pass through as certification premiums.
Pricing Analysis
High-volume memory packaging lines absorb equipment at compressed per-unit economics while automotive qualification runs sustain margin strength through silver sintering compatibility premiums. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified thermal compression platforms from GB-compliant domestic alternatives and unbundled Southeast Asian standalone systems. Pricing pressure stems from China's MIIT energy-efficiency mandates disqualifying legacy imports, forcing replacement cycles at distressed asset valuations. OSATs in Vietnam and Malaysia exhibit highest price sensitivity due to greenfield capital constraints, whereas South Korean IDM captive facilities prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Direct-to-OSAT channels handle high-volume demand from Taiwan and South Korean memory packaging houses, while regional third-party service networks capture aftermarket parts distribution in Southeast Asian expansion corridors. Sub-micron bonding heads and thermal compression actuators draw from Japanese precision machining clusters in Nagoya and Osaka, with high-purity silver paste sourcing tethered to precious metals refining capacity in China and South Korea. Single-source vulnerability concentrates in ceramic substrate supply for sintering applications, where Japanese material specialists control critical thermal conductivity specifications. Distribution runs through equipment vendor direct sales for integrated solutions, unbundled hardware procurement for Vietnamese greenfield sites, and subsystem specialist networks for precision component replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT GB energy-efficiency standards function as a cost-of-compliance moat, with regenerative thermal system requirements filtering import eligibility and creating protected domestic replacement demand for certified platform providers.
For Market Incumbents: Deploy subsystem modularization as the primary lever to compress capital deployment cycles across Taiwan OSATs serving volatile memory-to-logic product mixes. Backward integration into precision bonding head machining reduces exposure to Japanese supply chain chokepoints, while JIS-GB dual certification investments defend positioning against emerging Chinese equipment houses capturing state-backed Yangtze River Delta tenders. For New Entrants and Emerging Players: The premium-to-economy price-point gap in thermal compression platforms creates entry space for GB-certified domestic alternatives serving Chinese OSATs excluded from legacy import tenders. Vietnam's Samsung-Intel supplier ecosystem buildouts represent the most penetrable geography, with standalone system procurement patterns favoring unbundled hardware vendors over integrated equipment houses. A subsystem specialist positioning—bonding heads or thermal actuators—bypasses direct competition with ASM Pacific and Panasonic platform portfolios. For Investors and Strategic Acquirers: The window for entry favors precision subsystem specialists with JIS-certified manufacturing footprints and established Taiwanese OSAT relationships. Long-term viability centers on heterogeneous integration complexity sustaining sub-micron placement accuracy premiums across multiple semiconductor packaging generations. Watch for MIIT efficiency standard harmonization with METI benchmarks as the inflection signal compressing regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Subsystem Modularization | Taiwan OSATs adopt swappable force-heat-ultrasonic architectures to compress capital deployment across product generations. |
| Dual Certification Investment | JIS-GB alignment enables equipment acceptance at both South Korean IDM facilities and Chinese state-backed packaging clusters. |
| Regional Service Network Buildout | Third-party field engineering capacity captures unbundled maintenance demand in Vietnam and Malaysia greenfield corridors. |
| Silver Sintering Platform Expansion | Automotive radar and power module qualification runs sustain margin strength through AEC-Q100 compliance premiums. |
| Precision Machining Backward Integration | In-house bonding head production reduces exposure to Japanese supply chain concentration and tariff exposure. |
Study Parameters
SEC filings from Kulicke and Soffa Industries, BE Semiconductor Industries, and ASM Pacific Technology, alongside METI equipment certification databases and MIIT GB standard documentation, formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with OSAT procurement directors, IDM packaging engineers, and precision machining subsystem specialists validated equipment specification trends and replacement cycle timing. Customs data from Taiwan and South Korea, combined with Yangtze River Delta industrial zone investment filings, anchored bottom-up installation base estimates against top-down semiconductor packaging capacity expansion projections.
Historical trendline analysis of equipment procurement patterns across consumer electronics, automotive, and telecommunications packaging verticals established baseline growth trajectories without reliance on single-source disclosures. Segmentation modeling incorporated product type, technology, end-use application, and installation configuration dimensions, with cross-validation against regional regulatory compliance tiers. CAGRs were derived from capacity expansion announcements and capital expenditure disclosures, stress-tested against silver paste price volatility and precision component lead time fluctuations.
Inputs from METI certification pathways and MIIT tender documentation were available through the study window; gaps in real-time Vietnamese greenfield procurement data introduce uncertainty bands around Southeast Asian expansion velocity. Forecasts reflect assumptions regarding heterogeneous integration complexity sustaining sub-micron accuracy premiums and dual carbon mandate enforcement continuity. Periodic stress-testing of base assumptions against bonding material handling safety framework revisions and precious metals market volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Wafer Chucks Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Semiconductor Lithography Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market