
 Global Cell Imagers Market | 2026-2036
Global Cell Imagers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Imagers Market Foresight
Contract research organizations are redrawing demand patterns for cell imagers as pharmaceutical companies outsource early-stage screening. Thermo Fisher Scientific Inc. leverages its integrated reagent-instrument platform to dominate high-throughput workflows. Carl Zeiss AG anchors premium confocal systems through precision optics manufacturing. PerkinElmer Inc. competes on software-driven high-content analytics for phenotypic drug discovery.
Cell imagers are optical instruments that capture quantitative morphological and functional data from biological samples, typically achieving sub-micron resolution through fluorescence or confocal detection for applications including compound profiling and toxicology assessment. Live cell imagers lead product type demand as time-lapse microscopy replaces endpoint assays in immuno-oncology pipelines. Flow cytometry imaging hybrids represent the fastest-growing technology segment, merging single-cell resolution with population statistics. Academic research centers command the largest end-user share, though biotechnology firms concentrate margin pools through subscription service models.
The FDA enforces 21 CFR Part 11 electronic records standards that compel imager vendors to embed audit trails and access controls, while the EMA's MDR framework in Europe demands clinical-grade validation for diagnostic-adjacent instruments. Japan's PMDA applies QMS requirements to in-vitro diagnostic imaging modules, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor how AI-enabled image analysis algorithms trigger new software-as-medical-device classifications across FDA, EMA, and PMDA jurisdictions.
Market Dynamics
Live-cell microscopy is displacing static endpoint assays across immuno-oncology pipelines, forcing vendors to reconfigure hardware-software architectures for continuous time-lapse acquisition rather than single-frame capture.
Growth Catalysts
- 21 CFR Part 11 mandates:FDA electronic records requirements compel pharmaceutical manufacturers to upgrade imaging systems with embedded audit trails and access controls, accelerating replacement cycles in United States-based biopharma R&D facilities.
- Contract research organization outsourcing:Pharmaceutical companies are divesting early-stage screening infrastructure to CROs, creating concentrated demand spikes for high-throughput platforms at multi-site service providers.
- Neuroscience imaging expansion:Academic research centers in Germany and Japan are procuring dedicated live-cell systems for neuronal network mapping, driving specialized configuration demand distinct from standard oncology workflows.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component manufacturers control critical lens and filter supply, exposing imager OEMs to single-source risk and extended lead times for confocal system builds.
- High-content software validation costs:EMA MDR clinical-grade validation requirements impose documentation burdens that extend commercialization timelines for diagnostic-adjacent imaging modules by twelve to eighteen months.
- Flow cytometry substitution threat:Imaging-enhanced flow systems are capturing single-cell analysis budgets previously allocated to standalone imagers, particularly in toxicology screening applications.
Strategic Opportunities
- AI algorithm SaaS monetization:Cloud-based image analysis tools are creating recurring revenue streams independent of hardware sales, with phenotypic drug discovery firms in the United States piloting per-assay pricing models.
- India biotech infrastructure buildout:Government-funded research parks in Hyderabad and Bangalore are equipping new facilities, presenting first-mover advantages for vendors establishing localized service networks.
- Multi-omics integration:Convergence of spatial transcriptomics with high-content imaging is opening workflow bundles that combine morphological and molecular data capture in single instrument footprints.
Industry Challenges
- Computational microscopy talent scarcity:Shortages of specialists trained in both optical physics and machine learning are constraining R&D throughput for AI-enabled image reconstruction algorithms.
- Legacy system interoperability:Biopharma facilities running decade-old microscope platforms face integration friction when connecting modern high-content analyzers to existing laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Imagers Market |
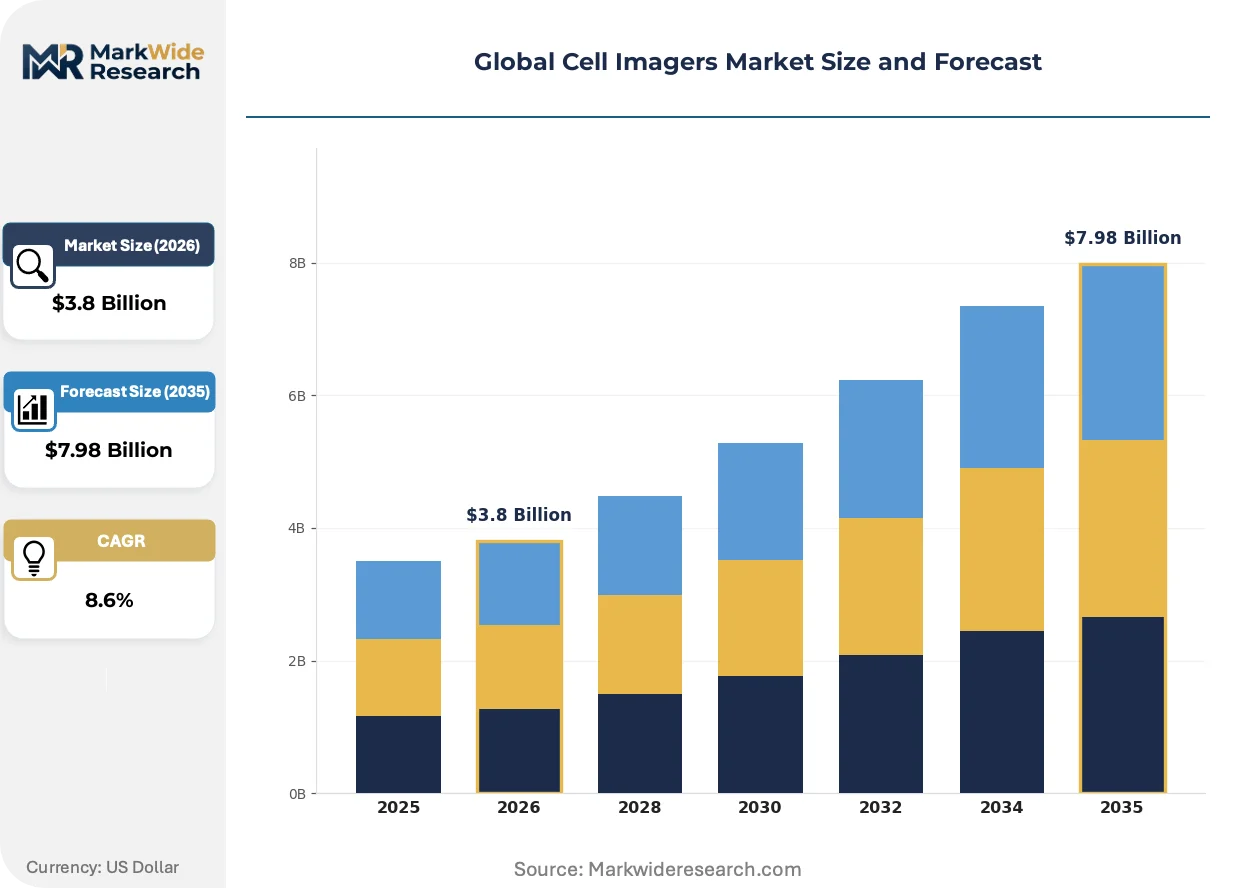
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Content Screening, Fluorescence Imagers, Live Cell Imagers, Confocal Imagers, Microplate Imagers Technology: Confocal Microscopy, Widefield Imaging, Flow Cytometry, Multiphoton Imaging, Brightfield Imaging Application: Drug Discovery, Cancer Research, Neurobiology, Immunology, Cell Viability Analysis End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Centers, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Carl Zeiss AG, PerkinElmer Inc., Leica Microsystems, Olympus Corp., Becton, Dickinson and Co., Bio-Rad Laboratories Inc., Sartorius AG, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Imagers Market Shifts & Advancements
Instrument architectures are fragmenting into modular components as buyers demand flexible upgrade paths rather than monolithic system replacements. Vendors are responding with software-subscription overlays and field-swappable detection modules.
Light-sheet fluorescence microscopy is decomposing the traditional trade-off between imaging speed and phototoxicity in developmental biology applications. Stem cell research institutes in Germany and Japan are adopting these systems for multi-day embryonic imaging without viability loss. The technology is compressing demand for conventional spinning-disk confocal units in longitudinal studies.
EMA MDR software-as-medical-device classifications are triggering re-registration requirements for AI-enabled image analysis algorithms previously treated as research tools. Diagnostic laboratories in France and Switzerland are reassessing vendor qualification protocols to ensure algorithm traceability. This regulatory expansion is favoring established players with dedicated quality management systems over emerging software specialists.
Service unbundling is separating hardware maintenance from application support contracts in high-content screening segments. Biotechnology firms in the United States are negotiating à-la-carte software training and assay development assistance distinct from instrument warranty coverage. This disaggregation is pressuring vendor pricing structures while creating openings for third-party service specialists.
Global Cell Imagers Market Segmentation
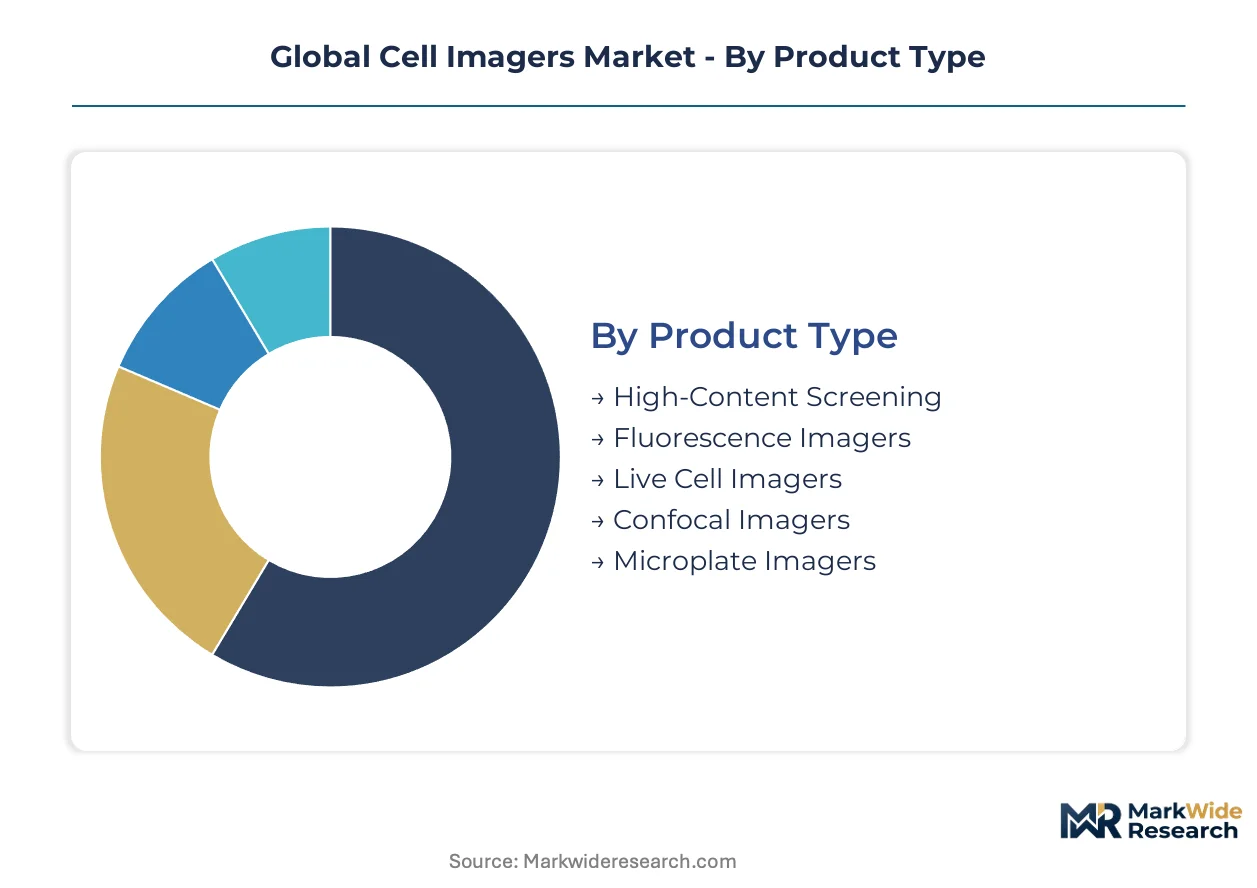
Cell imager procurement patterns diverge sharply across hardware configurations, detection technologies, therapeutic applications, and institutional buyer types. Regulatory compliance requirements from the FDA, EMA, and PMDA create tiered validation burdens that reshape segment economics and replacement cycles.
Product Type:
FDA 21 CFR Part 11 mandates drive divergent upgrade pressures across hardware categories, with electronic records compliance costs concentrating in pharmaceutical-facing configurations.
- Live Cell Imagers:Time-lapse microscopy systems capture longitudinal morphological dynamics without endpoint fixation. Neuroscience institutes in Germany and Japan are procuring dedicated neuronal network mapping configurations that diverge from standard oncology workflows.
- High-Content Screening:Automated multi-well plate analyzers integrate liquid handling with sub-micron resolution detection for compound profiling pipelines. Biopharma R&D clusters in the United States absorb the bulk of throughput demand as CRO outsourcing concentrates procurement at multi-site service providers.
- Fluorescence Imagers:Widefield epifluorescence systems serve entry-level screening applications with lower capital barriers.
- Confocal Imagers:Optical sectioning platforms eliminate out-of-focus blur for thick specimen analysis.
- Microplate Imagers:Dedicated absorbance and luminescence readers handle high-density format quantification.
Live cell imagers handle the majority of throughput; high-content screening is expanding most quickly on share.
Technology:
Cost tier differentiation separates premium optical architectures from accessible widefield alternatives, with subscription software overlays increasingly decoupled from hardware capital expenditure.
- Confocal Microscopy:Pinhole-based optical sectioning achieves sub-micron axial resolution through fluorescence rejection. German and Japanese precision optics manufacturers control critical lens supply, exposing OEMs to single-source risk and extended lead times.
- Flow Cytometry:Imaging-enhanced systems merge single-cell resolution with population statistics. Toxicology screening operations in the United States are redirecting budgets from standalone imagers toward these hybrid platforms.
- Widefield Imaging:Standard epifluorescence and transmitted light configurations dominate academic procurement.
- Multiphoton Imaging:Infrared excitation enables deep-tissue penetration with reduced phototoxicity.
- Brightfield Imaging:Transmitted light microscopy serves basic morphological assessment without fluorescent labeling.
Confocal microscopy commands the installed base; flow cytometry is climbing the fastest on trajectory.
Application:
Customer type concentration varies by therapeutic area, with biotechnology firms driving margin pools through subscription service models in phenotypic drug discovery.
- Drug Discovery:Compound profiling and target validation workflows demand high-throughput quantitative phenotyping. AI-enabled image analysis algorithms are triggering software-as-medical-device reclassifications across FDA, EMA, and PMDA jurisdictions.
- Cancer Research:Immuno-oncology pipelines are displacing static endpoint assays with continuous time-lapse acquisition protocols.
- Neurobiology:Neuronal network mapping requires specialized environmental control for multi-day viability maintenance.
- Immunology:Immune cell interaction dynamics drive demand for high-speed time-lapse configurations.
- Cell Viability Analysis:Cytotoxicity assessment represents a standardized entry application for automated imaging.
Drug discovery anchors volume commitment; neurobiology is gaining share fastest on specialization premiums.
End User:
Volume concentration separates capital-intensive hardware purchasers from recurring service subscribers, with procurement authority shifting toward CRO consolidation.
- Academic Research Centers:Public funding cycles drive capital equipment procurement with extended depreciation horizons. Stem cell research institutes in Germany and Japan are adopting light-sheet fluorescence systems for embryonic imaging without viability loss.
- Contract Research Organizations:Multi-site service providers concentrate demand spikes for high-throughput platforms as pharmaceutical companies divest early-stage screening infrastructure. CROs in the United States are negotiating à-la-carte software training distinct from instrument warranty coverage.
- Pharmaceutical Companies:Internal R&D facilities face legacy system interoperability friction when connecting modern analyzers to existing LIMS.
- Biotechnology Firms:Emerging drug developers pilot per-assay pricing models for cloud-based image analysis tools.
Academic research centers maintain the largest installed footprint; contract research organizations are expanding most quickly on outsourcing momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics manufacturing concentrates in Germany and Japan, creating supply dependencies that reshape procurement patterns for cell imager OEMs worldwide. Biopharma R&D clusters in the United States, Germany, and Japan absorb the majority of high-content screening demand. Regulatory divergence across FDA, EMA, and PMDA jurisdictions creates tiered compliance burdens that advantage established vendors with dedicated quality infrastructure.
United States
Biopharma R&D facilities in Boston and San Francisco drive concentrated demand for high-throughput screening platforms. FDA 21 CFR Part 11 electronic records mandates compel pharmaceutical manufacturers to upgrade imaging systems with embedded audit trails and access controls. Contract research organizations across the United States are negotiating à-la-carte software training contracts distinct from instrument warranty coverage.
Germany
Academic research centers in Heidelberg and Munich are procuring dedicated live-cell systems for neuronal network mapping applications. EMA MDR clinical-grade validation requirements impose documentation burdens that extend commercialization timelines for diagnostic-adjacent imaging modules. Precision optics manufacturers in Jena and Oberkochen control critical lens and filter supply for confocal system builds.
Japan
Stem cell research institutes in Kobe and Osaka are adopting light-sheet fluorescence systems for multi-day embryonic imaging without viability loss. PMDA QMS requirements apply to in-vitro diagnostic imaging modules, creating compliance barriers for non-domestic suppliers. Biopharma clusters in Tokyo and Yokohama concentrate demand for phenotypic drug discovery workflows.
India
Government-funded research parks in Hyderabad and Bangalore are equipping new facilities with automated imaging infrastructure. The country's national pharmaceutical regulator applies escalating quality standards to imported diagnostic equipment. Biotechnology startups in the Genome Valley cluster are piloting per-assay pricing models for cloud-based image analysis tools.
Switzerland
Diagnostic laboratories in Basel and Zurich are reassessing vendor qualification protocols to ensure AI algorithm traceability under expanding software-as-medical-device classifications. Swissmedic oversight of clinical-grade instruments favors established players with dedicated quality management systems. Pharmaceutical headquarters in Basel drive specialized procurement for compound profiling pipelines.
Global Cell Imagers Market Competitive Landscape
Concentration sits with diversified life science conglomerates that leverage integrated reagent-instrument platforms to dominate high-throughput workflows. The vendor landscape stratifies across three tiers: precision optics specialists commanding premium confocal configurations, diversified conglomerates capturing scale through bundled reagent-instrument offerings, and software-driven analytics providers competing on phenotypic drug discovery applications. Dominant competitive moves include strategic partnerships for multi-omics workflow integration and geographic expansion through localized service network establishment.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and PerkinElmer Inc. exemplify platform-centric positioning that merges hardware capital sales with recurring consumables revenue. Carl Zeiss AG occupies a position among precision optics specialists, leveraging manufacturing heritage in optical components to anchor premium-tier confocal system supply. These three entities represent the archetypal competitive vectors—platform integration, optical precision, and software analytics—that structure rivalry across the United States, German, and Japanese demand centers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Carl Zeiss AG |
| PerkinElmer Inc. |
| Leica Microsystems |
| Olympus Corp. |
| Becton, Dickinson and Co. |
| Bio-Rad Laboratories Inc. |
| Sartorius AG |
| GE HealthCare |
| Others |
Supply & Pricing Matrix
Light-sheet fluorescence microscopy displacing spinning-disk confocal units in longitudinal studies simultaneously concentrates procurement toward German and Japanese precision optics manufacturers and compresses pricing power for legacy confocal OEMs facing substitution-driven margin erosion.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across the cell imager market, separating pharmaceutical-grade validated systems from research-use-only configurations. Three-tier pricing structure across premium, standard, and economy levels reflects compliance certification depth, optical resolution specifications, and bundled software analytics. Cost compression in the research-use tier is intensifying because academic buyers are extending depreciation cycles and prioritizing modular upgrade paths over full-system replacement. Biotechnology firms in phenotypic drug discovery show least price sensitivity due to per-assay SaaS pricing models, while academic research centers in public funding cycles exhibit highest sensitivity to capital expenditure thresholds.
Supply Chain Analysis
Precision optics manufacturing chokepoints in Jena and Oberkochen anchor global confocal system production capacity. German and Japanese lens and filter specialists control critical component supply, with imager OEMs drawing from these concentrated sources for high-NA objective assemblies and dichroic filter coatings. Single-source vulnerability in specialized optical glass feedstock exposes build schedules to extended lead time volatility. Distribution runs through direct field service organizations for pharmaceutical accounts and academic distributors for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell imager market functions as a regulatory-moat industry where FDA, EMA, and PMDA validation entrenchment creates switching costs that protect incumbent positions against pure-software disrupters.
For Market Incumbents: Secure embedded audit trail architectures as the defensive anchor against cloud-native SaaS competitors seeking to unbundle hardware-software stacks. Deepen captive supply of precision optical components through exclusive partnerships with Jena and Oberkochen manufacturers to mitigate single-source exposure. Prioritize MDR-compliant quality management system investments that extend commercialization timelines for diagnostic-adjacent modules, raising barriers for emerging software specialists lacking validation infrastructure. For New Entrants and Emerging Players: Cloud-based image analysis algorithm gaps in the mid-market research segment present white-space entry points where incumbents under-serve with legacy perpetual licensing models. Target India biotech infrastructure buildout in Hyderabad and Bangalore research parks where localized service networks remain underdeveloped and government-funded procurement favors first-mover establishment. Pursue phenotypic drug discovery CROs as the most penetrable customer archetype through per-assay pricing pilots that align cost structure with outsourced screening volume variability. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision optics specialists holding proprietary lens manufacturing capabilities in German industrial clusters. Long-term viability across the analysis window hinges on regulatory entrenchment depth rather than hardware innovation velocity, favoring targets with established FDA master files and EMA notified body relationships. Monitor AI-enabled image analysis algorithm reclassifications across FDA, EMA, and PMDA jurisdictions as the critical inflection signal for software-as-medical-device valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Omics Workflow Integration | Combines spatial transcriptomics with high-content imaging in single instrument footprints for phenotypic drug discovery. |
| Localized Service Network Establishment | Captures first-mover advantage in India government-funded research parks before incumbent field organizations expand. |
| AI Algorithm SaaS Monetization | Creates recurring revenue independent of hardware cycles through per-assay pricing models at US biotechnology firms. |
| Precision Optics Supply Partnership | Secures exclusive access to Jena and Oberkochen lens manufacturers against single-source vulnerability. |
| MDR-Compliant Quality System Investment | Extends commercialization timelines for diagnostic-adjacent modules, raising barriers for emerging competitors. |
Research Methodology
Operator-level perspectives from instrument validation specialists, biopharma R&D procurement directors, academic core facility managers, and CRO screening operations leaders anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, PMDA QMS registration records, and academic procurement database trends. Bottom-up segmentation modeling triangulated with top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness across regulatory scenario variants and substitution elasticity assumptions. The analytical framework modeled volume and value outputs across product type, detection technology, therapeutic application, and institutional buyer segments, with additional dimensioning by regulatory compliance tier. CAGRs were derived from fitted growth curves against historical replacement cycle data and outsourcing penetration trajectories. Forecast inputs incorporated precision optics lead time volatility and AI algorithm reclassification probability assessments.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EMA MDR, and PMDA QMS regimes; material policy shifts in software-as-medical-device classification scope would require re-modeling. Practitioners should keep alternative scenarios live as AI-enabled diagnostic claims and cross-border data localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global AI in Computer Vision Market
Imaging
Mobile Camera Module Market
Imaging
Handheld Imaging Devices Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Thermal Imaging Systems Market
Imaging
Vision Processing Unit Market
Imaging
High-Speed Camera Market
Imaging
Vintage Cameras Market
Imaging
Asia Pacific IP Camera Market
Imaging
Global 3D Camera Market
Imaging
Pocket Video Camera Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Silent Scan Technology Market
Imaging
Global Panoramic Camera Market
Imaging
Digital X-Ray Technology Market
Imaging
Global Document Scanner Market