
 APAC Thermal Imaging Systems Market | 2026-2036
APAC Thermal Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Thermal Imaging Systems Market Outlook
Multi-source procurement of uncooled infrared detectors is expanding across APAC defense contractors seeking supply chain resilience. Teledyne FLIR leverages its vertically integrated sensor-to-system architecture to sustain premium positioning in military-grade thermal cameras. Wuhan Guide Infrared anchors regional supply through captive wafer fabrication, while Hangzhou Hikvision Digital Technology dominates commercial security deployments with aggressive channel control across tier-one Chinese cities.
Thermal imaging systems detect infrared radiation emitted by objects and convert it into visible images using focal plane arrays operating across specific spectral bands, typically long-wave infrared at 8-14 micrometers for uncooled applications. These systems serve critical functions in non-contact temperature measurement, night vision operations, and equipment fault detection across industrial and security environments. Cameras command the largest value share due to integrated optics and processing requirements, while predictive maintenance applications outpace surveillance in growth velocity as Japanese and South Korean factories automate condition-based monitoring protocols. Long-Wave Infrared technology leads volume shipments owing to mature uncooled microbolometer manufacturing, though Mid-Wave Infrared systems capture disproportionate margin in defense and process-industry segments requiring higher thermal discrimination.
Japan's METI enforces JIS standards for industrial thermal imager calibration, while China's NMPA and GB standards govern medical infrared diagnostic device registration and clinical validation protocols. South Korea's MFDS maintains separate certification tracks for diagnostic versus screening thermal systems, creating compliance complexity for cross-border equipment vendors. India's BIS mandatory certification for electronic safety equipment further fragments market access requirements across the region. Stakeholders must monitor evolving divergence between national electromagnetic compatibility test regimes and emerging cybersecurity mandates for networked thermal sensor deployments.
Market Dynamics
China's MIIT push for domestic infrared sensor production is forcing APAC defense contractors to requalify suppliers against new localization mandates, compressing procurement timelines while fragmenting vendor pools across Southeast Asian border surveillance programs.
Growth Catalysts
- Uncooled microbolometer maturation:Wafer-scale manufacturing cost reductions enable thermal camera deployment across India's industrial corridors for predictive maintenance applications.
- Japan's METI JIS calibration enforcement:Mandatory industrial thermal imager standards drive replacement cycles in Japanese automotive and electronics manufacturing facilities.
- Southeast Asian border militarization:Defense ministries in Vietnam, Indonesia, and Thailand accelerate thermal camera procurement for maritime and land boundary monitoring.
Market Restraints
- Germanium lens supply concentration:China's dominance in rare earth processing creates input cost volatility for long-wave infrared optical assemblies.
- South Korean MFDS dual certification tracks:Separate diagnostic versus screening thermal system pathways create regulatory friction for cross-border medical device vendors.
- Silicon-based visible camera substitution:Low-light CMOS sensors capture price-sensitive commercial security applications below thermal imaging thresholds.
Strategic Opportunities
- Vietnamese manufacturing automation:Underpenetrated factory condition-based monitoring creates whitespace for thermal predictive maintenance system vendors.
- China's dual carbon goals:Energy efficiency mandates for industrial facilities drive thermal audit equipment demand across steel and cement sectors.
- Edge-AI thermal fusion:On-device neural network processing enables real-time anomaly detection without cloud dependency in bandwidth-constrained environments.
Industry Challenges
- Microbolometer design talent scarcity:Specialized MEMS fabrication expertise concentrates in Wuhan and Tokyo, constraining regional capacity expansion.
- India BIS electromagnetic compatibility testing:Extended certification timelines for electronic safety equipment delay market entry for new thermal sensor suppliers.
- Legacy analog system integration:Retrofitting thermal analytics into existing CCTV infrastructure requires custom middleware development for municipal security deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Thermal Imaging Systems Market |
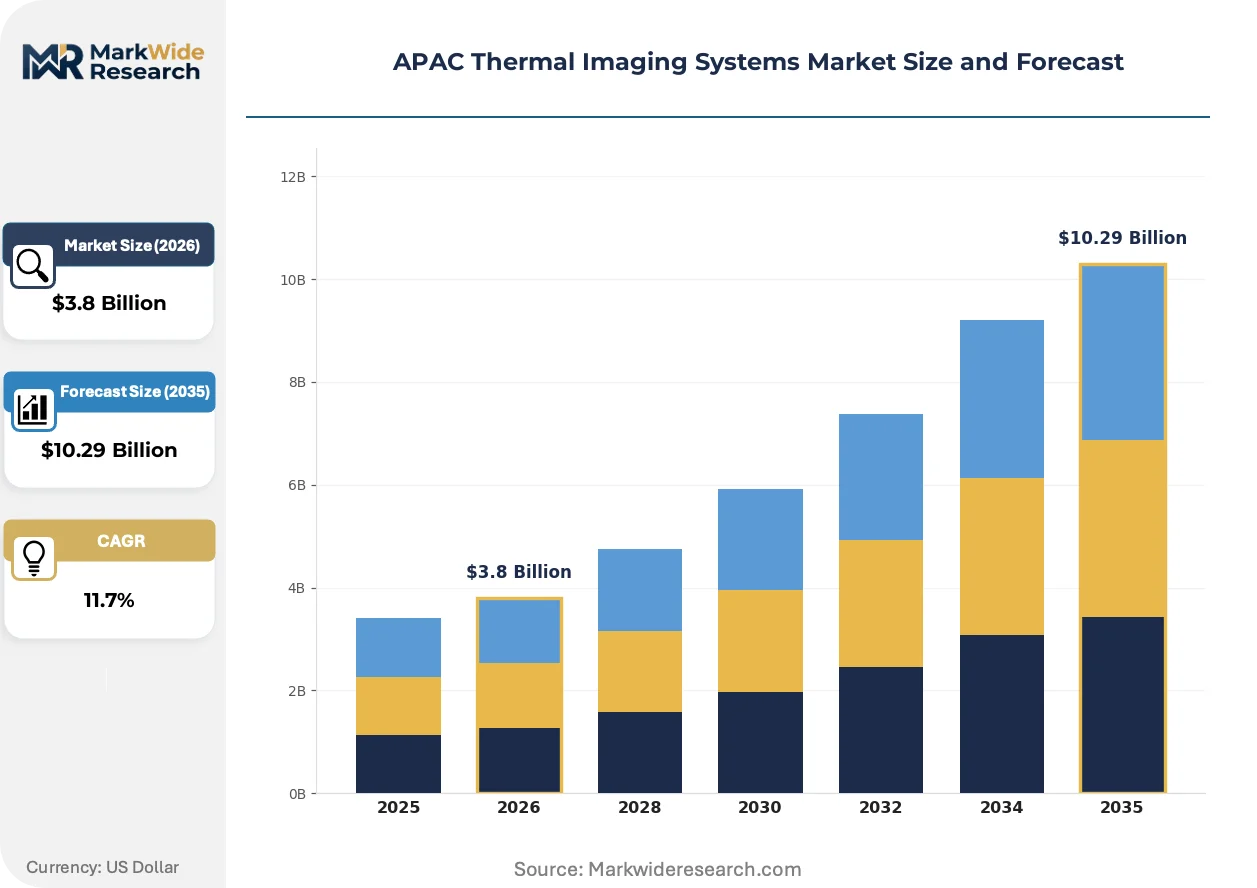
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Software, Accessories Application: Surveillance, Monitoring, Predictive Maintenance, Medical Diagnosis End User: Defense, Healthcare, Manufacturing, Energy Technology: Long-Wave Infrared, Short-Wave Infrared, Mid-Wave Infrared, Digital |
| Companies Covered | Teledyne FLIR LLC, Wuhan Guide Infrared Co., Ltd., Hangzhou Hikvision Digital Technology Co., Ltd., Fluke Corporation, Opgal Optronic Industries Ltd., LYNRED, Testo SE and Co. KGaA, L3Harris Technologies, BAE Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Thermal Imaging Systems Market Strategic Shifts
Wafer-level packaging advances and edge computing integration are compressing thermal camera form factors while expanding deployable use cases beyond traditional defense and industrial boundaries.
Vanadium oxide microbolometers are overtaking amorphous silicon alternatives in uncooled focal plane arrays due to superior thermal sensitivity coefficients. Japanese automotive Tier-1 suppliers are adopting these sensors for pedestrian detection systems at accelerating volumes. This technology shift is overtaking price-competitive silicon alternatives in safety-critical applications where detection range directly determines system architecture.
China's GB standards for networked sensor cybersecurity are mandating encryption protocols and firmware attestation for thermal cameras deployed in critical infrastructure. Industrial facility operators must upgrade existing installations to meet these requirements or face operational permit restrictions. Energy sector deployments in Shanghai and Guangdong industrial zones are experiencing the steepest compliance cost impacts as retrofit deadlines approach.
Subscription-based thermal monitoring services are displacing capital equipment purchases among mid-sized South Korean electronics manufacturers. System integrators bundle hardware, cloud analytics, and predictive algorithms into per-facility monthly fees. This model is compressing sales cycles and shifting vendor relationships from transactional procurement to ongoing service partnerships in Gyeonggi-do semiconductor fabrication clusters.
APAC Thermal Imaging Systems Market Segmentation
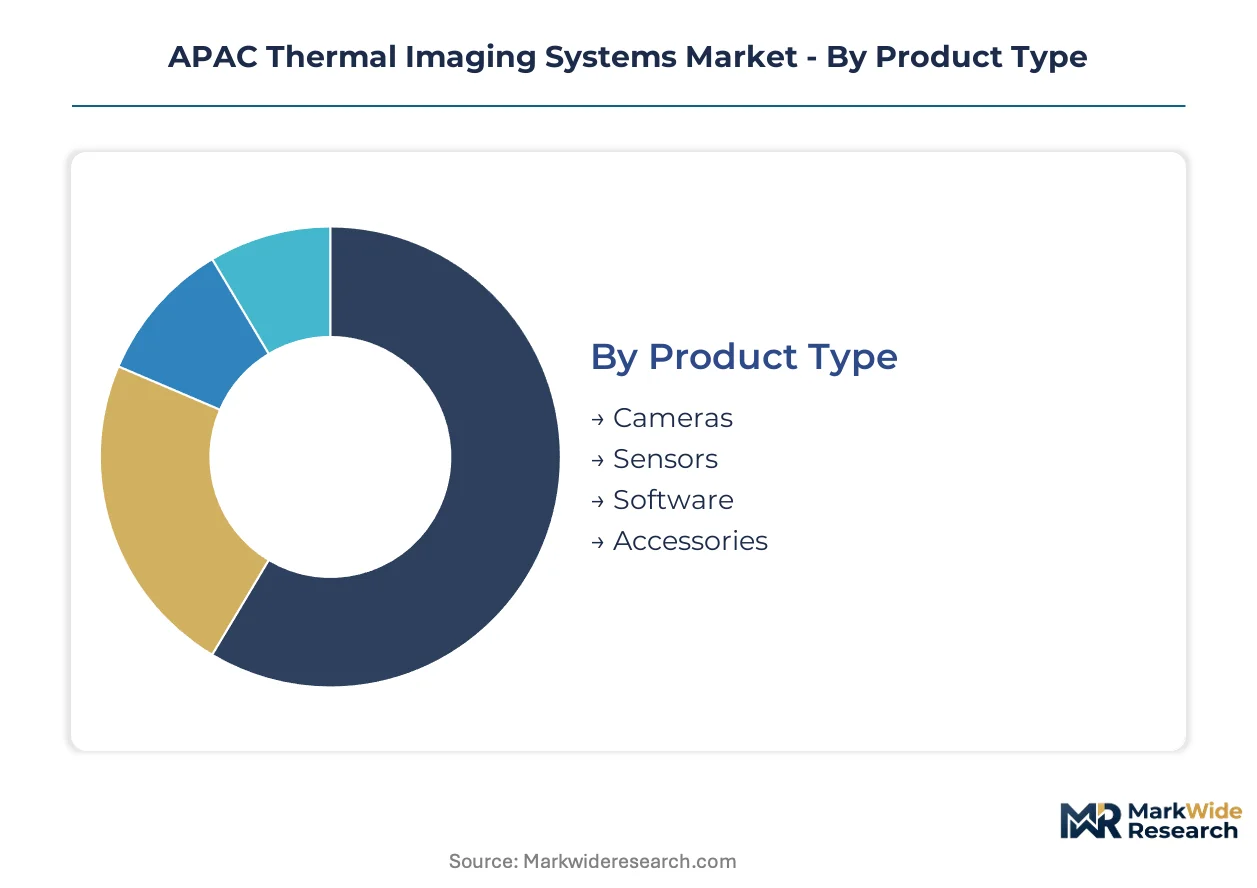
Segmentation in APAC thermal imaging systems reveals how procurement priorities diverge across defense budgets, industrial automation timelines, and healthcare regulatory pathways. Understanding these fault lines enables vendors to align R&D investment with buyer decision criteria rather than spreading resources across mismatched demand profiles.
Product Type:
Capital allocation intensity determines product selection, with integrated systems commanding premium budgets and discrete components serving cost-constrained deployments.
- Cameras:Integrated optical assemblies with embedded focal plane arrays and signal processing electronics. Japanese automotive suppliers drive demand for pedestrian detection units, while Indian steel mills deploy ruggedized enclosures for furnace monitoring in Jamshedpur and Bhilai corridors.
- Sensors:Discrete detector elements and microbolometer arrays requiring external optics and processing. Wuhan-based wafer fabs supply uncooled detectors to Southeast Asian defense contractors seeking supply chain resilience against MIIT localization mandates.
- Software:Thermal analytics platforms for anomaly detection and temperature trending. South Korean electronics manufacturers favor subscription-based predictive maintenance suites over perpetual licenses.
- Accessories:Germanium lenses, calibration sources, and mounting hardware. China's dominance in rare earth processing creates input cost volatility for long-wave infrared optical assemblies.
Cameras lead on scale; Sensors lead on momentum as defense contractors diversify procurement sources.
Application:
Return-on-investment horizons shape application prioritization, with predictive maintenance delivering measurable downtime reductions and surveillance requiring longer payback justification.
- Surveillance:Perimeter monitoring and night vision operations using thermal contrast for target detection. Vietnam, Indonesia, and Thailand defense ministries accelerate maritime and land boundary camera procurement.
- Monitoring:Continuous temperature observation for process control and safety systems. China's dual carbon goals drive thermal audit equipment demand across steel and cement sectors in Shanghai and Guangdong industrial zones.
- Predictive Maintenance:Condition-based equipment monitoring using thermal signatures to detect bearing failures, electrical hotspots, and insulation degradation. Japanese and South Korean factories automate protocols fastest, while Vietnamese manufacturing automation creates whitespace for system vendors.
- Medical Diagnosis:Non-contact fever screening and clinical thermal imaging for vascular and inflammatory assessment. South Korea's MFDS maintains separate certification tracks for diagnostic versus screening systems, fragmenting vendor compliance pathways.
Predictive Maintenance gains share fastest; Surveillance retains the largest installed base across APAC defense infrastructure.
End User:
Budget cycle predictability and procurement authority concentration determine end-user targeting, with defense offering multi-year commitments and manufacturing presenting fragmented decision-making.
- Defense:Military-grade thermal systems for reconnaissance, targeting, and border security. Southeast Asian ministries requalify suppliers against China's MIIT localization mandates, compressing procurement timelines.
- Healthcare:Clinical and screening thermal devices subject to national medical device regulations. China's NMPA and GB standards govern registration and clinical validation protocols for infrared diagnostic equipment.
- Manufacturing:Industrial thermal imaging for quality assurance and equipment reliability. Japan's METI enforces JIS calibration standards, driving replacement cycles in automotive and electronics facilities.
- Energy:Thermal inspection of transmission infrastructure, substations, and renewable generation assets. India's BIS mandatory certification for electronic safety equipment delays market entry for new sensor suppliers.
Defense leads on contract value; Manufacturing leads on deployment velocity as automation accelerates.
Technology:
Spectral band selection trades off thermal sensitivity, atmospheric transmission, and cost, with uncooled long-wave options dominating volume and cooled mid-wave systems capturing precision applications.
- Long-Wave Infrared:Uncooled microbolometer systems operating at 8-14 micrometers for ambient temperature imaging. Wafer-scale manufacturing cost reductions enable deployment across India's industrial corridors for predictive maintenance.
- Short-Wave Infrared:Silicon-based detector arrays for high-temperature measurement and solar cell inspection. Japanese semiconductor fabrication clusters adopt these for wafer quality control.
- Mid-Wave Infrared:Cooled photodetector systems requiring cryogenic cooling for superior thermal discrimination. Defense and process-industry segments requiring higher precision capture disproportionate margin despite lower volume.
- Digital:Software-defined thermal processing and edge-AI integration for on-device analytics. Networked sensor cybersecurity mandates under China's GB standards require encryption protocol upgrades.
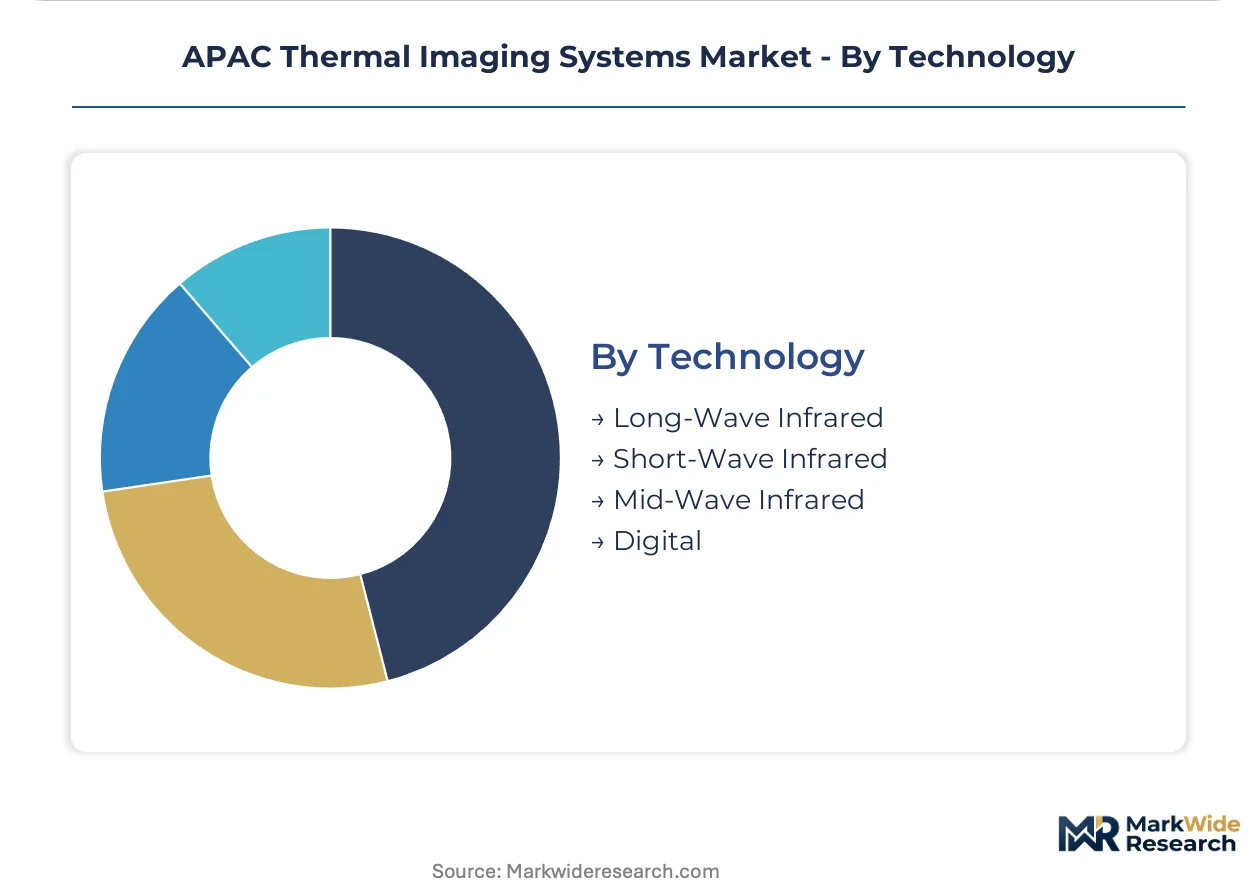
Long-Wave Infrared leads on shipment volume; Digital leads on innovation intensity as edge computing expands deployable use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Guangdong industrial zones anchor APAC thermal imaging demand through energy efficiency mandates and factory automation programs. Defense procurement across Southeast Asia accelerates border surveillance deployments. Regulatory fragmentation across national certification regimes shapes vendor market access strategies.
China
Steel and cement sectors in Shanghai and Guangdong industrial zones deploy thermal audit equipment under MIIT energy efficiency mandates. GB standards for networked sensor cybersecurity require encryption protocol upgrades for critical infrastructure deployments. Wuhan-based wafer fabs supply uncooled detectors to defense contractors navigating localization requirements.
Japan
Automotive Tier-1 suppliers adopt vanadium oxide microbolometers for pedestrian detection systems at accelerating volumes. METI enforces JIS calibration standards for industrial thermal imagers, driving replacement cycles in automotive and electronics manufacturing. Kanto region factories automate condition-based monitoring protocols fastest in the region.
India
Manufacturing facilities in Jamshedpur and Bhilai industrial corridors deploy ruggedized thermal enclosures for furnace monitoring and predictive maintenance. BIS mandatory certification for electronic safety equipment extends electromagnetic compatibility testing timelines for new sensor suppliers. Steel mills represent the primary demand concentration for industrial-grade thermal systems.
South Korea
Electronics manufacturers in Gyeonggi-do semiconductor fabrication clusters favor subscription-based thermal monitoring services over capital equipment purchases. MFDS maintains separate certification tracks for diagnostic versus screening thermal systems, fragmenting vendor compliance pathways. Daegu-Gyeongbuk industrial belt shows emerging whitespace for predictive maintenance system vendors.
Vietnam
Manufacturing automation remains underpenetrated, creating whitespace for thermal predictive maintenance system vendors in emerging industrial zones. Defense ministry accelerates maritime and land boundary camera procurement for border surveillance programs. Northern manufacturing provinces experience fastest adoption velocity as factory automation timelines compress.
APAC Thermal Imaging Systems Market Competitive Environment
Global majors compete with regional champions across sensor fabrication and system integration dimensions. The vendor base stratifies into three tiers: vertically integrated sensor-to-system architects, specialized detector fabricators with captive wafer capacity, and commercial security deployers leveraging aggressive channel control. Consolidation pressure concentrates in defense-grade segments where qualification barriers protect incumbent positions. Strategic moves center on backward integration into detector manufacturing and geographic expansion through localized certification compliance.
Among US-based system integrators, Teledyne FLIR LLC and L3Harris Technologies occupy positions emphasizing military-grade thermal camera architectures. Chinese specialists including Wuhan Guide Infrared Co., Ltd. and Hangzhou Hikvision Digital Technology Co., Ltd. exemplify regional champions with differentiated supply chain configurations. These named entities represent archetypes spanning premium defense positioning, captive wafer fabrication, and commercial security channel dominance respectively.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Wuhan Guide Infrared Co., Ltd. |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Fluke Corporation |
| Opgal Optronic Industries Ltd. |
| LYNRED |
| Testo SE and Co. KGaA |
| L3Harris Technologies |
| BAE Systems |
| Others |
Value Chain & Pricing Dynamics
Captive wafer fabrication in Wuhan and Tokyo anchors supply positions for regional thermal imaging champions while insulating them from germanium lens cost volatility that compresses margins for assembly-only competitors. This backward integration into detector manufacturing enables pricing power in defense-grade segments where qualification barriers protect incumbent positions.
Pricing Analysis
Germanium lens cost pass-through from China's rare earth processing dominance creates asymmetric pressure across thermal camera tiers. Three-tier pricing structure across military-certified, industrial-grade, and commercial security levels reflects certification grade and volume scale differentiation. Pricing pressure intensifies in commercial security as low-light CMOS sensors capture price-sensitive applications below thermal thresholds. Mid-sized South Korean electronics manufacturers exhibit highest price sensitivity through subscription-based service preferences, while defense ministries show lowest sensitivity due to multi-year procurement commitments.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Japanese automotive Tier-1 suppliers and Indian steel mill operators, while system integrators serve fragmented mid-market manufacturing. Supply concentrates in China for rare earth processing and wafer-scale microbolometer production, with Japan and South Korea contributing specialized MEMS fabrication expertise. Germanium lenses, vanadium oxide detector materials, and cryogenic cooling assemblies constitute critical input dependencies. Single-source vulnerability in rare earth processing creates tariff exposure for optical assembly costs. Distribution runs through defense procurement offices, industrial automation distributors, and security channel partners across tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC thermal imaging market compounds steadily as factory automation protocols proliferate across underpenetrated manufacturing corridors. This structural automation wave generates predictable replacement cycles and service attachment opportunities.
For Market Incumbents: Cement qualification advantages by deepening JIS and BIS certification investments before localization mandates harden. Expand captive detector capacity in Wuhan to offset MIIT supply chain requalification disruptions. Channel control in tier-one Chinese cities defends against Hikvision's aggressive commercial security positioning.
For New Entrants and Emerging Players: System integrators in Vietnam's northern manufacturing provinces offer the most penetrable entry channel for predictive maintenance solutions. Target Daegu-Gyeongbuk industrial belt in South Korea through subscription-based thermal monitoring partnerships. Partner with Japanese automotive Tier-2 suppliers for pedestrian detection module co-development.
For Investors and Strategic Acquirers: Roll-up economics work for specialized detector fabricators because MEMS design talent scarcity in Wuhan and Tokyo constrains organic capacity expansion. Five-to-ten year viability hinges on edge-AI thermal fusion capabilities. Watch for cybersecurity mandate enforcement under China's GB standards as inflection indicator for retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Fabrication | Wuhan-based wafer fabs supply uncooled microbolometers to Southeast Asian defense contractors navigating MIIT mandates. |
| Edge-AI Thermal Fusion Development | On-device neural network processing enables real-time anomaly detection in bandwidth-constrained factory environments. |
| Subscription Service Model Launch | South Korean electronics manufacturers in Gyeonggi-do clusters favor monthly facility fees over capital equipment purchases. |
| GB Standards Cybersecurity Compliance | Encryption protocol upgrades become mandatory for thermal cameras deployed in Shanghai and Guangdong critical infrastructure. |
| Vietnamese Manufacturing Channel Expansion | Northern industrial provinces show fastest automation adoption velocity for predictive maintenance system vendors. |
Study Parameters
Bottom-up manufacturing facility deployment modeling reconciled against top-down defense procurement tracking forms the analytical core of this study. Primary interviews with plant maintenance directors, defense procurement officers, thermal system integration specialists, and MEMS fabrication engineers combined with secondary validation from customs trade data, MIIT localization policy filings, METI JIS standard updates, and BIS electromagnetic compatibility test records. This triangulation approach ensures supply-side and demand-side estimates converge across the analysis window.
Input-output matrices map thermal camera shipments by spectral band against end-use automation timelines and regulatory compliance deadlines. Segmentation dimensions include product type, application, technology, and end-user vertical with geographic production cluster differentiation. CAGRs derive from installed base replacement cycles, new facility automation adoption curves, and defense budget allocation patterns. Forecast inputs incorporate wafer-scale manufacturing cost reduction trajectories and cybersecurity mandate enforcement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions, MIIT localization mandate expansion, and silicon-based visible camera substitution acceleration. Assumptions reflect documented procurement timelines, regulatory filing patterns, and technology substitution thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Visualiser Market
Imaging
India CCTV Camera Market
Imaging
Side View Camera System Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Chemiluminescence Imaging Market
Imaging
Digitizer Market
Imaging
Microscopic Camera Market
Imaging
Image Based Barcode Reader Market
Imaging
Plenoptic Camera Market
Imaging
Thermal Imaging Systems Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Event Camera Market
Imaging
Smartphone with Periscope Lens Market
Imaging
Printed Image Sensors Market
Imaging
Global Image Signal Processor Market