
 2D and 3D Machine Vision Systems Market | 2026-2036
2D and 3D Machine Vision Systems Market Size, Share, and Industry Trends Forecast 2026-2036
2D and 3D Machine Vision Systems Market Analysis
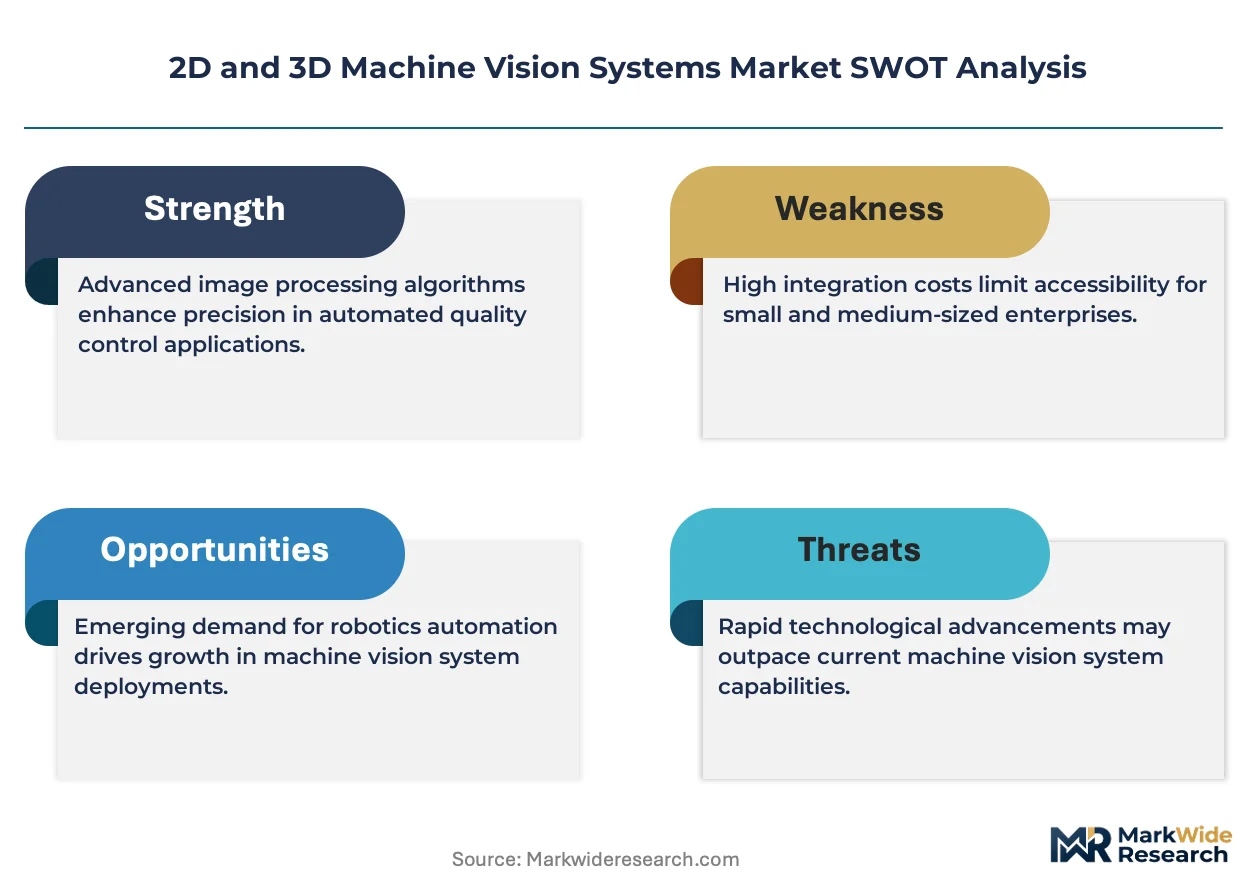
Aftermarket service revenue from calibration, software updates, and lens replacement is narrowing as a distinct margin pool, with OEMs bundling multi-year service contracts into initial system sales. Cognex Corporation leverages its deep software library to sustain recurring revenue streams beyond hardware shipment. Keyence Corporation anchors its position through direct sales engineers who control technical specification conversations with plant managers. Teledyne Technologies Incorporated competes by extending its sensor technology leadership from aerospace into industrial inspection applications.
2D and 3D machine vision systems comprise camera modules, illumination arrays, image processors, and algorithmic software that extract dimensional, positional, or defect data from captured scenes, typically operating at frame rates exceeding 30 fps with spatial resolutions down to single-digit micrometers for semiconductor wafer inspection. Their primary purpose is to automate visual quality verification and robotic positioning in manufacturing environments where human inspection proves too slow or inconsistent. 3D imaging systems now lead capital deployment in automotive body-in-white measurement, while smart cameras dominate food and beverage packaging lines where space constraints and cost sensitivity shape procurement. Vision software captures expanding margin pools as customers prioritize algorithm retraining and defect-classification accuracy over incremental camera hardware improvements.
The EU Machinery Directive, CE marking requirements, and FDA's Quality System Regulation for medical device manufacturing all elevate compliance burdens for vision system suppliers seeking market access. FDA 21 CFR Part 820 inspections specifically challenge pharmaceutical vision deployments where software validation and traceability documentation determine supplier qualification. ISO 10218 safety standards for industrial robots further constrain how 3D guidance systems integrate into collaborative workcells. Stakeholders must monitor whether emerging AI Act conformity requirements in Europe will force algorithmic transparency disclosures that erode proprietary advantage in defect-detection models.
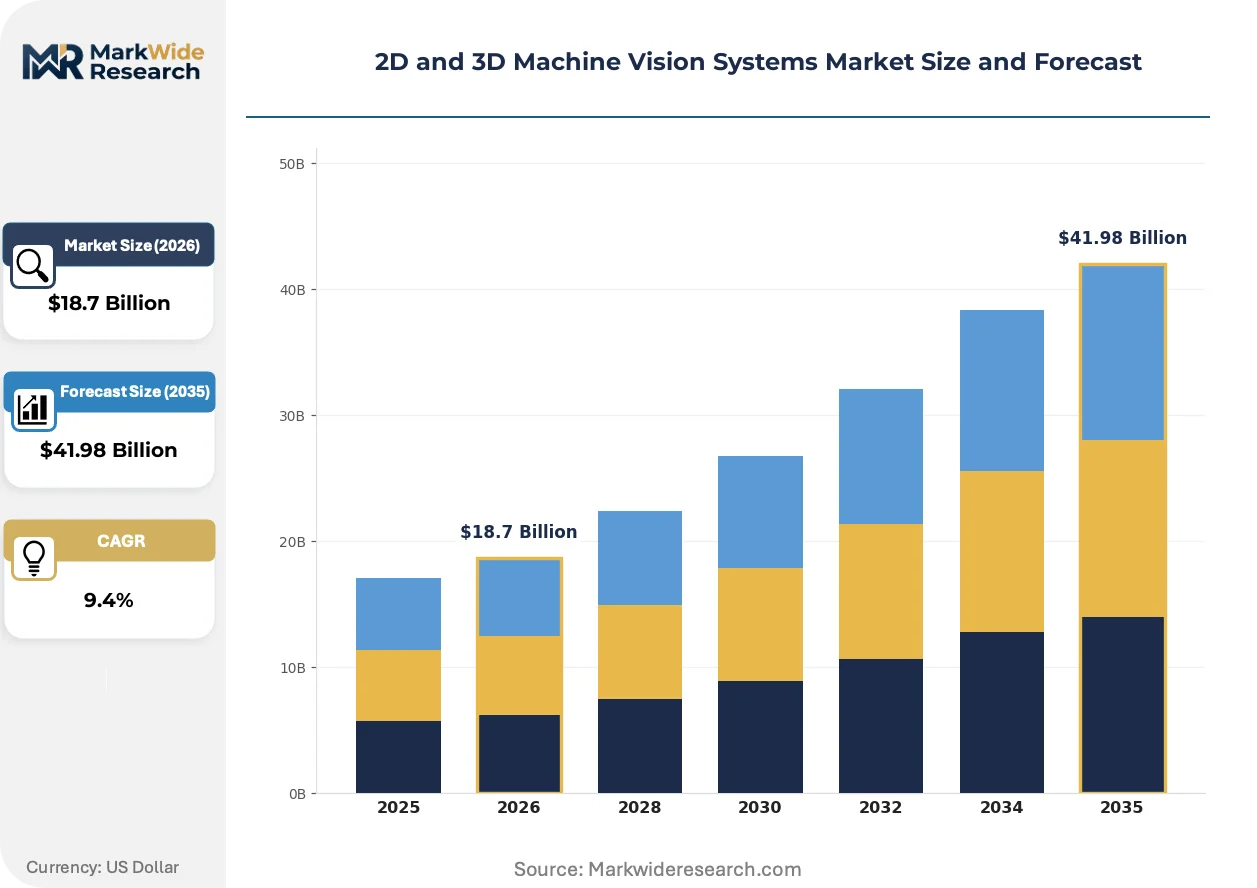
Market Dynamics
Automotive OEMs in Germany's manufacturing belt are forcing machine vision standardization across Tier-1 supplier networks, compressing procurement cycles and mandating 3D guidance compatibility for robotic welding cells.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for safety-related control systems compel European manufacturers to replace legacy 2D setups with certified 3D guidance architectures.
- Semiconductor wafer inspection:Spatial resolution demands below 10 micrometers are accelerating deployment of high-frame-rate 3D imaging systems in cleanroom environments.
- Adhesive dispensing automation:Automotive body-in-white assembly lines now require real-time 3D bead verification, pulling capital toward multi-camera guidance networks.
Market Restraints
- Illumination array costs:Structured light and laser projection components face price volatility from rare-earth phosphor supply concentration in China.
- Algorithmic opacity:Proprietary defect-detection models resist third-party validation, creating procurement friction under FDA 21 CFR Part 820 traceability requirements.
- 2D camera commoditization:Smart camera margins in food packaging are compressing as open-source image processing libraries erode software differentiation.
Strategic Opportunities
- Collaborative robot integration:ISO 10218 safety standard compliance creates specification authority for 3D guidance vendors designing workcell entry systems.
- India pharmaceutical packaging:CDSCO enforcement of visual inspection protocols for parenteral drugs is opening demand for validated machine vision lines.
- Edge-AI convergence:On-camera inference chips combined with cloud-based model retraining are enabling subscription software revenue beyond hardware shipment.
Industry Challenges
- Optical calibration expertise:Lens distortion correction and multi-camera triangulation require specialized technicians scarce in Midwest US manufacturing hubs.
- Legacy PLC integration:Decades-old automotive line controllers demand custom communication gateways, extending deployment timelines and acceptance testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2D and 3D Machine Vision Systems Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: 2D Imaging, 3D Imaging, Smart Cameras, Vision Software Application: Quality Control, Robotic Guidance, Inspection, Measurement Industry Vertical: Automotive, Electronics, Food & Beverage, Pharmaceuticals End User: Manufacturers, System Integrators, Research Institutions, Third-party Evaluators |
| Companies Covered | Cognex Corporation, Keyence Corporation, Teledyne Technologies Incorporated, Basler AG, Omron Corporation, SICK AG, National Instruments Corporation, ISRA Vision AG, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2D and 3D Machine Vision Systems Market Emerging Trajectories
Software-defined inspection architectures are separating algorithm performance from camera hardware specifications, enabling continuous model improvement without capital replacement cycles.
Time-of-flight depth sensing is migrating from consumer electronics into industrial bin-picking applications. Tier-1 automotive suppliers in Stuttgart and Wolfsburg are piloting these sensors for unsorted component handling. This migration is compressing the price premium between structured-light and solid-state 3D alternatives.
REACH restrictions on halogenated flame retardants are forcing illumination housing redesigns across European machine vision suppliers. Manufacturers must validate alternative thermal management materials without degrading LED array lifespans. German automotive OEMs are now requiring material compliance documentation upstream in supplier qualification.
Service contract bundling is displacing transactional aftermarket revenue. Cognex and Keyence field organizations now lead specification conversations with multi-year calibration and software update commitments. This pattern concentrates most visibly in Germany's automotive belt where OEMs demand uptime guarantees across supplier networks.
2D and 3D Machine Vision Systems Market Segmentation
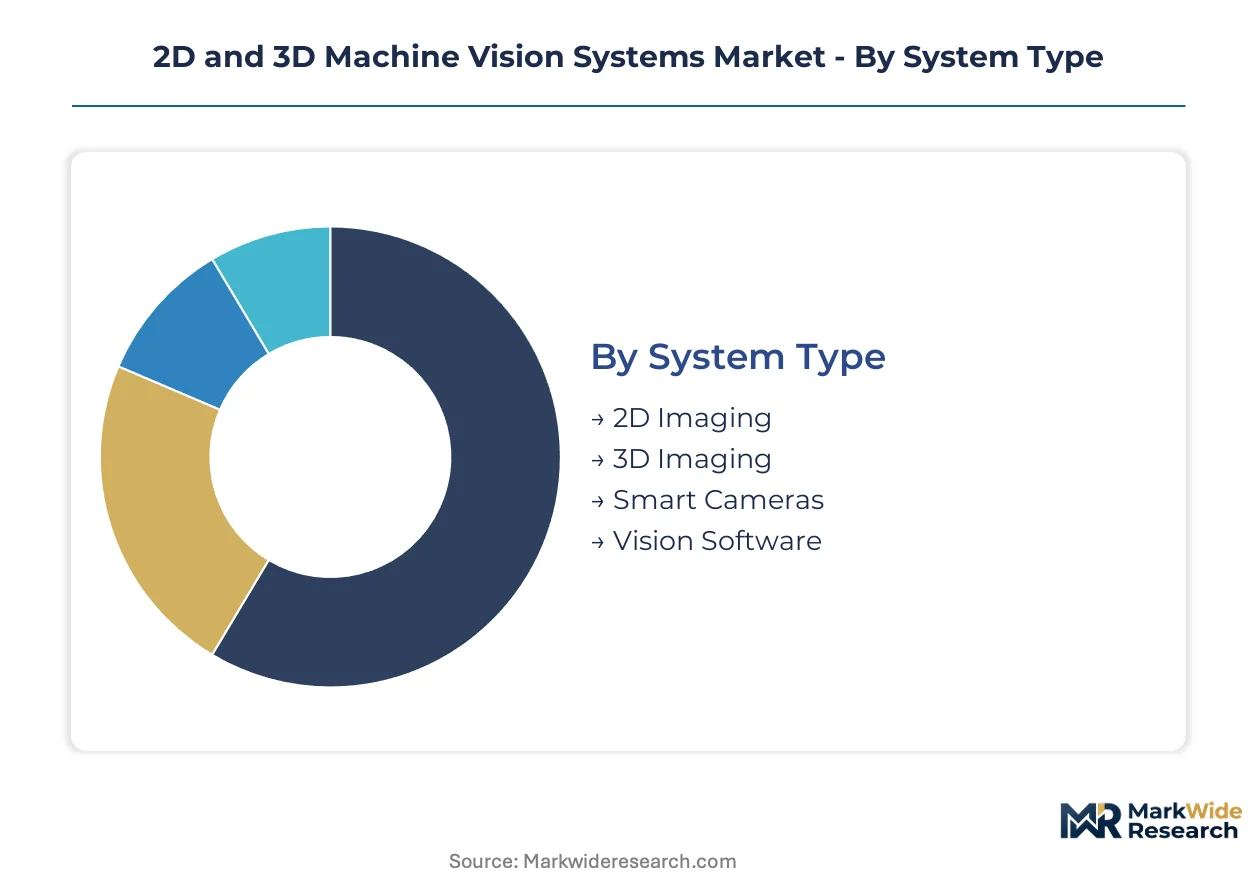
Machine vision procurement patterns diverge sharply across system architectures, deployment contexts, and buyer sophistication. Understanding these segment boundaries clarifies where specification authority concentrates and which technology transitions command capital allocation.
System Type:
Industrial deployments span a functional spectrum from simple presence detection to complex dimensional reconstruction, with cost and integration complexity escalating across the hierarchy.
- 2D Imaging:Conventional area-scan and line-scan cameras capture intensity-based images for pattern recognition, barcode reading, and surface defect detection. Food packaging lines in the Netherlands and Belgium deploy these systems for label verification where space constraints and throughput requirements dominate specification conversations.
- 3D Imaging:Structured light, laser triangulation, and stereo vision systems generate point clouds for volumetric measurement and spatial positioning. Automotive body-in-white assembly in Stuttgart and Wolfsburg drives capital concentration here, with real-time bead inspection for adhesive dispensing now mandatory across Tier-1 supplier networks.
- Smart Cameras:Embedded processing units combining image sensors with onboard computation for decentralized decision-making. Electronics assembly in South Korea favors these for component placement verification where network latency would compromise cycle times.
- Vision Software:Algorithmic platforms for image processing, model training, and system integration. Pharmaceutical manufacturers in Ireland and Switzerland prioritize validated software libraries under FDA and EMA quality system requirements.
Established volume favors 2D Imaging; emerging adoption favors 3D Imaging.
Application:
Deployment purpose determines camera specification, illumination design, and computational architecture with minimal overlap between use cases.
- Quality Control:Pass-fail determination against tolerance thresholds for cosmetic and dimensional attributes. Semiconductor wafer fabs in Taiwan and South Korea operate these systems at frame rates exceeding 100 fps with sub-5-micrometer resolution requirements.
- Robotic Guidance:Real-time coordinate transmission to manipulators for pick-and-place, welding, and assembly operations. Automotive OEMs in Germany's manufacturing belt mandate 3D guidance compatibility across robotic welding cell procurements.
- Inspection:Defect classification and traceability documentation for regulatory compliance. Medical device manufacturers in Massachusetts and Minnesota face FDA 21 CFR Part 820 validation requirements that shape software selection.
- Measurement:Dimensional metrology for geometric dimensioning and tolerancing verification. Aerospace suppliers in Toulouse and Hamburg deploy multi-camera networks for airframe assembly alignment.
Procurement frequency runs highest for Quality Control; specification complexity peaks with Robotic Guidance.
Industry Vertical:
End-use sector dictates environmental robustness, certification requirements, and supplier qualification protocols.
- Automotive:Body-in-white measurement, paint surface inspection, and powertrain assembly verification. German OEMs coordinate standardization across supplier networks, compressing procurement cycles and mandating interoperability.
- Electronics:PCB inspection, component placement verification, and final assembly quality. South Korean and Taiwanese contract manufacturers drive demand for high-magnification imaging with thermal management for continuous operation.
- Food & Beverage:Packaging integrity, label verification, and contaminant detection. Dutch and Danish producers prioritize IP69K-rated housings for washdown environments.
- Pharmaceuticals:Parenteral drug inspection, serialization, and aggregation for track-and-trace. Irish and Swiss facilities face EMA and FDA dual compliance burdens that elevate documentation requirements.
Capital intensity concentrates in Automotive; compliance rigor peaks in Pharmaceuticals.
End User:
Buyer type determines technical specification involvement, procurement process length, and service contract structure.
- Manufacturers:Direct deployment for internal production lines with in-house maintenance capabilities. German automotive Tier-1 suppliers maintain dedicated vision engineering teams for line optimization.
- System Integrators:Third-party designers and installers of complete automation solutions. These intermediaries control camera selection for mid-market electronics producers in Eastern Europe.
- Research Institutions:Universities and national laboratories developing novel imaging algorithms. ETH Zurich and TU Munich maintain partnerships with industrial suppliers for technology transfer.
- Third-party Evaluators:Independent testing organizations and certification bodies. These entities influence pharmaceutical supplier qualification through validation protocol development.
Volume concentration sits with Manufacturers; emerging influence flows through System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in machine vision procurement diverges sharply across manufacturing belts. German automotive buyers prioritize specification authority and uptime guarantees over unit cost. Packaging producers in the Netherlands and Belgium select compact smart cameras where footprint constraints dominate capital decisions.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate 3D guidance compatibility across Tier-1 supplier networks, compressing procurement cycles. The EU Machinery Directive and CE marking requirements compel manufacturers to replace legacy 2D setups with certified architectures. Bavaria's manufacturing corridor concentrates the highest density of robotic welding cell deployments with integrated vision guidance.
United States
Semiconductor wafer fabs in Arizona and Texas drive demand for sub-5-micrometer resolution systems at frame rates exceeding 100 fps. FDA 21 CFR Part 820 inspections challenge pharmaceutical vision deployments in Massachusetts and Minnesota, elevating software validation documentation requirements. The Midwest manufacturing hub faces acute shortages of optical calibration technicians for lens distortion correction and multi-camera triangulation.
China
Electronics contract manufacturers in the Yangtze River Delta and Pearl River Delta deploy high-magnification imaging for PCB inspection and component placement verification. GB standards and MIIT industrial automation directives shape local procurement specifications. Shenzhen and Suzhou cluster the densest concentration of smart camera integration for consumer electronics assembly lines.
South Korea
Memory chip and display panel producers in the Seoul Capital Area and Busan-Ulsan region favor embedded processing units where network latency would compromise cycle times. MFDS enforcement of visual inspection protocols for pharmaceutical manufacturing elevates validated system requirements. Samsung and LG supplier ecosystems coordinate machine vision standardization across component fabrication facilities.
India
Pharmaceutical packaging lines in Maharashtra and Gujarat face CDSCO enforcement of visual inspection protocols for parenteral drugs. The PLI scheme for electronics manufacturing is attracting machine vision deployment for mobile phone assembly verification. Pune and Ahmedabad industrial zones represent the fastest-expanding demand centers for validated inspection systems under emerging regulatory pressure.
2D and 3D Machine Vision Systems Market Vendor Landscape
Integrated platform vendors and specialized component suppliers split the market along the hardware-software boundary. Consolidation pressure concentrates among automotive OEM procurement offices where standardization mandates favor full-stack solution providers. Three archetypes dominate: sensor-technology specialists extending from adjacent industries, direct-sales organizations controlling technical specification conversations, and software-centric platforms capturing recurring revenue through algorithm licensing. Dominant competitive moves include strategic partnerships for collaborative robot integration and geographic expansion into pharmaceutical manufacturing corridors.
Within the direct-sales archetype, Keyence Corporation exemplifies specification control through embedded field engineers. Cognex Corporation and Teledyne Technologies Incorporated occupy positions spanning software libraries and sensor technology extension respectively. Basler AG represents the component-specialist vector with focused camera module expertise. Omron Corporation and SICK AG anchor integrated automation portfolios where vision systems complement broader factory control offerings. These named entities illustrate how competitive positioning stratifies across technical specification depth, distribution model intensity, and vertical application breadth.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Teledyne Technologies Incorporated |
| Basler AG |
| Omron Corporation |
| SICK AG |
| National Instruments Corporation |
| ISRA Vision AG |
| Canon Inc. |
| Others |
Supply Flow & Price Mechanics
Rare-earth phosphor supply concentration in China exposes illumination array costs to commodity volatility, compressing margin spreads between premium 3D guidance systems and economy 2D camera tiers while forcing European manufacturers toward alternative sourcing strategies.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture, with multi-year calibration and software update bundles displacing transactional parts revenue. Three-tier pricing structure across premium certified, standard industrial, and economy smart camera levels reflects differentiation by CE marking compliance and algorithmic retraining access. Cost compression in the economy tier intensifies as open-source image processing libraries erode software differentiation. Food and beverage packaging producers exhibit highest price sensitivity due to space constraints and throughput requirements, while German automotive OEMs prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock for structured light and laser projection components draws from rare-earth processing facilities concentrated in China, with secondary optical glass and LED phosphor sourcing from Japan and Germany. Image sensor fabrication rests on Taiwan and South Korea foundry capacity, while precision lens grinding clusters in Germany and Japan. Single-source vulnerability in rare-earth phosphor supply creates tariff exposure and price volatility risks. Distribution runs through direct sales engineers controlling technical specification conversations with plant managers, supplemented by system integrator channels for mid-market electronics producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine vision procurement is shifting toward platform economics where software-defined architectures and interoperability mandates across German automotive supplier networks create winner-take-most dynamics for ecosystem orchestrators.
For Market Incumbents: Entrench specification authority by embedding field engineers deeper into Tier-1 supplier technical conversations and securing multi-year service contract renewals before hardware replacement cycles. Open-source image processing libraries threaten software differentiation; respond by accelerating proprietary algorithm retraining capabilities and validated software libraries for pharmaceutical compliance. Backward integration into illumination component sourcing mitigates rare-earth phosphor volatility exposure. For New Entrants and Emerging Players: Mid-market electronics contract manufacturers in Eastern Europe represent the most penetrable entry point, where system integrator channel relationships remain underdeveloped and price sensitivity exceeds brand loyalty. India's pharmaceutical packaging corridors under CDSCO enforcement pressure offer validated system demand without entrenched incumbent relationships. Target these geographies through partnership with regional system integrators lacking in-house vision engineering expertise. For Investors and Strategic Acquirers: The market sits at a standardization phase that favors full-stack solution providers with software-centric recurring revenue models over component-specialist hardware vendors. Long-term viability across the projection horizon favors acquisition targets possessing validated pharmaceutical software libraries or established direct sales organizations in Germany's automotive belt. Watch for EU AI Act conformity requirements as an inflection signal that could force algorithmic transparency disclosures eroding proprietary defect-detection model advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Development | Separates algorithm performance from camera hardware, enabling continuous model improvement without capital replacement. |
| Collaborative Robot Integration Partnership | ISO 10218 safety compliance creates specification authority for 3D guidance vendors designing workcell entry systems. |
| Pharmaceutical Validation Documentation Investment | FDA 21 CFR Part 820 and EMA quality system requirements elevate barriers for unvalidated software competitors. |
| Edge-AI Inference Chip Integration | On-camera processing combined with cloud-based model retraining enables subscription software revenue beyond hardware shipment. |
| Direct Sales Organization Geographic Expansion | Field engineer presence controls technical specification conversations with plant managers in procurement decisions. |
Methodological Framework
Desk research of SEC filings, EU regulatory databases, and automotive production statistics preceded structured interviews with vision system engineering directors, Tier-1 supplier procurement managers, pharmaceutical quality assurance leads, and system integrator technical specialists. Primary fieldwork across Germany's automotive belt, the Netherlands packaging corridor, and South Korean electronics clusters was cross-validated against secondary trade flow data and patent filing trends. Bottom-up unit deployment estimates were triangulated with top-down capital expenditure projections from manufacturing sector surveys.
Forecast assumptions held fixed the EU Machinery Directive enforcement trajectory and FDA inspection intensity while varying semiconductor capital expenditure cycles and collaborative robot adoption rates across the analysis window. Segmentation modeling spanned system architecture, application purpose, industry vertical, and end-user sophistication dimensions. CAGRs were derived from logistic diffusion curves fitted to historical deployment data and adjusted for regulatory mandate acceleration effects in automotive and pharmaceutical sectors.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor capital expenditure cycles, or rare-earth export restrictions would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution rates. Cross-checking against IHS Markit vehicle production databases and SEMAPHORE pharmaceutical capital expenditure indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Photoacoustic Imaging Market
Imaging
Microscope Digital Cameras Market
Imaging
Weatherproof Camera Market
Imaging
X Ray Tubes Market
Imaging
Video Microscopes Market
Imaging
Semiconductor Microscopes Market
Imaging
Printed Image Sensors Market
Imaging
Camera Technology Market
Imaging
Small CCTV Camera Market
Imaging
Global Image Signal Processor Market
Imaging
Document Imaging Market
Imaging
Acoustic Microscopy Market
Imaging
Automotive Compact Camera Module Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Infrared Imaging Market