
 Computer Aided Detection Market | 2026-2036
Computer Aided Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Aided Detection Market Analysis
Hospital procurement of computer aided detection systems is collapsing toward centralized radiology departments and away from fragmented clinic-level purchasing. Siemens Healthineers AG leverages its installed base of imaging modalities to bundle CAD software across European and North American accounts. GE Healthcare anchors its position through tight integration with PACS workflows and enterprise imaging contracts. iCAD Inc. specializes in mammography CAD, competing on breast density assessment algorithms that differentiate its offerings from full-line competitors.
Computer aided detection comprises software algorithms that analyze medical images to flag suspicious regions for radiologist review, typically processing DICOM-standard outputs from CT, MRI, mammography, and ultrasound systems with sensitivity thresholds calibrated per clinical indication. Its primary purpose is reducing false-negative rates in cancer screening programs and accelerating interpretation throughput in high-volume diagnostic environments. Deep learning architectures now dominate technology development, displacing earlier rule-based pattern recognition systems as convolutional neural networks demonstrate superior lesion detection accuracy in pulmonary and breast imaging applications. Mammography represents the most mature product segment with established reimbursement codes, while computed tomography CAD for lung nodule assessment captures the fastest growth trajectory driven by lung cancer screening program expansions.
FDA premarket notification pathways for AI/ML-based software as a medical device shape commercial timelines and clinical validation requirements for entrants targeting the United States. EMA's Medical Device Regulation and CE marking obligations under MDR impose conformity assessment burdens that filter software-only vendors from European hospital procurement shortlists. ISO 13485 quality management certification and IEC 62304 software lifecycle standards function as baseline qualifications for tenders across OECD healthcare systems. Stakeholders must monitor evolving FDA guidance on predetermined change control plans, as this framework will determine whether algorithm updates require new regulatory submissions or proceed under continuous learning protocols.
Market Dynamics
Deep learning architectures are decomposing the competitive moat of established CAD vendors by enabling algorithmic parity from software-only entrants without legacy imaging hardware ties.
Growth Catalysts
- Lung Cancer Screening Expansion:National screening program rollouts in the United States and Japan are generating installed base demand for CT nodule detection algorithms. Radiology departments prioritize sensitivity-optimized tools to minimize false-negative liability in high-volume programs.
- FDA Predetermined Change Control Plans:The agency's guidance on continuous learning protocols reduces regulatory friction for algorithm updates. Developers deploy model improvements without full premarket resubmission cycles.
- DICOM Standardization:Universal image format compatibility enables plug-and-play software deployment across multi-vendor imaging fleets. Hospital IT departments favor CAD solutions that integrate without PACS replacement.
Market Restraints
- CE Marking Burden Under MDR:EMA's Medical Device Regulation imposes clinical evidence requirements that strain software-only vendors without bench testing infrastructure. Conformity assessment timelines extend 18-24 months for novel algorithms.
- Radiologist Workflow Friction:Alert fatigue from high-sensitivity thresholds degrades user acceptance. Departments disable flagging features when false-positive rates exceed 15% on retrospective audits.
- Reimbursement Code Gaps:CT and MRI CAD lack established CPT codes in most OECD markets. Hospitals absorb software costs through operational budgets rather than procedure-based revenue.
Strategic Opportunities
- India Diagnostic Imaging Growth:Private hospital chains in Mumbai and Delhi are deploying teleradiology networks that centralize AI-assisted interpretation. CDSCO's streamlined software medical device pathway accelerates commercial entry relative to MDR timelines.
- Point-of-Care Ultrasound Integration:Handheld probe manufacturers are embedding real-time lesion detection for emergency and primary care settings. Algorithm miniaturization for edge compute deployment opens ambulatory channels outside hospital radiology.
- EU AI Act Conformity:High-risk medical device classification creates first-mover advantage for vendors with established quality management systems. CE marking under MDR satisfies core AI Act technical documentation requirements.
Industry Challenges
- Algorithm Validation Data Scarcity:Multi-site prospective studies require 10,000-plus annotated cases per indication. Academic medical centers control access to curated datasets, extracting collaboration fees or co-development equity.
- PACS Integration Complexity:Legacy enterprise imaging platforms from 2015-2019 vintages lack API architectures for real-time AI orchestration. Middleware development consumes 30-40% of implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Aided Detection Market |
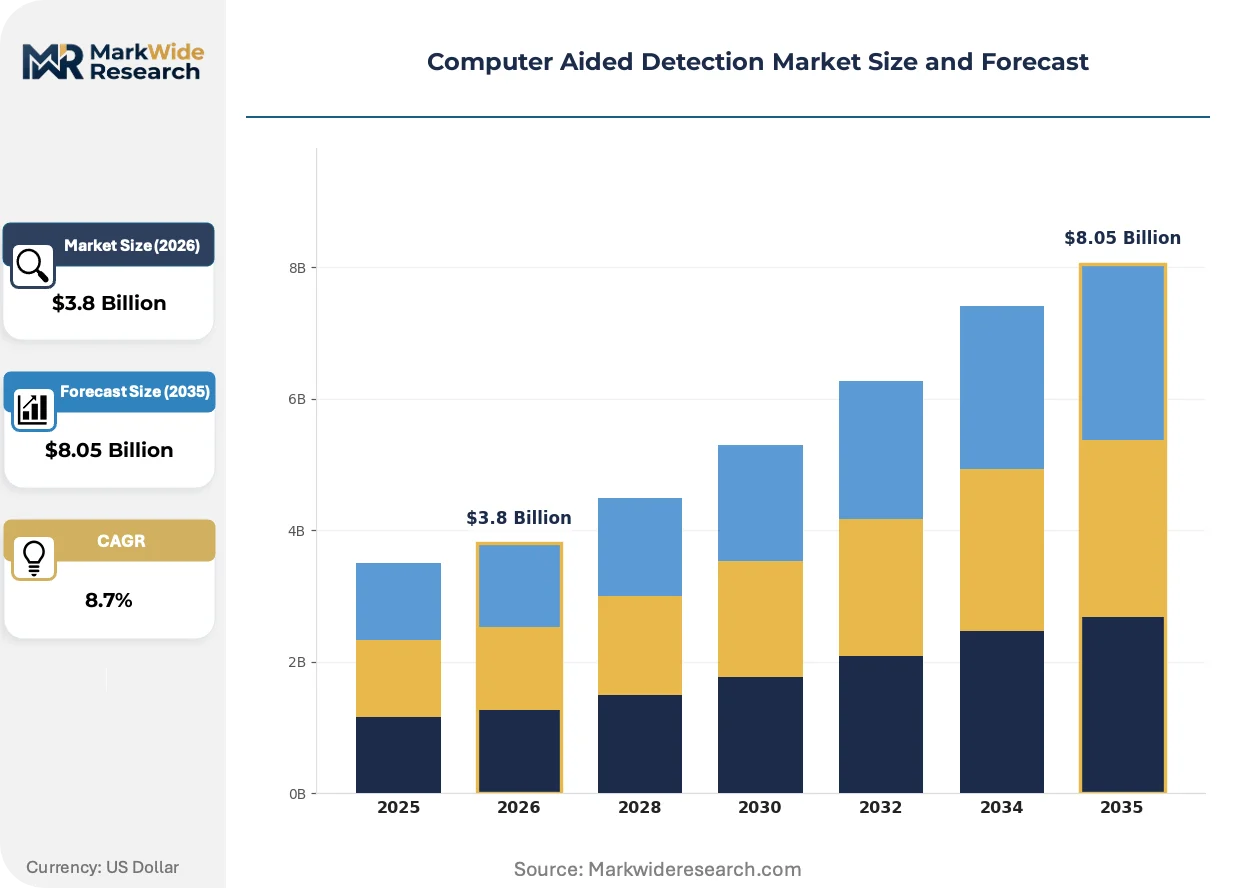
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mammography, Computed Tomography, MRI, Ultrasound Technology: Deep Learning, Machine Learning, Image Analysis, Pattern Recognition End User: Hospitals, Diagnostic Centers, Research Institutes, Radiology Clinics Application: Cancer Detection, Cardiovascular Screening, Neurological Assessment, Pulmonary Examination |
| Companies Covered | FUJIFILM Holdings Corporation, GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., Hologic Inc., iCAD Inc., EDDA Technology Inc., Canon Medical Systems Corporation, Riverain Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Aided Detection Market Emerging Trajectories
Federated learning frameworks and regulatory sandboxes are compressing development cycles while fragmenting competitive advantage across specialized algorithm developers rather than integrated modality vendors.
Convolutional neural network architectures are decomposing the traditional CAD value chain by separating image preprocessing, feature extraction, and clinical decision support into modular components. Academic medical centers in Boston and Heidelberg are assembling best-of-breed pipelines rather than purchasing monolithic platforms. This componentization is compressing vendor margins on standalone detection software while expanding addressable market for specialized training data and annotation services.
EMA's Medical Device Regulation is mandating post-market surveillance systems that track algorithm performance across deployed sites. Software vendors must establish quality management systems capturing real-world sensitivity metrics and adverse event reporting. Breast imaging applications face the steepest compliance burden due to established screening program infrastructure and litigation exposure in German and French markets.
Radiology group purchasing organizations are consolidating software procurement decisions across multi-hospital systems. Banner Health and Kaiser Permanente in the United States are negotiating enterprise licenses spanning 20-plus facilities, displacing site-by-site purchasing. This concentration shifts bargaining power toward buyers and compresses implementation service margins for vendors competing on deployment support rather than algorithm differentiation.
Computer Aided Detection Market Segmentation
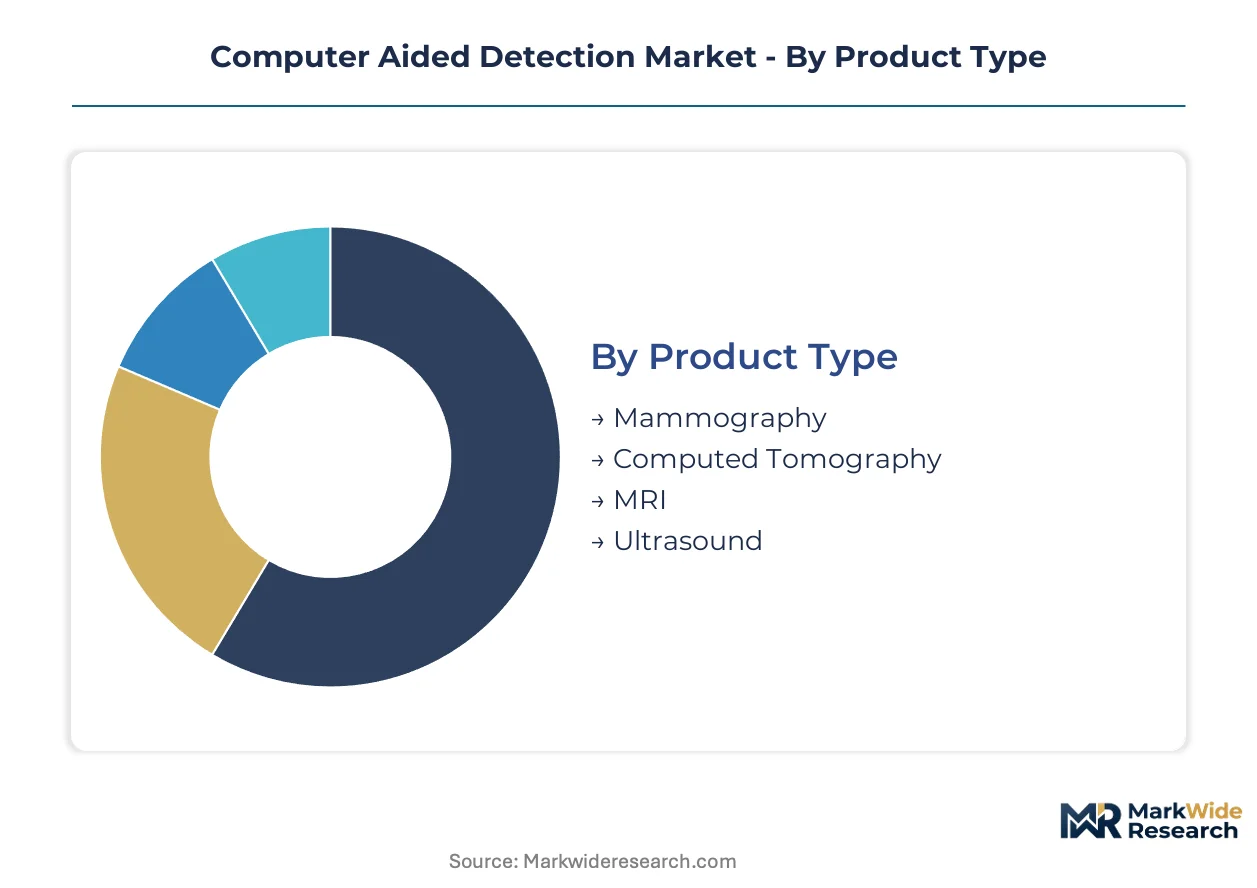
Segmentation in computer aided detection reveals distinct procurement patterns across imaging modalities and care settings. Hospital radiology departments prioritize sensitivity-optimized tools for high-volume screening programs, while diagnostic centers favor workflow-integrated solutions that minimize interpretation time.
Product Type:
Mammography CAD dominates domestic procurement in established screening markets, while CT and ultrasound systems drive export-led expansion into emerging diagnostic networks.
- Computed Tomography:Algorithms process DICOM-standard chest CT outputs to flag pulmonary nodules with calibrated sensitivity thresholds. Demand concentrates in United States and Japanese hospital systems where national lung cancer screening programs mandate high-volume interpretation throughput.
- Mammography:Breast density assessment algorithms analyze full-field digital mammography outputs, with established CPT reimbursement codes supporting procurement in German and French screening programs. FDA premarket clearance pathways streamline commercial entry for sensitivity-optimized tools.
- MRI:Neurological and musculoskeletal applications leverage convolutional neural networks for lesion detection in multi-sequence protocols.
- Ultrasound:Real-time embedded algorithms for handheld probe systems enable point-of-care deployment in emergency and primary care settings.
Mammography holds the largest share; momentum sits with computed tomography.
Technology:
Deep learning architectures command premium pricing tiers, while pattern recognition systems persist in cost-sensitive installations.
- Deep Learning:Convolutional neural networks demonstrate superior lesion detection accuracy in pulmonary and breast imaging, displacing earlier rule-based systems. Academic medical centers in Boston and Heidelberg assemble modular pipelines separating preprocessing, feature extraction, and clinical decision support.
- Machine Learning:Supervised classification algorithms with structured feature engineering retain deployment in legacy PACS environments lacking API architectures for real-time AI orchestration.
- Image Analysis:Quantitative morphometry and texture analysis tools support specific clinical indications with deterministic output requirements.
- Pattern Recognition:Rule-based detection systems persist in installed base maintenance contracts and regulatory jurisdictions with stringent algorithm validation requirements.
Deep learning holds the largest share; pattern recognition is losing share fastest.
End User:
Hospital procurement concentrates in centralized radiology departments, while diagnostic centers and research institutes fragment across specialized applications.
- Hospitals:Enterprise imaging contracts bundle CAD software across multi-facility systems, with Banner Health and Kaiser Permanente negotiating licenses spanning 20-plus sites. Radiology group purchasing organizations consolidate decisions across hospital systems, compressing implementation service margins.
- Diagnostic Centers:Teleradiology networks in Mumbai and Delhi centralize AI-assisted interpretation, with CDSCO's streamlined software medical device pathway accelerating commercial entry.
- Radiology Clinics:Site-by-site purchasing persists in fragmented markets, though procurement is collapsing toward centralized department-level decisions.
- Research Institutes:Academic medical centers control access to curated datasets, extracting collaboration fees or co-development equity from algorithm developers.
Hospitals hold the largest share; diagnostic centers are expanding most quickly.
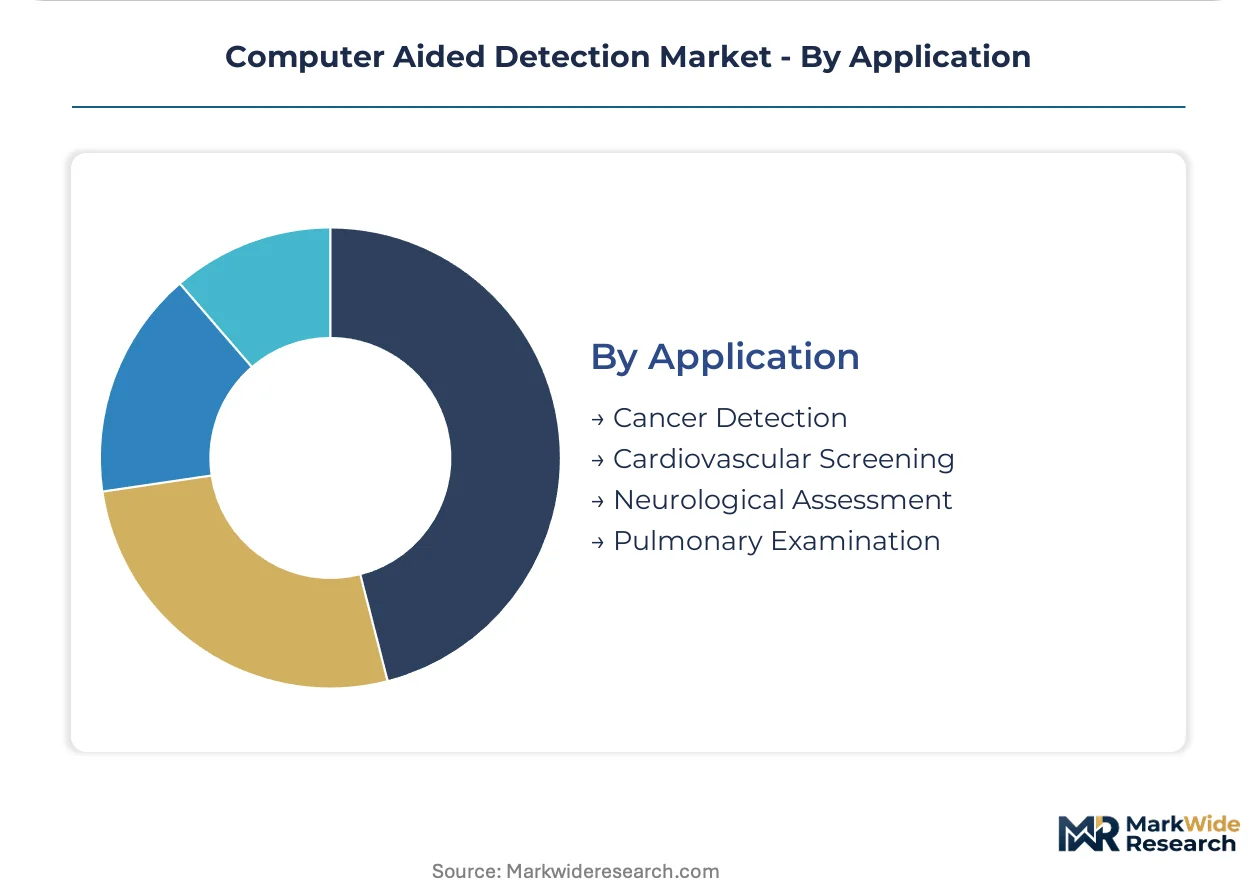
Application:
Cancer detection applications carry established reimbursement frameworks, while cardiovascular and neurological screening absorb costs through operational budgets.
- Cancer Detection:Breast and lung screening programs generate installed base demand with sensitivity-optimized tools minimizing false-negative liability. EMA's Medical Device Regulation mandates post-market surveillance tracking algorithm performance across deployed German and French sites.
- Pulmonary Examination:CT nodule detection algorithms capture the steepest expansion trajectory driven by screening program rollouts in United States and Japan.
- Cardiovascular Screening:Coronary artery calcium scoring and plaque characterization lack established CPT codes in most OECD markets.
- Neurological Assessment:Stroke detection and dementia screening applications face algorithm validation data scarcity, requiring 10,000-plus annotated cases per indication.
Cancer detection holds the largest share; pulmonary examination is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors regional demand through its extensive teleradiology backbone connecting academic medical centers in Boston, Baltimore, and Houston to distributed screening networks. FDA premarket clearance pathways for AI/ML-based software as medical device streamline commercial entry for algorithm developers targeting lung cancer screening expansion.
United States
National lung cancer screening program rollouts drive CT nodule detection procurement across Veterans Affairs and Medicare networks. FDA predetermined change control plans reduce regulatory friction for continuous algorithm learning. The Boston-Heidelberg corridor concentrates academic medical center partnerships controlling curated training datasets.
Germany
Breast cancer screening infrastructure generates installed base demand for mammography CAD with sensitivity-optimized tools. EMA Medical Device Regulation mandates post-market surveillance tracking algorithm performance across deployed sites. The Rhine-Ruhr metropolitan region hosts Siemens Healthineers AG bundling software across European hospital accounts.
Japan
National health insurance reimbursement frameworks for computer-aided diagnosis support procurement in high-volume screening programs. PMDA streamlined review pathways for AI-based diagnostic software accelerate commercial timelines. Tokyo-Osaka metropolitan corridors concentrate radiology department consolidation and enterprise imaging contract negotiations.
India
Private hospital chains in Mumbai and Delhi deploy teleradiology networks centralizing AI-assisted interpretation for tier-two cities. CDSCO streamlined software medical device pathway accelerates commercial entry relative to European MDR timelines. Karnataka's Bangalore cluster attracts algorithm development centers serving domestic and export markets.
Computer Aided Detection Market Vendor Landscape
Concentration sits with integrated imaging modality manufacturers leveraging hardware-installed bases to bundle CAD software across enterprise contracts. Siemens Healthineers AG and GE Healthcare anchor this tier through tight PACS workflow integration. Three strategic archetypes structure competition: full-line modality vendors, specialized algorithm developers, and software-only entrants deploying deep learning architectures. Dominant competitive moves include strategic partnerships with academic medical centers for dataset access and portfolio diversification into point-of-care ultrasound integration.
Within the full-line modality tier, Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips N.V. occupy positions bundling detection software across European and North American hospital systems. Specialized algorithm developers exemplified by iCAD Inc. represent the breast imaging concentration, differentiating on density assessment capabilities distinct from full-line competitors. Riverain Technologies and EDDA Technology Inc. sit within the pulmonary and general imaging specialization vectors respectively.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Hologic Inc. |
| iCAD Inc. |
| EDDA Technology Inc. |
| Canon Medical Systems Corporation |
| Riverain Technologies |
| Others |
Supply Flow & Price Mechanics
Installed base economies in imaging hardware anchor pricing power for bundled CAD software, concentrating margin leverage among Siemens Healthineers AG and GE Healthcare while compressing standalone algorithm vendors into subscription-tier competition. Scale advantages in PACS integration and enterprise contracting create price floors that software-only entrants cannot match without multi-site validation investments.
Pricing Analysis
Volume-discount tiering structures separate enterprise imaging contracts spanning 20-plus hospital sites from single-department licenses and pay-per-study arrangements. Premium-mid-economy pricing differentiation rests on FDA premarket clearance tier, ISO 13485 certification status, and bundled implementation support. Cost compression in the standalone software tier is intensifying because radiology group purchasing organizations consolidate procurement decisions across multi-hospital systems. Diagnostic centers in teleradiology networks exhibit highest price sensitivity, while academic medical centers prioritize sensitivity-optimized tools with established reimbursement codes.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native CAD vendors, while strategic stockpiling of regulatory documentation and curated training datasets characterizes established players preparing for EMA post-market surveillance mandates. Algorithm development draws from GPU cloud compute clusters concentrated in the United States, Germany, and India, with annotation services anchored in Bangalore and Hyderabad. Single-source vulnerability sits with academic medical centers controlling access to 10,000-plus annotated case datasets. Distribution runs through PACS middleware layers and enterprise imaging platforms rather than direct hospital IT procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm validation data scarcity and regulatory pathway expertise constitute the critical capability gaps separating viable competitors from marginal vendors in this market.
For Market Incumbents: Consolidate dataset access through exclusive partnerships with academic medical centers in Boston and Heidelberg, locking out emerging entrants from curated training repositories. Deepen PACS workflow integration to raise switching costs for hospital systems evaluating best-of-breed alternatives. FDA predetermined change control plan investments anchor regulatory moats against software-only competitors lacking quality management infrastructure. For New Entrants and Emerging Players: Lead with point-of-care ultrasound embedded algorithms for emergency and primary care settings, bypassing entrenched hospital radiology procurement channels. CDSCO's streamlined software medical device pathway in India offers the most penetrable regulatory entry relative to EMA MDR timelines. Teleradiology networks in Mumbai and Delhi provide go-to-market traction without enterprise imaging contract complexity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized algorithm developers with FDA-cleared pulmonary or breast imaging assets over full-line modality vendors facing margin compression in hardware. Long-term viability hinges on continuous learning protocol capabilities and post-market surveillance infrastructure. The signal to watch is CMS reimbursement code expansion for CT and MRI CAD applications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan | Enables algorithm updates without full premarket resubmission, accelerating Siemens Healthineers deployment cycles. |
| Academic Medical Center Partnership | Secures curated training datasets from Boston and Heidelberg clusters, extracting co-development equity from algorithm vendors. |
| PACS Workflow Integration | Tight GE Healthcare enterprise imaging contracts embed CAD software through API architectures, raising hospital switching costs. |
| Point-of-Care Ultrasound Embedding | Handheld probe manufacturers open ambulatory channels outside hospital radiology through real-time lesion detection miniaturization. |
| CE Marking Under MDR | Satisfies EU AI Act technical documentation requirements for high-risk medical device classification, creating first-mover advantage. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EMA MDR conformity assessments, and hospital procurement databases. Primary interviews engaged radiology department heads, biomedical engineers, GPO contracts managers, and regulatory affairs leads at algorithm developers. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification registries, and DICOM standard committee documentation. Bottom-up installed base estimates triangulate against top-down screening program volume projections.
Segmentation dimensions modeled span imaging modality, technology architecture, end-user facility type, and clinical application across the projection horizon. Deep learning versus pattern recognition technology splits, hospital versus diagnostic center procurement channels, and cancer detection versus cardiovascular screening applications structure the analytical framework. CAGRs derive from algorithm adoption curves in lung cancer screening programs and mammography density assessment reimbursement expansion. Forecast inputs incorporate PACS replacement cycles and teleradiology network buildouts.
Underlying assumptions cover FDA guidance continuity on continuous learning protocols, with deviation risk concentrated in EMA MDR timeline extensions and radiologist workflow acceptance thresholds. Revision becomes warranted when false-positive rate audit findings cross 15% disabling thresholds or when CMS establishes new CPT codes for CT CAD applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Holographic Imaging Market
Imaging
Global 3D Camera Market
Imaging
Global Camera Module Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Virtual Reality Camera Market
Imaging
X Ray Tubes Market
Imaging
Multimodal Imaging Market
Imaging
North America Image Sensors Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Photography Equipment Market
Imaging
Hyperspectral Cameras Market
Imaging
Europe Image Sensors Market
Imaging
Mobile Imaging Market
Imaging
Instant Digital Cameras Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Middle East and Africa Image Sensors Market