
 Video Microscopes Market | 2026-2036
Video Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Video Microscopes Market Intelligence
The European Union's Medical Device Regulation (MDR) is restructuring the compliance burden for video microscopes used in healthcare facilities. This regulatory shift favors established vendors with deep documentation and quality management systems. Carl Zeiss AG leverages its extensive optics legacy to serve high-end research and medical segments. Meanwhile, Keyence Corporation differentiates through its focus on integrated digital solutions for industrial quality control applications.
A video microscope integrates a digital camera with traditional microscope optics to display a magnified image on a screen, eliminating the need for eyepieces. These systems rely on high-resolution CMOS sensors and specialized imaging software to capture, analyze, and store images. Within applications, semiconductor inspection demands the highest precision and automation capabilities. Industrial microscopes represent the largest product type, driven by quality control requirements in manufacturing units across automotive and electronics.
Beyond the EU's MDR, manufacturers must adhere to ISO 9001 for quality management and may require FDA clearance for specific medical diagnostic uses in the United States. These standards dictate design, manufacturing, and documentation protocols, influencing market access. The critical decision for system integrators and end-users involves balancing the upfront cost of advanced imaging software with the long-term benefits of improved inspection accuracy and data management.
Market Dynamics
The central force shaping the video microscope market is the convergence of high-resolution CMOS imaging with automated, software-driven analytics. This fusion moves inspection from a manual, qualitative task to a quantitative, data-rich process critical for advanced manufacturing.
Growth Catalysts
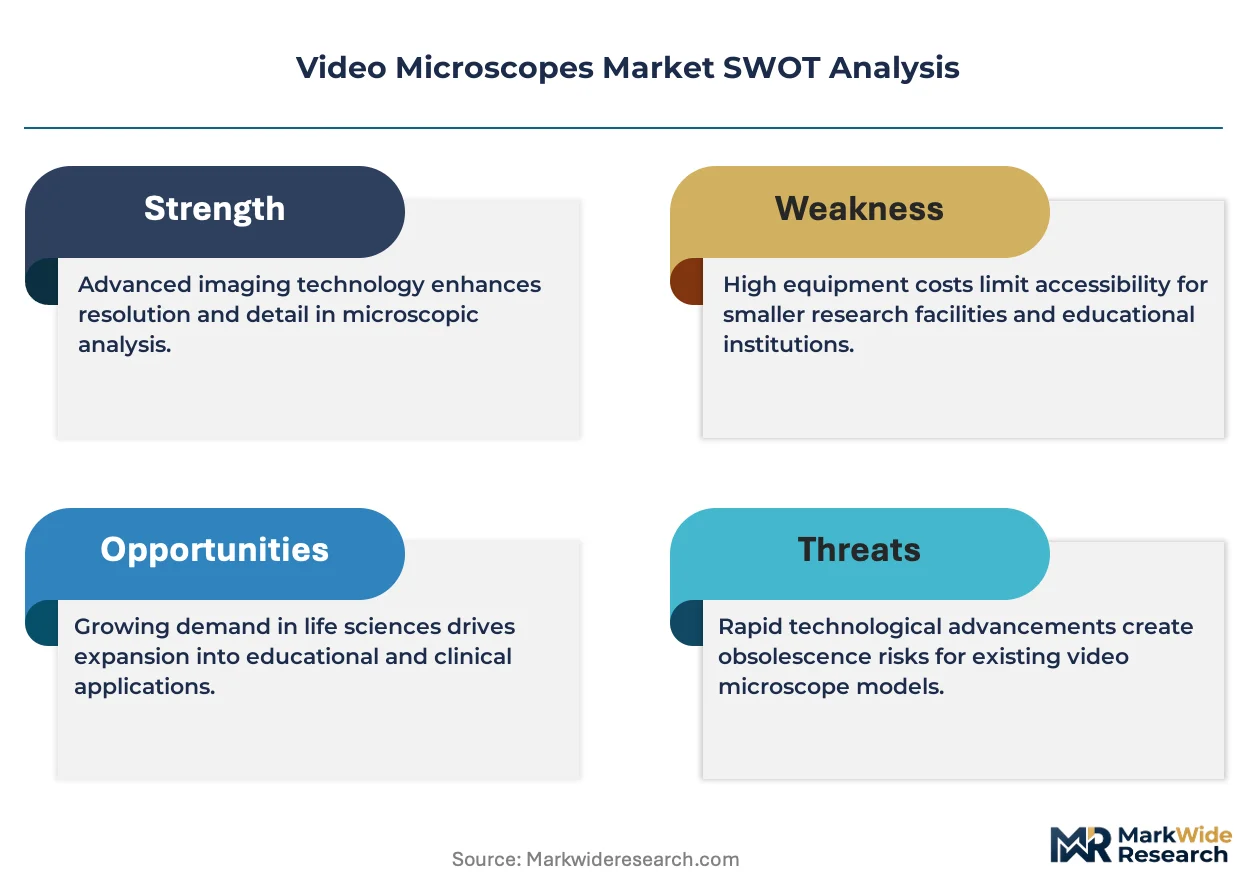
- Semiconductor Miniaturization:Continuous reduction in transistor size for advanced logic and memory chips drives demand for higher-magnification, automated inspection systems, particularly within the manufacturing clusters of Taiwan and South Korea.
- Medical Device Regulation:The European Union's stringent Medical Device Regulation (MDR) creates a significant catalyst for high-end, fully documented video microscopes used for quality control and R&D in healthcare manufacturing.
- Automotive Electronics Complexity:The expansion of advanced driver-assistance systems (ADAS) and complex infotainment units in vehicles necessitates rigorous microscopic inspection of PCBs, connectors, and micro-electromechanical systems (MEMS) to ensure reliability.
Market Restraints
- High Total Cost of Ownership:The significant upfront investment required for systems featuring advanced metrology software, automation capabilities, and ergonomic accessories acts as a barrier for small and medium-sized enterprises in industrial sectors.
- CMOS Sensor Supply Concentration:The global supply of high-performance, low-noise CMOS image sensors is dominated by a few key manufacturers, creating potential vulnerability to price fluctuations and supply chain disruptions for microscope vendors.
- Threat from AOI Systems:In high-volume electronics assembly lines, dedicated Automated Optical Inspection (AOI) systems offer higher throughput for standardized inspection tasks, presenting a substitution threat for certain video microscope applications.
Strategic Opportunities
- Industrial Expansion in Emerging Economies:Growth in manufacturing investment, particularly in electronics and automotive components within Southeast Asia and Eastern Europe, presents an untapped market for mid-range industrial video microscope systems.
- Life Science and Pharmaceutical Applications:There is a significant opportunity in applying video microscopy to cell culture monitoring, sterile fill-finish inspection, and medical textile analysis, where documentation and high-resolution imaging are critical.
- AI-Powered Defect Classification:Integrating machine learning algorithms into imaging software to automate defect detection and classification offers a path to create high-value, subscription-based analytical services for industrial quality control.
Industry Challenges
- Software Integration Complexity:A primary operational challenge is ensuring the seamless integration of proprietary microscope software with a customer's existing Manufacturing Execution Systems (MES) and enterprise-level quality management platforms.
- Regulatory Compliance Timelines:Navigating the lengthy and resource-intensive validation processes for standards such as the EU's MDR or specific FDA clearances for diagnostic use delays market entry for new medical-grade products.
- Data Management Infrastructure:The large file sizes of high-resolution images and 3D datasets create significant challenges for network bandwidth, secure data storage, and archival, especially in regulated GxP environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Microscopes Market |
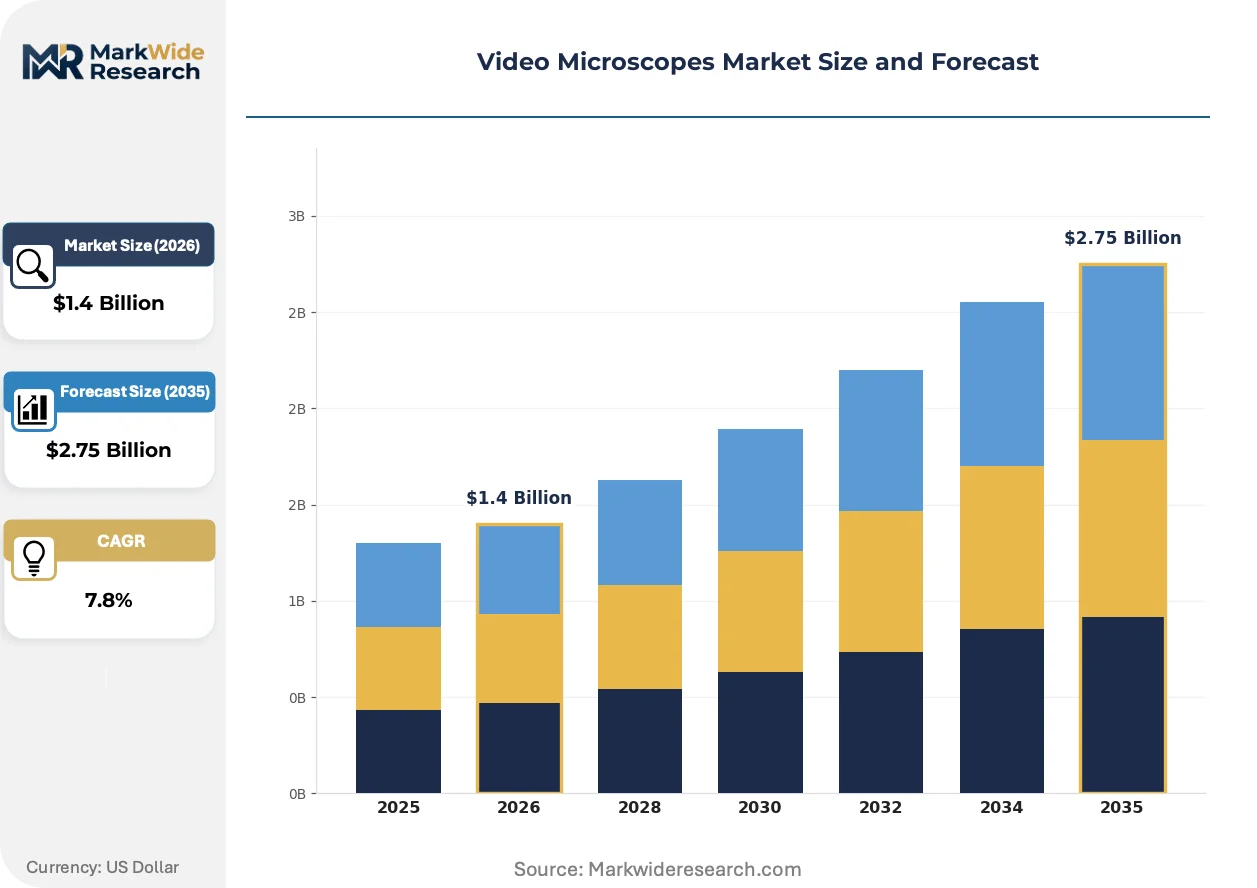
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Microscopes, USB Microscopes, Portable Microscopes, Industrial Microscopes Application: Biological Research, Semiconductor Inspection, Quality Control, Education End User: Laboratories, Educational Institutions, Manufacturing Units, Healthcare Facilities Technology: Microlens Systems, CMOS Sensors, LED Illumination, Imaging Software |
| Companies Covered | Olympus Corporation, Nikon Instruments Inc., Carl Zeiss AG, Leica Microsystems, Keyence Corporation, Hirox Co., Ltd., Hitachi High-Technologies Corporation, Thermo Fisher Scientific Inc., Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Microscopes Market Strategic Shifts & Innovations
Software-defined capabilities are transforming video microscopy from a hardware-centric imaging tool into an integrated data analytics platform. The fusion of computational techniques with advanced optics enables new levels of inspection accuracy and automation, reshaping workflows in quality control.
Computational imaging uses algorithms to reconstruct images or extract data beyond the physical limitations of the optical hardware. Semiconductor and microelectronics manufacturers are rapidly adopting these techniques to resolve sub-micron features without cost-prohibitive optical upgrades. This software-centric approach is absorbing functions previously performed by more expensive, specialized metrology instruments, thereby reducing overall system cost.
The ISO 13485 standard for medical device quality management systems is exerting significant influence on the market. This regulation mandates rigorous process controls and full lifecycle traceability, including for all inspection and testing equipment. This affects medical device manufacturers most profoundly, forcing them to select video microscopes from vendors that provide comprehensive validation packages and auditable software.
End-users are increasingly procuring fully integrated inspection solutions rather than purchasing standalone microscope hardware and separate third-party software. This behavioral shift disrupts the traditional reseller channel, which often bundled components, and favors vendors offering a complete, pre-validated stack. The trend is most visible in regulated sectors like aerospace and medical devices, where system-level validation is non-negotiable for compliance.
Video Microscopes Market Segmentation
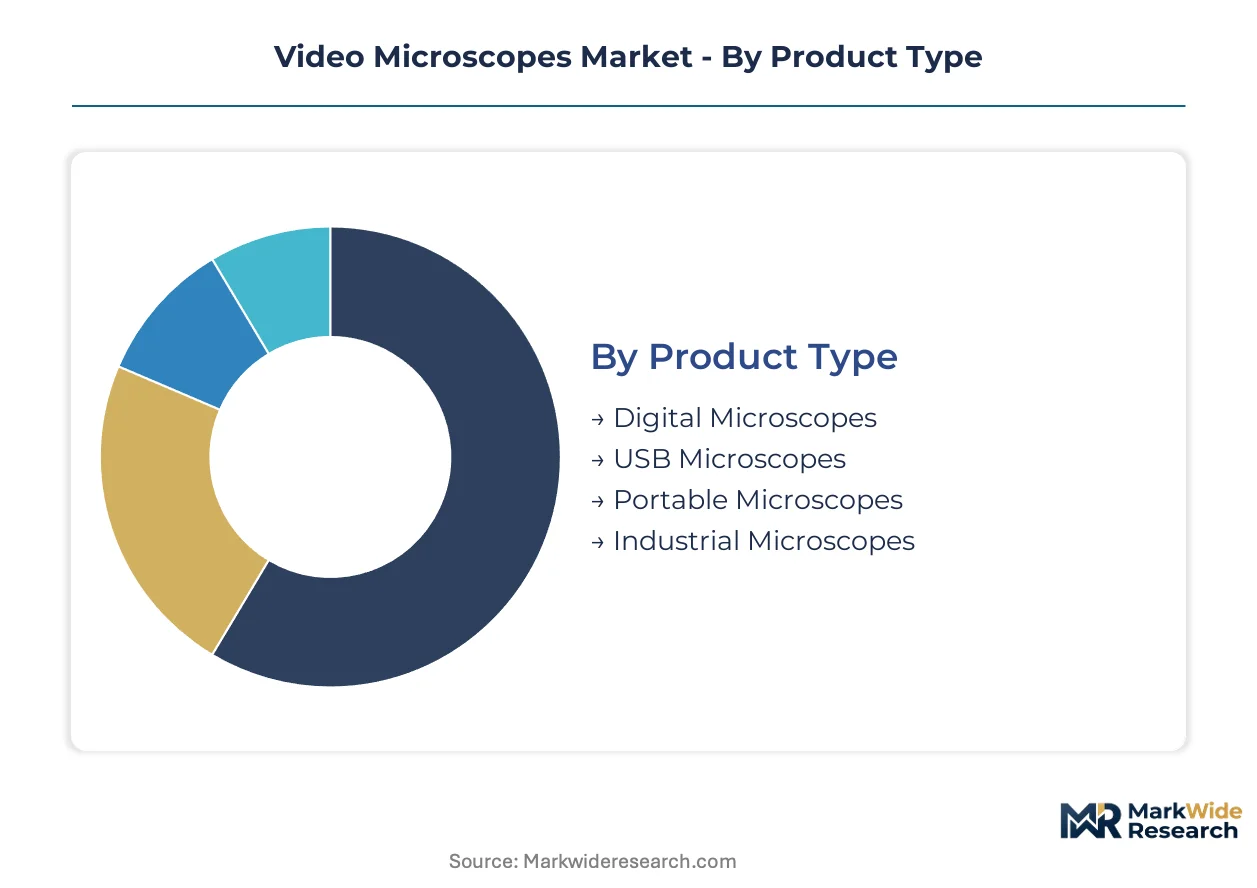
The video microscopes market segmentation reveals distinct buyer needs and technological preferences across various industrial and scientific domains. Understanding these segments is crucial for manufacturers to tailor product development, refine market strategies, and address specific regulatory requirements. This granular view helps identify areas of concentrated demand and emerging growth opportunities.
Product Type:
Buyers in the product type segment differentiate primarily by the form factor and core functionality required for their operational environment.
- Industrial Microscopes:These robust systems are engineered for continuous operation in manufacturing environments, providing high-magnification imaging for quality control and defect analysis on production lines. Demand for industrial microscopes concentrates in electronics and automotive manufacturing units, driven by stringent quality standards and high-volume inspection needs.
- Digital Microscopes:Integrating a digital camera with optical components, these microscopes display magnified images directly on a screen, eliminating eyepieces. Semiconductor inspection facilities in Taiwan and South Korea represent a significant demand cluster, requiring digital systems for precise sub-micron feature analysis.
- Portable Microscopes:Designed for field use or flexible inspection tasks, these compact devices offer mobility and convenience for on-site analysis.
- USB Microscopes:These entry-level digital microscopes connect directly to a computer via USB, suitable for basic inspection and educational applications.
Volume sits with Industrial Microscopes; growth tilts toward Digital Microscopes.
Application:
Application segments delineate where video microscopes are deployed, reflecting specific operational requirements and analytical objectives.
- Semiconductor Inspection:This application demands ultra-high resolution and automated defect detection capabilities for micro-scale components on wafers and chips. Manufacturers in key Asian semiconductor hubs require these systems to ensure the integrity of advanced logic and memory devices.
- Quality Control:Video microscopes in quality control ensure product integrity and adherence to specifications across diverse manufacturing sectors. Automotive electronics production and medical device assembly lines represent critical areas for these precise inspection tools.
- Biological Research:These systems support cell culture monitoring, tissue analysis, and other life science investigations, providing magnified views for scientific discovery.
- Education:Educational institutions utilize video microscopes for teaching and student learning, offering visual engagement and collaborative viewing experiences in classrooms.
Demand is concentrated in Quality Control while Semiconductor Inspection exhibits significant expansion.
End User:
Customer types define the primary organizations leveraging video microscope technology, influencing purchasing criteria and service expectations.
- Manufacturing Units:These entities, spanning electronics, automotive, and aerospace, employ video microscopes for in-process inspection and final product quality assurance. The need for rigorous quality checks on complex components drives substantial investment in these inspection tools.
- Healthcare Facilities:Hospitals, clinics, and medical device manufacturers use video microscopes for diagnostic imaging, surgical assistance, and R&D. Compliance with regulations like the EU's MDR heavily influences technology adoption in this sector.
- Laboratories:Research and analytical laboratories across various disciplines utilize video microscopes for detailed sample examination and data collection.
- Educational Institutions:Universities, colleges, and schools integrate video microscopes into science curricula for hands-on learning and visual demonstration.
The primary adoption comes from Manufacturing Units, with Healthcare Facilities showing accelerated interest.
Technology:
Technological maturity within the video microscope market dictates performance capabilities and potential for future innovation.
- CMOS Sensors:These high-resolution digital imaging components are fundamental to modern video microscopes, enabling detailed image capture and analysis. Continuous miniaturization of CMOS sensors drives improvements in imaging quality and device compactness for various applications.
- Imaging Software:Specialized software processes raw image data, provides measurement tools, and automates defect detection, transforming microscopes into analytical platforms. The integration of AI-powered algorithms offers significant opportunities for enhanced industrial quality control.
- Microlens Systems:These miniature optical components are integrated into compact video microscopes, enabling high magnification within constrained form factors.
- LED Illumination:Light Emitting Diodes provide efficient, long-lasting, and cool illumination for samples, enhancing image clarity and reducing heat-related damage.
Fundamental capabilities are provided by CMOS Sensors, but differentiation increasingly stems from Imaging Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global video microscopes market exhibits strong regional concentration, particularly within advanced manufacturing hubs. Science Parks in Taiwan, such as Hsinchu Science Park, and South Korea's Gyeonggi Province, drive demand for high-precision inspection tools. These zones foster innovation and require sophisticated equipment for semiconductor production.
Taiwan
Demand for video microscopes in Taiwan stems from continuous miniaturization of semiconductor components and advanced packaging technologies. The government's "Taiwan Advanced Semiconductor Manufacturing" initiative supports cutting-edge R&D. Hsinchu Science Park remains a critical hub, where major foundries utilize video microscopes for sub-micron feature analysis and quality control.
South Korea
South Korea's robust electronics manufacturing and semiconductor industry fuel significant demand for integrated digital video microscope solutions. The Ministry of Trade, Industry and Energy (MOTIE) promotes investment in advanced display and memory chip production. Gyeonggi Province, home to major tech conglomerates, sees extensive deployment of these systems for quality assurance.
Germany
European demand for video microscopes concentrates in Germany, driven by its strong automotive, medical device, and precision engineering sectors. The EU's Medical Device Regulation (MDR) mandates rigorous quality control for healthcare products. Bavaria and Baden-Württemberg, with their high-tech manufacturing clusters, are key areas for advanced industrial microscopy.
United States
The United States market for video microscopes benefits from extensive R&D in life sciences, advanced electronics, and aerospace manufacturing. FDA clearance requirements for medical diagnostic devices influence product development. Silicon Valley and the Boston-Cambridge biotech corridor are critical regions for high-resolution imaging and analytical applications.
China
China's massive manufacturing base, particularly in electronics and automotive, generates substantial volume demand for industrial video microscopes. Government initiatives like "Made in China 2025" emphasize domestic innovation and quality upgrades. The Yangtze River Delta and Pearl River Delta regions are major production hubs requiring precise inspection tools.
Video Microscopes Market Key Industry Players
Japanese and European producers anchor one tier of the video microscopes market; North American specialists hold another. This market exhibits a tiered structure, with established optical companies competing alongside integrated digital solution providers. Strategic archetypes include high-precision optics manufacturers focusing on scientific research and industrial quality control, and software-centric analytical platform developers. Portfolio diversification into adjacent applications and strategic partnerships for system integration represent dominant competitive moves among market participants.
On the premium-tier vector, Carl Zeiss AG, a German Aktiengesellschaft, exemplifies a legacy optical manufacturer with extensive offerings for high-end research and medical segments. Keyence Corporation, a Japanese corporation, represents a specialist in integrated digital solutions for industrial quality control, emphasizing automation and software. Olympus Corporation, another Japanese corporation, occupies a position as a diversified provider, spanning life science, industrial, and medical applications with its microscopy portfolio. These entities collectively underscore the market's segmentation by application focus and technological heritage.
| Leading Market Players |
|---|
| Olympus Corporation |
| Nikon Instruments Inc. |
| Carl Zeiss AG |
| Leica Microsystems |
| Keyence Corporation |
| Hirox Co., Ltd. |
| Hitachi High-Technologies Corporation |
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| Others |
Cost & Logistics Intelligence
Continuous miniaturization of CMOS sensors simultaneously reshapes cost economics by demanding higher precision components and concentrates supply within specialized manufacturing hubs. This dynamic creates a complex interplay between component sourcing and final product pricing strategies for video microscope vendors.
Pricing Analysis
Premium pricing for video microscopes with short lead times reflects the high demand for immediate deployment in critical manufacturing lines. The dominant pricing structure for advanced systems is project-based, often incorporating subscription-based licensing for specialized imaging software. Price differentiation drivers include the system's certification level for regulated applications like ISO 13485 in medical devices, and the depth of integration with customer Manufacturing Execution Systems (MES). Pricing pressure stems from the competitive threat posed by high-throughput Automated Optical Inspection (AOI) systems in standardized tasks. Regulated sectors, such as medical device manufacturing, exhibit the least price sensitivity due to stringent compliance needs, while small and medium-sized enterprises remain most price-sensitive.
Supply Chain Analysis
Certification and qualification gating profoundly influence the video microscope supply chain, particularly for medical-grade optics and electronics. Geographic supply concentration centers on Taiwan and South Korea for high-resolution CMOS sensors, alongside Germany for specialized optical components. The supply chain relies heavily on high-performance digital image sensors, precision ground lenses, and advanced computational imaging software modules. A structural risk is the single-source vulnerability inherent in the concentrated supply of high-end CMOS image sensors. Distribution runs primarily through direct sales channels for complex integrated systems and specialized system integrators for custom solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The video microscopes market reads as a consolidation play, with the increasing complexity of regulatory compliance, such as the EU's MDR, forcing out smaller, less capitalized vendors. This pressure favors established players with robust quality management systems and deep documentation capabilities.
For Market Incumbents: Extend your leadership in regulated sectors by deepening R&D investment in AI-powered computational imaging and advanced metrology software. Acquire niche software firms specializing in defect classification algorithms to counter the throughput advantages of Automated Optical Inspection (AOI) systems. Prioritize comprehensive validation packages for medical-grade devices to meet stringent ISO 13485 standards, reinforcing market access in healthcare facilities.
For New Entrants and Emerging Players: AI-powered defect classification offers a technology-first wedge into the industrial quality control segment. Target underpenetrated manufacturing units in Southeast Asia and Eastern Europe with mid-range industrial video microscope systems featuring intuitive, integrated software. A compelling go-to-market angle involves offering subscription-based analytical services that provide actionable insights from inspection data, reducing upfront capital expenditure for end-users.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated solution providers offering comprehensive hardware-software-service packages for regulated industries. The market exhibits long-term viability driven by sustained demand for precision inspection in advanced manufacturing and life sciences over the next 5-10 years. Target acquisition archetypes include specialized software developers with expertise in computational imaging or AI for quality control. A signal to watch is the increasing investment by major foundries in integrated inspection solutions, indicating a shift towards fully automated quality assurance.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Software Integration | Enhances system capabilities beyond hardware, transforming microscopes into analytical platforms for industrial quality control. |
| Acquire AI Analytics Firms | Accelerates the development of automated defect detection and classification, addressing a critical need in semiconductor inspection. |
| Expand in Southeast Asia | Captures demand from growing electronics and automotive manufacturing investments in emerging economies. |
| Invest in ISO 13485 Certification | Secures market access and strengthens competitive positioning within the highly regulated medical device manufacturing sector. |
| Form Strategic MES Partnerships | Ensures seamless integration with customer Manufacturing Execution Systems, critical for industrial quality control workflows. |
Research Approach
Independent corroboration across primary interviews with industry stakeholders, secondary validation from regulatory documents, and corporate financial reports underwrites the qualitative findings of this analysis. The study integrates insights from R&D directors, quality control managers, procurement specialists, and regulatory affairs leads across key manufacturing and healthcare sectors. Bottom-up and top-down triangulation methods were employed to ensure accuracy and consistency in market sizing and trend identification.
The analytical framework decomposes the rate of change across the analysis window, modeling market dynamics based on historical trends and projected technological advancements. Key segmentation dimensions modeled include product type, application, end-user, technology, and regional manufacturing clusters. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of supply-side capacity expansions and demand-side adoption patterns. Industry-specific forecast inputs include semiconductor fabrication plant investment cycles and medical device manufacturing output projections.
Several conditions sit outside the modeled scope, including unforeseen geopolitical trade policies impacting CMOS sensor supply and rapid, disruptive shifts in alternative inspection technologies. Forecasts reflect assumptions documented through extensive primary and secondary research, acknowledging potential variations. A model refresh is warranted upon material change in global manufacturing investment patterns or significant regulatory shifts in major markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Global Digital Photography Market
Imaging
Smart Camera Market
Imaging
360-Degree Camera Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Instant Digital Cameras Market
Imaging
Infrared Imaging Software Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Silent Scan Technology Market
Imaging
Virtual Reality Camera Market
Imaging
Fiducial Markers Market
Imaging
Microscope Digital Cameras Market
Imaging
CCD Image Sensors Market
Imaging
Machine Vision System and Services Market
Imaging
SDI Camera Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market