
 Pico Projector Market | 2026-2036
Pico Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Pico Projector Market Intelligence
Online direct-to-consumer channels is rewriting how compact projection hardware reaches buyers, bypassing traditional retail markups and accelerating replacement cycles. Texas Instruments leverages its DLP chipset monopoly to sustain pricing power across mid-tier and premium tiers. MicroVision competes through proprietary laser beam scanning architecture, while AAXA Technologies anchors the budget segment with LED-based portability.
A pico projector is a handheld or pocket-sized image projection device typically weighing under two pounds, employing solid-state light sources such as LEDs or lasers paired with LCoS, DLP, or MEMS micromirror arrays to render images between ten and one hundred diagonal inches. Its primary commercial purpose is enabling mobile, large-format visual display without fixed installation infrastructure. LED and laser product types now dominate unit shipments due to elimination of lamp replacement cycles and mercury disposal constraints. Digital Light Processing technology leads in brightness-per-watt efficiency, while Liquid Crystal on Silicon occupies niche premium positioning for color-accurate applications.
FCC certification governs electromagnetic emissions for US-bound devices, while the EU's RoHS and REACH frameworks restrict hazardous substances in optical engines and power supplies, directly influencing supplier qualification and redesign costs. China's GB standards and MIIT type-approval requirements add compliance layers for manufacturers targeting domestic volume. Stakeholders must monitor how converging laser safety classifications across FDA, IEC, and national health agencies reshape product roadmaps and regional launch sequencing.
Market Dynamics
Texas Instruments' DLP chipset monopoly and Shenzhen's MEMS manufacturing cluster are concentrating optical engine supply, while educational procurement and mercury-free mandates from the EU's Ecodesign Directive reshape downstream demand patterns.
Growth Catalysts
- Educational procurement:K-12 institutions and universities deploy portable classroom solutions for hybrid learning, eliminating fixed installation infrastructure.
- REACH compliance:The EU's restriction of hazardous substances in optical engines accelerates LED and laser transitions away from mercury-based lamps.
- Shenzhen manufacturing cluster:China's electronics hub drives cost-competitive MEMS and DLP module production, compressing bill-of-materials costs for mid-tier devices.
Market Restraints
- Input cost volatility:Rare earth elements in laser diodes and MEMS fabrication equipment face price swings tied to Chinese export quotas.
- Technical limitation:Thermal management constraints cap brightness-per-watt efficiency below 500 lumens for pocket-sized form factors without active cooling.
- Regulatory friction:FDA laser safety classifications and IEC 60825-1 compliance add six-to-nine month certification timelines for new product launches.
Strategic Opportunities
- Underpenetrated geography:India's tier-2 and tier-3 cities lack fixed projection infrastructure, creating white space for battery-powered portable units in coaching centers.
- Technology convergence:Integration of laser beam scanning with augmented reality waveguides opens enterprise training and field service applications.
- Channel innovation:Direct-to-consumer platforms bypass traditional retail markups, accelerating replacement cycles and capturing margin previously allocated to distributors.
Industry Challenges
- Skill scarcity:Optical engineers with MEMS fabrication expertise command premium compensation, constraining R&D expansion for mid-cap manufacturers.
- Certification complexity:Multi-jurisdictional compliance across FCC, CE marking, and China's MIIT type-approval fragments product roadmaps and delays regional launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pico Projector Market |
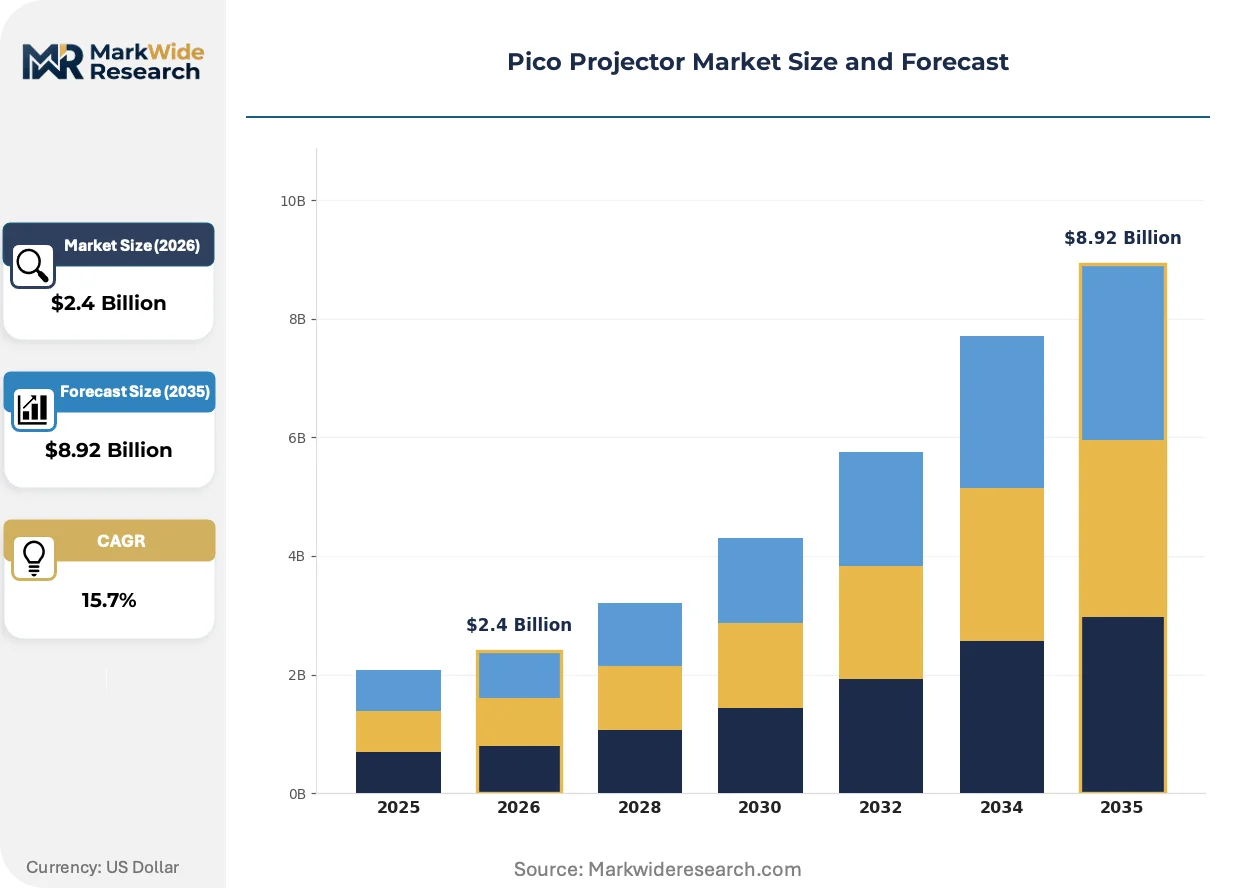
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lamp-Based, Laser, LED, DLP, LCD Technology: Micro-Electro-Mechanical Systems, Digital Light Processing, Liquid Crystal on Silicon, Laser Phosphor, Liquid Crystal Display Application: Home Entertainment, Education, Corporate Presentations, Gaming, Outdoor Events End User: Consumers, Educational Institutions, Enterprises, Event Organizers, Visual Artists |
| Companies Covered | AAXA Technologies, Inc., Texas Instruments, Inc., MicroVision, Inc., LG Electronics, Inc., Lenovo Group Limited, Coretronic Corporation, Syndiant, Inc., Celluon, Inc., Miroir, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pico Projector Market Strategic Shifts & Innovations
Laser beam scanning architectures and solid-state illumination are compressing form factors while regulatory pressure on mercury elimination accelerates technology transitions across all price tiers.
MEMS micromirror arrays paired with RGB laser sources are digitizing image formation by replacing mechanical color wheels and discrete DLP chips with single-chip solutions. Automotive head-up display developers and medical imaging OEMs adopt these architectures fastest, drawn by vibration tolerance and thermal stability. This convergence is digitizing supply chains by collapsing multiple component tiers into integrated optical subassemblies.
The EU's Ecodesign Directive and RoHS recast are tightening mercury-free illumination mandates for products placed on the European market. Manufacturers must redesign optical engines and power supplies to eliminate restricted substances or face market withdrawal. Premium color-accurate applications in Germany and France absorb these compliance costs most readily, while budget-tier suppliers delay EU launches pending redesign completion.
Enterprise buyers now unbundle hardware procurement from maintenance contracts, treating pico projectors as consumable peripherals rather than capital equipment. This pattern displaces traditional AV integrators with IT procurement channels and self-service deployment models. The shift is most visible in North American and Western European corporate training departments, where refresh cycles compress from five years to eighteen months.
Pico Projector Market Segmentation
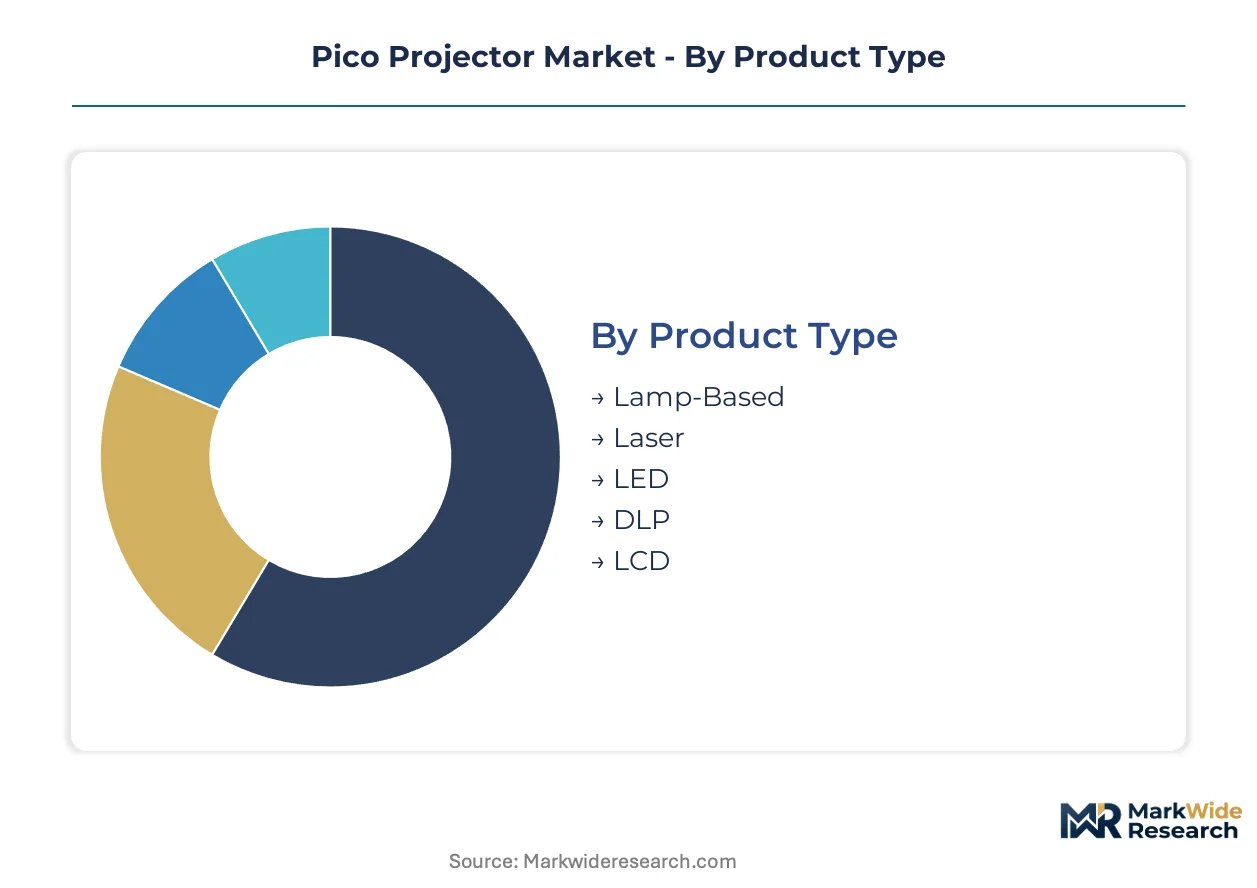
Pico projector procurement patterns diverge sharply across illumination technologies and deployment contexts. Service intensity, replacement cycles, and compliance burdens vary by segment, reshaping vendor engagement models and margin structures.
Product Type:
After-sales-service intensity correlates inversely with solid-state illumination adoption, as LED and laser architectures eliminate lamp replacement revenue streams that sustained legacy service contracts.
- Laser:RGB laser diodes paired with MEMS micromirror arrays deliver 500+ lumens in sub-200 gram enclosures. Demand clusters in Germany and France for color-critical medical imaging and architectural visualization, where REACH mercury bans and Ecodesign efficiency mandates accelerate premium procurement.
- LED:Phosphor-converted blue LEDs with DLP or LCoS engines dominate battery-powered portable units. Indian coaching centers and Indonesian mobile cinemas drive volume, prioritizing 10,000-hour lifespans and passive thermal designs over peak brightness.
- Lamp-Based:Mercury vapor arc lamps face regulatory phase-out across EU markets under RoHS recast timelines.
- DLP:Texas Instruments' micromirror chipsets anchor mid-tier and premium device architectures.
- LCD:Transmissive liquid crystal panels occupy budget positioning with lower optical efficiency tradeoffs.
By volume, LED leads. By growth pace, laser is ahead.
Technology:
Cost tier stratification separates integrated single-chip solutions from multi-component optical assemblies, with MEMS and DLP commanding premium positioning against LCD alternatives.
- Digital Light Processing:Micromirror arrays tilt thousands of times per second to modulate light, achieving highest brightness-per-watt efficiency. Shenzhen manufacturing clusters compress bill-of-materials costs for mid-tier DLP engines, while Texas Instruments maintains chipset pricing power through foundry exclusivity.
- Micro-Electro-Mechanical Systems:Silicon-fabricated scanning mirrors paired with laser sources eliminate color wheels and discrete imaging chips. Automotive HUD developers and enterprise AR headset manufacturers in Japan and South Korea adopt MEMS fastest, drawn by vibration tolerance and thermal stability in mobile environments.
- Liquid Crystal on Silicon:Reflective LC panels deliver color accuracy for German and French broadcast monitoring applications.
- Laser Phosphor:Blue laser excitation of yellow phosphor wheels balances efficiency and cost in mid-brightness corporate projectors.
- Liquid Crystal Display:Transmissive TFT panels serve entry-level price sensitivity with acceptable fidelity tradeoffs.
DLP captures highest revenue per unit. MEMS is climbing the fastest as automotive and AR applications scale.
Application:
Customer type determines procurement channel and replacement cadence, with institutional buyers treating devices as consumable peripherals while consumers view them as durable electronics.
- Education:K-12 institutions and universities deploy portable classroom solutions for hybrid learning, eliminating fixed installation infrastructure. US school districts and UK further education colleges prioritize FCC and CE-certified units with three-year warranties, compressing refresh cycles from five years to eighteen months.
- Corporate Presentations:IT procurement channels displace traditional AV integrators as enterprises unbundle hardware from maintenance contracts. North American financial services and consulting firms treat pico projectors as employee-issued peripherals, accelerating replacement through direct-to-consumer platforms.
- Home Entertainment:Consumers prioritize streaming integration and keystone correction for bedroom and backyard use.
- Gaming:Low-input-lag modes and high refresh rates attract console and PC players seeking immersive screen sizes.
- Outdoor Events:Battery-powered ruggedized units serve festival organizers and mobile cinemas in climate-variable environments.
Education leads by institutional volume. Corporate Presentations is expanding most quickly as IT procurement channels mature.
End User:
Geography shapes specification requirements, with emerging market volume concentration in price-sensitive segments and developed market premium capture in certified professional tiers.
- Educational Institutions:Procurement aggregates through district-level tenders in the US and local authority frameworks in the UK, favoring established suppliers with compliance documentation. India's tier-2 and tier-3 cities lack fixed projection infrastructure, creating white space for battery-powered portable units in coaching centers.
- Enterprises:Self-service deployment models and consumable-peripheral treatment compress refresh cycles. German and French corporate training departments absorb EU Ecodesign compliance costs most readily, while budget-tier suppliers delay launches pending redesign completion.
- Consumers:Direct-to-consumer platforms bypass retail markups, accelerating replacement cycles.
- Event Organizers:Rental and staging applications prioritize rapid deployment and environmental durability.
- Visual Artists:Color accuracy and compact form factors enable projection mapping and immersive installations.
Educational Institutions lead by unit volume. Enterprises are gaining share fastest as IT channel penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and France where REACH mercury bans and Ecodesign efficiency mandates accelerate certified procurement, while Shenzhen's manufacturing cluster compresses bill-of-materials costs for volume-tier production destined for price-sensitive education markets in India and Indonesia.
United States
K-12 institutions and universities deploy portable classroom solutions for hybrid learning, compressing refresh cycles from five years to eighteen months. FCC certification governs electromagnetic emissions for US-bound devices, directly influencing supplier qualification timelines. Texas Instruments anchors DLP chipset supply from its Dallas-area operations, sustaining pricing power across mid-tier and premium device architectures.
Germany
Corporate training departments and medical imaging OEMs absorb EU Ecodesign compliance costs most readily, prioritizing color-accurate professional tiers. The EU's RoHS recast tightens mercury-free illumination mandates, forcing optical engine redesigns for market access. Stuttgart and Munich host automotive head-up display developers adopting MEMS architectures fastest, drawn by vibration tolerance in mobile environments.
China
Shenzhen's electronics manufacturing cluster drives cost-competitive MEMS and DLP module production, enabling battery-powered portable units for emerging market volume. MIIT type-approval requirements and GB standards add compliance layers for domestic manufacturers targeting local procurement tenders. Yangtze River Delta optical subassembly suppliers digitize supply chains by collapsing multiple component tiers into integrated modules.
India
Tier-2 and tier-3 cities lack fixed projection infrastructure, creating white space for LED-based portable units in coaching centers and mobile cinemas. BIS certification requirements and DGFT import regulations shape supplier qualification for multinational entrants. Maharashtra and Karnataka electronics manufacturing zones absorb component sourcing from Shenzhen clusters, assembling finished devices for domestic education procurement.
Japan
Automotive HUD developers and enterprise AR headset manufacturers in Nagoya and Osaka adopt MEMS laser beam scanning architectures fastest. METI efficiency standards and JIS certification frameworks accelerate solid-state illumination transitions away from legacy lamp technologies. Kyushu-based precision optics fabricators supply micromirror arrays for integration into vibration-tolerant mobile projection systems.
Pico Projector Market Key Industry Players
Component suppliers and device integrators split the market along technology-licensing versus manufacturing-execution lines. Texas Instruments maintains foundry exclusivity for DLP micromirror chipsets, while Shenzhen-based optical engine assemblers compete on bill-of-materials compression. Three archetypes dominate: semiconductor licensors controlling core imaging IP, integrated device manufacturers with captive optical engine production, and contract assemblers serving white-label education procurement. Competitive moves center on technology licensing expansions into adjacent automotive HUD applications and backward integration into laser diode sourcing.
Within the semiconductor licensor tier, Texas Instruments, Inc. and MicroVision, Inc. exemplify divergent architectural approaches—DLP micromirror arrays versus laser beam scanning—each anchoring distinct supply chain ecosystems for downstream device integration. AAXA Technologies, Inc. occupies a position within the budget-tier device integrator archetype, representing the LED-based portability segment where Shenzhen manufacturing clusters enable cost-competitive positioning. Coretronic Corporation and Syndiant, Inc. sit within the optical engine specialist category, supplying subassemblies to brands lacking captive MEMS or LCoS fabrication capabilities.
| Leading Market Players |
|---|
| AAXA Technologies, Inc. |
| Texas Instruments, Inc. |
| MicroVision, Inc. |
| LG Electronics, Inc. |
| Lenovo Group Limited |
| Coretronic Corporation |
| Syndiant, Inc. |
| Celluon, Inc. |
| Miroir |
| Others |
Cost & Logistics Intelligence
Rare earth export quota volatility from Chinese supply authorities determines both the premium spread between laser and LED illumination tiers and the geographic clustering of MEMS fabrication capacity. Buyers face pricing tier compression when gallium and indium phosphide sourcing tightens, while suppliers reconfigure optical engine assembly locations to manage landed cost exposure.
Pricing Analysis
The customization-premium spread separates configured-to-order medical imaging units from standard education procurement batches. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade differentiation, with FCC and CE marking tiers commanding 40-60% uplifts over uncertified alternatives. Pricing pressure stems from Shenzhen assembly cost compression feeding into mid-tier DLP devices. Education procurement officers exhibit highest price sensitivity, while German medical OEMs absorb REACH compliance premiums without volume elasticity.
Supply Chain Analysis
Supplier-financing facilities from Yangtze River Delta optical subassembly vendors extend 90-120 day payment terms to white-label device integrators. China, Japan, and the United States anchor MEMS micromirror and laser diode sourcing. Rare earth elements in laser diodes and precision optics fabrication equipment draw from concentrated Chinese processing capacity. Single-source vulnerability sits with Texas Instruments' DLP chipset foundry exclusivity. Distribution runs through direct-to-consumer platforms and IT procurement channels, bypassing traditional AV integrator markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH mercury bans and multi-jurisdictional certification requirements create switching costs that protect incumbent positioning against low-cost challengers.
For Market Incumbents: Insulate chipset pricing power through backward integration into laser diode sourcing and captive MEMS fabrication capacity additions in Kyushu or Stuttgart clusters. Emerging LED-based portability challengers from Shenzhen threaten mid-tier margin compression, requiring certification investment in FDA laser safety tiers to maintain premium positioning.
For New Entrants and Emerging Players: India's tier-2 and tier-3 coaching centers represent the most penetrable entry point for battery-powered LED units, with Indonesian mobile cinemas as secondary white-space. BIS certification pathways and DGFT import navigation offer the clearest go-to-market angle against established distributors.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors optical engine specialists with captive MEMS capabilities. Long-term viability over the next decade rests on automotive HUD and AR headset convergence rather than consumer entertainment saturation. Watch MEMS adoption rates in Japanese automotive tier-1 suppliers as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Architecture Licensing | Automotive HUD developers in Stuttgart and Nagoya adopt laser beam scanning for vibration tolerance. |
| REACH Compliance Redesign | Mercury-free illumination mandates force optical engine redesigns for EU market access. |
| Direct-to-Consumer Channel Launch | Bypassing retail markups captures margin previously allocated to AV integrators in North America. |
| Laser Diode Backward Integration | Captive sourcing of gallium-based emitters reduces exposure to Chinese rare earth quota volatility. |
| Education Procurement Certification | FCC and CE marking tiers unlock district-level tenders in US K-12 and UK further education frameworks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, and MIIT type-approval databases. Interviews with optical engine procurement managers, MEMS fabrication engineers, education technology directors, and AV channel distributors informed demand-side validation. Bottom-up unit shipment modeling triangulated against top-down revenue estimates from component supplier disclosures.
Forecast inputs include illumination technology transition curves, regulatory compliance timeline shifts, and geographic procurement pattern evolution across the analysis window. Segmentation dimensions span product type, technology architecture, application context, and end-user procurement channel. CAGRs derive from fitted growth curves applied to technology-specific adoption rates, with laser beam scanning penetration in automotive HUDs as a primary demand driver.
Practitioners should monitor Chinese rare earth export policy adjustments and FDA laser safety classification updates for early signals of supply or regulatory revision. Forecasts reflect documented assumptions about technology cost reduction trajectories and procurement channel migration patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Computational Photography Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Mobile Imaging Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Handheld Imaging Devices Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
High-Speed Camera Market
Imaging
Europe IP Camera Market
Imaging
Industrial Camera Market
Imaging
US Near Infrared Imaging Market
Imaging
Whole Slide Imaging Systems Market
Imaging
China Electron Microscopy Market
Imaging
Side View Camera System Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market