
 Global Functional Near-Infrared Optical Brain Imaging Market | 2026-2036
Global Functional Near-Infrared Optical Brain Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Near-Infrared Optical Brain Imaging Market Foresight
Clinical rehabilitation applications are expanding faster than pure research deployments, pulling fNIRS hardware into stroke recovery wards and pediatric neurology units. NIRx Medical Technologies leverages its modular cap designs to dominate European academic installations. Shimadzu Corporation anchors Asian supply through integrated spectroscopy manufacturing. Kernel competes on miniaturization, shrinking optical sensor arrays toward consumer-accessible form factors.
Functional near-infrared optical brain imaging employs near-infrared light between 650 and 950 nanometers to detect hemodynamic responses in cortical tissue, measuring oxygenated and deoxygenated hemoglobin concentration changes through differential absorption. The technique enables non-invasive neural monitoring without ionizing radiation, making it suitable for repeated longitudinal studies and vulnerable populations. Continuous wave systems occupy the largest installed base due to lower cost and simpler calibration, though time domain architectures capture premium pricing from laboratories requiring depth-resolved cortical mapping. Portable deployment formats are growing fastest as battery-powered miniaturization unlocks ambulatory cognitive monitoring outside controlled lab environments.
FDA 510(k) clearance requirements shape commercialization timelines for clinical fNIRS devices in the United States, while ISO 80601-2-56 standards govern electrical safety and electromagnetic compatibility for brain imaging equipment. EMA medical device regulations under the EU MDR framework impose stricter clinical evidence thresholds for European market access. Japan's PMDA enforces QMS ministerial ordinances that delay foreign manufacturer registration. Stakeholders must monitor evolving reimbursement codes for functional neuroimaging across Medicare, NHS England, and Japan's MHLW to anticipate institutional purchasing cycles.
Market Dynamics
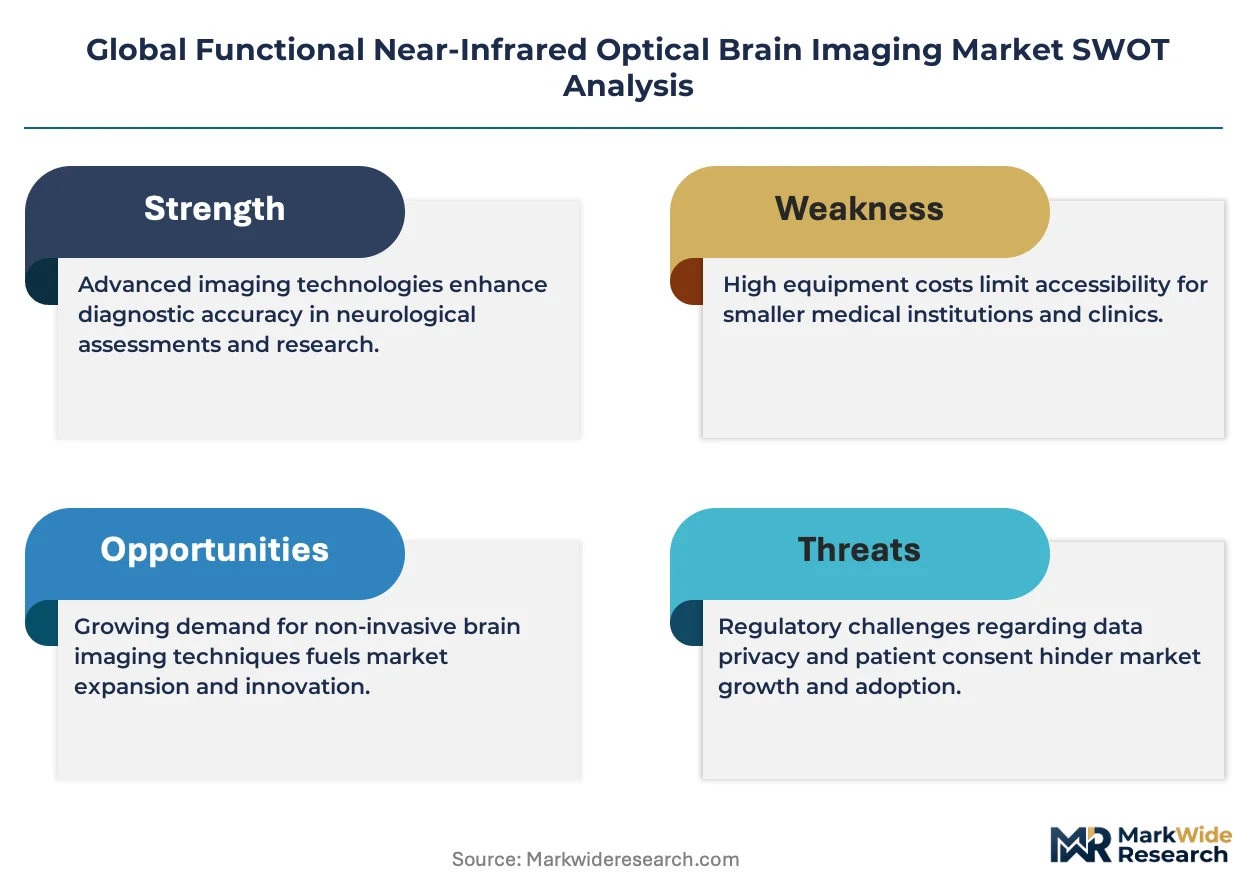
Portable fNIRS system miniaturization is compressing hardware margins while simultaneously expanding addressable use cases beyond traditional laboratory confines into ambulatory and point-of-care settings.
Growth Catalysts
- NIH-funded cognitive monitoring programs:Sustained federal research allocations in the United States channel institutional procurement toward longitudinal neural monitoring studies.
- EU MDR framework evolution:Stricter clinical evidence thresholds for European market access elevate quality benchmarks that differentiate compliant manufacturers.
- Stroke recovery wards:Clinical rehabilitation departments are integrating fNIRS for real-time cortical activation feedback during motor therapy sessions.
Market Restraints
- Optical sensor array costs:Specialized photodiode and laser diode components face supply concentration from East Asian semiconductor foundries.
- Depth resolution limitations:Continuous wave architectures cannot discriminate cortical layer activation below three centimeters, restricting clinical diagnostic confidence.
- PMDA QMS ministerial ordinances:Japan's quality management system requirements impose extended registration timelines that delay foreign manufacturer market entry.
Strategic Opportunities
- Pediatric neurology units:Non-invasive hemodynamic monitoring without ionizing radiation addresses unmet needs in infant and adolescent populations.
- fNIRS-EEG hybrid systems:Converging optical and electrophysiological modalities enable multimodal neural decoding for brain-computer interface development.
- DARPA neurotechnology contracts:Defense Advanced Research Projects Agency funding accelerates procurement cycles for high-performance cognitive monitoring hardware.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management system audits require eighteen to twenty-four months for initial manufacturer qualification.
- Spectroscopy calibration expertise:Shortage of trained biomedical engineers capable of maintaining differential absorption coefficient accuracy across multi-site deployments.
- Legacy fMRI integration:Hospital IT infrastructure requires costly middleware development to synchronize optical imaging data with existing radiological information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Near-Infrared Optical Brain Imaging Market |
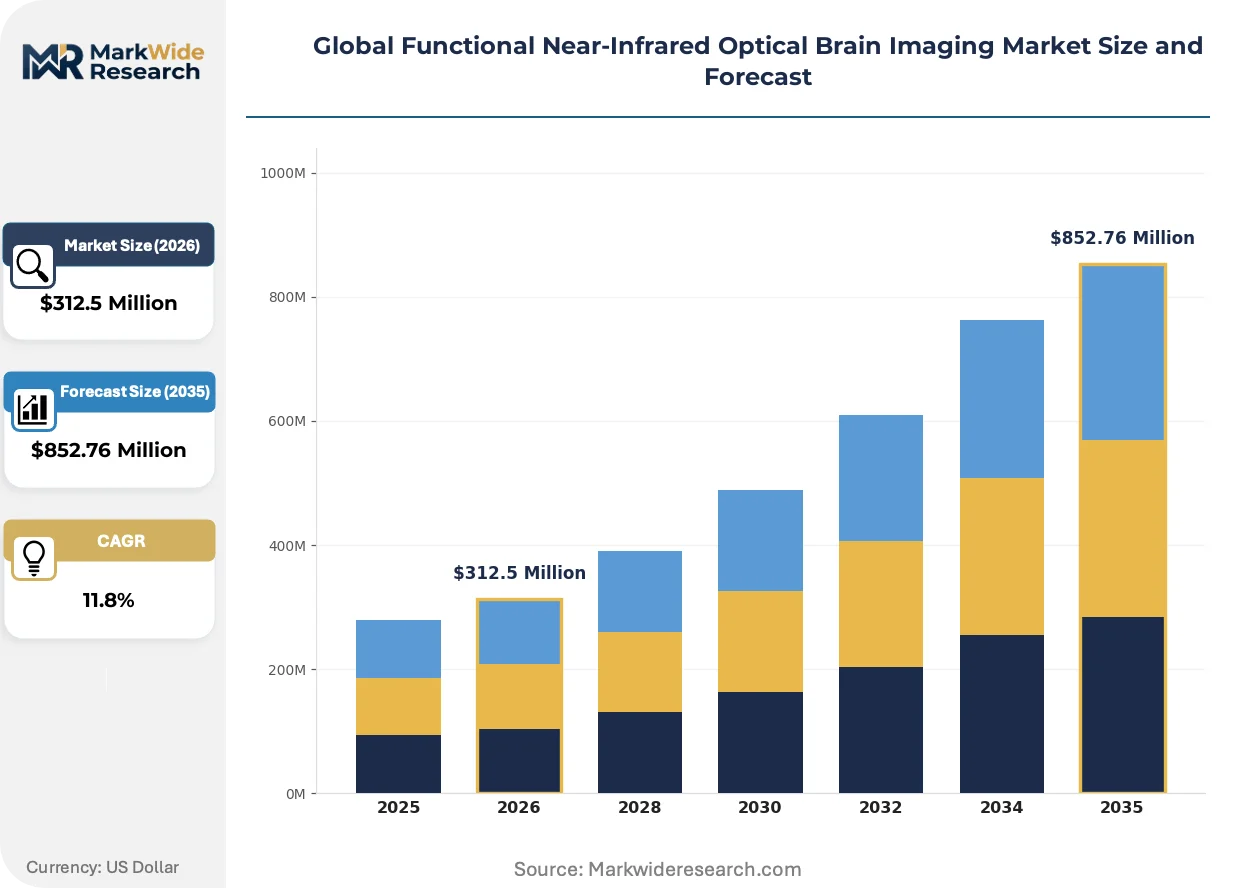
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $852.76 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Wave, Frequency Domain, Time Domain, Hybrid Systems Application: Neuroscience Research, Cognitive Monitoring, Brain-Computer Interface, Psychiatric Diagnosis, Sleep Studies End User: Academic Institutions, Clinical Laboratories, Research Organizations, Rehabilitation Centers, Government Agencies Deployment: Portable Devices, Wearable Units, Bedside Monitors, Fixed Systems |
| Companies Covered | NIRx Medical Technologies, Artinis Medical Systems, Shimadzu Corporation, Hitachi, Biopac Systems Inc., Gowerlabs Ltd, Soterix Medical Inc., Hamamatsu Photonics, Kernel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Near-Infrared Optical Brain Imaging Market Shifts & Advancements
Hardware architecture is fragmenting into specialized form factors optimized for distinct use environments rather than universal laboratory deployment. This specialization is compressing development cycles and reshaping competitive differentiation.
Multichannel fNIRS cap systems are modularizing around swappable sensor arrays that permit rapid reconfiguration between adult and pediatric head geometries. Rehabilitation centers in Germany are adopting these platforms for same-day deployment across stroke and traumatic brain injury patient cohorts. This modularity is compressing capital equipment replacement cycles while expanding per-device utilization rates.
EMA medical device regulations under the EU MDR framework are mandating post-market clinical follow-up studies for Class IIa neurological devices. Manufacturers must now maintain active surveillance registries that track real-world performance across diverse European hospital networks. Small-to-mid scale device developers are responding by consolidating regulatory affairs functions and outsourcing notified body interactions to specialized consultancies.
Academic procurement committees are unbundling hardware acquisition from software licensing and technical support agreements. Research institutions in Japan now issue separate RFPs for spectroscopy hardware, analysis platforms, and maintenance contracts. This disaggregation is most visible within national university hospital systems where centralized purchasing departments exercise greater vendor negotiation leverage.
Global Functional Near-Infrared Optical Brain Imaging Market Segmentation
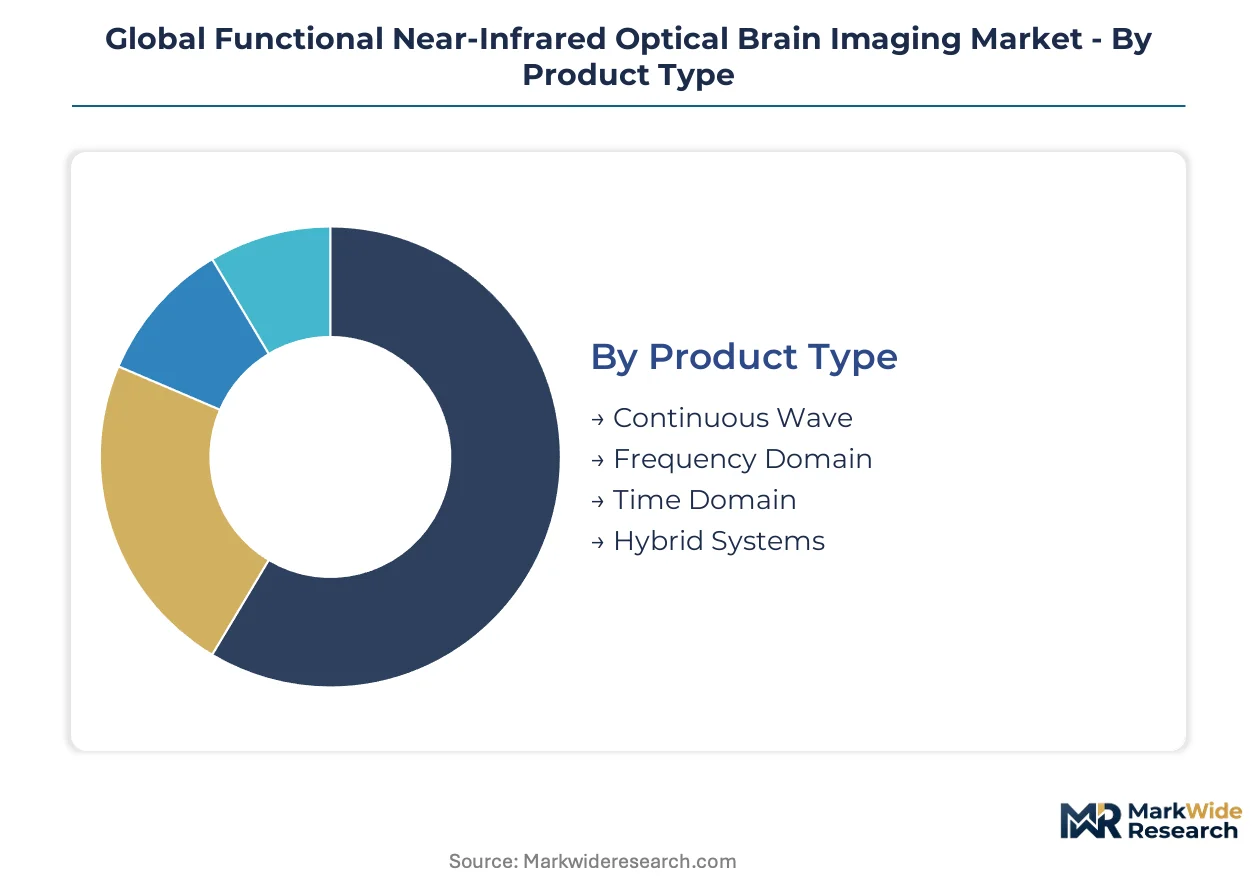
Segmentation in the fNIRS market reveals divergent hardware architectures and deployment contexts that shape procurement decisions. Product type determines technical capability and price positioning, while application focus channels R&D investment toward specific clinical and research endpoints.
Product Type:
Continuous wave systems dominate unit volume through cost accessibility, while time domain architectures command premium pricing from laboratories requiring depth-resolved cortical mapping.
- Continuous Wave:Near-infrared light sources operate at constant intensity to measure hemoglobin concentration changes through differential absorption. Academic institutions in Germany and Japan favor these systems for large-scale neuroscience studies where budget constraints limit capital expenditure.
- Time Domain:Pulsed laser diodes emit femtosecond pulses enabling photon time-of-flight measurement for depth-resolved tissue interrogation. NIH-funded cognitive monitoring programs in the United States prioritize these systems for longitudinal studies requiring subcortical activation discrimination.
- Frequency Domain:Modulated light sources measure amplitude attenuation and phase shift to quantify optical path length. Research organizations deploy these for intermediate depth sensitivity without time domain cost premiums.
- Hybrid Systems:Combined continuous wave and time domain architectures optimize cost-performance tradeoffs. Clinical laboratories adopt these for multimodal imaging protocols.
Today's leader: Continuous Wave. Tomorrow's challenger: Time Domain.
Application:
Neuroscience research absorbs the largest hardware procurement volumes, though clinical rehabilitation applications are expanding fastest as stroke recovery wards integrate real-time cortical feedback.
- Neuroscience Research:Fundamental brain function studies employ fNIRS for non-invasive hemodynamic monitoring across repeated longitudinal protocols. University hospitals in Japan concentrate demand through national brain mapping initiatives.
- Cognitive Monitoring:Real-time neural activity tracking supports attention and workload assessment in operational environments. DARPA neurotechnology contracts in the United States accelerate procurement for defense and aerospace applications.
- Brain-Computer Interface:Hemodynamic signal decoding enables neural control of external devices. Research organizations focus development resources on hybrid fNIRS-EEG architectures for improved signal fidelity.
- Psychiatric Diagnosis:Prefrontal cortex activation patterns inform mood disorder biomarker development. Clinical laboratories in Germany pilot these applications under EU MDR post-market surveillance requirements.
- Sleep Studies:Overnight cortical monitoring during sleep stages requires portable form factors. Rehabilitation centers adopt these for traumatic brain injury recovery assessment.
Neuroscience Research holds installed base dominance. Cognitive Monitoring climbs the fastest as operational deployment expands beyond laboratory confines.
End User:
Academic institutions concentrate demand for research-grade systems, while rehabilitation centers represent the fastest-expanding customer category as clinical integration accelerates.
- Academic Institutions:University neuroscience departments and research hospitals procure multi-channel cap systems for basic science investigations. German national university hospital systems exercise centralized purchasing leverage through unbundled RFPs.
- Rehabilitation Centers:Stroke and traumatic brain injury facilities integrate fNIRS for motor therapy feedback. These centers in Germany adopt modular platforms enabling same-day reconfiguration across patient cohorts.
- Clinical Laboratories:Hospital-based diagnostic units require FDA 510(k) cleared devices for patient monitoring. ISO 13485 certification timelines shape vendor selection criteria.
- Research Organizations:Independent institutes and government laboratories fund exploratory neurotechnology development. NIH and DARPA allocations channel procurement toward high-performance hardware.
- Government Agencies:Defense and public health entities sponsor cognitive monitoring standardization. These agencies in the United States and Japan establish technical specifications that downstream vendors must satisfy.
Academic Institutions anchor current revenue. Rehabilitation Centers gain share fastest through clinical workflow integration.
Deployment:
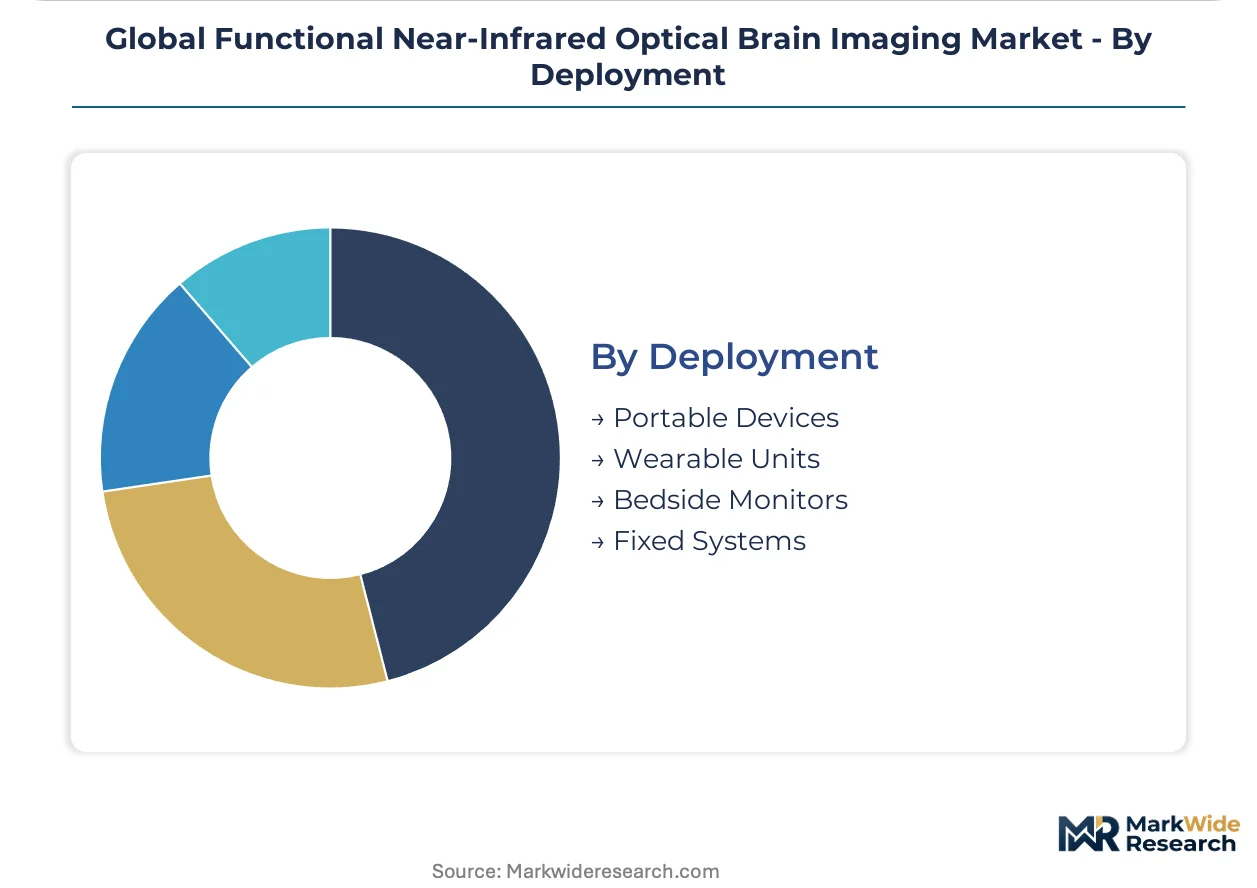
Fixed laboratory systems retain revenue concentration, though portable device miniaturization is compressing hardware margins while unlocking ambulatory use cases.
- Portable Devices:Battery-powered systems enable cognitive monitoring outside controlled environments. Kernel and competing developers miniaturize optical sensor arrays toward consumer-accessible specifications.
- Fixed Systems:Rack-mounted laboratory installations maximize channel count and signal fidelity. Academic institutions in Japan prioritize these for national brain imaging consortium participation.
- Wearable Units:Head-mounted form factors support extended monitoring during natural behavior. Research organizations pilot these for ecological validity in cognitive assessment.
- Bedside Monitors:Clinical-grade devices integrate with hospital IT infrastructure for real-time patient monitoring. FDA electrical safety standards under ISO 80601-2-56 govern design requirements.
Fixed Systems maintain revenue leadership. Portable Devices show steepest expansion trajectory as battery technology and optical miniaturization converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as ISO 13485 certification timelines and FDA 510(k) clearance costs widen compliance gaps between jurisdictions. Device developers migrate final assembly toward markets with streamlined quality management pathways while maintaining R&D concentration in funding-rich clusters.
United States
NIH-funded cognitive monitoring programs channel institutional procurement toward longitudinal neural monitoring studies. FDA 510(k) clearance requirements shape commercialization timelines for clinical fNIRS devices. The Boston-Cambridge corridor anchors neurotechnology R&D through DARPA brain-computer interface contracts.
Germany
Neuroscience research departments at academic institutions expand procurement of portable fNIRS systems. EU MDR framework regulations impose stricter clinical evidence thresholds for European market access. Rehabilitation centers in Munich and Heidelberg adopt modular cap platforms for stroke recovery wards.
Japan
National university hospital systems concentrate demand through centralized brain mapping initiatives. PMDA QMS ministerial ordinances enforce extended registration timelines that delay foreign manufacturer market entry. The Kanto region around Tokyo hosts integrated spectroscopy manufacturing clusters.
United Kingdom
NHS England reimbursement code evolution shapes institutional purchasing cycles for functional neuroimaging. MHRA post-Brexit regulatory alignment maintains EU MDR-equivalent standards. London-Oxford academic partnerships drive pediatric neurology unit adoption.
China
Domestic semiconductor foundry expansion targets photodiode and laser diode component supply concentration. NMPA medical device registration pathways are streamlining for Class II neurological monitoring equipment. Yangtze River Delta manufacturing hubs absorb optical sensor array assembly migration.
Global Functional Near-Infrared Optical Brain Imaging Market Competitive Landscape
Technology licensing dominates the current landscape as modular hardware architectures compress proprietary differentiation windows. The vendor base organizes around three tiers: integrated spectroscopy conglomerates with captive component manufacturing, specialized neurotechnology developers focused on miniaturization, and academic spinouts commercializing laboratory prototypes. Strategic archetypes include full-stack system integrators, optical component specialists, and software-defined platform vendors. Geographic expansion and portfolio diversification represent the dominant competitive moves as participants seek regulatory jurisdiction arbitrage and application segment breadth.
Within the integrated spectroscopy tier, Shimadzu Corporation and Hamamatsu Photonics exemplify Japanese conglomerates with upstream control over laser diode and photodiode production. NIRx Medical Technologies occupies a position among specialized neurotechnology developers leveraging modular cap designs. Kernel anchors the miniaturization-focused segment, representing developers shrinking optical sensor arrays toward ambulatory form factors. These three archetypes illustrate how competitive positioning fragments across manufacturing depth, clinical application focus, and consumer-market ambition.
| Leading Market Players |
|---|
| NIRx Medical Technologies |
| Artinis Medical Systems |
| Shimadzu Corporation |
| Hitachi |
| Biopac Systems Inc. |
| Gowerlabs Ltd |
| Soterix Medical Inc. |
| Hamamatsu Photonics |
| Kernel |
| Others |
Supply & Pricing Matrix
Photodiode and laser diode spot prices on East Asian semiconductor exchanges cascade through fNIRS hardware tiers, compressing margins on continuous wave systems while time domain architectures retain pricing power through component scarcity and specialized calibration requirements.
Pricing Analysis
Distributor markups on research-grade systems typically run 15-25 percent above manufacturer net prices, though direct-to-hospital procurement contracts for FDA-cleared clinical devices bypass channel layers entirely. Three-tier pricing structure across premium time domain, standard continuous wave, and economy portable configurations stratifies by optical channel count and depth resolution capability. Cost compression in the portable segment is intensifying because Kernel and competing miniaturization specialists are driving sensor array costs toward consumer electronics scales. Academic institutions exhibit highest price sensitivity, prioritizing continuous wave systems for large-cohort studies, while DARPA-funded defense contractors absorb premium pricing for time domain depth discrimination.
Supply Chain Analysis
Regional distribution centers in Yokohama, Munich, and Boston coordinate hub-and-spoke fulfillment patterns for modular cap systems and replacement sensor arrays. Manufacturing concentration rests on Japan for integrated spectroscopy components, Germany for precision optical assembly, and China for photodiode wafer fabrication. Specialized femtosecond laser diodes, high-sensitivity avalanche photodiodes, and medical-grade fiber optic bundles constitute critical input dependencies. Single-source vulnerability concentrates in Japanese laser diode foundries serving time domain architectures. Distribution runs through academic procurement consortia and GPO contracts for hospital systems, with direct OEM relationships dominating defense and research laboratory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) clearance timelines and EU MDR post-market surveillance costs creates geographic differentiation opportunities for capital allocation and manufacturing footprint decisions.
For Market Incumbents: Anchor market position through backward integration into photodiode supply and captive spectroscopy calibration service capacity. NIRx Medical Technologies and Shimadzu Corporation should expand ISO 13485-certified manufacturing in Germany to exploit streamlined EU MDR notified body pathways, while defending against Kernel's miniaturization threat by accelerating portable product line refresh cycles. Certification investment in FDA dual-submission strategies preserves access to NIH-funded procurement channels. For New Entrants and Emerging Players: Direct-to-researcher digital sales channels bypass entrenched distributor relationships and compress customer acquisition costs for modular cap accessories and software analysis platforms. Pediatric neurology units in NHS England and Japan's national university hospital systems represent the most penetrable white-space segments, with unmet demand for non-invasive infant monitoring driving faster procurement cycles than saturated academic neuroscience departments. Freemium software tiering with hardware attach conversion offers viable go-to-market economics. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid fNIRS-EEG platform developers possessing multimodal neural decoding IP and DARPA contract visibility. The five-to-ten year viability window favors acquisition targets with established FDA 510(k) clearances and EU MDR technical documentation rather than pre-revenue miniaturization ventures. Kernel's consumer-market pivot progress serves as the critical signal to watch for ambulatory neurotechnology inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Compresses eighteen-to-twenty-four month quality system timelines for EU MDR market access. |
| Hybrid fNIRS-EEG Platform Development | Captures DARPA brain-computer interface contract flows through multimodal signal fidelity. |
| Photodiode Backward Integration | Reduces East Asian foundry dependency and stabilizes cost structures for time domain systems. |
| Pediatric Neurology Unit Partnerships | Locks in NHS England procurement through non-invasive infant monitoring differentiation. |
| Modular Cap Rapid Reconfiguration | Expands per-device utilization across stroke and traumatic brain injury cohorts in German rehabilitation centers. |
Research Methodology
Bottom-up academic institution and rehabilitation center procurement modeling reconciled against top-down spectroscopy hardware shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at notified bodies combined with secondary validation against FDA 510(k) filings, EMA medical device databases, NIH RePORTER grant records, and Japanese MHLW reimbursement code updates. Triangulation between demand-side procurement cycle analysis and supply-side component bill-of-materials verification ensures cross-dimensional consistency.
Input-output matrices map optical channel count, depth resolution architecture, and end-user certification requirements against price realization and volume throughput across the projection horizon. Segmentation dimensions modeled include product type tier, application endpoint, end-user institutional category, and deployment form factor, with regional regulatory cluster differentiation overlaying geographic demand distribution. CAGRs derive from installed base replacement cycles, expansion rates in clinical rehabilitation settings, and miniaturization-driven unit economics improvement. NIH funding appropriation trajectories and EU MDR implementation phase transitions constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for time domain depth-resolved cortical mapping would alter the outlook if continuous wave architectures achieve comparable subcortical discrimination through algorithmic advancement. Forecasts reflect documented assumptions regarding regulatory clearance timelines, reimbursement code expansion, and semiconductor component supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Automotive Imaging Market
Imaging
Cooled IR Camera Market
Imaging
Chemical Imaging Systems Market
Imaging
Global 4K Camera Market
Imaging
Hyperspectral Imaging Market
Imaging
Semiconductor Microscopes Market
Imaging
Multi Camera System Market
Imaging
US Near Infrared Imaging Market
Imaging
Digital Image Processing Market
Imaging
Global Camera Module Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Handheld Imaging Systems Market
Imaging
Global Image Processing Systems Market
Imaging
Europe Image Sensors Market