
 Global a-Si X-Ray Flat Panel Detectors Market | 2026-2036
Global a-Si X-Ray Flat Panel Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global a-Si X-Ray Flat Panel Detectors Market Foresight
Software-defined image processing subscriptions is broadening revenue models beyond hardware sales in the a-Si X-Ray Flat Panel Detectors space. Varex Imaging Corporation leverages its vertical integration in tube and detector manufacturing to sustain pricing power across radiography and fluoroscopy lines. Canon Inc. anchors its position through deep R&D investment in photodiode arrays and thin film transistor backplanes. Konica Minolta, Inc. competes by specializing in compact portable detector form factors for chiropractic and point-of-care settings.
Amorphous silicon X-ray flat panel detectors consist of a glass substrate coated with a thin film transistor array and overlaid photodiode layer, typically achieving spatial resolutions between 100 and 200 micrometers per pixel for diagnostic clarity. These assemblies convert incident X-ray photons into electrical signals for real-time digital imaging in medical and veterinary applications. Indirect conversion detectors dominate installed base volumes due to mature scintillator supply chains and lower unit costs, while direct conversion configurations capture premium positioning in mammography where dose efficiency and spatial resolution command higher pricing. Portable detectors represent the fastest-growing product type as ambulatory imaging centers and field veterinary units prioritize mobility over fixed-room throughput.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access costs for manufacturers serving Western healthcare systems. China's NMPA registration pathway and Japan's PMDA quality audits add further compliance layers for companies targeting Asia-Pacific expansion. Stakeholders must monitor evolving reimbursement codes for digital radiography across Medicare, NHS England, and Germany's G-DRG framework, as payment parity with computed radiography will determine replacement velocity in budget-constrained hospital systems.
Market Dynamics
Hospital consolidation across Germany and the United States is compressing procurement timelines and favoring bundled imaging suite contracts over standalone detector purchases. This structural shift toward bulk procurement is reshaping vendor-customer relationships and pricing negotiations.
Growth Catalysts
- EU MDR Conformity Assessments:The Medical Device Regulation's stricter quality requirements are accelerating replacement of aging computed radiography systems with certified digital flat panel detectors in European hospitals.
- Emergency Department Digitalization:Hospital emergency departments in the United States are replacing film-based trauma imaging with real-time digital radiography to reduce patient throughput times.
- Cesium Iodide Scintillator Maturation:Advances in columnar CsI crystal growth are improving detective quantum efficiency and lowering per-unit production costs for indirect conversion detectors.
Market Restraints
- Amorphous Silicon Substrate Concentration:Glass substrate and TFT backplane production concentrates in East Asian foundries, exposing supply chains to geopolitical friction and shipping disruptions.
- Direct Conversion Material Costs:Selenium-based photoconductor layers for mammography applications face raw material price volatility and limited supplier base.
- FDA 510(k) Documentation Burden:Substantial equivalence filings require extensive clinical validation data, extending time-to-market for iterative detector designs by 12-18 months.
Strategic Opportunities
- Veterinary Point-of-Care Expansion:Equine and large-animal veterinary practices in Australia and Brazil are adopting portable wireless detectors for field diagnostic imaging.
- Software Subscription Attachments:AI-powered image enhancement and dose tracking modules create recurring revenue streams beyond hardware replacement cycles.
- Japan's PMDA Streamlined Pathways:Revised quality management system audits for previously approved device families reduce regulatory burden for incremental detector upgrades.
Industry Challenges
- TFT Backplane Design Talent Scarcity:Specialized expertise in low-noise analog circuit design for large-area electronics remains concentrated among a handful of engineering teams.
- Legacy PACS Integration Complexity:New detector installations must bridge DICOM compatibility gaps with decade-old hospital archiving systems without disrupting clinical workflows.
- Cleanroom Capital Intensity:Semiconductor-grade fabrication facilities for photodiode deposition require substantial upfront investment with multi-year depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global a-Si X-Ray Flat Panel Detectors Market |
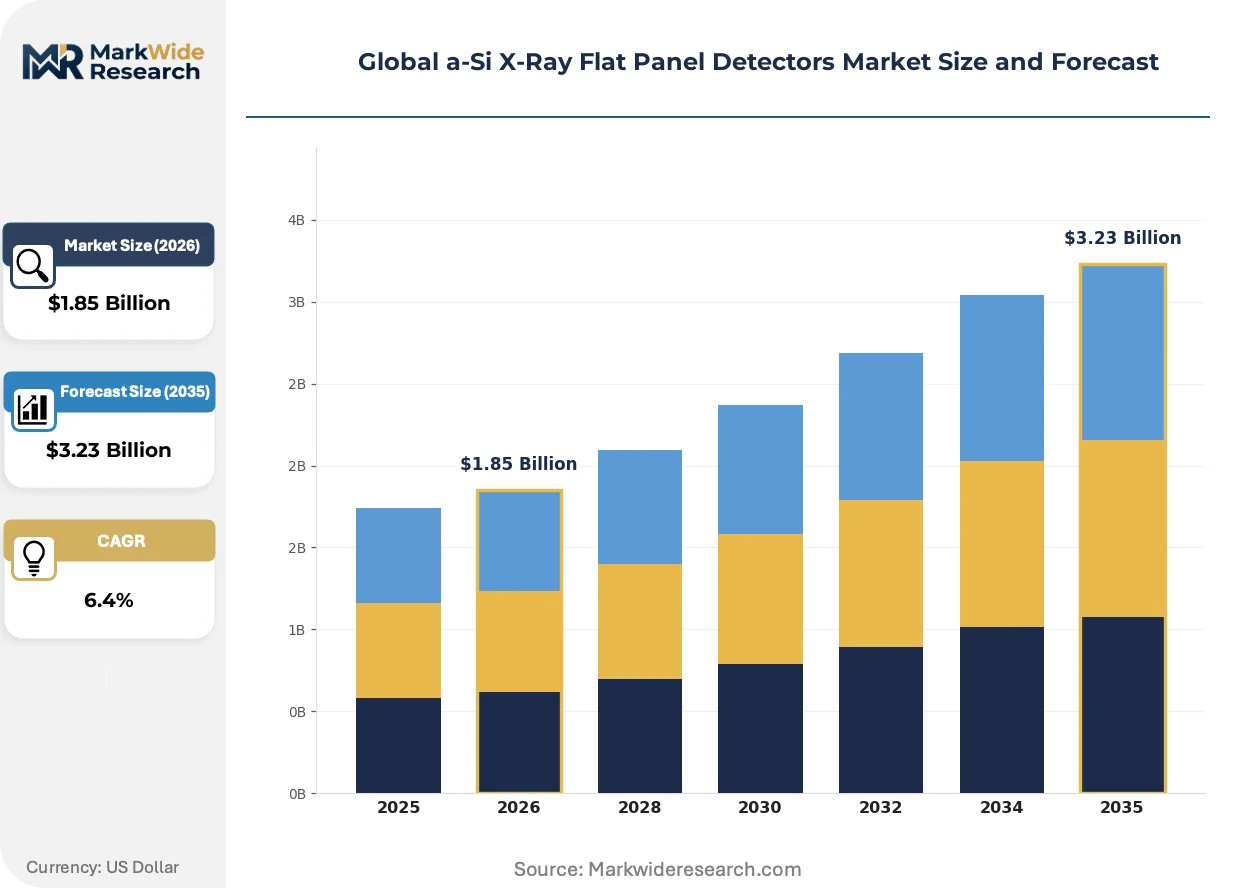
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Conversion Detectors, Indirect Conversion Detectors, Flat Panel Sensors, Portable Detectors Technology: Thin Film Transistor, Photodiode, Amorphous Silicon, CMOS End User: Hospitals, Diagnostic Imaging Centers, Research Laboratories, Chiropractic Clinics Application: Radiography, Mammography, Fluoroscopy, Veterinary Imaging |
| Companies Covered | Varex Imaging Corporation, Konica Minolta, Inc., Agfa-Gevaert Group, FUJIFILM Holdings America Corporation, Innolux Corporation, Thales Group, Rayence, Shanghai Iray Electronics Technology Co., Ltd., Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global a-Si X-Ray Flat Panel Detectors Market Shifts & Advancements
Wireless data transmission and edge computing capabilities are transforming detector architecture from passive sensors to intelligent imaging nodes. These advances are compressing installation footprints and enabling decentralized clinical deployment models.
CMOS-integrated photodiode arrays are electrifying the transition from passive amorphous silicon backplanes to active pixel architectures with on-chip analog-to-digital conversion. Mobile C-arm manufacturers in Germany and the United States are adopting these sensors for fluoroscopy applications requiring sub-millisecond latency. The technology is electrifying competitive positioning by enabling real-time surgical guidance without cable tethering.
China's NMPA implementation of unique device identification requirements is forcing manufacturers to reconfigure labeling systems and supply chain traceability protocols. Domestic Chinese producers must now maintain electronic records linking each detector to component batch records. The policy most affects exporters serving tier-three hospital procurement programs, which are consolidating around NMPA-registered suppliers.
Subscription-based image processing licenses are displacing perpetual software purchases in radiology department budgeting. Hospital procurement teams in the United Kingdom's NHS England framework now prioritize operational expenditure models over capital equipment outlays. This shift is most visible in teleradiology networks serving rural clinics, where pay-per-study arrangements reduce upfront detector deployment costs.
Global a-Si X-Ray Flat Panel Detectors Market Segmentation
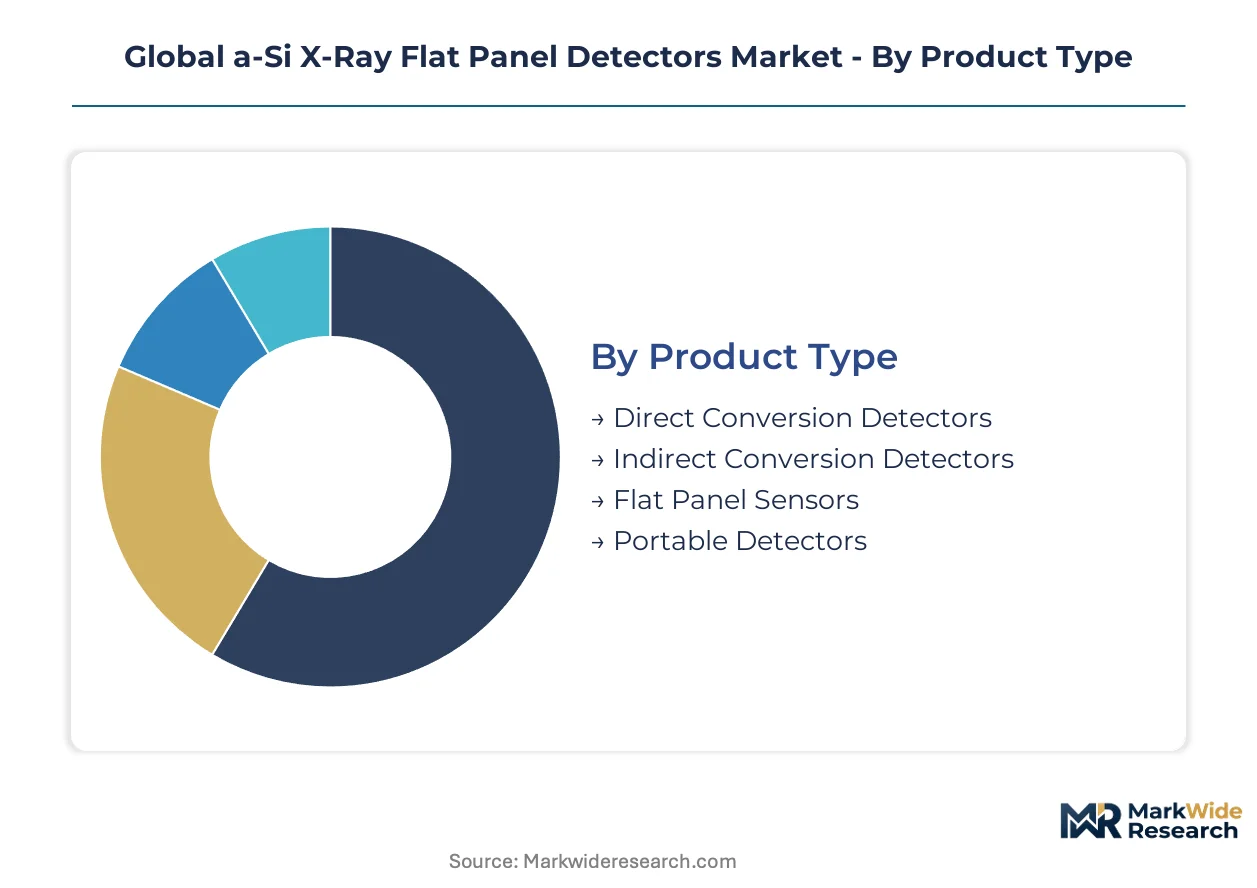
Segmentation in the a-Si X-Ray Flat Panel Detectors market reveals divergent certification pathways and pricing architectures. Each dimension—product type, technology, end user, and application—carries distinct regulatory burdens that shape vendor go-to-market strategies and customer procurement timelines.
Product Type:
Portable detectors require FDA 510(k) clearance for wireless transmission protocols, while fixed-room direct conversion systems face additional IEC 60601-1-3 electrical safety testing. Indirect conversion detectors leverage mature scintillator supply chains with streamlined EU MDR technical documentation.
- Direct Conversion Detectors:Selenium-based photoconductor layers convert X-ray photons directly to electrical charge without intermediate scintillation. Mammography suites in Germany and the United States specify these for dose efficiency below 0.3 mGy per view, though selenium raw material volatility constrains production scaling.
- Indirect Conversion Detectors:Cesium iodide scintillator crystals coupled to amorphous silicon photodiode arrays dominate installed base economics. Hospital procurement teams in the United Kingdom prioritize these for general radiography rooms where detective quantum efficiency above 70% satisfies NHS England diagnostic imaging standards.
- Flat Panel Sensors:Integrated scintillator-TFT assemblies for OEM integration into C-arm and angiography systems.
- Portable Detectors:Battery-powered wireless units with edge computing for ambulatory and veterinary field deployment.
Leading the category by volume: Indirect Conversion Detectors. Growing fastest: Portable Detectors.
Technology:
Thin film transistor backplane architecture determines pixel pitch limits and readout noise floors, with direct costs scaling nonlinearly below 150 micrometer feature sizes. Photodiode deposition processes require semiconductor-grade cleanrooms with capital intensity varying by substrate size.
- Thin Film Transistor:Amorphous silicon TFT arrays on borosilicate glass substrates enable active matrix addressing for megapixel-scale imaging areas. Diagnostic imaging centers in Japan specify these for fluoroscopy latency below 33 milliseconds under PMDA-approved quality management systems.
- Photodiode:P-i-n structured hydrogenated amorphous silicon layers convert visible scintillator output to electrical signals with fill factors above 80%. Research laboratories in Switzerland demand these for quantitative dosimetry applications requiring linear response across four decades of exposure.
- Amorphous Silicon:Mature deposition processes with established supply chains for large-area electronics.
- CMOS:Crystalline silicon active pixel sensors with on-chip ADC for surgical C-arm integration.
Highest unit margins: CMOS. Steepest expansion trajectory: Thin Film Transistor for large-area radiography.
End User:
Hospital procurement operates through centralized imaging suite contracts with bundled service agreements, while chiropractic clinics purchase standalone portable units through distributor networks with shorter sales cycles.
- Hospitals:Multi-modality imaging departments with PACS integration requirements and 24/7 uptime service contracts. German hospital consolidation is compressing vendor lists to three approved suppliers per procurement region.
- Diagnostic Imaging Centers:Outpatient facilities with high throughput requirements and teleradiology connectivity. Australia's TGA-registered centers are adopting subscription-based image processing to convert capital expenditure to operational models.
- Research Laboratories:Quantitative imaging for phantom studies and protocol development with custom calibration requirements.
- Chiropractic Clinics:Point-of-care extremity imaging with compact detector footprints and reduced shielding requirements.
Dominant revenue concentration: Hospitals. Fastest-growing customer type: Diagnostic Imaging Centers.
Application:
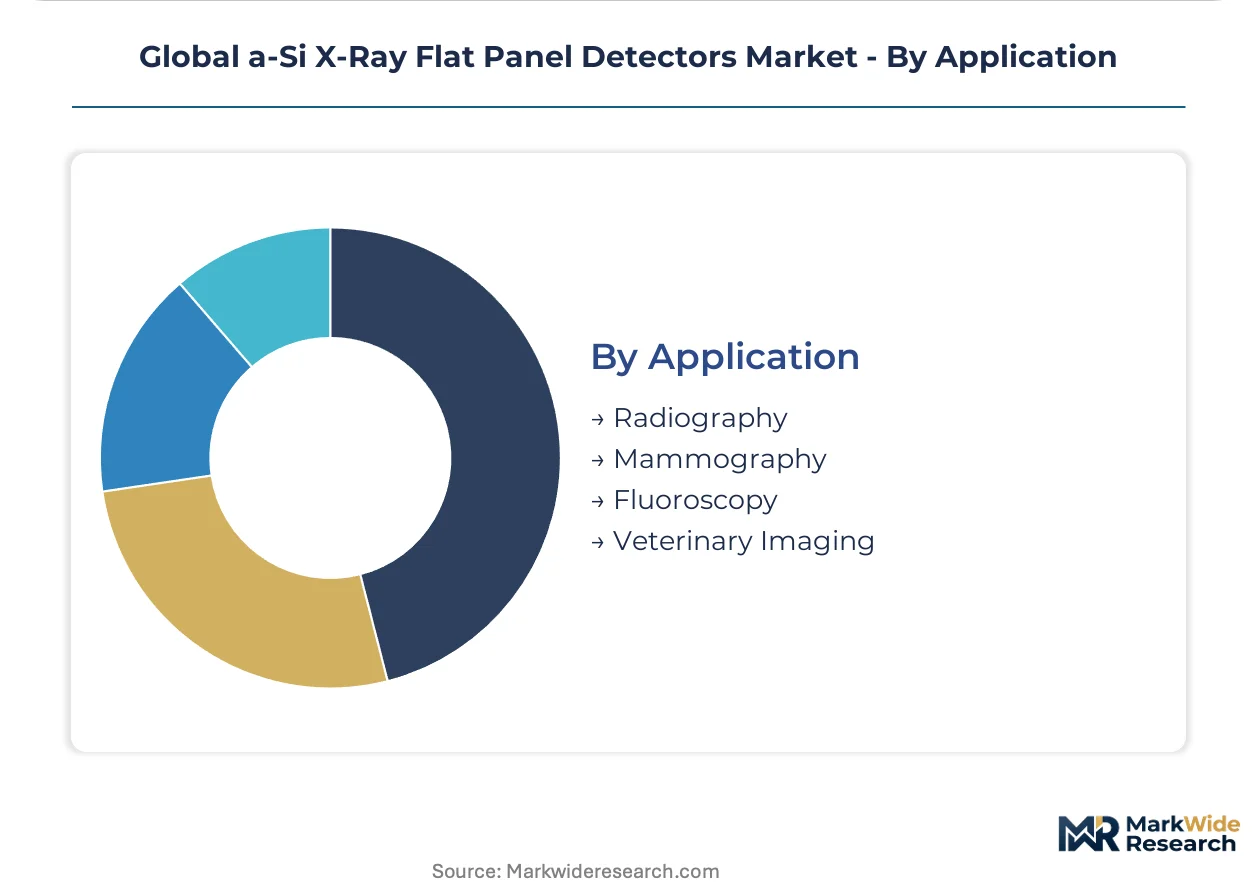
Mammography applications command premium pricing for direct conversion architectures with specialized spatial resolution requirements, while veterinary imaging tolerates lower specification tiers with reduced regulatory documentation.
- Radiography:Chest and extremity imaging with 400-micrometer pixel pitch for general diagnostic purposes. Emergency departments in the United States are replacing computed radiography with these for throughput gains above 30 patients per hour.
- Mammography:Microcalcification detection requiring 50-micrometer effective pixel size and low-dose optimization. FDA 510(k) submissions for these systems require extensive clinical validation against film-screen benchmarks.
- Fluoroscopy:Real-time surgical guidance with sub-100 millisecond latency and high frame rate readout.
- Veterinary Imaging:Equine and small-animal diagnostics with portable wireless detectors for field deployment.
Largest installed base: Radiography. Expanding most quickly: Veterinary Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors detector component fabrication, with foundries supplying TFT backplanes to imaging equipment assemblers across three continents. Hospital procurement contracts in Germany and the United States currently absorb the highest unit volumes for finished systems. Regulatory divergence between FDA 510(k) pathways and EU MDR conformity assessments is forcing manufacturers to maintain parallel certification teams.
United States
Emergency department digitalization at trauma centers in Houston and Phoenix is compressing replacement cycles for legacy film-based systems. FDA 510(k) clearance requirements for wireless transmission protocols add 12-18 months to product introductions. The Boston-Cambridge medical device cluster houses engineering teams specializing in low-noise analog circuit design for large-area electronics.
Germany
Hospital consolidation in North Rhine-Westphalia and Bavaria is driving bundled imaging suite contracts over standalone detector purchases. EU MDR conformity assessments are accelerating replacement of aging computed radiography systems with certified digital flat panel detectors. The Munich-Stuttgart industrial corridor concentrates TFT backplane design talent among specialized engineering firms.
China
Tier-three hospital procurement programs are consolidating around NMPA-registered suppliers with unique device identification traceability systems. Yangtze River Delta foundries dominate glass substrate and amorphous silicon deposition capacity for photodiode arrays. Shanghai-based producers are expanding into veterinary portable detectors for export to Australia and Brazil.
Japan
PMDA streamlined pathways for previously approved device families are reducing regulatory burden for incremental detector upgrades. Diagnostic imaging centers in Tokyo and Osaka specify amorphous silicon TFT arrays for fluoroscopy latency below 33 milliseconds. The Nagoya industrial zone maintains semiconductor-grade cleanroom facilities for photodiode deposition processes.
United Kingdom
NHS England procurement frameworks now prioritize operational expenditure models with subscription-based image processing over capital equipment outlays. Teleradiology networks serving rural clinics in Scotland and Wales are adopting pay-per-study arrangements to reduce upfront deployment costs. London-based hospital trusts are piloting AI-powered dose tracking modules as recurring revenue attachments.
Global a-Si X-Ray Flat Panel Detectors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the a-Si X-Ray Flat Panel Detectors landscape. The vendor base concentrates around three strategic tiers: vertically integrated imaging conglomerates with captive tube and detector manufacturing, specialized component foundries supplying OEM integrators, and regional assemblers serving price-sensitive veterinary and chiropractic segments. Competitive moves center on backward integration into scintillator crystal growth and strategic partnerships with mobile C-arm manufacturers for fluoroscopy integration.
Within the vertically integrated tier, Varex Imaging Corporation and Canon Inc. occupy positions anchored by in-house production of critical subsystems. Konica Minolta, Inc. exemplifies the specialization archetype, with its corporate name signaling Japanese origin and compact form factor focus. Shanghai Iray Electronics Technology Co., Ltd. represents the regional fabricator model, its naming structure indicating Chinese base and electronics technology concentration.
| Leading Market Players |
|---|
| Varex Imaging Corporation |
| Konica Minolta, Inc. |
| Agfa-Gevaert Group |
| FUJIFILM Holdings America Corporation |
| Innolux Corporation |
| Thales Group |
| Rayence |
| Shanghai Iray Electronics Technology Co., Ltd. |
| Canon Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FDA 510(k)-cleared hospital systems and unregistered veterinary field units manifests in parallel pricing architectures and divergent sourcing strategies. Premium configurations draw from semiconductor-grade cleanroom facilities in Japan and Germany, while economy tiers feed from Yangtze River Delta foundries with reduced traceability documentation.
Pricing Analysis
Margin tightening in portable wireless tiers reflects NMPA registration cost absorption and battery subsystem commodity escalation. Three-tier pricing structure across premium, standard, and economy levels separates mammography direct conversion systems from general radiography indirect units and unregistered veterinary detectors. German hospital procurement teams demonstrate lowest price sensitivity through bundled imaging suite contracts, while Australian equine practices drive hardest bargain for field-deployable units.
Supply Chain Analysis
Refurbishment flows for end-of-life detectors concentrate in Shenzhen and Singapore, where TFT backplane recovery yields secondary market feedstock. Glass substrate fabrication anchors in China and Taiwan, with selenium photoconductor layers drawing from Belgian and Japanese chemical processors. Single-source vulnerability haunts columnar cesium iodide crystal supply. Distribution runs through OEM integrator networks for fixed-room systems and veterinary distributor channels for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment deadlines and FDA 510(k) documentation burdens are compressing vendor viability windows, forcing asset-light assemblers toward exit or acquisition.
For Market Incumbents: Deepen captive scintillator crystal growth capabilities to offset selenium price volatility and secure detective quantum efficiency differentiation. Expand service contract attach rates in German hospital consolidation zones to lock out substitute CMOS-integrated challengers.
For New Entrants and Emerging Players: Japan's PMDA streamlined pathways for previously approved device families opens a window for incremental detector upgrade specialization. Veterinary point-of-care in Brazil and Australia offers most penetrable white-space, with distributor partnership models bypassing hospital GPO complexity.
For Investors and Strategic Acquirers: Re-rating potential sits with TFT backplane design boutiques given CMOS transition acceleration and talent scarcity in low-noise analog circuit expertise. Monitor NMPA unique device identification enforcement rigor as inflection signal for Chinese domestic producer consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses time-to-market for wireless transmission protocol iterations in emergency department segments. |
| EU MDR Technical Documentation Investment | Secures conformity assessment passage for computed radiography replacement campaigns across German hospital networks. |
| Software Subscription Companion Development | Converts capital equipment sales to recurring revenue through AI-powered dose tracking module attachments. |
| Backward Integration into CsI Crystal Growth | Reduces per-unit scintillator cost exposure and improves detective quantum efficiency specification control. |
| Veterinary Distributor Channel Partnership | Unlocks ambulatory field deployment in Australian equine and Brazilian large-animal diagnostic practices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and fluoroscopy equipment specialists. FDA 510(k) clearance databases, EU MDR notified body documentation, NMPA registration records, and PMDA quality management system audits supplied regulatory trajectory validation. Bottom-up detector shipment modeling triangulated against top-down imaging equipment market sizing.
Granularity-level modeling addressed product type, conversion technology, end-user facility class, and application-specific certification requirements across the analysis window. CAGRs derived from installed base replacement velocity analysis and digital radiography reimbursement parity assumptions. Forecast inputs incorporated PACS integration lag times and cleanroom capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for CMOS-integrated photodiode arrays would alter the outlook. Practitioners should monitor Medicare digital radiography reimbursement code revisions and NHS England operational expenditure policy shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Magnetic Crack Detectors Market
Detection and Regulation Devices
Transient Voltage Suppressor Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Ultraviolet Currency Detector Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Leak Detection Equipment Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Vacuum Leak Detectors Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market