
 Video Capture Card Market | 2026-2036
Video Capture Card Market Size, Share, and Industry Trends Forecast 2026-2036
Video Capture Card Market Outlook
The capital-intensity divergence between in-house ASIC designers and third-party chipset assemblers is bifurcating competitive trajectories. AVerMedia leverages captive firmware development to sustain margin capture across external capture cards. Elgato anchors its position through deep software-hardware integration for game streaming creators. Razer competes on brand extension from peripherals into capture hardware for content developers.
A video capture card converts analog or digital video signals into encoded digital formats for recording, streaming, or real-time processing, typically supporting HDMI, SDI, or composite inputs with hardware encoding at resolutions up to 4K60 or 8K30 depending on interface bandwidth. External USB capture cards lead volume shipment due to plug-and-play deployment across laptops and mobile workstations, while PCIe internal cards retain the premium tier for low-latency broadcast pipelines. 4K capture technology grows fastest as streaming platforms enforce higher bitrate thresholds, and HDR capture commands outsized margins from professional content creators seeking Rec. 2020 color accuracy.
The FCC governs electromagnetic interference certification for capture hardware sold in the United States, while the EU Radio Equipment Directive mandates CE marking for wireless-enabled models. China's MIIT enforces GB standards on signal processing equipment entering domestic broadcast supply chains. Stakeholders must monitor interface protocol evolution and encoder licensing costs as AV1 and VVC codecs displace legacy H.264 dependencies.
Market Dynamics
HDMI 2.1 interface migration is compressing product refresh cycles as capture hardware vendors race to support 48Gbps bandwidth for uncompressed 4K120 and 8K60 workflows.
Growth Catalysts
- Esports Broadcasting Infrastructure:Professional tournament operators in China and Germany are mandating 4K60 HDR capture standards for live event production, forcing venue upgrades across tier-one cities.
- Creator Economy Tax Incentives:The United States IRA extends equipment depreciation benefits to content production hardware, accelerating solo creator investment in external capture devices.
- AV1 Hardware Encoding:Royalty-free codec adoption is displacing H.264 licensing dependencies in mid-tier capture cards, lowering BOM costs for third-party chipset assemblers.
Market Restraints
- FPGA Supply Concentration:Xilinx and Altera dominate programmable logic for real-time video processing, creating single-source vulnerability for PCIe internal card manufacturers.
- FCC Certification Timelines:Electromagnetic interference testing for USB 3.2 Gen 2x2 capture devices averages 14-18 weeks, delaying product launches in the United States.
- Thunderbolt Royalty Stack:Intel's licensing fees for Thunderbolt 4 certification add material cost pressure to premium external capture solutions targeting Mac workstations.
Strategic Opportunities
- India Creator Infrastructure:YouTube and Twitch localization investments in Mumbai and Bangalore are building demand for entry-level USB capture hardware among regional language streamers.
- Medical Imaging Convergence:Surgical visualization systems in Germany are repurposing broadcast-grade capture cards for 4K endoscope recording, opening non-entertainment verticals.
- EU Repairability Mandates:The EU Green Deal's right-to-repair provisions favor modular external capture designs with replaceable USB-C ports over sealed internal PCIe alternatives.
Industry Challenges
- Firmware Engineering Scarcity:Real-time video pipeline optimization requires specialized embedded systems talent concentrated in Taiwan and South Korea, constraining Western vendor R&D scaling.
- HDCP Handshake Complexity:Content protection protocol variations across streaming platforms force continuous firmware patching, elevating post-launch support costs for capture card vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Capture Card Market |
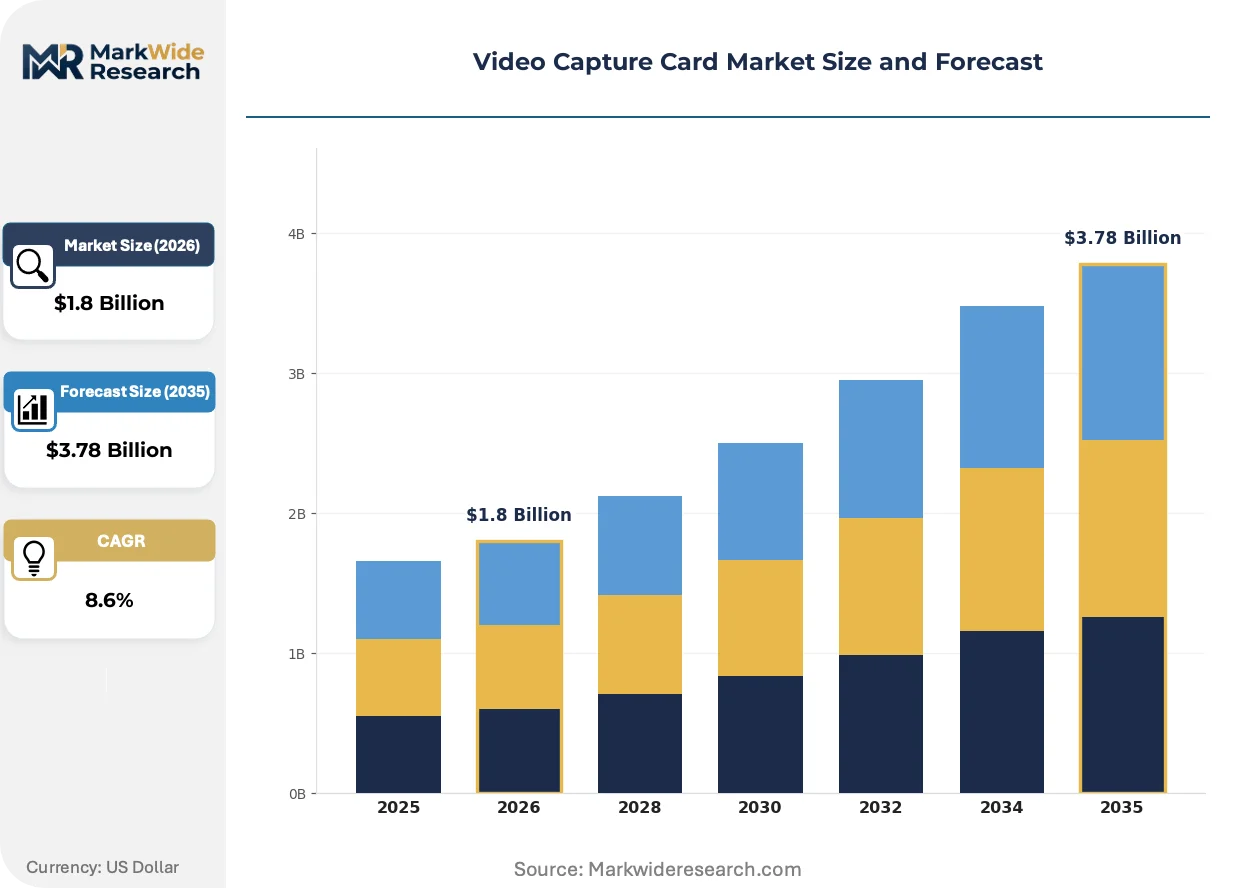
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Capture Cards, External Capture Cards, PCIe Capture Cards, USB Capture Cards, HDMI Capture Cards Technology: HD Capture, 4K Capture, HDR Capture, 8K Capture, Analog Capture Application: Live Streaming, Video Conferencing, Game Streaming, Virtual Events, Content Creation End User: Broadcasters, Content Developers, Media Agencies, Esports Teams, Online Educators |
| Companies Covered | Razer, EVGA, AVerMedia, NearStream, RØDE, Elgato, Epiphan Systems, Audio Express, NZXT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Capture Card Market Strategic Shifts
Codec transitions and interface protocol evolution are redefining hardware specifications faster than typical 18-month product lifecycles can accommodate.
PCIe 4.0 x4 capture cards with onboard AV1 hardware encoders are displacing H.264-dependent solutions in professional broadcast trucks. Live sports producers in the United States are adopting these devices to reduce upstream bandwidth costs for remote production workflows. The shift is compressing encoder licensing revenue pools while expanding addressable market for royalty-free alternatives.
The EU Radio Equipment Directive now mandates CE marking documentation for wireless-enabled capture devices, including USB Wi-Fi dongle bundles. Hardware vendors are consolidating SKUs to avoid dual certification tracks for wired-only and wireless variants. Germany's KBA-equivalent notified bodies are processing these filings with 8-12 week backlogs, delaying EU market entry for Asian manufacturers.
Enterprise procurement teams at esports organizations are consolidating capture hardware purchasing through direct vendor relationships rather than distributor channels. This disintermediation is squeezing margin for value-added resellers while rewarding vendors with captive firmware development capabilities. The pattern is most pronounced in China, where Bilibili and Douyu operate centralized equipment procurement for contracted streamers.
Video Capture Card Market Segmentation
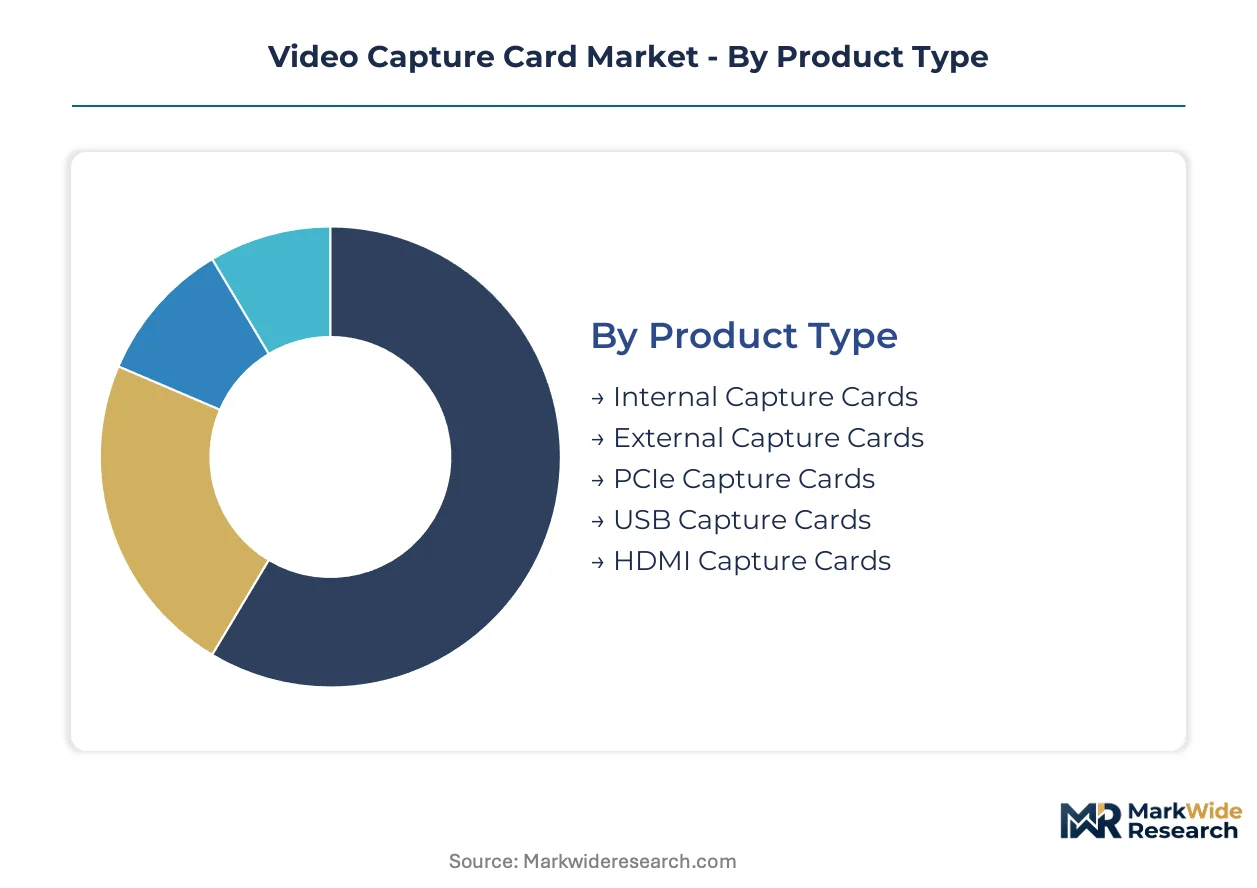
Segmentation in the video capture card market determines channel strategy, margin structure, and firmware development priorities. Product form factor and interface protocol create distinct procurement patterns across broadcast infrastructure, creator workflows, and enterprise IT deployments.
Product Type:
Distribution channels bifurcate sharply between direct-to-creator external devices and systems-integrator-mediated internal cards for broadcast trucks.
- Internal Capture Cards:These PCIe-based solutions mount directly into workstation motherboards, delivering sub-frame latency for multi-camera broadcast pipelines. Demand concentrates among German regional broadcasters upgrading OB van infrastructure to 4K120 standards, constrained by Xilinx FPGA allocation bottlenecks.
- External Capture Cards:Self-contained USB or Thunderbolt units enable laptop-based streaming without hardware installation. Solo creators in the United States leverage these for Twitch and YouTube workflows, accelerated by IRA equipment depreciation incentives.
- PCIe Capture Cards:Dedicated expansion slot hardware targets professional post-production suites with sustained throughput requirements.
- USB Capture Cards:Plug-and-play devices dominate entry-level procurement through Amazon and B&H retail channels.
- HDMI Capture Cards:Interface-specific variants optimize for consumer electronics signal compatibility in live event production.
By volume, external capture cards lead. By growth pace, internal PCIe solutions are climbing the fastest.
Technology:
Resolution tier directly maps to encoder licensing cost structure and BOM composition.
- 4K Capture:3840x2160 resolution at 60fps with 10-bit color depth has become the baseline for professional streaming platforms. Esports tournament operators in China mandate this specification for tier-one venue contracts, displacing HD infrastructure.
- HD Capture:1080p60 processing remains viable for budget-conscious educators and secondary streaming channels. Online educators in India deploy these for regional language content, constrained by upstream bandwidth limitations in tier-two cities.
- HDR Capture:Rec. 2020 color gamut support commands premium positioning for cinematic content workflows.
- 8K Capture:7680x4320 resolution targets early-adopter broadcasters and medical imaging applications.
- Analog Capture:Legacy composite and component input support serves archival digitization and industrial monitoring.
HD capture maintains the largest installed base. 4K capture is gaining share fastest as platform bitrate thresholds harden.
Application:
Use case determines latency tolerance, software integration requirements, and support contract complexity.
- Live Streaming:Real-time encoding with sub-50ms passthrough latency defines this segment. Media agencies in Germany deploy redundant capture chains for corporate webcast reliability, driven by CSRD-mandated transparency in shareholder communications.
- Game Streaming:Console and PC gameplay capture optimized for platform-native integration. Content developers in the United States prioritize OBS Studio compatibility and instant replay buffer features.
- Video Conferencing:Enterprise Zoom and Teams integration demands plug-and-play reliability over premium specifications.
- Virtual Events:Hybrid conference production requires multi-source switching and ISO recording capabilities.
- Content Creation:YouTube and TikTok post-production workflows emphasize editing timeline efficiency.
Game streaming represents the largest addressable pool. Live streaming shows the steepest expansion trajectory as enterprise hybrid events institutionalize.
End User:
Procurement authority and volume scale separate enterprise broadcast from individual creator purchasing patterns.
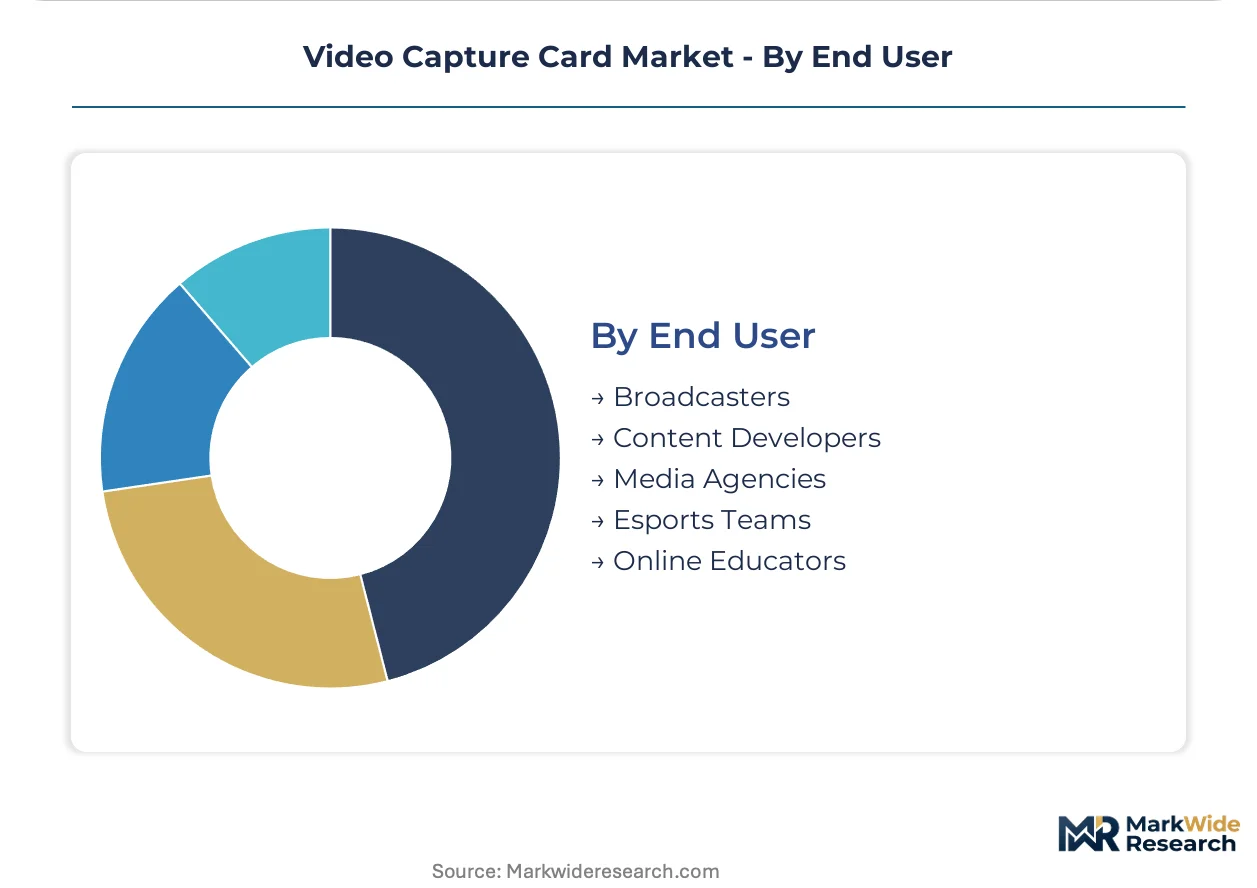
- Broadcasters:National and regional television networks with capital budgets exceeding individual creator spend by orders of magnitude. Public broadcasters in Germany centralize capture hardware procurement through framework agreements, influenced by EU Green Deal repairability mandates.
- Esports Teams:Professional gaming organizations with venue-specific infrastructure requirements. Organizations in China negotiate direct vendor relationships for tournament-standard equipment, bypassing distributor markups.
- Content Developers:Individual creators and small production shops with price-sensitive, feature-driven purchasing.
- Media Agencies:Full-service production companies managing brand-owned streaming channels.
- Online Educators:Individual instructors and institutional e-learning departments with reliability-focused requirements.
Content developers move the highest unit volumes. Broadcasters drive the fastest technology refresh cycles as interface standards migrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where professional broadcast infrastructure commands premium hardware specifications, while cost-sensitive procurement in India and China drives volume manufacturing at compressed margins.
United States
Solo content developers and esports tournament operators drive external capture card adoption through Twitch and YouTube workflows. The IRA extends equipment depreciation benefits to content production hardware, accelerating individual creator investment. Los Angeles and Austin host dense clusters of streaming studios upgrading to 4K60 HDR capture standards.
China
Bilibili and Douyu operate centralized procurement for contracted streamers, consolidating demand for tournament-standard equipment. MIIT enforces GB standards on signal processing equipment entering domestic broadcast supply chains. Shenzhen and Hangzhou concentrate hardware manufacturing and firmware engineering talent for PCIe internal card production.
Germany
Regional broadcasters upgrade OB van infrastructure to 4K120 standards, creating sustained demand for low-latency internal capture solutions. The EU Green Deal's right-to-repair provisions favor modular external designs with replaceable components. Berlin and Cologne anchor esports venue construction mandating professional capture specifications.
India
YouTube and Twitch localization investments in Mumbai and Bangalore build demand for entry-level USB capture hardware among regional language streamers. TRAI bandwidth regulations constrain upstream capacity in tier-two cities, limiting resolution requirements for online educators. The PLI scheme for electronics manufacturing attracts assembly investment in Tamil Nadu and Karnataka.
Japan
Professional post-production suites in Tokyo sustain demand for premium PCIe capture cards with sustained throughput requirements. METI standards govern electromagnetic compatibility certification for broadcast equipment deployment. Osaka hosts specialized vendors serving medical imaging convergence applications for surgical visualization systems.
Video Capture Card Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the capture card market. The vendor base separates into three tiers: captive firmware developers commanding premium positioning, third-party chipset assemblers competing on BOM efficiency, and peripheral brand extenders leveraging ecosystem lock-in. Strategic differentiation runs through software-hardware integration depth and interface protocol certification speed rather than manufacturing scale alone. Consolidation pressure intensifies as HDMI 2.1 migration compresses product refresh cycles and raises R&D fixed costs.
Among Taiwan-based specialists with captive engineering capabilities, AVerMedia and Elgato exemplify the firmware-integrated archetype that sustains margin capture across external capture devices. Razer represents the peripheral ecosystem extender, translating brand equity from gaming accessories into creator hardware procurement decisions. These three anchors illustrate how competitive positioning depends on vertical scope rather than unit volume scale.
| Leading Market Players |
|---|
| Razer |
| EVGA |
| AVerMedia |
| NearStream |
| RØDE |
| Elgato |
| Epiphan Systems |
| Audio Express |
| NZXT |
| Others |
Value Chain & Pricing Dynamics
AV1 hardware encoder substitution for legacy H.264 chipsets is simultaneously redrawing component sourcing maps toward Taiwan and South Korea while collapsing royalty-dependent pricing premiums that once sustained mid-tier vendor margins.
Pricing Analysis
Configured-to-order PCIe internal cards for German broadcast truck operators command 40-60% premiums over standard external USB units sold through Amazon retail channels. Three-tier pricing structure across premium, standard, and economy levels separates Thunderbolt 4-certified solutions for Mac workstations from USB 3.2 Gen 1 entry-level devices. Cost compression in the mid-tier is intensifying because royalty-free AV1 encoders eliminate per-unit licensing fees that previously anchored BOM calculations. Solo content developers in the United States exhibit the highest price sensitivity, while enterprise broadcasters prioritize latency specifications over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate external capture card assembly in Shenzhen, whereas strategic FPGA stockpiling by German and United States PCIe card manufacturers reflects Xilinx allocation anxiety. Component sourcing draws from Taiwan for programmable logic, South Korea for DRAM modules, and China for PCB fabrication and final assembly. Single-source vulnerability concentrates in Xilinx and Altera programmable logic for real-time video processing pipelines. Distribution runs through direct vendor relationships with Chinese esports platforms and systems integrators for broadcast infrastructure, bypassing traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through centralized procurement at Bilibili, Douyu, and regional German broadcast consortiums, fragmenting pricing leverage away from distributor intermediaries toward volume-committed end users.
For Market Incumbents: Shield firmware development capabilities through captive engineering retention in Taiwan and South Korea, where embedded systems talent scarcity constrains Western vendor R&D scaling. Prioritize HDMI 2.1 interface certification speed to outpace product refresh cycles compressing below 18 months. Defend margin position by deepening software-hardware integration depth rather than competing on BOM efficiency against third-party chipset assemblers. For New Entrants and Emerging Players: Anchor in India's entry-level USB capture segment, where YouTube and Twitch localization investments in Mumbai and Bangalore are building demand among regional language streamers with limited incumbent penetration. Target online educators in tier-two Indian cities constrained by TRAI bandwidth regulations that limit resolution requirements and favor cost-optimized hardware. Pursue white-label partnerships with Tamil Nadu and Karnataka electronics manufacturers benefiting from PLI scheme incentives. For Investors and Strategic Acquirers: The market sits at a codec-transition phase that favors captive firmware developers over third-party chipset assemblers, as AV1 hardware encoding displaces H.264 licensing dependencies and rewards vertical integration. Acquisition targets should display in-house encoder optimization capabilities and established certification relationships with the FCC and EU notified bodies. Monitor Intel Thunderbolt royalty structures and FPGA allocation stability as inflection indicators for premium-tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| AV1 Hardware Encoder Integration | Royalty-free codec adoption collapses H.264 licensing costs for mid-tier vendors competing on BOM efficiency. |
| HDMI 2.1 Interface Certification | 48Gbps bandwidth support for 4K120 workflows separates professional broadcast tiers from consumer-grade alternatives. |
| Firmware Engineering Captivity | In-house embedded systems talent in Taiwan and South Korea sustains margin capture through software-hardware integration depth. |
| Direct Procurement Relationships | Bypassing distributor channels with Chinese esports platforms and German broadcast consortiums captures volume pricing power. |
| EU Repairability Compliance | Modular external designs with replaceable USB-C ports align with Green Deal mandates favoring sustainable hardware architectures. |
Study Parameters
Initial hypotheses were tested against primary input from broadcast engineering directors, esports tournament operators, content creator equipment purchasers, and PCIe card firmware developers, and refined through secondary validation against FCC certification databases, MIIT GB standard filings, EU Radio Equipment Directive documentation, and customs trade data for video processing equipment. Bottom-up demand modeling across product form factors and interface protocols was triangulated with top-down market sizing derived from encoder licensing revenue pools and semiconductor shipment reports.
Variance decomposition across the projection horizon isolates volume drivers by resolution tier, end-user procurement authority, and regional regulatory cluster. The analytical framework segments by product type, technology specification, application use case, and geographic adoption pattern. CAGRs were derived from installed base replacement cycles and platform bitrate threshold enforcement trajectories. Forecast inputs incorporate FPGA allocation constraints, Thunderbolt royalty stack evolution, and AV1 hardware encoder penetration curves.
Decision-makers should treat outputs as directional under assumptions of stable HDMI protocol migration timelines and sustained creator economy equipment depreciation incentives; material deviation in codec adoption curves or regulatory certification delays would warrant model refresh. Practitioners should keep alternative scenarios live as FPGA supply concentration and wireless-enabled capture device CE marking backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Automotive Compact Camera Module Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Thermal Imaging Systems Market
Imaging
Cinematographic Camera Market
Imaging
Machine Vision Camera Market
Imaging
AI Camera Market
Imaging
Infrared Imaging Software Market
Imaging
Borescope Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Global Automotive Imaging Market
Imaging
Microscope Digital Cameras Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Embedded Smart Cameras Market
Imaging
Global Digital Binoculars Market
Imaging
Global Broadcast Cameras Market
Imaging
Software-Defined Camera (SDC) Market