
 Digitizer Market | 2026-2036
Digitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Digitizer Market Analysis
Specialized optical engineering talent is bifurcating the competitive landscape as legacy CCD expertise loses premium value. Fujitsu leverages its deep bench in contact-image-sensor architecture to dominate high-speed document scanning for enterprise archiving. Canon anchors its position through in-house production of precision lens arrays that control cost curves across flatbed and drum product lines. HP Inc. differentiates by sustaining R&D intensity in laser triangulation methods for surveying-grade field units.
A digitizer is an electro-optical input device that converts physical images, documents, or spatial coordinates into digital data through sensor arrays with resolutions typically ranging from 300 to 4800 dots per inch. Flatbed configurations remain the volume anchor in artwork preservation and historical archives due to their stability with fragile originals, while handheld laser variants represent the fastest-expanding margin pool in mobile surveying and field mapping. Optical technology leads installed base across education and engineering end users, though contact-sensor platforms compete aggressively on unit economics in emerging personal-use segments.
FCC electromagnetic-emission standards in the United States, CE marking requirements under EU machinery directives, and RoHS substance restrictions collectively shape product design cycles and market-access timelines for manufacturers. Japan's METI energy-efficiency benchmarks and China's GB standards for electronic products add further compliance layers for cross-border suppliers. Stakeholders must monitor convergence between ESG disclosure rules and hardware circularity mandates as procurement criteria harden across institutional buyers.
Market Dynamics
Optical scanning architectures are systematically dismantling legacy CCD platforms across institutional document management, creating a bifurcation where engineering talent pools and capital allocation strategies must pivot toward contact-image-sensor expertise or risk obsolescence.
Growth Catalysts
- E-waste directive enforcement:Germany's tightened circular economy regulations are compelling engineering firms to accelerate CAD archiving digitization, directly stimulating large-format flatbed procurement cycles.
- Contact-image-sensor maturation:Advances in CIS architecture are compressing unit economics for high-volume document capture, expanding addressable demand among emerging-market education institutions.
- Mobile surveying expansion:Handheld laser triangulation units are capturing field-mapping workflows previously served by total stations, opening margin pools in construction and environmental monitoring.
Market Restraints
- Precision optics supply concentration:Japanese and German lens array manufacturers control critical upstream capacity, exposing flatbed and drum digitizer producers to input bottlenecks and price volatility.
- CCD inventory obsolescence:Legacy sensor stockpiles and maintenance expertise are depreciating rapidly as optical platforms dominate new installations, stranding capital in installed bases.
- RoHS substance compliance:EU restrictions on hazardous materials in electronic products are extending product redesign timelines and certification costs for cross-border suppliers.
Strategic Opportunities
- Artwork preservation digitization:Museums and cultural heritage institutions in Italy and France are systematically converting fragile collections, creating sustained demand for archival-grade flatbed stability.
- Energy-efficiency incentives:Japan's METI benchmarking programs are subsidizing next-generation sensor deployments, accelerating replacement cycles among institutional buyers.
- Cloud-integrated capture workflows:Enterprise document management platforms are embedding digitizer APIs, enabling hardware-as-a-service models that reduce upfront procurement friction.
Industry Challenges
- Optical engineering talent scarcity:Specialized CIS and laser triangulation expertise commands premium compensation, constraining R&D velocity for mid-tier manufacturers competing with dominant incumbents.
- Multi-jurisdiction certification complexity:Simultaneous FCC, CE marking, and GB standard compliance requirements are extending market-access timelines and diverting engineering resources from product differentiation.
- Legacy system integration friction:Enterprise archiving environments running proprietary document management software require custom driver development, inflating deployment costs and elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digitizer Market |
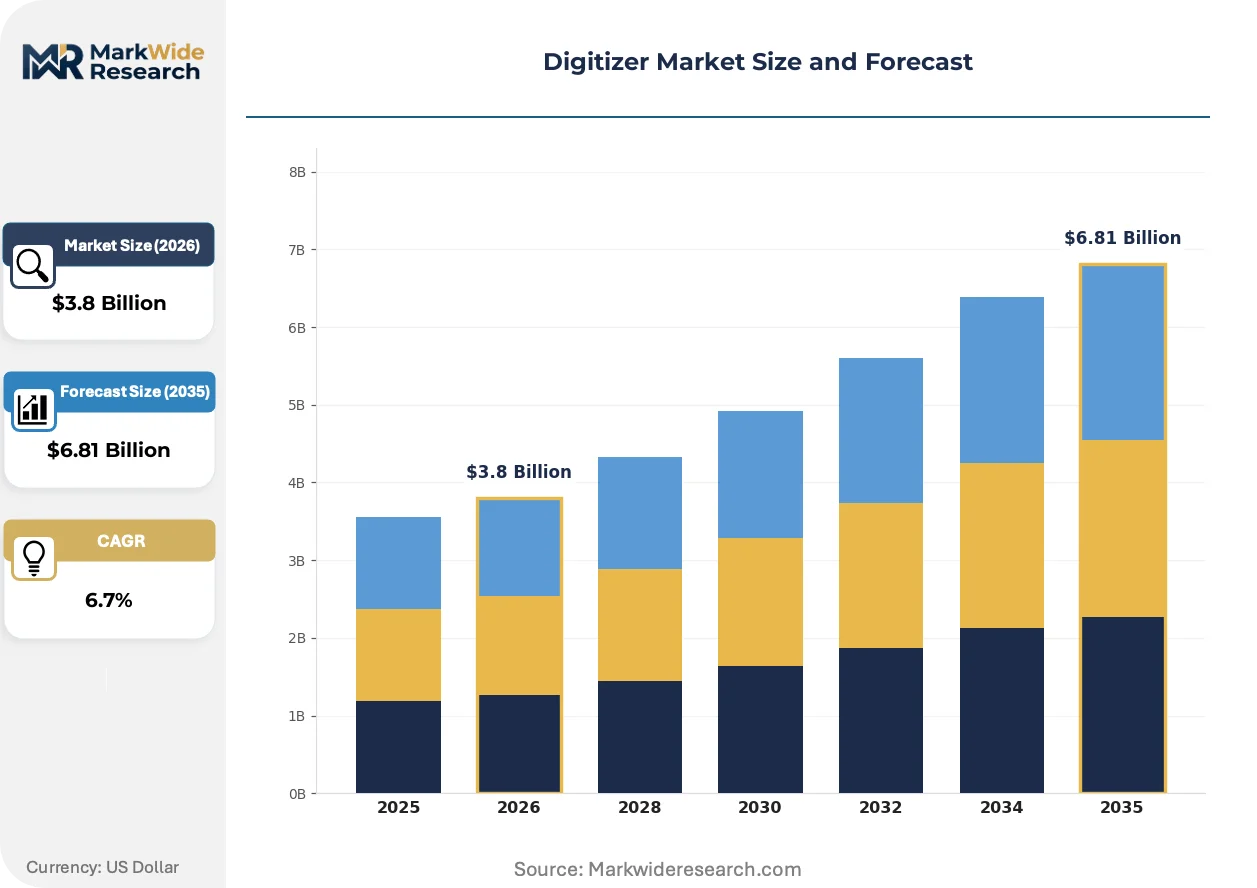
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Handheld, Drum, A0 Technology: Optical, Laser, CCD, Contact End User: Education, Engineering, Historical Archives, Personal Application: Surveying, Document Management, Artwork Preservation, Mapping |
| Companies Covered | Ricoh, Canon, Xerox, Fujitsu, HP Inc., Konica Minolta, Brother Industries, Panasonic, Kyocera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digitizer Market Emerging Trajectories
Sensor architecture evolution, regulatory disclosure mandates, and procurement model restructuring are converging to reshape competitive positioning and value capture mechanisms across the digitizer value chain.
Contact-image-sensor technology is decomposing the traditional resolution-versus-speed tradeoff that constrained document management workflows for decades. Enterprise archiving departments in North American financial services and East Asian government agencies are adopting CIS platforms at accelerated replacement cycles. This architectural shift is compressing the premium historically commanded by CCD-based systems and redistributing margin toward software-integrated capture solutions.
EU CSRD disclosure requirements are mandating granular hardware circularity reporting from institutional technology suppliers. Manufacturers must now document component provenance, repairability scores, and end-of-life recovery pathways across flatbed and handheld product lines. Large-format digitizer vendors serving European engineering and heritage sectors are restructuring supply chains to meet these transparency thresholds, with compliance emerging as a procurement gatekeeper.
Institutional buyers are consolidating vendor relationships around integrated capture-to-archive service contracts rather than discrete hardware transactions. Value-added resellers and direct manufacturer channels are being displaced by platform partnerships that bundle digitizer deployment, cloud storage, and metadata indexing. This pattern is most pronounced among US healthcare systems and German automotive suppliers managing high-volume technical document conversion.
Digitizer Market Segmentation
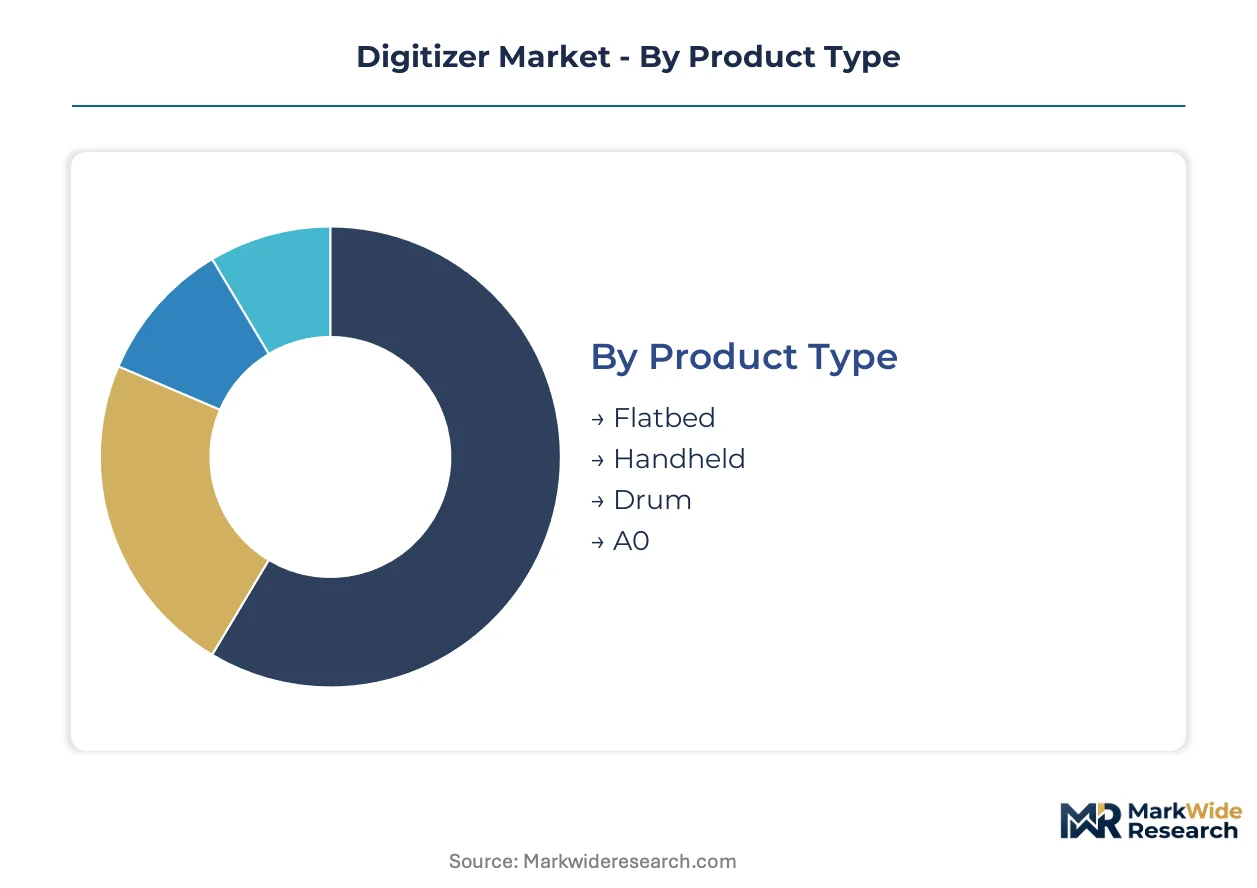
Segmentation in the digitizer market reveals distinct margin architectures across hardware configurations, sensor technologies, and institutional versus consumer demand pools. Understanding these divisions enables precise targeting of procurement cycles and R&D allocation.
Product Type:
Margin pools concentrate in large-format flatbed units serving engineering and heritage institutions, while handheld variants capture expanding field-service premiums.
- Flatbed:Stationary scanning platforms with precision motion control and stabilized illumination arrays. Engineering firms in Germany and Japan are accelerating procurement under tightened E-waste directives mandating CAD archiving digitization.
- Handheld:Portable laser triangulation units optimized for mobile coordinate capture. Environmental monitoring agencies and construction contractors are displacing total station workflows, opening the steepest expansion trajectory in mobile surveying.
- Drum:Rotational scanning mechanisms for continuous-feed document processing.
- A0:Oversized flatbed format accommodating architectural blueprints and technical drawings.
The dominant share belongs to flatbed configurations, while handheld units are gaining share fastest.
Technology:
Cost tier stratification separates mature CCD platforms from next-generation optical and contact-sensor architectures competing on speed-to-resolution ratios.
- Optical:Lens-array-based scanning with charge-coupled device or complementary metal-oxide-semiconductor sensors. North American financial services and East Asian government agencies are replacing legacy CCD installations at accelerated replacement cycles.
- Contact:Image-sensor arrays with direct document contact eliminating optical path length. Emerging-market education institutions are adopting CIS platforms as unit economics compress below CCD thresholds.
- Laser:Triangulation-based spatial coordinate capture for field surveying applications.
- CCD:Legacy charge-coupled device technology facing rapid depreciation in installed base value.
Optical platforms command the dominant share, though contact sensors are expanding most quickly in volume terms.
End User:
Customer type determines procurement channel structure, with institutional buyers consolidating around integrated service contracts versus discrete hardware transactions.
- Engineering:Technical document conversion and CAD archiving workflows. German automotive suppliers and Japanese construction conglomerates are bundling digitizer deployment with cloud storage and metadata indexing.
- Historical Archives:Fragile original preservation requiring stabilized illumination and minimal handling. Museums in Italy and France are systematically converting collections, creating sustained demand for archival-grade stability.
- Education:High-volume document capture for administrative and research purposes.
- Personal:Consumer-grade scanning for home office and creative applications.
Engineering end users hold the dominant share, while historical archives are climbing the fastest as ESG disclosure rules harden procurement criteria.
Application:
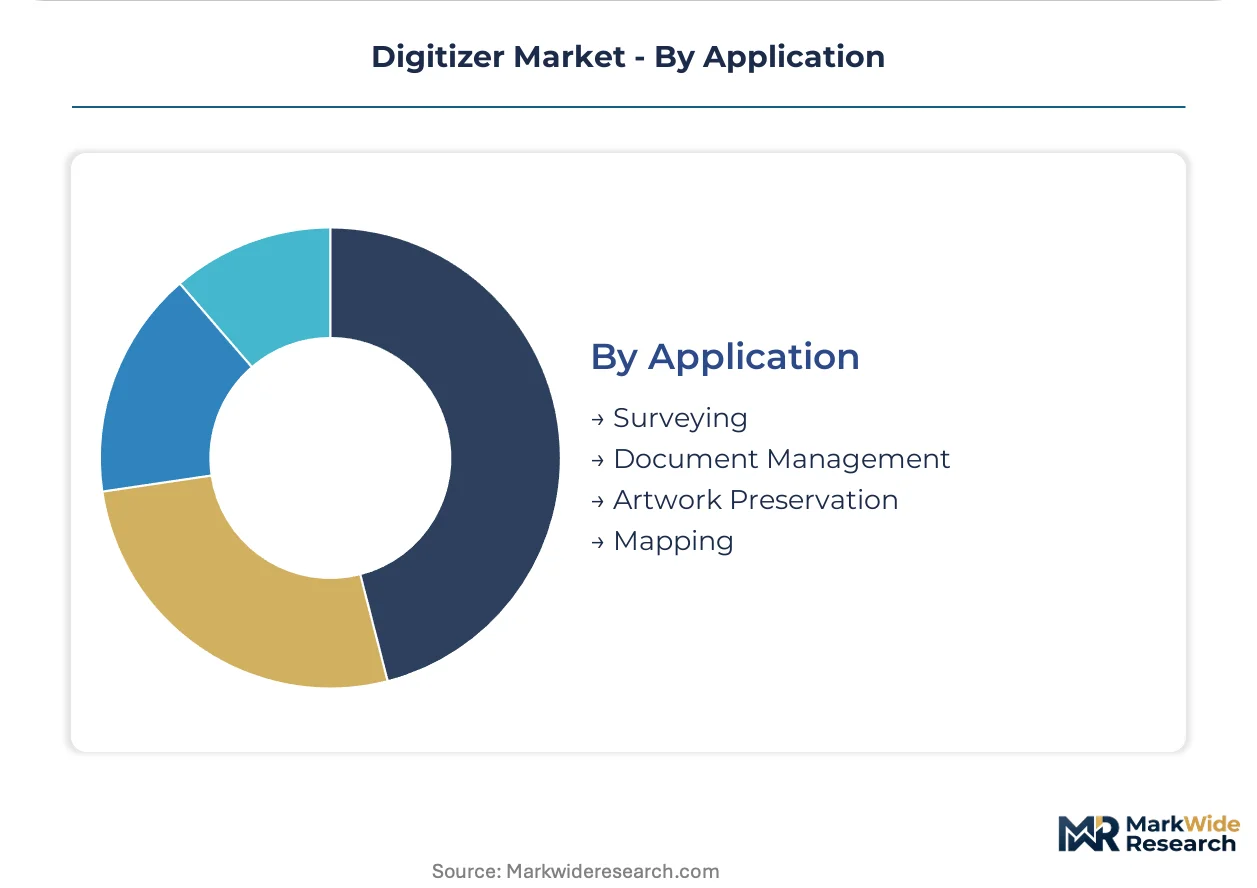
Volume concentration varies sharply between mature document management workflows and emerging field-mapping use cases with distinct hardware requirements.
- Document Management:Enterprise archiving and workflow digitization across financial and government sectors. US healthcare systems are consolidating vendor relationships around capture-to-archive platform partnerships.
- Surveying:Field coordinate capture for construction and infrastructure projects. METI energy-efficiency subsidies in Japan are accelerating replacement cycles among institutional buyers deploying next-generation sensor platforms.
- Artwork Preservation:Cultural heritage digitization with specialized handling protocols.
- Mapping:Geospatial data collection for environmental and urban planning.
Document management retains the dominant share, while surveying applications are capturing margin expansion fastest through handheld laser displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering firms command pricing premiums for archival-grade flatbed systems, while Chinese manufacturers compress margins on volume document scanners through aggressive CIS platform scaling.
United States
Healthcare systems and financial services drive enterprise document capture demand. FCC electromagnetic-emission standards shape product design cycles for cross-border suppliers. The Boston-Cambridge corridor anchors high-precision optical engineering talent pools serving archival digitization workflows.
Germany
Automotive suppliers and engineering conglomerates accelerate CAD archiving procurement under tightened E-waste directives. CE marking requirements and RoHS substance restrictions extend certification timelines. The Stuttgart-Munich industrial belt concentrates precision optics manufacturing capacity for flatbed and drum configurations.
Japan
Construction conglomerates and environmental monitoring agencies deploy handheld laser units for field surveying displacement. METI energy-efficiency benchmarks subsidize next-generation sensor replacements. The Nagoya-Osaka manufacturing corridor hosts captive lens array production controlling upstream supply.
China
Emerging-market education institutions adopt contact-image-sensor platforms as unit economics compress below legacy thresholds. GB standards for electronic products add compliance layers for domestic and cross-border suppliers. The Yangtze River Delta cluster dominates volume manufacturing of consumer-grade scanning hardware.
France
Museums and cultural heritage institutions systematically convert fragile collections, sustaining demand for archival-grade flatbed stability. EU CSRD disclosure requirements mandate hardware circularity reporting from technology suppliers. The Paris-Saclay research cluster advances optical sensor architectures for preservation workflows.
Digitizer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated structure where precision optics specialists capture premium margins while scale manufacturers dominate volume segments. The vendor base consolidates around three strategic groupings: diversified electronics conglomerates with captive sensor production, specialized imaging equipment pure-plays, and contract manufacturers serving private-label channels. Dominant competitive moves include backward integration into precision lens production and strategic partnerships with cloud-integrated document management platforms.
Within the diversified conglomerate tier, Canon, Fujitsu, and HP Inc. occupy positions that exemplify divergent technology bets. Canon anchors precision lens array production across flatbed and drum product lines. Fujitsu represents contact-image-sensor architecture dominance in high-speed enterprise archiving. HP Inc. exemplifies sustained R&D positioning in laser triangulation methods for field surveying applications.
| Leading Market Players |
|---|
| Ricoh |
| Canon |
| Xerox |
| Fujitsu |
| HP Inc. |
| Konica Minolta |
| Brother Industries |
| Panasonic |
| Kyocera |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for precision lens arrays from Japanese and German suppliers compress margin flexibility for flatbed and drum digitizer manufacturers, concentrating pricing power upstream while forcing downstream producers toward captive production or long-term offtake commitments.
Pricing Analysis
The customization-premium spread separates configured-to-order archival-grade flatbed systems from standard document scanners by a factor reflecting precision optics certification and after-sales service bundling. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ISO-grade lens certification and volume procurement scale. Cost compression in emerging-market education segments is intensifying because Chinese CIS manufacturers are scaling below legacy CCD thresholds. Enterprise engineering buyers show least price sensitivity due to E-waste directive compliance mandates, while personal-use segments remain most responsive to unit cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai-to-Long Beach and Yokohama-to-Hamburg trade lanes expose digitizer assemblers to container availability volatility and port congestion surcharges. Precision lens array production concentrates in Japan, Germany, and Taiwan, while CIS sensor fabrication draws from South Korean and Chinese foundries. Supply chain risk centers on single-source dependency for high-resolution optical assemblies. Distribution runs through authorized reseller networks for institutional buyers and direct-to-consumer e-commerce for personal-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-integrated capture workflows and metadata indexing services are expanding faster than hardware unit sales, positioning the digitizer market as a service-attach opportunity where recurring revenue streams command superior valuation multiples.
For Market Incumbents: Consolidate backward integration into precision lens production to defend against Japanese and German supplier bottlenecks, and deepen API partnerships with enterprise document management platforms to lock in institutional replacement cycles before CIS commoditization accelerates.
For New Entrants and Emerging Players: Lead with handheld laser triangulation units targeting environmental monitoring agencies in Southeast Asia and Latin America, where total station displacement creates white-space demand and METI-style efficiency subsidies are beginning to replicate.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized optical engineering talent scarcity will drive acquirer interest in CIS and laser triangulation pure-plays with proven institutional customer bases; watch for inflection when EU CSRD disclosure mandates harden hardware circularity requirements into procurement gatekeepers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Production | Canon and Fujitsu already control captive supply, forcing followers to secure Japanese or German optical partnerships. |
| API Integration with Cloud Archive Platforms | US healthcare systems and German automotive suppliers are consolidating vendor relationships around bundled service contracts. |
| CIS Architecture Scale-Up | Chinese manufacturers compress unit economics below CCD thresholds for emerging-market education procurement. |
| Handheld Laser Unit Field Expansion | Environmental monitoring agencies in Japan displace total station workflows with mobile coordinate capture. |
| CSRD Compliance Supply Chain Restructuring | European heritage institutions now mandate component provenance documentation as a procurement gatekeeper. |
Methodological Framework
The analysis maps flatbed, handheld, drum, and A0 format sub-sectors, each validated through primary interviews with digitizer product managers, precision optics procurement leads at engineering conglomerates, museum conservation technologists, and enterprise document management platform engineers, combined with secondary validation against FCC equipment authorization databases, METI energy-efficiency benchmarking reports, EU CSRD disclosure filings, and customs trade flow records, with bottom-up unit shipment builds cross-checked against top-down addressable market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period, with segmentation dimensions including product configuration, sensor technology architecture, end-user industry vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and emerging application penetration curves, incorporating METI subsidy acceleration effects and E-waste directive enforcement timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FCC electromagnetic-emission standards, CE marking machinery directives, and RoHS substance restrictions; material policy shifts in EU circularity mandates or Japanese energy-efficiency benchmarking would require re-modeling. Practitioners should keep alternative scenarios live as CIS platform commoditization and cloud-integrated capture adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Hyperspectral Imaging Camera Market
Imaging
Global Thermal Imager Market
Imaging
Underwater Camera Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Global Image Signal Processor Market
Imaging
IR Camera Market
Imaging
Handheld Imager Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Global Image Processing Systems Market
Imaging
Mobile Imaging Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Global AI in Computer Vision Market
Imaging
Mobile Camera Module Market
Imaging
Wide Field Imaging Devices Market
Imaging
Machine Vision System Market