
 AI-Enabled Testing Tools Market | 2026-2036
AI-Enabled Testing Tools Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Enabled Testing Tools Market Analysis
Software engineering talent scarcity is rotating enterprise investment toward autonomous testing platforms that reduce manual script maintenance. IBM Corporation leverages deep research heritage in natural language processing to anchor its position in intelligent test orchestration. Tricentis specializes in model-based automation that sustains execution speed across complex enterprise stacks. Katalon competes through accessible pricing that extends platform reach to mid-market development teams.
AI-enabled testing tools integrate machine learning models, computer vision, and predictive analytics to autonomously generate, execute, and maintain test scripts across software environments, typically operating with execution speeds measured in milliseconds per test case and defect detection accuracy thresholds exceeding rule-based frameworks. Their primary commercial purpose centers on collapsing release cycles while preserving coverage breadth in continuous integration pipelines. Automated testing dominates current procurement volumes as enterprises prioritize regression suite acceleration, while security testing represents the fastest-expanding category as shift-left mandates harden supply chain integrity requirements. Cloud-based deployment captures the largest margin pool through recurring subscription architectures, though hybrid configurations gain traction among regulated entities managing sensitive workload partitioning.
FDA guidance on software as a medical device, EU AI Act conformity assessment obligations, and NIST AI risk management frameworks collectively elevate documentation and traceability requirements for testing tool vendors serving regulated industries. These standards reshape product roadmaps toward explainable test outcomes and audit-ready execution logs. Stakeholders must monitor evolving jurisdictional divergence in algorithmic accountability mandates to anticipate certification burdens that will determine competitive access across priority customer segments.
Market Dynamics
DevOps velocity mandates are compressing release cycles from months to days, forcing quality assurance infrastructure to automate script generation and maintenance without human intervention. This structural pressure is redistributing budget from manual testing labor toward autonomous orchestration platforms.
Growth Catalysts
- EU AI Act conformity obligations:Article 10 requirements for high-risk AI systems mandate automated testing with traceable documentation, compelling financial services and healthcare enterprises to procure intelligent verification platforms.
- Shift-left security integration:Supply chain attacks on software dependencies are accelerating procurement of autonomous security testing tools embedded within CI/CD pipelines.
- India's enterprise software clusters:Bangalore and Hyderabad development centers are driving concentrated demand for cloud-based testing infrastructure serving offshore delivery operations.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for computer vision-based test analysis depend on NVIDIA hardware subject to supply constraints and price spikes.
- Model explainability limitations:Black-box AI test generation produces outputs that fail audit scrutiny under FDA software-as-medical-device guidance and EU AI Act transparency requirements.
- Fragmented toolchain integration:Enterprise environments mixing SAP, Salesforce, and custom Java stacks require expensive connector development for unified test orchestration.
Strategic Opportunities
- German automotive software verification:ISO 26262 functional safety mandates for autonomous driving systems create unmet demand for AI-generated edge-case test suites.
- Natural language test specification:Convergence of large language models with computer vision enables business analysts to generate executable tests from plain English requirements.
- Outcome-based pricing models:Vendors can capture value through defect-prevention guarantees rather than seat-based subscriptions, aligning commercial terms with customer ROI.
Industry Challenges
- Test data synthesis expertise:Engineering teams lack practitioners capable of generating statistically representative synthetic datasets that preserve production schema constraints without privacy exposure.
- Legacy mainframe integration:COBOL and assembler systems in banking and insurance resist API-based test automation, requiring costly screen-scraping and emulator middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Enabled Testing Tools Market |
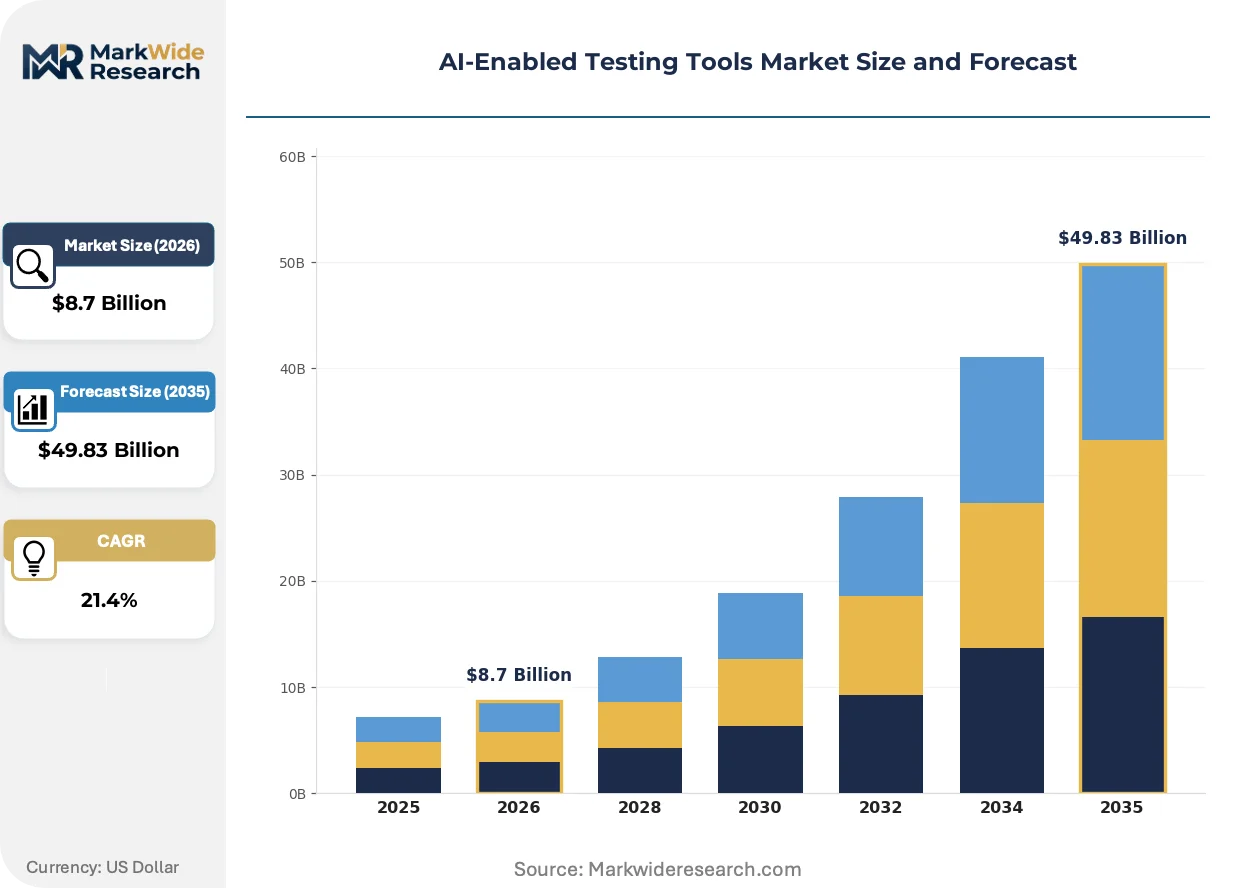
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $49.83 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Testing, Performance Testing, Functional Testing, Security Testing End User: Enterprises, Software Vendors, IT Service Providers, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Open Source Application: Web Applications, Mobile Applications, APIs, Embedded Systems |
| Companies Covered | Capgemini SE, IBM Corporation, Sauce Labs Inc., Applitools, Tricentis, Mabl, Katalon, Functionize, Inc, TestRigor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Enabled Testing Tools Market Emerging Trajectories
Autonomous test generation is displacing rule-based script maintenance as the dominant quality assurance paradigm. Three converging developments are compressing the traditional testing lifecycle and redistributing competitive advantage toward vendors with proprietary model training data.
Self-healing test scripts powered by computer vision and reinforcement learning are displacing brittle DOM-based selectors that fail on minor UI changes. Retail and SaaS enterprises with weekly release cadences are deploying these systems at scale. This capability is displacing offshore manual regression teams and collapsing the economics of traditional test outsourcing arrangements.
The EU AI Act's conformity assessment framework mandates explainable test outcomes and audit-ready execution logs for high-risk AI deployments. Vendors must architect products to generate human-interpretable rationale for each generated test case and defect flag. Financial services procurement teams in Frankfurt and Paris are prioritizing platforms with built-in documentation pipelines over pure execution speed.
Enterprise buyers are consolidating vendor relationships around integrated quality platforms rather than point solutions for functional, performance, and security testing. Mid-market development teams in Austin and Berlin are rejecting best-of-breed toolchains in favor of unified subscriptions. This consolidation is most visible among Series C software companies seeking to reduce toolchain management overhead ahead of IPO readiness.
AI-Enabled Testing Tools Market Segmentation
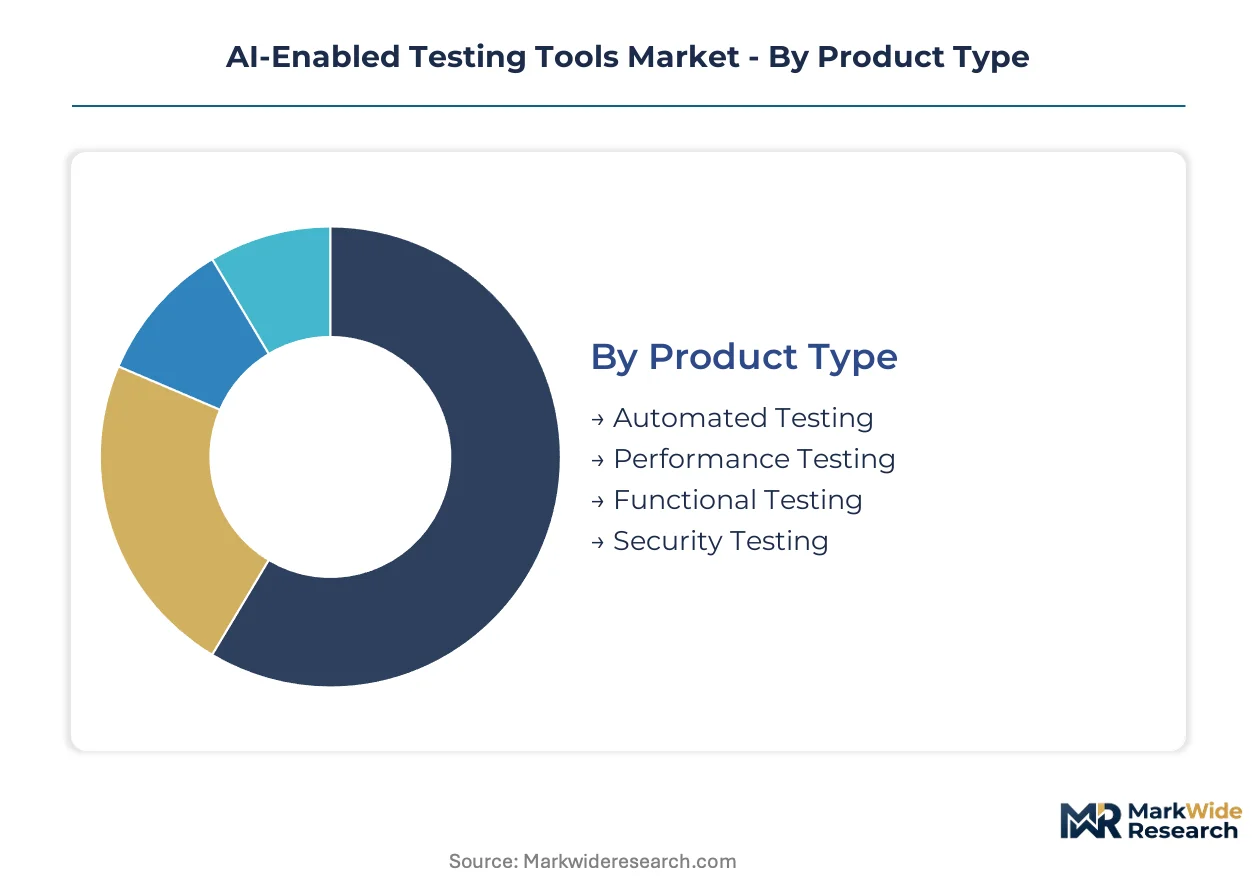
Segmentation in AI-enabled testing tools reveals how procurement patterns split between regulated enterprises demanding audit trails and agile development shops prioritizing execution velocity. Understanding these divides exposes where vendors must architect compliance features versus speed optimizations.
Product Type:
Geographic spread varies sharply across product categories, with automated testing concentrated in domestic enterprise accounts while security testing exports dominate cross-border procurement from specialized vendors.
- Automated Testing:Platforms autonomously generate and maintain regression suites using reinforcement learning to adapt scripts to UI changes without human intervention. Demand concentrates in United States financial services and German automotive supply chains where release frequency mandates outpace manual team scaling.
- Security Testing:Autonomous vulnerability scanning and dependency analysis tools integrate into CI/CD pipelines to flag supply chain risks pre-deployment. Export-led procurement from Israeli and Estonian specialists serves global SaaS companies facing shift-left compliance mandates.
- Performance Testing:Load simulation platforms using predictive analytics to model system behavior under traffic spikes.
- Functional Testing:Business-logic verification tools validating application behavior against specifications.
Automated testing holds the largest share; momentum sits with security testing.
End User:
Cost tier stratification separates enterprise buyers paying premium for compliance documentation from mid-market adopters prioritizing per-seat economics.
- Enterprises:Fortune 500 technology, financial services, and healthcare organizations procure integrated platforms with audit-ready execution logs and explainable AI outputs. United States and German buyers drive volume, with procurement teams mandating EU AI Act conformity features ahead of formal deadlines.
- Software Vendors:Product companies embedding testing infrastructure into their own development pipelines and customer-facing quality assurance services. India's Bangalore and Hyderabad clusters represent concentrated demand for cloud-based orchestration serving offshore delivery models.
- IT Service Providers:Systems integrators and managed testing services firms deploying platforms across client environments.
- Educational Institutions:Universities and coding bootcamps licensing platforms for curriculum integration and research purposes.
Enterprises dominate procurement value; software vendors are expanding most quickly.
Deployment:
Application criticality determines deployment choice, with customer-facing workloads favoring cloud elasticity and sensitive systems demanding data residency controls.
- Cloud-Based:SaaS delivery models with subscription billing and elastic compute scaling for variable test execution loads. United States and Indian development teams favor this model for its elimination of infrastructure management overhead and rapid provisioning for sprint cycles.
- Hybrid:Configurations partitioning sensitive test data on-premises while leveraging cloud compute for execution orchestration. German automotive and French financial services buyers mandate this architecture to satisfy works council and CNIL data localization requirements.
- On-Premises:Self-managed installations in air-gapped environments with complete data sovereignty.
- Open Source:Community-maintained frameworks with commercial support subscriptions for enterprise feature extensions.
Cloud-based deployment commands the margin pool; hybrid configurations gain share fastest.
Application:
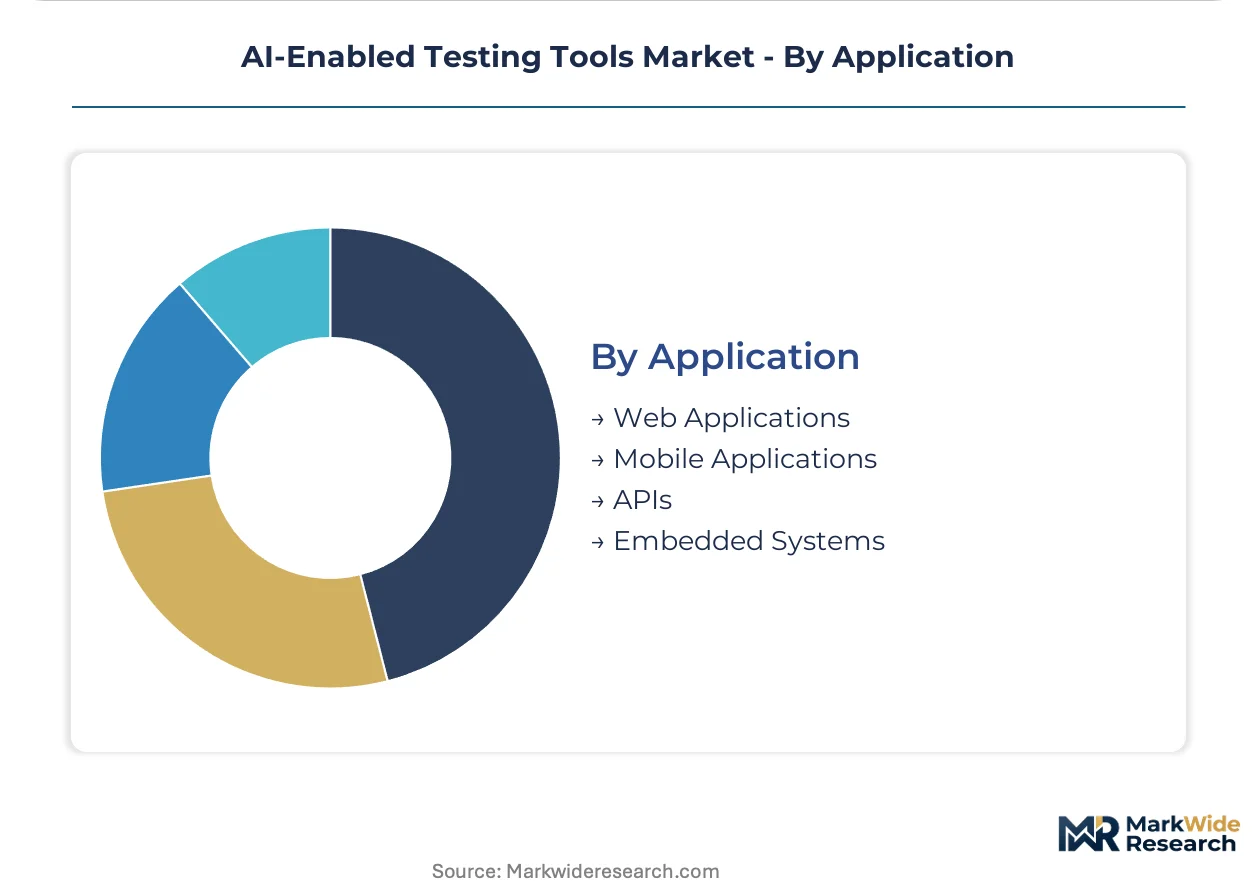
Volume concentration tracks software development modality shifts, with web and mobile dominating current pipelines while API testing scales with microservices architecture adoption.
- APIs:Automated contract testing, schema validation, and endpoint security scanning for microservices architectures. United States fintech and healthcare IT sectors drive concentrated demand as these industries decompose monolithic systems into service meshes requiring continuous interface verification.
- Mobile Applications:Cross-platform test generation spanning iOS and Android with device farm integration for hardware-specific validation. Indian and Vietnamese development shops serving global consumer app publishers represent export-led procurement concentration.
- Web Applications:Browser-based functional and visual regression testing for SaaS products.
- Embedded Systems:Hardware-in-the-loop testing for firmware and IoT device software stacks.
API testing holds the steepest expansion trajectory; web applications retain the volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises deploy AI-enabled testing tools for DevOps velocity, while German buyers prioritize EU AI Act compliance documentation and Indian development clusters favor cloud-based orchestration for offshore delivery economics.
United States
Financial services and healthcare IT sectors drive procurement of autonomous test generation platforms, with FDA software-as-medical-device guidance elevating documentation requirements. NIST AI risk management frameworks reshape vendor selection criteria toward explainable test outcomes. Silicon Valley and Austin development clusters concentrate demand for self-healing scripts that collapse regression cycles from weeks to hours.
Germany
Automotive software verification for autonomous driving systems creates specialized demand for ISO 26262-compliant test suites. EU AI Act conformity assessment obligations mandate audit-ready execution logs and human-interpretable rationale for each generated test case. Stuttgart and Munich engineering centers procure hybrid deployment configurations to satisfy works council data localization requirements while leveraging cloud compute elasticity.
India
Bangalore and Hyderabad enterprise software clusters represent concentrated demand for cloud-based testing infrastructure serving offshore delivery operations. Cost-optimized procurement favors accessible pricing tiers that extend platform reach beyond Fortune 500 accounts. RBI guidelines on IT governance for financial institutions accelerate adoption of automated security testing embedded within CI/CD pipelines.
United Kingdom
London fintech and SaaS product companies prioritize execution speed over compliance documentation, favoring SaaS delivery models with elastic compute scaling. FCA operational resilience requirements for critical third-party services harden supply chain integrity verification mandates. Cambridge and Manchester development hubs drive procurement of API testing tools for microservices architecture decomposition.
France
Paris financial services procurement teams prioritize platforms with built-in documentation pipelines for EU AI Act transparency requirements. CNIL data localization rules mandate hybrid deployment architectures partitioning sensitive test data on-premises. Sophia Antipolis technology cluster generates demand for natural language test specification capabilities that enable business analysts to generate executable tests from plain French requirements.
AI-Enabled Testing Tools Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around vendors offering unified quality platforms rather than point solutions. The upper tier captures premium pricing through compliance documentation features and audit-ready execution logs, while specialists compete on execution speed and accessible economics. Three strategic archetypes dominate: research-anchored technology conglomerates, model-based automation specialists, and cloud-native accessibility challengers. Competitive moves center on M&A for toolchain integration capabilities and outcome-based pricing models that align commercial terms with customer defect-prevention ROI.
Within the research-anchored tier, IBM Corporation occupies a position exemplifying deep heritage in natural language processing applied to intelligent test orchestration. Tricentis and Katalon represent contrasting archetypes—Tricentis anchors the model-based automation specialist position, while Katalon exemplifies the accessibility challenger competing through pricing that extends platform reach to mid-market development teams.
| Leading Market Players |
|---|
| Capgemini SE |
| IBM Corporation |
| Sauce Labs Inc. |
| Applitools |
| Tricentis |
| Mabl |
| Katalon |
| Functionize, Inc |
| TestRigor |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity assessment obligations gate both vendor qualification and price differentiation simultaneously, compelling testing tool providers to embed audit-ready documentation pipelines that separate premium compliance tiers from basic automation offerings. This regulatory architecture concentrates pricing power among incumbents with established certification infrastructure while forcing mid-tier vendors to absorb compliance engineering costs or exit regulated segments.
Pricing Analysis
Long-term enterprise subscriptions dominate contract structures, with annual recurring revenue models capturing the largest margin pool through seat-based tiers that scale with development team size. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by compliance documentation depth and explainable AI feature sets. Cost compression in the standard tier intensifies because open-source frameworks and cloud-native challengers erode per-seat pricing power. Mid-market software vendors in India and Vietnam exhibit the highest price sensitivity, while Fortune 500 financial services in the United States and Germany accept premium pricing for EU AI Act-ready platforms.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes and container availability constraints elevate inbound logistics costs for GPU hardware sourced from Taiwan and South Korea. NVIDIA silicon fabrication concentrates supply exposure in East Asian foundries, while specialized testing infrastructure components draw from German precision engineering and Indian software development clusters. Single-source vulnerability in GPU compute creates structural risk for vendors training proprietary computer vision models. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with channel partners serving mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
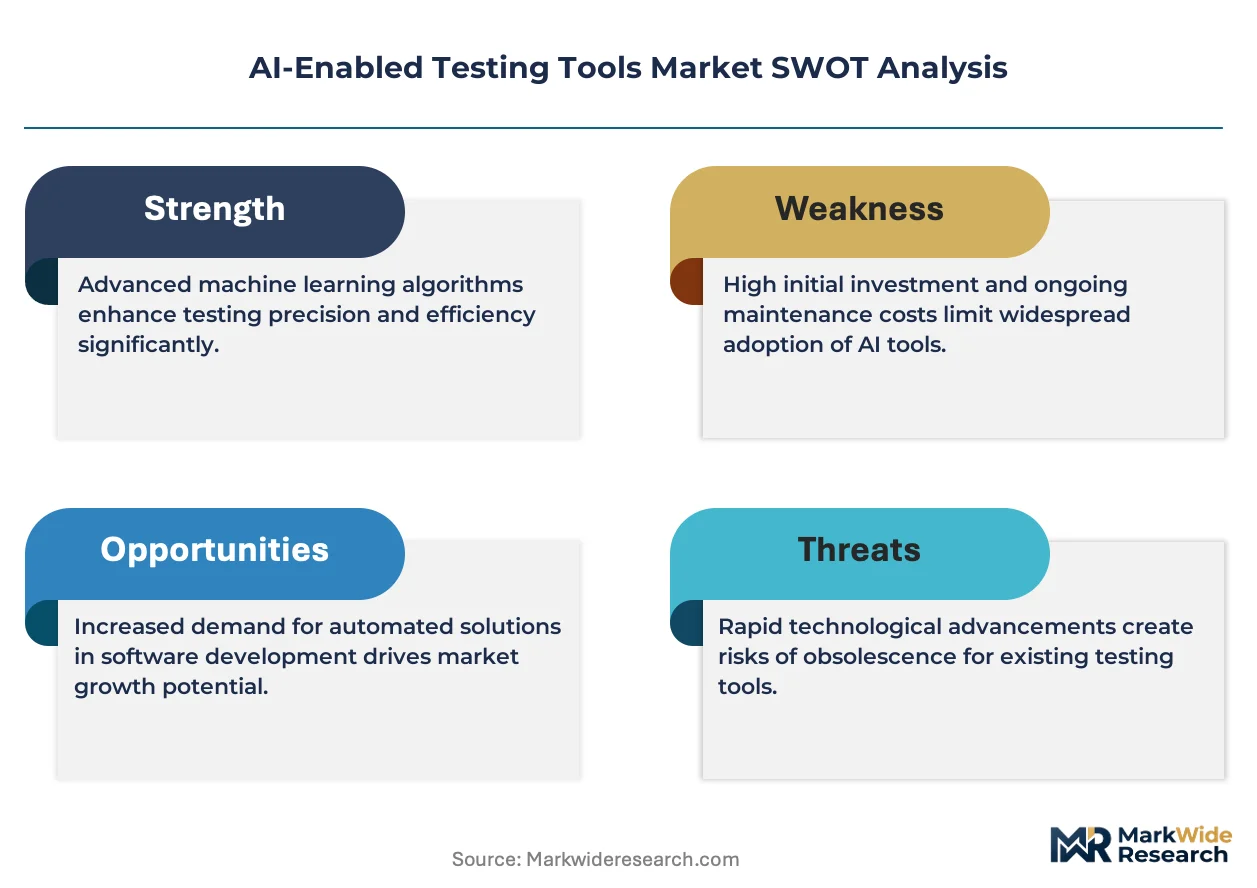
Open-source test automation frameworks and low-code AI platforms threaten incumbent pricing power, forcing established vendors to defend through compliance differentiation and integration depth that substitutes cannot replicate.
For Market Incumbents: Compound defensive moats by deepening explainable AI documentation pipelines that satisfy FDA software-as-medical-device guidance and EU AI Act transparency mandates. Acquire specialized security testing firms to close capability gaps against shift-left compliance demands. Vertical integration into synthetic test data generation preserves margin against GPU compute cost volatility. For New Entrants and Emerging Players: Natural language test specification capabilities represent the most penetrable service-layer gap, with incumbents under-serving business analyst personas who lack scripting expertise. Target mid-market SaaS companies in Austin and Berlin seeking unified quality platforms without enterprise compliance overhead. Pursue outcome-based pricing models that align commercial terms with defect-prevention ROI rather than seat-based subscriptions. For Investors and Strategic Acquirers: EU AI Act enforcement deadlines reshape the acquisition landscape toward vendors with pre-built conformity assessment infrastructure. Long-term viability centers on platforms serving regulated industries where compliance documentation creates switching costs. Target acquisition archetypes include model-based automation specialists with ISO 26262 automotive credentials. Monitor FDA guidance evolution on AI-enabled medical device software as the critical inflection signal for healthcare segment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies functional, security, and performance testing for DevOps toolchain consolidation in United States enterprise accounts. |
| Acquisition of Specialist Firm | Adds synthetic test data generation capabilities that address GDPR and CNIL privacy constraints for European financial services. |
| Geographic Expansion | Establishes delivery presence in Bangalore and Hyderabad to capture offshore software development demand. |
| Strategic Partnership | Integrates with hyperscaler CI/CD pipelines to embed autonomous testing within cloud-native development workflows. |
| Product Launch | Introduces self-healing test scripts using reinforcement learning to displace offshore manual regression teams. |
Methodological Framework
Cross-validation between executive interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Primary fieldwork encompassed CTOs, DevOps platform engineers, IT procurement officers, and quality assurance directors at financial services, healthcare IT, and automotive software organizations across the United States, Germany, and India. Secondary validation drew from FDA guidance documents, EU AI Act implementing texts, NIST AI risk management frameworks, SEC 10-K disclosures, and hyperscaler infrastructure investment reports. Bottom-up segment sizing and top-down macroeconomic triangulation ensured methodological consistency.
Sensitivity analysis across deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster dimensions structured the forecast framework. CAGRs derive from regression analysis of historical procurement patterns against projected DevOps velocity mandates and compliance deadline impacts. Model inputs incorporate GPU compute cost trajectories, enterprise software development headcount forecasts, and shift-left security adoption curves without specifying discrete time periods.
Forecasts assume regulatory continuity in EU AI Act implementation, FDA software-as-medical-device guidance, and NIST AI risk management frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Destructive Testing Market
Test and Measurement
Semiconductor Assembly and Testing Services Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Metrology Software Market
Test and Measurement
Handheld Digital Multimeter Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
High-Aspect-Ratio 3D NAND Metrology Equipment Market
Test and Measurement
Shock Data Logger Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Scratch Testers Market