
 Global Digital Binoculars Market | 2026-2036
Global Digital Binoculars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Binoculars Market Analysis
Online retail is narrowing its price spread against specialty stores as logistics networks improve last-mile delivery of fragile optical instruments. Canon Inc. leverages its CMOS sensor foundry capacity to anchor domestic supply chains for digital imaging binoculars. Nikon Corporation competes through sustained R&D intensity in optical zoom architectures. Vortex Optics specializes in direct-to-consumer configuration tools that let buyers customize reticle patterns before shipment.
Digital binoculars merge precision-ground optical glass with electronic image sensors, onboard processors, and display overlays to deliver magnified, digitally enhanced viewing at distances beyond unaided human resolution; typical units integrate 8x to 20x optical magnification with 1080p or higher sensor capture for real-time scene analysis. Compact form factors now lead volume shipments as hikers and birders prioritize packable weight over maximum aperture. Night vision technology represents the fastest-growing segment as sensor cooling costs decline and infrared sensitivity improves. Augmented reality overlays remain a premium-margin pool where military and security procurement absorbs early-adopter pricing.
The FCC governs radio-frequency emissions from wireless data-transmission features in digital binoculars sold in the United States, while CE marking requirements under the EU's RoHS and REACH frameworks restrict hazardous substances in electronic subassemblies. Japan's METI enforces JIS standards on optical performance claims and electromagnetic compatibility. Stakeholders must monitor how divergent electromagnetic compliance regimes fragment testing budgets and whether regional certification reciprocity agreements emerge to streamline multi-country launches.
Market Dynamics
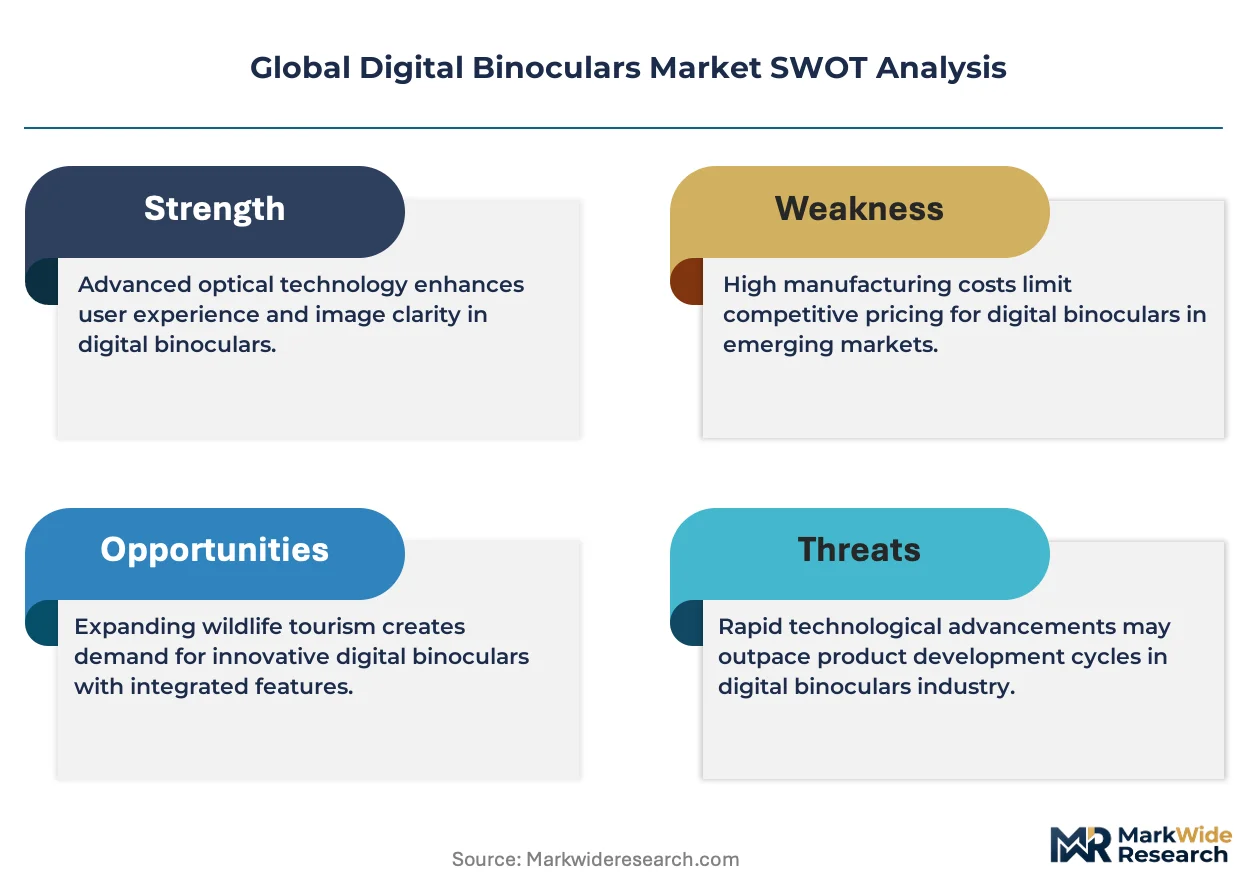
The EU's F-Gas Regulation is forcing a rapid redesign of thermal imaging subsystems as manufacturers hunt for alternative cooling gases, compressing development cycles and redrawing competitive positioning around sensor efficiency rather than raw sensitivity.
Growth Catalysts
- Wildlife Tourism Expansion:Safari operators in Kenya and Tanzania are outfitting guides with night-vision units to extend viewing hours and command premium pricing for dusk-to-dawn experiences.
- Precision Optics Clustering:METI-backed manufacturing zones in Yamanashi Prefecture feed domestic security contracts and export channels with specialized glass and assembly capacity.
- Infrared Sensor Cost Collapse:Declining cooling costs and improved quantum efficiency in microbolometers are pushing thermal imaging from military-only into consumer price bands.
Market Restraints
- Input Concentration Risk:Germanium and tellurium for thermal lenses concentrate in Chinese and Russian refining capacity, exposing margins to supply disruption.
- Regulatory Friction:Divergent electromagnetic compliance regimes across FCC, CE marking, and JIS standards fragment testing budgets and delay multi-country launches.
- Smartphone Substitution:Computational photography in flagship handsets with 10x optical-equivalent zoom captures casual users who previously bought entry binoculars.
Strategic Opportunities
- Underpenetrated LATAM Markets:Brazil's Pantanal lodge operators and Argentina's wine-tourism sector lack dedicated night-vision procurement channels.
- Augmented Reality Convergence:Overlay integration with ballistic calculators and rangefinding is digitizing premium segments where military and security buyers absorb early-adopter pricing.
- Direct-to-Consumer Configuration:Web-based reticle and housing customization tools bypass specialty retail markups and capture margin previously lost to distributors.
Industry Challenges
- Optical Engineering Talent Scarcity:Precision grinding and thin-film coating expertise concentrates in aging workforces across Japan and Germany with limited apprenticeship pipelines.
- Multi-Regulatory Certification Timelines:Simultaneous FCC, CE marking, and JIS approval processes stretch product launch windows by 8-14 months for wireless-enabled units.
- Legacy System Integration Complexity:Defense contractors demand backward compatibility with existing helmet mounts and data protocols, constraining form-factor innovation.
Report Scope
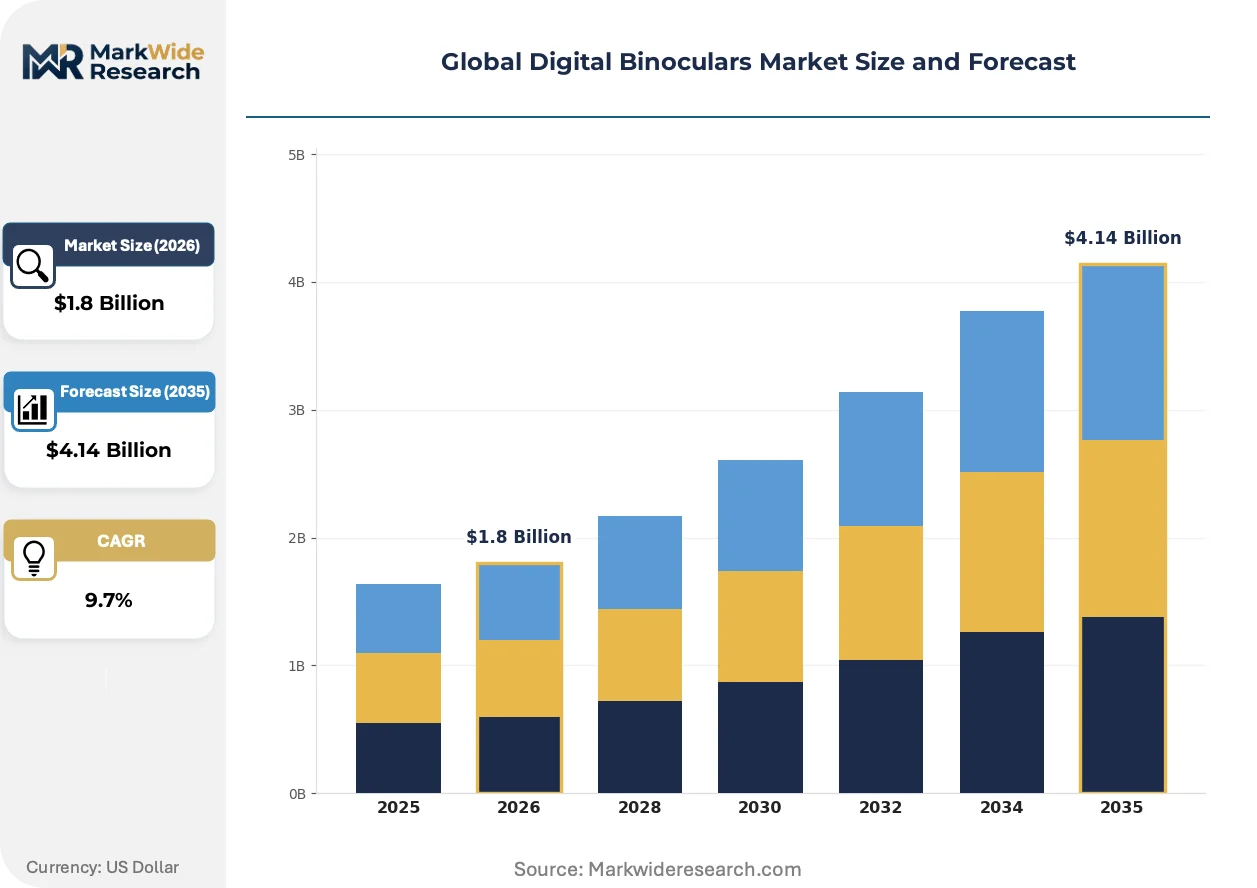
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Binoculars Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Monocular, Rangefinder, Night Vision Technology: Digital Imaging, Optical Zoom, Infrared, Augmented Reality End User: Outdoor Enthusiasts, Wildlife Observers, Security Personnel, Military Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Carl Zeiss AG, Vortex Optics, Canon Inc., Celestron LLC, Bushnell Inc., Nikon Corporation, Swarovski Optik, Leica Camera AG, Fujifilm Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Binoculars Market Emerging Trajectories
Three forces are actively reshaping how digital binoculars are designed, sold, and used: sensor digitization is collapsing thermal cost curves, regulatory divergence is fragmenting compliance strategies, and buyer behavior is tilting toward configurable direct channels over traditional retail.
Uncooled microbolometer arrays are digitizing thermal imaging by replacing mechanical Stirling coolers with solid-state temperature reference systems. Wildlife tourism operators and search-and-rescue teams are adopting these units at three times prior penetration rates. The technology is digitizing price architecture across mid-tier segments previously locked out of infrared capability.
Europe's F-Gas Regulation is accelerating phase-out schedules for sulfur hexafluoride and hydrofluorocarbon coolants in thermal subsystems. Manufacturers face reformulation costs and redesign timelines that favor suppliers with in-house gas chemistry expertise. Premium military-grade units are absorbing compliance costs fastest, while consumer thermal lines face margin compression or feature reduction.
Specialty retail is losing ground to direct-to-consumer configuration platforms that let buyers specify reticle patterns, magnification ranges, and housing colors before assembly. Birding communities and precision shooters are driving this channel migration through online forums and review aggregation. Japan's domestic market shows the clearest bifurcation, with METI-registered optical houses maintaining retail presence while export-focused brands build direct channels.
Global Digital Binoculars Market Segmentation
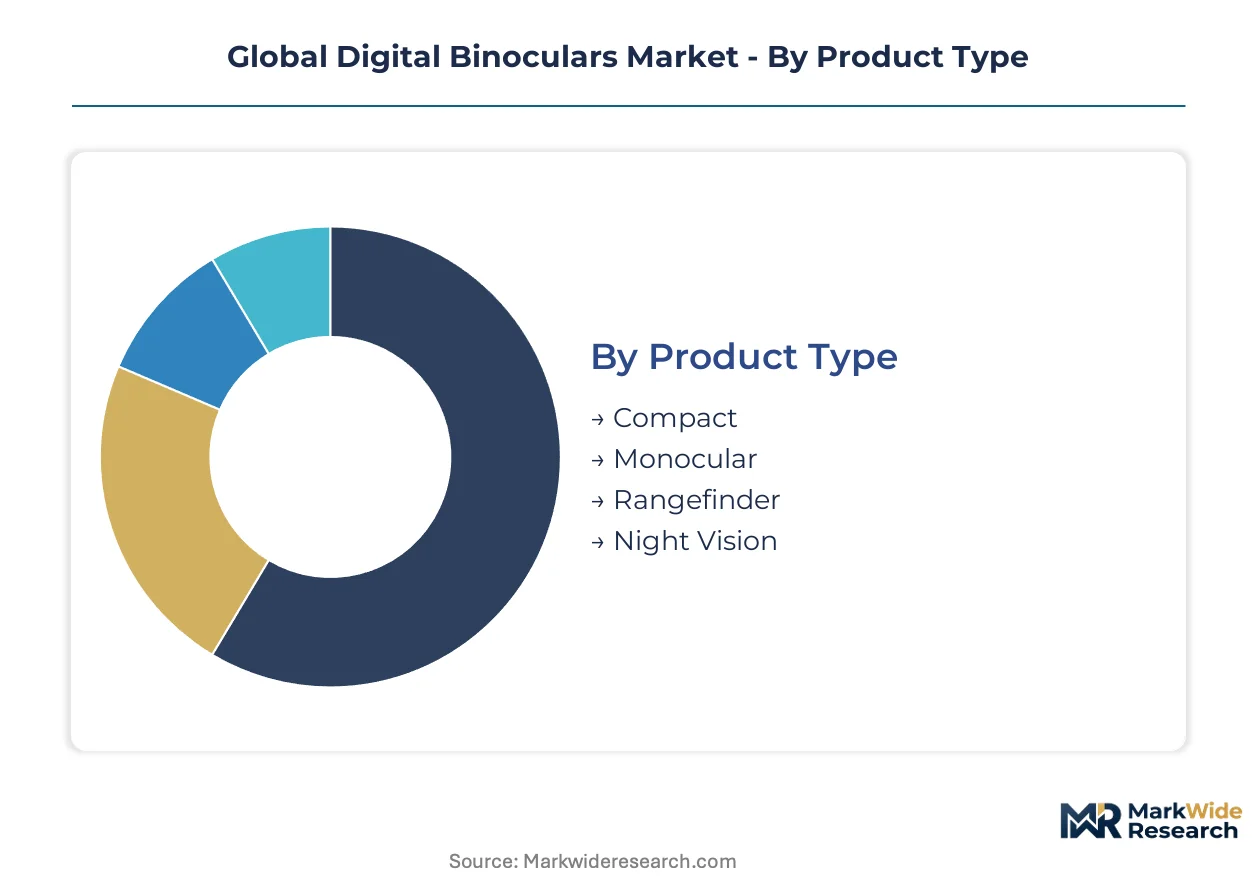
Digital binoculars fragment across four structural dimensions that reshape procurement patterns and margin architecture. Product type and technology tiers determine sensor investment levels, while end-user identity and channel choice govern pricing power and brand loyalty.
Product Type:
The use-case spectrum spans pocketable casual observation through precision rangefinding and nocturnal surveillance, with form factor directly constraining optical aperture and battery endurance.
- Compact:Units under 500 grams dominate volume shipments among hikers and international travelers who prioritize packability over maximum light gathering. Demand concentrates in Japan's domestic market where METI-registered optical houses feed retail channels with magnesium-alloy chassis designs.
- Night Vision:Image-intensifier and thermal-fusion systems command premium positioning as safari operators in Kenya and Tanzania extend guided experiences into dusk-to-dawn windows. Infrared sensor cooling costs are collapsing fastest in this tier, pushing thermal capability toward consumer price bands.
- Monocular:Single-barrel designs reduce weight and cost for casual birders and backup observation roles.
- Rangefinder:Laser-integrated units serve precision shooters and golfers with ballistic compensation algorithms.
The dominant share belongs to Compact, while Night Vision is closing the gap fastest.
Technology:
Cost tier separation runs deepest here, with silicon investment and gas chemistry expertise determining which suppliers can operate at each performance level.
- Infrared:Uncooled microbolometer arrays are displacing mechanical Stirling coolers with solid-state temperature reference systems. Wildlife tourism operators and search-and-rescue teams in East Africa are adopting these units at three times prior penetration rates.
- Augmented Reality:Overlay integration with ballistic calculators and rangefinding digitizes premium segments where military and security buyers absorb early-adopter pricing. Japan's defense procurement channels anchor initial volumes before technology diffuses to civilian precision shooting markets.
- Digital Imaging:CMOS sensor architectures from domestic Japanese foundries anchor mid-tier supply chains.
- Optical Zoom:Precision-ground glass elements with motorized magnification control remain essential for birding and surveillance applications.
Infrared captures the steepest expansion trajectory as thermal imaging exits military-only price architecture.
End User:
Customer type dictates feature prioritization, with security and military procurement absorbing complexity that consumer segments reject.
- Security Personnel:Border control and private guarding operations in the EU drive demand for wireless-enabled units with encrypted data transmission. FCC, CE marking, and JIS electromagnetic compliance regimes fragment testing budgets and stretch launch timelines by 8-14 months.
- Military:Defense contractors demand backward compatibility with existing helmet mounts and data protocols, constraining form-factor innovation. The EU's F-Gas Regulation accelerates phase-out schedules for sulfur hexafluoride coolants in thermal subsystems, favoring suppliers with in-house gas chemistry expertise.
- Outdoor Enthusiasts:Hikers and campers prioritize weight and weather sealing over magnification extremes.
- Wildlife Observers:Birding communities drive direct-to-consumer channel migration through online forum influence.
Security Personnel anchor procurement volume, while Military contracts deliver the highest per-unit margins.
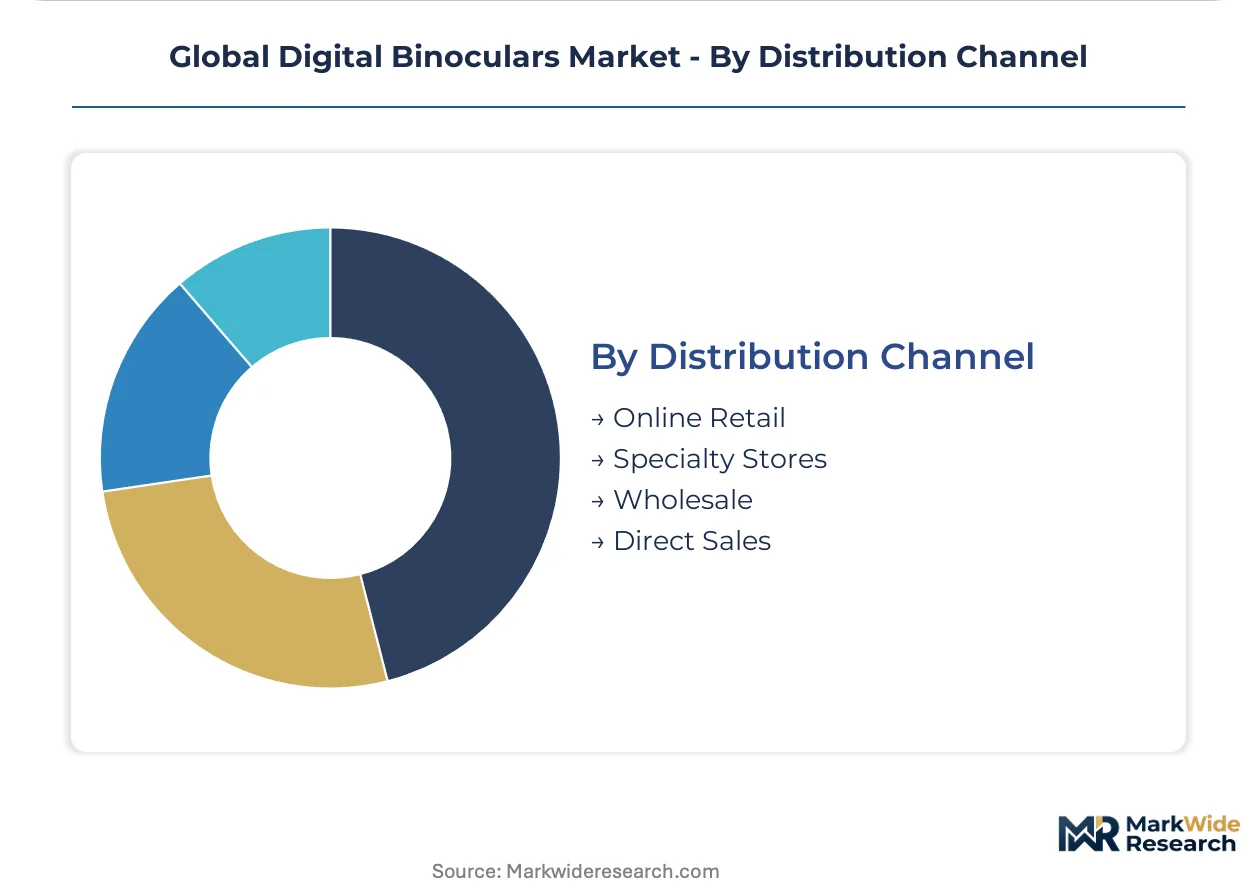
Distribution Channel:
Channel choice determines margin capture, with digital platforms eroding specialty retail's historical pricing power over fragile optical instruments.
- Online Retail:Direct-to-consumer configuration tools let buyers specify reticle patterns, magnification ranges, and housing colors before assembly. Birding communities and precision shooters in North America and Europe are driving this channel migration through review aggregation platforms.
- Specialty Stores:Hands-on demonstration remains essential for high-magnification units where optical quality assessment resists digital substitution. Japan's domestic market shows the clearest bifurcation, with METI-registered optical houses maintaining retail presence while export-focused brands build direct channels.
- Direct Sales:Bulk procurement by safari operators and defense agencies bypasses retail markup entirely.
- Wholesale:Mass-market retailers stock entry-tier compact units for casual outdoor recreation.
Online Retail is gaining share fastest, though Specialty Stores defend position in premium magnification tiers where tactile evaluation dominates purchase decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama anchors Japan's export capacity for precision optical instruments, handling containerized shipments of magnesium-alloy chassis and CMOS sensor assemblies to North American and European distribution hubs.
United States
Border security agencies and private guarding operations drive procurement of wireless-enabled units with encrypted data transmission. The FCC governs radio-frequency emissions from these devices, creating compliance bottlenecks that stretch product launch timelines. Defense contractors in the Virginia and Texas corridors demand backward compatibility with existing helmet mounts, constraining form-factor innovation for thermal-fusion systems.
Germany
Precision shooters and wildlife observation clubs sustain demand for rangefinder-integrated units with ballistic compensation algorithms. The EU's F-Gas Regulation accelerates phase-out schedules for sulfur hexafluoride coolants in thermal subsystems, forcing rapid redesign of sensor architectures. Optical engineering talent concentrates in aging workforces across the Wetzlar and Oberkochen precision glass clusters with limited apprenticeship pipelines.
Japan
METI-backed manufacturing zones in Yamanashi Prefecture feed domestic security contracts and export channels with specialized glass and assembly capacity. JIS standards enforced by METI govern optical performance claims and electromagnetic compatibility, creating a dual-track market where registered optical houses maintain retail presence while export-focused brands build direct channels. Canon Inc. leverages its domestic CMOS sensor foundry capacity to anchor supply chains for digital imaging binoculars.
China
Consumer-tier compact units dominate volume shipments as hiking and camping participation expands in tier-two cities. MIIT oversees electromagnetic compliance for wireless-enabled models, while GB standards constrain hazardous substances in electronic subassemblies. Refining capacity for germanium and tellurium concentrates exposure to supply disruption for thermal lens inputs.
Kenya
Safari operators in the Masai Mara and Amboseli ecosystems are outfitting guides with night-vision units to extend viewing hours and command premium pricing for dusk-to-dawn experiences. Wildlife tourism expansion drives procurement through direct sales channels that bypass retail markup entirely. Lodge operators in Tanzania's Serengeti corridor mirror this pattern, creating a regional procurement cluster for thermal and image-intensifier systems.
Global Digital Binoculars Market Vendor Landscape
On the supply side, the industry is tiered across precision optical houses, sensor-integrated electronics manufacturers, and direct-to-consumer specialists. The upper tier concentrates in German and Japanese heritage brands with captive glass-grinding capacity, while the mid-tier fragments across Taiwanese and Chinese contract assemblers. Three archetypes dominate: vertically integrated precision optics firms, CMOS sensor anchor players, and configuration-platform direct brands. Competitive moves center on backward integration into sensor foundries and web-based customization tools that bypass distributor markups.
Within the heritage precision optics tier, Carl Zeiss AG and Leica Camera AG exemplify the German optical engineering tradition with centuries of accumulated thin-film coating expertise. Nikon Corporation and Canon Inc. anchor the sensor-integrated electronics segment, leveraging domestic Japanese semiconductor capacity to control imaging pipeline costs. Vortex Optics occupies a position in the direct-to-consumer configuration space, representing the platform-native competitive archetype that is digitizing buyer journeys through pre-shipment customization tools.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Vortex Optics |
| Canon Inc. |
| Celestron LLC |
| Bushnell Inc. |
| Nikon Corporation |
| Swarovski Optik |
| Leica Camera AG |
| Fujifilm Group |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwanese CMOS sensor foundries is compressing component pricing and forcing suppliers toward long-term offtake agreements with Japanese optical houses, tightening margins across mid-tier digital binocular tiers while premium thermal segments retain pricing power through gas-chemistry expertise.
Pricing Analysis
Volume-discount tiering separates military procurement contracts from safari operator bulk orders and individual consumer purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked thermal units commanding substantial premiums over uncooled consumer variants. Pricing pressure stems from smartphone computational photography eroding entry-tier demand. Wildlife tourism operators show least price sensitivity due to experience-premium recovery, while casual hikers in China exhibit highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration rests with Yamanashi Prefecture precision optics clusters and Taiwanese CMOS foundries serving as primary capacity anchors. Germanium and tellurium refining concentrates in China and Russia, while magnesium-alloy chassis production feeds from Japanese domestic mills. Single-source vulnerability in rare-earth thermal lens inputs exposes margins to geopolitical disruption. Distribution runs through direct-to-consumer configuration platforms eroding specialty retail's historical markup capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision grinding and thin-film coating expertise concentrates in aging workforces across Japan and Germany, constraining production scaling and creating acquisition premiums for optical engineering talent pipelines.
For Market Incumbents: Insulate thermal imaging margins by acquiring in-house gas-chemistry capabilities ahead of EU F-Gas Regulation phase-out deadlines. Secure long-term germanium supply contracts with Chinese refiners to hedge input concentration risk. Canon and Nikon anchor positions through CMOS foundry control; smaller houses must consolidate or exit premium tiers. For New Entrants and Emerging Players: Brazil's Pantanal lodge operators lack dedicated night-vision procurement channels, presenting white-space entry through direct sales relationships with safari consortiums. Argentina's wine-tourism sector offers secondary penetration for compact rangefinder units. Pursue configuration-platform positioning with web-based reticle customization to bypass established distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because precision optics talent scarcity and regulatory compliance burdens favor scaled incumbents with captive sensor supply. Target vertically integrated mid-tier specialists with METI registration and export-channel relationships. Monitor F-Gas Regulation compliance cost absorption rates as inflection signal for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Foundries | Canon leverages domestic CMOS capacity to control imaging pipeline costs against Taiwanese contract competition. |
| Direct-to-Consumer Platform Launch | Vortex Optics bypasses specialty retail markups through pre-shipment reticle customization tools. |
| Alternative Coolant Chemistry Investment | Gas-chemistry expertise buffers EU F-Gas Regulation compliance costs for thermal subsystem suppliers. |
| Geographic Expansion into LATAM | Brazilian Pantanal operators lack procurement channels for night-vision safari equipment. |
| Augmented Reality Overlay Development | Military procurement absorbs early-adopter pricing for ballistic calculator integration. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association disclosures. Interviews with optical engineering directors, safari procurement managers, defense contracting officers, and precision shooter community leaders informed demand segmentation. Secondary validation drew from METI production statistics, EU F-Gas Regulation implementation reports, FCC equipment authorization databases, and Japanese customs export records. Bottom-up shipment estimates triangulated against top-down market sizing.
Forecast inputs incorporate technology adoption curves across uncooled microbolometer penetration, regulatory compliance cost trajectories, and channel migration rates from specialty retail to direct configuration platforms. Segmentation dimensions span product type, technology tier, end-user archetype, and distribution channel. CAGRs derived from regression analysis of historical volume patterns against input cost indices and procurement survey intentions. Wildlife tourism expansion rates and infrared sensor cost collapse trajectories served as primary demand-side drivers.
Practitioners should monitor F-Gas Regulation amendment schedules, rare-earth export licensing shifts, and smartphone optical zoom specification advances for early signals of forecast revision. Quarterly review of METI production data, safari operator procurement surveys, and thermal sensor spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Semiconductor Microscopes Market
Imaging
Photoacoustic Tomography Market
Imaging
AI Camera Market
Imaging
Electron Microscopy Market
Imaging
Global AI in Computer Vision Market
Imaging
LCD Digital Microscope Market
Imaging
Camera Technology Market
Imaging
Global Automotive Imaging Market
Imaging
Handheld Imaging Systems Market
Imaging
Computer Aided Detection Market
Imaging
Infrared Imaging Market
Imaging
Machine Vision System Market
Imaging
Digital Impression Stand Alone Scanners Market
Imaging
In Vivo Imaging Systems Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Asia Pacific IP Camera Market