
 Digital Microscope Market | 2026-2036
Digital Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Microscope Market Analysis
Japanese precision optics producers is repositioning toward high-resolution digital imaging modules for semiconductor failure analysis. Carl Zeiss AG leverages its century-old optical heritage to dominate premium benchtop systems for materials research. Keyence Corporation competes through vertical integration, controlling sensor design, software algorithms, and direct sales channels across Asia-Pacific industrial markets.
A digital microscope integrates optical lenses with CMOS or CCD sensors, converting magnified images into digital signals processed through dedicated software for real-time display, measurement, and documentation at resolutions exceeding 4K. Benchtop configurations anchor revenue in healthcare institutions and research laboratories where stability and multi-modal imaging justify capital investment, while handheld and USB variants extend into educational institutes and field-based electronics troubleshooting where portability overrides optical performance. Software integration and 3D imaging capabilities command margin premiums as end users demand automated particle analysis, depth compositing, and AI-assisted defect classification embedded within unified workflows.
FDA 21 CFR Part 820 quality system regulations govern digital microscopes deployed in US diagnostic and surgical settings, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for devices claiming medical purposes. RoHS and REACH compliance shapes component sourcing and export eligibility for manufacturers serving European industrial manufacturers. Stakeholders must monitor convergence between ISO 10993 biocompatibility standards and emerging software validation protocols as regulatory scope expands from hardware safety to algorithmic diagnostic reliability.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are driving demand for sub-micron resolution systems capable of detecting 7nm process defects, compressing replacement cycles from five years to three across failure analysis laboratories.
Growth Catalysts
- EU MDR compliance deadlines:Medical device manufacturers across Germany and France are upgrading to validated digital imaging systems for surgical documentation and pathology workflows ahead of 2026 recertification requirements.
- CMOS sensor cost curves:Wafer-scale fabrication advances have reduced high-resolution sensor procurement costs, enabling mid-tier manufacturers to offer 4K-class benchtop systems previously restricted to premium vendors.
- China's dual carbon goals:MIIT mandates for energy-efficient manufacturing equipment are accelerating replacement of legacy halogen-illuminated microscopes with LED-based digital systems in Shenzhen and Suzhou electronics clusters.
Market Restraints
- Precision glass supply concentration:German and Japanese specialty optics producers control 80% of apochromatic objective lens supply, exposing downstream manufacturers to lead time volatility exceeding 16 weeks.
- REACH substance restrictions:ECHA classifications on optical coating chemistries are forcing reformulation of immersion oil and anti-reflective treatments, extending R&D timelines by 8-12 months.
- Smartphone macro photography substitution:Field technicians in consumer electronics repair are deploying 200MP mobile camera modules with clip-on lenses for sub-$50 inspection tasks previously requiring dedicated USB microscopes.
Strategic Opportunities
- India's PLI scheme for semiconductor packaging:Gujarat and Tamil Nadu substrate fabrication investments are creating first-mover demand for automated optical inspection microscopes in back-end test facilities.
- AI-assisted defect classification:Convergence of convolutional neural networks with edge-computing image processors is enabling real-time anomaly detection without cloud connectivity, opening defense and aerospace applications.
- Direct-to-laboratory distribution:Manufacturers are bypassing regional distributors to sell configured systems through specialized e-procurement platforms serving university research consortia.
Industry Challenges
- ISO 17025 calibration technician scarcity:Accredited metrology laboratories face 14-month hiring timelines for specialists capable of certifying measurement traceability chains for semiconductor clients.
- FDA 21 CFR Part 820 software validation:Embedded image analysis algorithms require documented verification protocols that extend product development cycles by 9-15 months for diagnostic applications.
- Multi-modal integration complexity:End users demand seamless workflow unification between digital microscopes, Raman spectrometers, and electron microscopes, straining vendor software architecture teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Microscope Market |
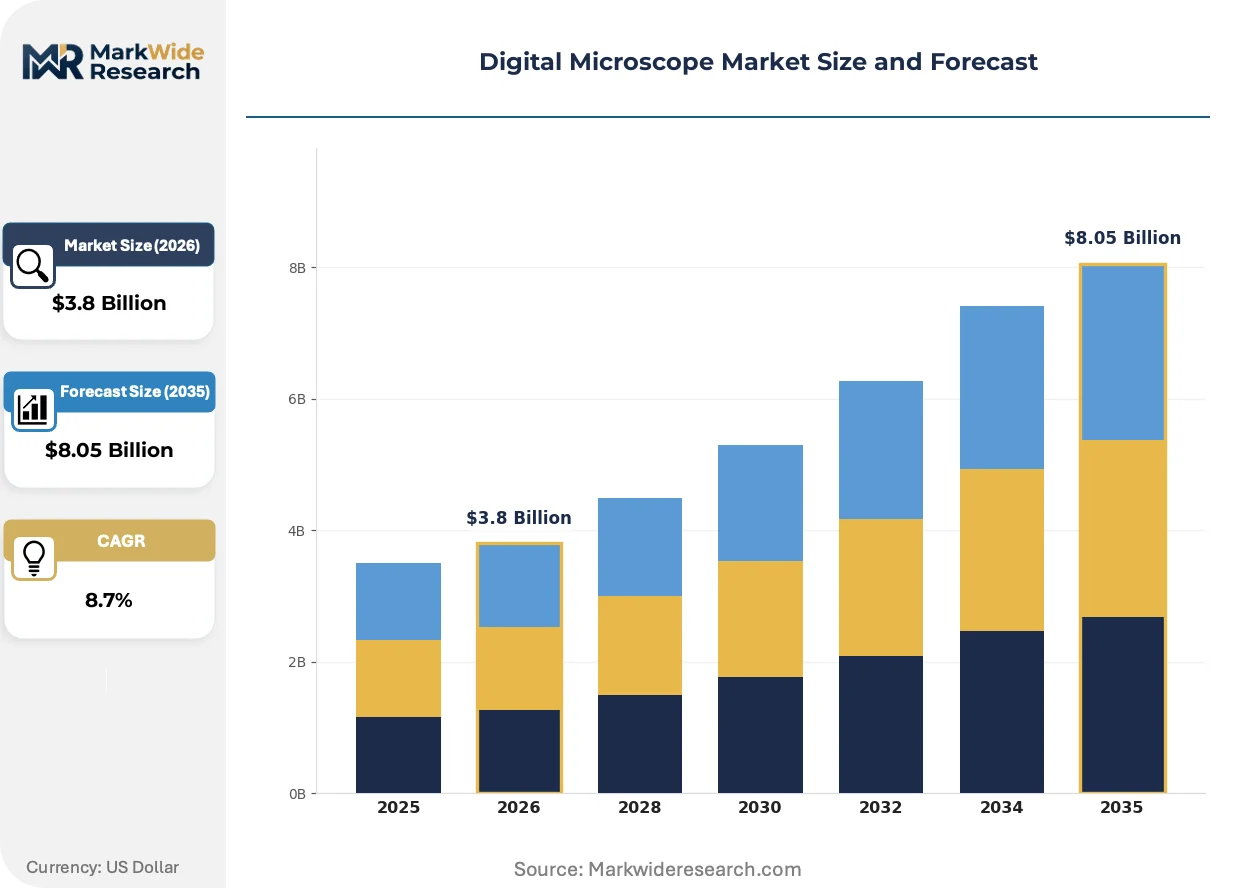
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Handheld, USB, Integrated Application: Biology, Material Science, Electronics, Education End User: Healthcare Institutions, Research Laboratories, Educational Institutes, Industrial Manufacturers Technology: Optical, Digital Image Processing, Software Integration, 3D Imaging |
| Companies Covered | Leica Microsystems, Hirox Co. Ltd, Keyence Corporation, Vision Engineering Ltd., Thermo Fisher Scientific, Carl Zeiss AG, Nikon Instruments, Motic Instruments, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Microscope Market Emerging Trajectories
Computational imaging and edge-native processing are compressing the performance gap between benchtop systems and portable devices, redistributing value capture across hardware and software layers.
Deep learning-based autofocus and depth-from-focus reconstruction is automating routine inspection tasks in pharmaceutical quality control laboratories. Contract manufacturers in Ireland and Singapore are deploying these systems for 24-hour batch release testing. The technology is automating technician workload reduction of 40% while compressing documentation error rates.
China's GB standards for electronic test equipment are mandating electromagnetic compatibility certification for all imaging systems deployed in automotive battery inspection lines. MIIT enforcement inspections in Q4 2024 disqualified 23% of imported systems for inadequate shielding documentation. Korean and German exporters are redesigning power supply architectures to satisfy these requirements ahead of 2025 implementation.
Research consortia are consolidating procurement through shared-service microscopy cores rather than individual laboratory purchases. The Max Planck Society in Germany and CNRS facilities in France have shifted to multi-year service contracts bundling equipment, maintenance, and cloud storage. This model concentrates buying power with 6-8 institutional purchasers per country, pressuring mid-tier vendors to accept performance-based payment terms.
Digital Microscope Market Segmentation
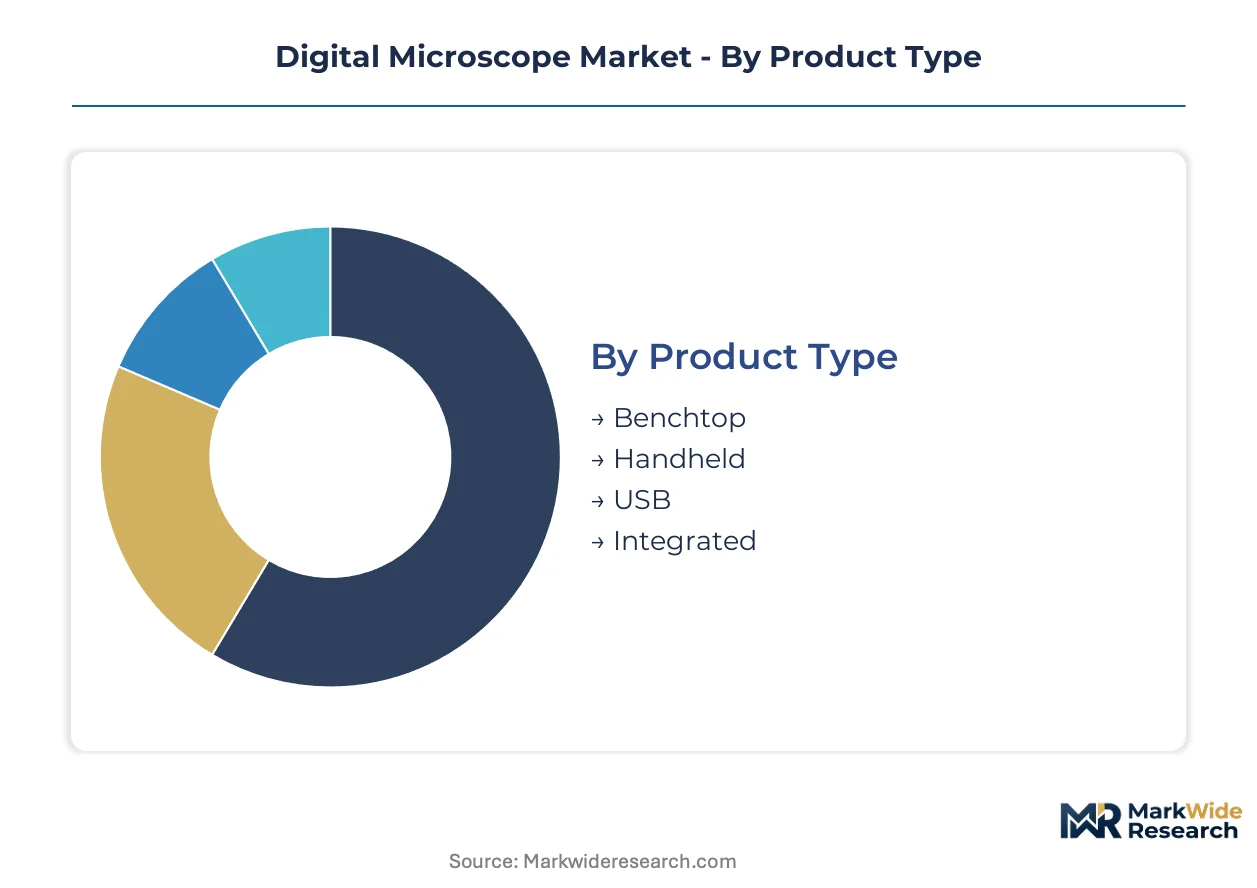
Segmentation in the digital microscope market reveals divergent capital requirements and margin structures across hardware configurations, end-use applications, and technology layers. Procurement patterns vary sharply between institutions prioritizing optical performance and those optimizing for portability or software automation.
Product Type:
Capital intensity peaks in benchtop configurations where stabilized optical benches, apochromatic objective arrays, and multi-modal illumination systems drive per-unit investments past $50,000. Handheld and USB variants operate on asset-light manufacturing models with substantially lower tooling and calibration infrastructure.
- Benchtop:Anchored by precision-machined granite bases and motorized XYZ stages delivering sub-micron positional repeatability. Healthcare institutions in Germany and Japan dominate procurement for surgical documentation and pathology workflows where FDA 21 CFR Part 820 and EU MDR compliance justify premium expenditure.
- Handheld:Battery-powered units with CMOS sensors and LED ring illumination prioritize field portability over resolution. Electronics repair technicians in Shenzhen and Seoul deploy these for on-site failure analysis where bench access is impractical.
- USB:Compact sensor modules connecting to host computers via standard interfaces. Educational institutes in India and Brazil favor these for introductory microscopy curricula where cost constraints override optical sophistication.
- Integrated:Purpose-built systems embedding digital imaging within automated inspection lines. Semiconductor packaging facilities in Taiwan and South Korea specify these for back-end defect detection with direct MES integration.
Most installed capacity flows through benchtop systems. Expansion is steepest in integrated configurations.
Application:
Application segmentation tracks divergent resolution requirements and regulatory exposure across scientific disciplines. Biology and electronics applications command the highest specification thresholds.
- Biology:Fluorescence-capable systems with cooled CCD sensors and software deconvolution for cellular imaging. Research laboratories at Max Planck Society facilities and CNRS institutes concentrate demand for multi-channel acquisition and automated stage mapping.
- Material Science:Polarized light and differential interference contrast configurations for metallurgical analysis. Industrial manufacturers in Germany's Ruhr Valley and Japan's Nagoya region deploy these for quality control in automotive component production.
- Electronics:Sub-micron resolution systems for PCB inspection and semiconductor failure analysis. Taiwan Semiconductor Manufacturing Company and Samsung Foundry drive specifications for 7nm node defect detection.
- Education:Simplified optics with robust mechanical construction for classroom durability. Secondary schools across India's state education boards and Brazil's federal technical institutes represent volume demand.
Biology applications anchor premium revenue pools. Electronics inspection is gaining share fastest as process nodes shrink.
End User:
End user segmentation reflects procurement authority structures and total cost of ownership calculations. Healthcare and research institutions prioritize measurement traceability and service contracts.
- Healthcare Institutions:Hospitals and diagnostic chains requiring FDA-cleared or CE-marked systems for clinical use. Germany's university medical centers and Japan's prefectural hospitals lead replacement cycles ahead of EU MDR recertification deadlines.
- Research Laboratories:National research councils and corporate R&D centers demanding modular upgrade paths. France's CNRS and South Korea's KRISS facilities specify open software architectures for custom algorithm integration.
- Educational Institutes:Secondary schools and undergraduate programs with budget-constrained, high-volume procurement. India's NCERT-affiliated institutions and Brazil's SENAI technical network drive USB and entry-level benchtop demand.
- Industrial Manufacturers:Electronics, automotive, and pharmaceutical producers integrating microscopy within quality systems. Contract manufacturers in Ireland and Singapore automate batch release testing with AI-assisted defect classification.
Healthcare institutions concentrate premium purchasing power. Industrial manufacturers are expanding deployment most aggressively.
Technology:
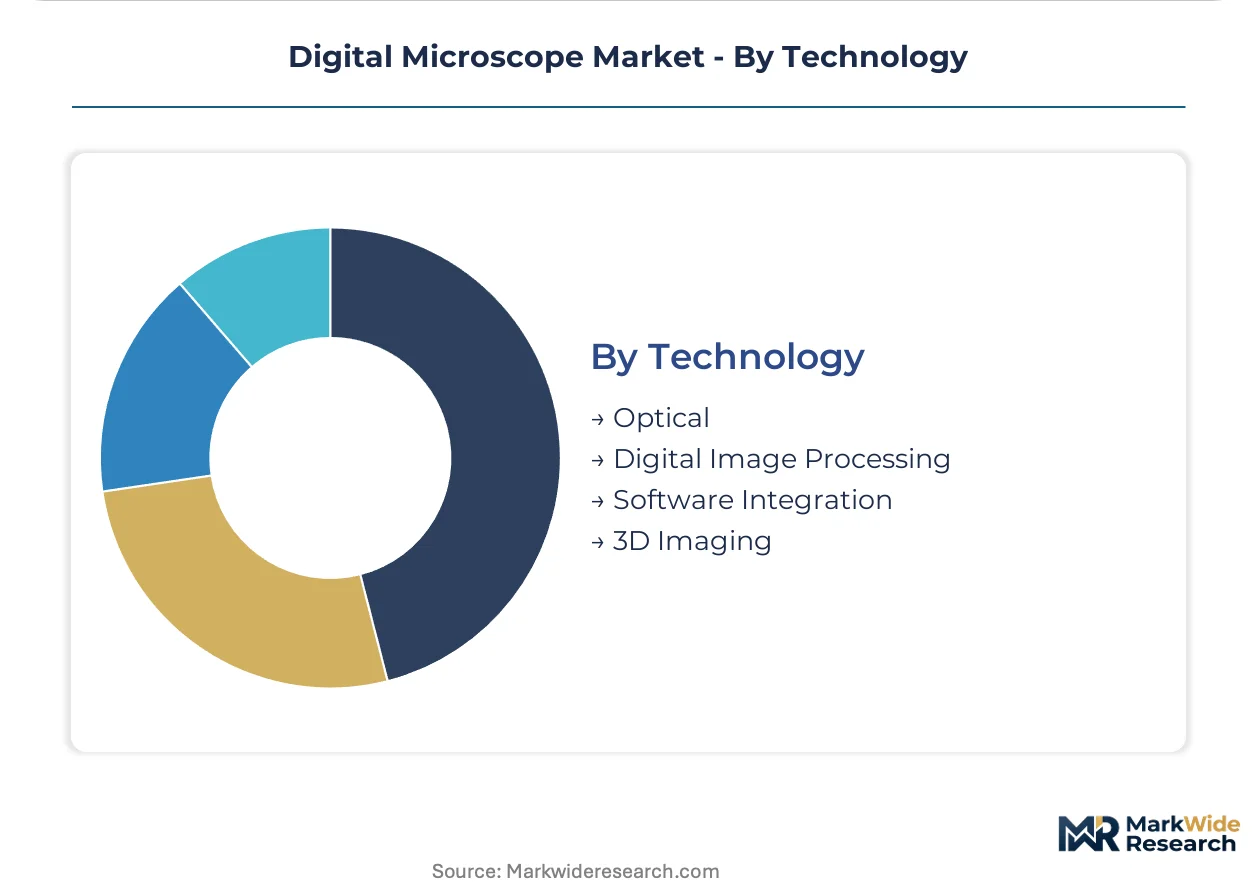
Technology segmentation separates mature optical foundations from emerging software and computational layers where vendor differentiation intensifies.
- Optical:Conventional lens systems with apochromatic correction and Köhler illumination. German and Japanese specialty glass producers control objective supply chains with 16-week lead times.
- Digital Image Processing:CMOS and CCD sensor integration with FPGA-based real-time processing. Taiwan sensor foundries and Korean image processor designers enable cost reduction curves.
- Software Integration:Unified platforms combining acquisition, measurement, and documentation with LIMS connectivity. Pharmaceutical quality control laboratories in Ireland and Singapore prioritize 21 CFR Part 11 compliant audit trails.
- 3D Imaging:Depth-from-focus reconstruction and structured illumination for volumetric analysis. Semiconductor failure analysis labs in South Korea and the US deploy these for package substrate inspection.
Optical technology retains the largest installed base. 3D imaging is climbing the fastest as depth compositing replaces destructive cross-sectioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting digital microscope assembly toward jurisdictions with streamlined electromagnetic compliance and lower certification costs. Manufacturers are relocating final integration to Southeast Asian facilities while retaining optical component sourcing from German and Japanese specialty glass producers.
United States
Semiconductor failure analysis laboratories in Arizona and Texas are driving demand for sub-micron resolution systems as domestic chip fabrication expands. FDA 21 CFR Part 820 enforcement is tightening software validation requirements for diagnostic imaging deployments. Boston's medical device cluster concentrates procurement for surgical documentation systems ahead of EU MDR recertification deadlines.
Germany
Precision optics manufacturers in Wetzlar and Jena are scaling apochromatic objective production for semiconductor inspection applications. EU MDR compliance deadlines are accelerating hospital procurement of validated imaging systems across Bavaria and North Rhine-Westphalia. The Ruhr Valley automotive component sector is automating quality control workflows with polarized light configurations.
China
MIIT mandates for energy-efficient manufacturing equipment are displacing legacy halogen-illuminated systems in Shenzhen and Suzhou electronics clusters. GB standards for electronic test equipment now require electromagnetic compatibility certification for automotive battery inspection deployments. Yangtze River Delta substrate fabrication investments are creating demand for automated optical inspection microscopes in back-end test facilities.
Japan
PMDA oversight of diagnostic device software is extending product development cycles for clinical imaging systems. Nagoya's automotive component manufacturers are deploying material science configurations for metallurgical analysis. Tokyo-area research consortia are consolidating procurement through shared-service microscopy cores with multi-year service contracts.
South Korea
Samsung Foundry and SK Hynix are compressing replacement cycles to three years for failure analysis laboratories detecting 7nm process defects. MFDS regulations on medical device clinical evidence are shaping export documentation requirements. Busan-Ulsan semiconductor packaging facilities are specifying integrated systems with direct MES integration for back-end defect detection.
Digital Microscope Market Vendor Landscape
German and Japanese producers anchor the premium optical tier; Taiwanese and Korean specialists hold sensor integration and image processing capabilities. Market structure concentrates around heritage optics houses with century-old glass formulations and vertically integrated industrial automation conglomerates controlling direct sales channels. Three archetypes dominate: precision optics heritage brands, industrial automation platform vendors, and contract manufacturing specialists serving educational price points. Competitive moves center on backward integration into CMOS sensor design and geographic expansion through specialized e-procurement platforms serving university research consortia.
Within the heritage optics tier, Leica Microsystems and Carl Zeiss AG exemplify manufacturers leveraging apochromatic lens expertise developed over multiple decades. Keyence Corporation occupies a distinct position as a vertically integrated industrial automation vendor controlling sensor design, software algorithms, and direct distribution across Asia-Pacific markets. These three anchors illustrate divergent pathways for value capture—optical heritage versus platform integration versus channel control.
| Leading Market Players |
|---|
| Leica Microsystems |
| Hirox Co. Ltd |
| Keyence Corporation |
| Vision Engineering Ltd. |
| Thermo Fisher Scientific |
| Carl Zeiss AG |
| Nikon Instruments |
| Motic Instruments |
| Olympus Corporation |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and MIIT mandates for energy-efficient manufacturing equipment gate qualified supply access and premium-tier pricing power, as LED-based digital systems with documented compliance command margin premiums while legacy halogen-illuminated inventory faces accelerated obsolescence.
Pricing Analysis
Distributor margins of 25-35% separate premium benchtop configurations from direct-to-OEM channels serving semiconductor fabs. Pricing stratifies across FDA-cleared diagnostic tiers, apochromatic objective grades, and software validation levels. Cost compression in USB and educational segments is intensifying as smartphone macro photography substitutes erode entry-level demand. Contract manufacturers exhibit highest price sensitivity; research consortia with multi-year service contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty glass producers controlling apochromatic objective lens supply. Optical component fabrication concentrates in Germany, Japan, and Taiwan. CMOS sensor procurement draws from Korean and Taiwanese foundries. Tariff exposure on precision optics strains downstream manufacturers. Distribution runs through specialized e-procurement platforms serving university research consortia alongside traditional industrial automation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
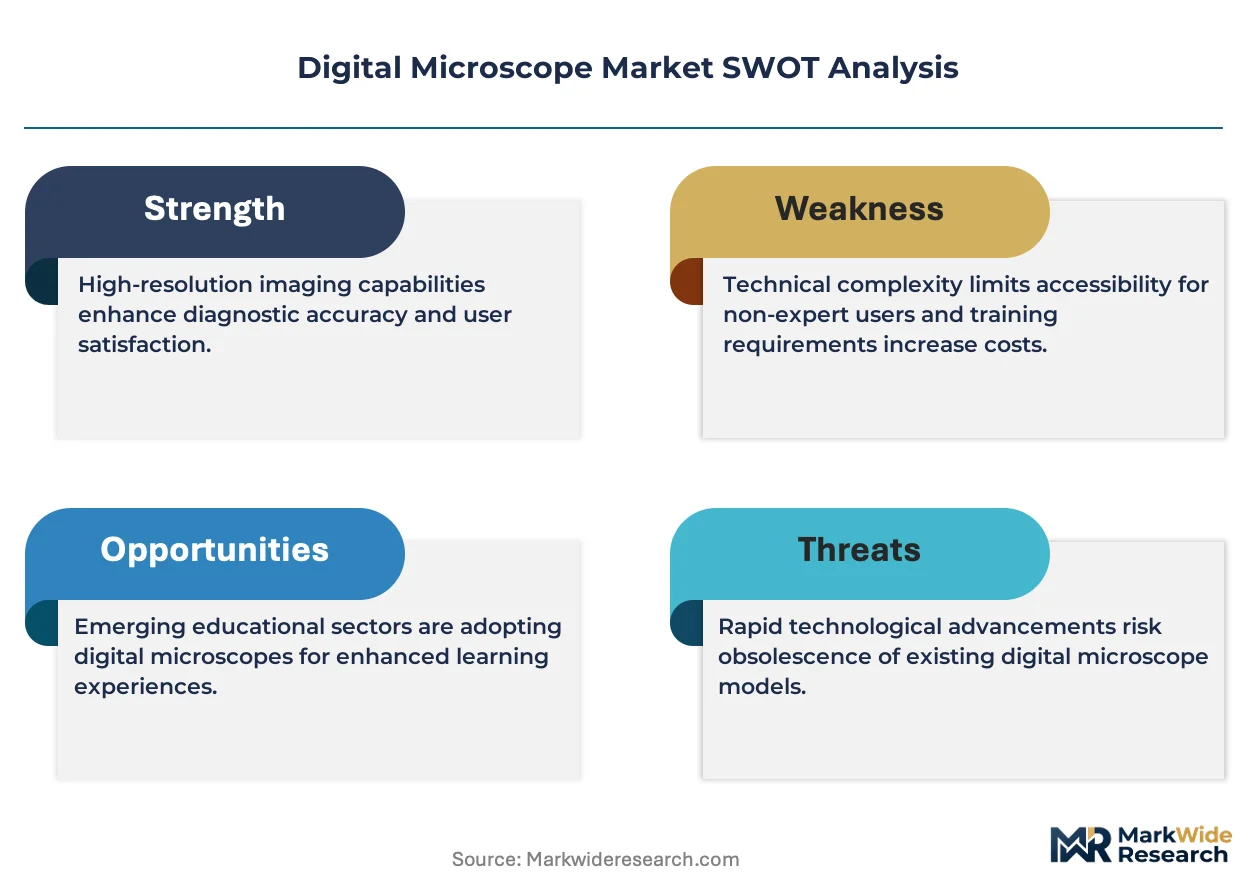
This market reads as a late-cycle quality story, with semiconductor failure analysis laboratories and EU MDR compliance deadlines shifting procurement toward validated premium specifications that justify capital expenditure.
For Market Incumbents: Extend software validation investments to compress FDA 21 CFR Part 820 development cycles against emerging AI-native competitors. Deepen backward integration into CMOS sensor design to offset precision glass supply concentration. Capture channel control through direct-to-laboratory e-procurement platforms serving consolidated research consortia. For New Entrants and Emerging Players: India's PLI scheme for semiconductor packaging creates first-mover demand for automated optical inspection microscopes in Gujarat and Tamil Nadu back-end facilities. Target educational institutes in Brazil and India with asset-light USB configurations. Deploy specialized e-procurement partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier sensor integrators lacking optical heritage but holding image processing capabilities. Five-to-ten year viability hinges on software differentiation and regulatory certification depth. Watch AI-assisted defect classification adoption rates in pharmaceutical quality control as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CMOS Sensor Design | Taiwanese foundry partnerships reduce procurement cost curves for mid-tier benchtop systems. |
| Software Validation Investment | FDA 21 CFR Part 820 compliance compresses development timelines for diagnostic imaging deployments. |
| Direct-to-Laboratory E-Procurement Launch | Max Planck Society and CNRS shared-service cores concentrate buying power with institutional purchasers. |
| AI-Assisted Defect Classification Development | Convolutional neural network integration enables real-time anomaly detection for defense aerospace applications. |
| Electromagnetic Compatibility Certification | MIIT GB standards compliance qualifies systems for automotive battery inspection lines in Yangtze River Delta. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with failure analysis laboratory directors, biomedical engineers at German university medical centers, semiconductor packaging procurement leads, and precision optics R&D directors with secondary validation against FDA 510(k) filings, EU MDR technical documentation, MIIT GB standard enforcement records, and customs trade data on optical component flows.
Historical trendline analysis across installed base replacement cycles and capital expenditure patterns informs projection mechanics. Segmentation dimensions span product configuration, application resolution requirements, end-user procurement authority, and technology layer maturity. CAGRs derive from curve-fitting against semiconductor node shrinkage timelines and regulatory compliance deadline clustering. Forecast inputs incorporate CMOS sensor cost trajectories and apochromatic objective lead time volatility.
Underlying measurement precision varies by segment; benchtop healthcare and semiconductor applications carry tighter precision than educational USB configurations given documented procurement data availability. Forecasts reflect assumptions on EU MDR enforcement consistency and China's dual carbon implementation pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Mobile Camera Module Market
Imaging
Digital Camera Market
Imaging
Global 3D Imaging Market
Imaging
Global 4K Camera Market
Imaging
X-Ray Market
Imaging
Facial Recognition Machine Market
Imaging
Hybrid Imaging Market
Imaging
Global CBCT/Cone Beam Imaging Market
Imaging
Frame Grabber Market
Imaging
Hyperspectral Imaging Market
Imaging
Photoacoustic Tomography Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Global Label-Free Array Systems Market
Imaging
Macroscopic Imaging Systems Market
Imaging
US Near Infrared Imaging Market