
 Global Digital Photography Market | 2026-2036
Global Digital Photography Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Photography Market Analysis
Camera-lens bundling is hardening as the default purchasing pattern for enthusiast and professional segments, with manufacturers locking body-and-lens combinations into tiered kit configurations. Canon Inc. leverages its RF mount ecosystem to lock buyers into proprietary lens lineups. Sony Corporation anchors its Alpha series through aggressive sensor technology leadership across full-frame and APS-C formats. Nikon Corporation competes by extending its Z-mount roadmap with specialized optics for wildlife and sports photography.
Global Digital Photography encompasses image capture, processing, and output systems utilizing electronic sensors—primarily CMOS architectures with photosite densities exceeding 40 megapixels—to convert optical signals into digital files for commercial, artistic, and documentary purposes. Mirrorless device types are displacing DSLR volumes as mechanical shutter assemblies give way to stacked-CMOS readout electronics, while smartphone integration as a device type now dominates casual-user image capture through multi-array computational sensors. Professional photographers within the end-user segmentation command premium pricing and sustain aftermarket lens and lighting accessory ecosystems that carry margins above hardware bodies.
Japan's METI oversees domestic precision equipment standards that constrain export-bound manufacturing tolerances for imaging sensors, while the EU RoHS and REACH frameworks restrict hazardous substance deployment in European-market camera electronics and battery assemblies. China's GB standards and MIIT directives mandate electromagnetic compatibility certification for imported digital imaging equipment entering domestic retail channels. Stakeholders must monitor how computational photography patents and cross-border semiconductor equipment controls reshape component sourcing strategies and regional manufacturing footprints.
Market Dynamics
Computational photography algorithms embedded in smartphones are absorbing casual consumer demand that previously flowed to dedicated compact cameras, forcing manufacturers to retreat upmarket toward enthusiast and professional segments where sensor size and optical performance still command premium positioning.
Growth Catalysts
- Mirrorless sensor architectures:Wedding and event studios are upgrading to full-frame mirrorless bodies as client expectations for low-light performance and resolution climb. Stacked-CMOS readout electronics enable silent shooting and high-speed capture that DSLRs cannot match.
- China's domestic supply chain dominance:Volume manufacturing for CMOS sensors and lens assemblies concentrates in Chinese production clusters, reducing component costs for global camera assembly. MIIT directives on electromagnetic compatibility certification streamline domestic retail channel entry for compliant equipment.
- REACH and RoHS frameworks:EU hazardous substance restrictions on camera electronics and battery assemblies are accelerating design-for-recyclability investments. Manufacturers achieving compliance early capture preferential placement in European retail channels.
Market Restraints
- Silicon wafer supply concentration:Advanced CMOS sensor fabrication depends on semiconductor equipment subject to cross-border export controls, constraining capacity expansion for high-megapixel arrays.
- Smartphone substitution:Multi-array computational sensors in flagship smartphones deliver portrait-mode and night-mode outputs that satisfy casual users, collapsing the entry-level compact camera segment.
- Japan METI precision standards:Domestic tolerance requirements for export-bound imaging sensors add certification overhead that extends product development cycles for manufacturers targeting Japanese market entry.
Strategic Opportunities
- India's underpenetrated professional segment:Wedding photography demand in tier-2 Indian cities outpaces local rental infrastructure, creating openings for equipment leasing platforms and certified pre-owned marketplaces.
- Computational-optical convergence:Hybrid systems combining smartphone connectivity with dedicated camera sensors enable real-time cloud editing workflows. Content creators on platforms like YouTube and Instagram are adopting these bridge devices for speed-to-publish.
- EU Green Deal circularity incentives:Battery replacement programs and modular repairable designs qualify for sustainability-linked procurement preferences in European public-sector and corporate event contracts.
Industry Challenges
- Specialized technician scarcity:Mirrorless camera repair requires expertise in stacked-CMOS calibration and firmware-level diagnostics that traditional DSLR service networks lack, extending turnaround times for warranty claims.
- Legacy mount compatibility:Photographers with extensive DSLR lens collections face expensive adapter purchases or full-system replacement when transitioning to mirrorless platforms, slowing upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Photography Market |
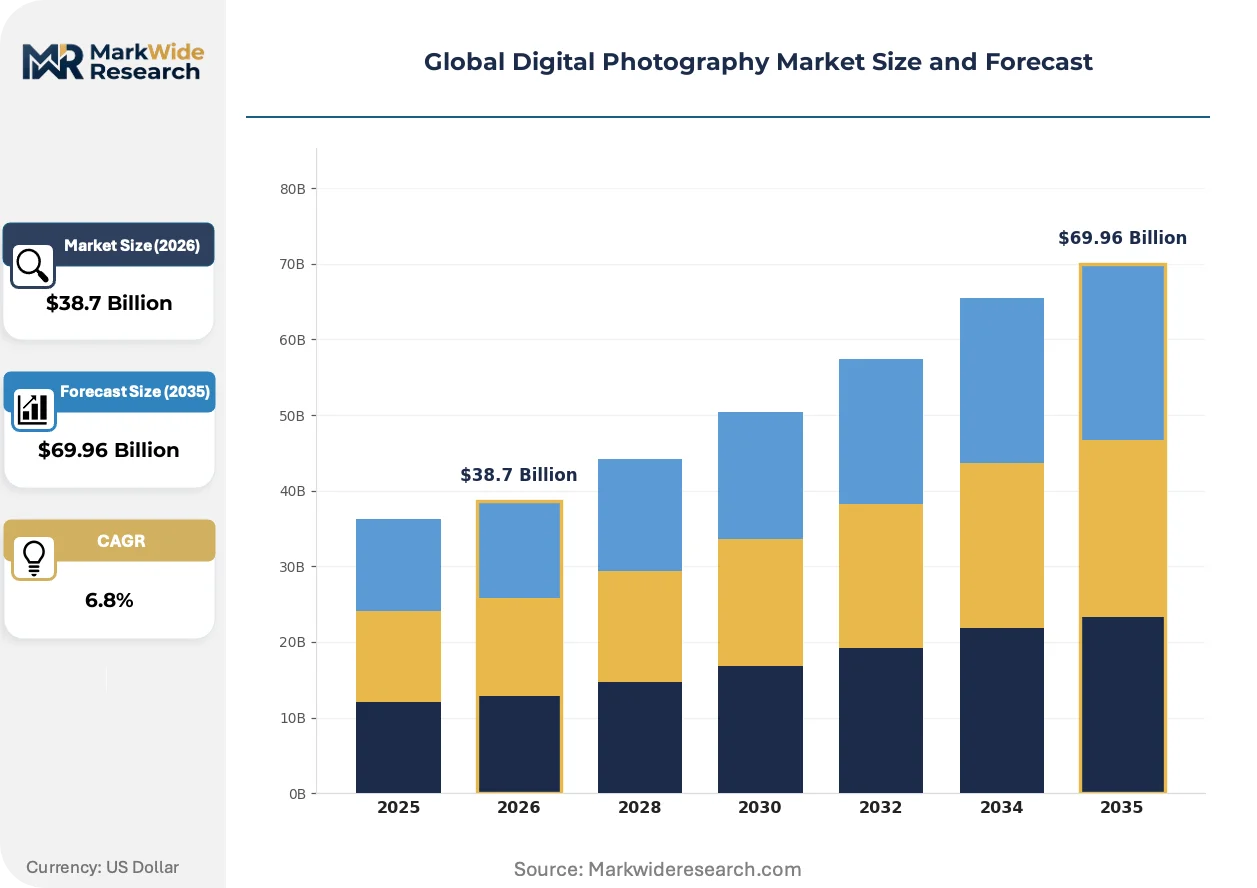
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: DSLR, Mirrorless, Compact, Smartphone End User: Professional Photographers, Enthusiasts, Casual Users, Businesses Image Sensor Type: CMOS, CCD, Live MOS, Foveon Distribution Channel: Online Retail, Electronics Stores, Specialty Shops, Wholesale |
| Companies Covered | Fujifilm Corporation, Olympus Corporation, Canon Inc., OM Digital Solutions, GoPro, Inc., Sony Corporation, Panasonic Corporation, Hasselblad, Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Photography Market Emerging Trajectories
Three convergent forces are restructuring how image capture hardware reaches end users: sensor-stack architectures that compress mechanical complexity, regulatory pressure on material composition and recyclability, and professional procurement patterns that favor rental and subscription over outright purchase.
Stacked-CMOS sensor technology is absorbing the functions previously performed by mechanical shutter assemblies, enabling global electronic shutter operation at speeds exceeding mechanical limits. Wildlife and sports photographers are adopting these sensors for silent burst capture at frame rates above 30fps. The technology is absorbing market share from DSLR architectures that cannot match readout speeds without mirror-box elimination.
EU RoHS and REACH frameworks are restricting cadmium, lead, and mercury deployment in camera electronics and battery assemblies, compelling manufacturers to reformulate solder compositions and cell chemistries. Japanese exporters must demonstrate compliance to maintain European market access. Professional-grade bodies with replaceable battery modules are gaining preference over sealed designs that complicate end-of-life processing.
Rental and subscription-based equipment access is displacing outright purchase among freelance photographers facing irregular project flows. Platforms offering weekly body-and-lens bundles are capturing volume in metropolitan creative clusters. This shift is most visible in London, Berlin, and Los Angeles, where gig-economy content creators prioritize cash-flow flexibility over asset ownership.
Global Digital Photography Market Segmentation
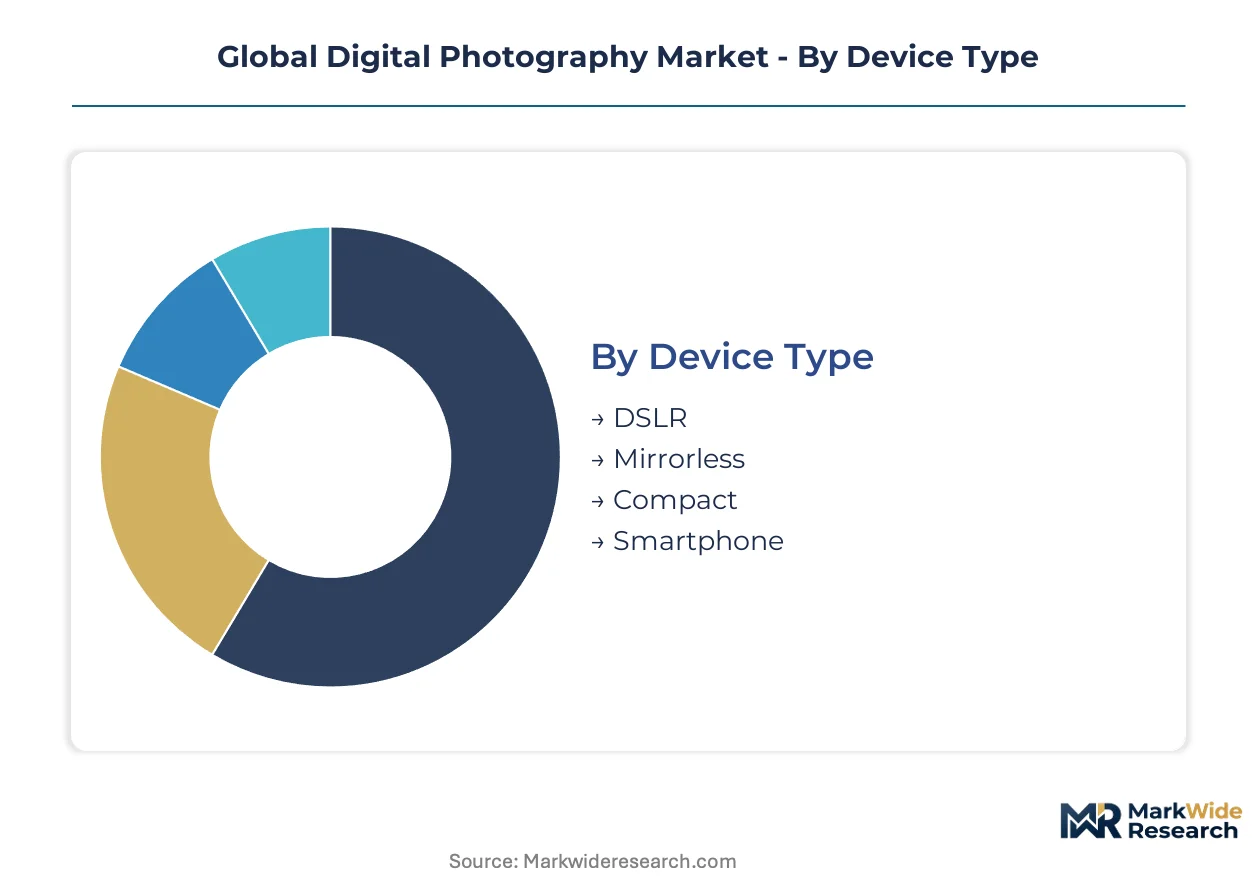
Segmentation in digital photography reveals how certification burdens, sensor architectures, and procurement patterns split value capture across hardware ecosystems. Manufacturers align product roadmaps to these divisions because each segment carries distinct margin profiles and aftermarket attachment rates.
Device Type:
EU RoHS and REACH compliance requirements fall heaviest on mirrorless and DSLR bodies due to their complex PCB assemblies and lithium-ion battery systems, while smartphones face streamlined CE marking through OEM bundling arrangements.
- Mirrorless:Stacked-CMOS architectures eliminate mechanical shutter assemblies, enabling silent burst capture above 30fps. Wedding studios in Shanghai and Mumbai are upgrading to full-frame mirrorless bodies as client expectations for low-light resolution climb.
- DSLR:Optical viewfinder systems with pentaprism assemblies maintain loyalty among sports photographers requiring zero-lag composition. Japan's METI precision standards constrain export-bound manufacturing tolerances for imaging sensors, extending development cycles for manufacturers targeting domestic market entry.
- Compact:1-inch sensor formats face collapsing demand as computational photography in flagship smartphones absorbs casual capture needs.
- Smartphone:Multi-array computational sensors with portrait-mode and night-mode algorithms dominate volume in China through domestic brand dominance.
Smartphone sits at the top of the volume ranking, with mirrorless climbing the fastest.
End User:
Cost tier stratification separates professional photographers commanding premium pricing from enthusiasts seeking value-optimized body-lens bundles and casual users defaulting to integrated smartphone solutions.
- Professional Photographers:Commercial studios and freelance operators sustain aftermarket lens ecosystems carrying margins above hardware bodies. Wildlife specialists in Kenya and sports photographers in Qatar demand specialized optics with weather-sealed construction.
- Enthusiasts:Advanced amateurs drive mirrorless upgrade cycles through RF-mount and Z-mount ecosystem lock-in. Canon's proprietary lens lineups capture this segment through aggressive body-and-lens kit configurations.
- Casual Users:Social media content creators prioritize smartphone connectivity and real-time cloud editing workflows over dedicated hardware investment.
- Businesses:Corporate event departments and real estate marketing teams favor rental subscriptions over capital expenditure for irregular project flows.
Professional photographers command the highest per-unit margins, with businesses gaining share fastest through subscription procurement models.
Image Sensor Type:
Application requirements determine sensor selection, with CMOS architectures dominating where readout speed and power efficiency matter, while specialized formats persist in scientific and archival contexts.
- CMOS:Backside-illuminated and stacked architectures exceed 40-megapixel densities with global electronic shutter capability. China's domestic supply chains concentrate volume manufacturing for these sensors, reducing component costs for global camera assembly.
- CCD:Full-frame transfer architectures persist in scientific imaging and astronomy applications requiring uniform pixel response. Research institutions in Germany and Switzerland maintain limited procurement for specialized spectroscopy equipment.
- Live MOS:Four Thirds format sensors balance readout speed with power consumption in compact system cameras. Olympus and Panasonic camera divisions anchor demand for this architecture.
- Foveon:Vertical color separation technology captures full RGB data per photosite without demosaicing. Sigma Corporation maintains niche production for fine-art reproduction and landscape specialists.
CMOS holds absolute volume dominance, with stacked-CMOS variants expanding most quickly across professional mirrorless deployments.
Distribution Channel:
Geography shapes channel effectiveness, with metropolitan creative clusters favoring rental platforms while tier-2 cities depend on specialty shops for hands-on evaluation.
- Online Retail:E-commerce platforms capture enthusiast and professional segments through detailed specification comparison and body-lens bundle pricing. Amazon and B&H Photo dominate in the US and UK markets.
- Electronics Stores:Big-box retailers serve casual users seeking immediate smartphone accessory purchases alongside camera hardware. Best Buy and Yodobashi Camera leverage foot traffic for impulse lens attachments.
- Specialty Shops:Independent dealers provide hands-on evaluation and technical consultation for high-value purchases. Tier-2 Indian cities like Jaipur and Lucknow outpace local rental infrastructure, forcing wedding photographers toward certified pre-owned marketplaces.
- Wholesale:Direct B2B procurement serves rental houses, educational institutions, and corporate event departments with volume discounts and extended warranty terms.
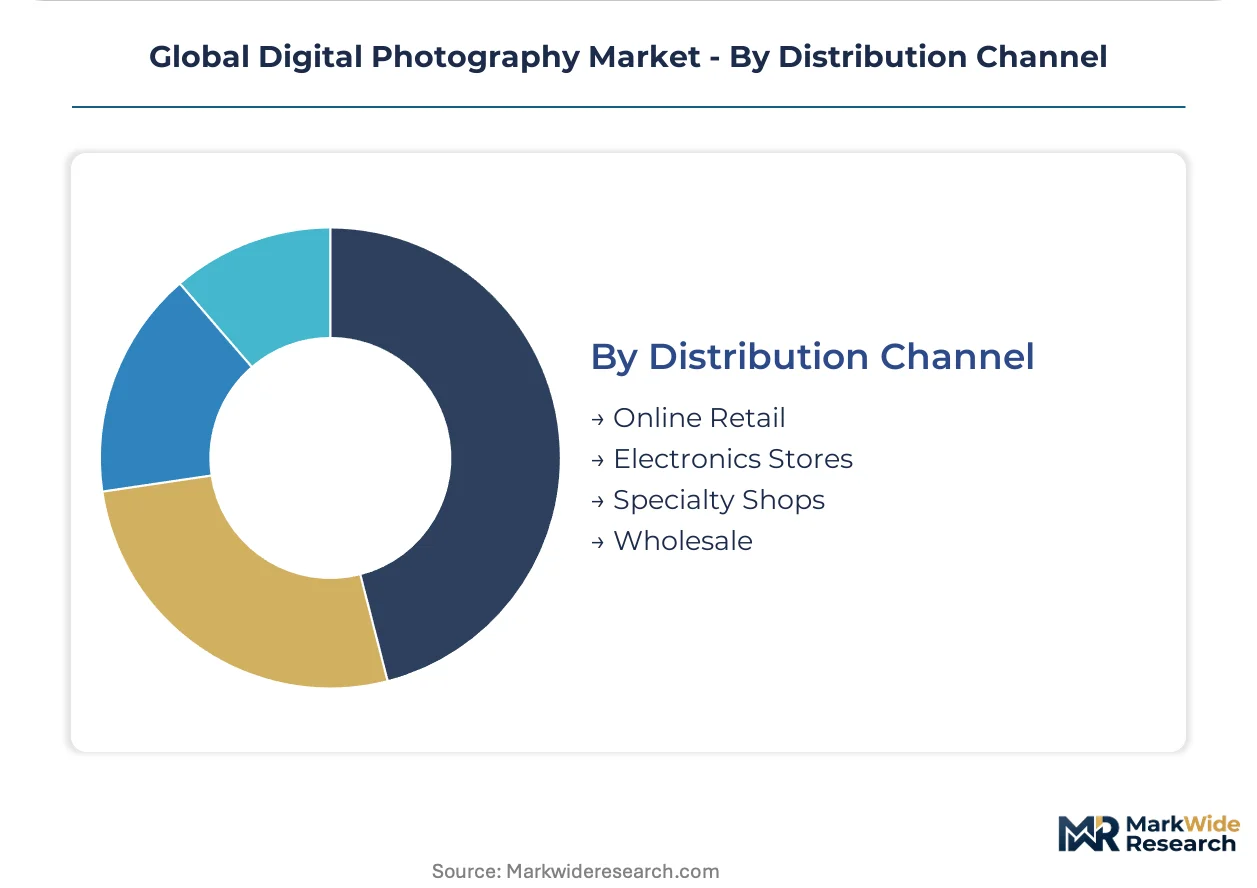
Online retail leads volume throughput, with specialty shops retaining the steepest expansion trajectory in underpenetrated regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered consumer digital imaging with the commercialization of electronic sensors in the 1980s, establishing precision manufacturing clusters that continue to shape global supply chains for CMOS architectures and optical assemblies.
Japan
Wedding studios in Tokyo and Osaka drive mirrorless procurement as client expectations for resolution climb. METI precision equipment standards constrain export-bound manufacturing tolerances for imaging sensors, extending certification cycles. Precision optics fabrication concentrates in the Chubu region around Nagoya, where lens grinding traditions supply global camera assembly lines.
China
Domestic brands dominate volume manufacturing for CMOS sensors and lens assemblies serving both local consumption and export markets. MIIT directives mandate electromagnetic compatibility certification for imported digital imaging equipment entering domestic retail channels. Shenzhen and Dongguan production clusters assemble mirrorless bodies for global brands while cultivating indigenous camera ecosystems.
United States
Content creators in Los Angeles and New York sustain rental subscription demand for irregular project flows. FCC equipment authorization requirements govern wireless-enabled camera systems with smartphone connectivity features. Metropolitan creative clusters prioritize speed-to-publish workflows that favor hybrid computational-optical devices.
Germany
Research institutions in Munich and Berlin maintain limited procurement for scientific imaging requiring uniform pixel response. ECHA REACH frameworks restrict hazardous substance deployment in camera electronics and battery assemblies, accelerating design-for-recyclability investments. Baden-Württemberg precision engineering traditions persist in specialized optical metrology equipment.
India
Wedding photography demand in tier-2 cities like Jaipur and Lucknow outpaces local rental infrastructure. BIS certification requirements govern safety standards for imported lithium-ion battery systems in professional camera bodies. Maharashtra and Karnataka host emerging equipment leasing platforms addressing certified pre-owned marketplace gaps.
Global Digital Photography Market Vendor Landscape
The competitive structure tilts toward ecosystem-locked incumbents with proprietary mount systems and sensor fabrication capabilities. Consolidation around full-frame mirrorless architectures has eliminated several legacy DSLR specialists, leaving tiered competition between vertically integrated sensor manufacturers and optics-as-a-platform licensors. Dominant archetypes include mount-ecosystem orchestrators, stacked-CMOS technology leaders, and computational imaging bridge-device specialists. Competitive moves center on strategic patent licensing for computational photography algorithms and exclusive sensor supply agreements that constrain rival access to advanced readout electronics.
Among Japan-based precision equipment manufacturers, Canon Inc., Sony Corporation, and Nikon Corporation occupy positions spanning the ecosystem-orchestrator and technology-leader archetypes. Canon exemplifies mount-ecosystem lock-in through proprietary RF lens lineups. Sony anchors stacked-CMOS leadership across full-frame and APS-C formats. Nikon sits within the specialized-optics tier with Z-mount roadmaps targeting wildlife and sports segments.
| Leading Market Players |
|---|
| Fujifilm Corporation |
| Olympus Corporation |
| Canon Inc. |
| OM Digital Solutions |
| GoPro, Inc. |
| Sony Corporation |
| Panasonic Corporation |
| Hasselblad |
| Nikon Corporation |
| Others |
Supply Flow & Price Mechanics
Captive sensor fabrication in Japan and China anchors both supply security and pricing power for full-frame mirrorless manufacturers. Sony Corporation and Canon Inc. leverage in-house stacked-CMOS production to defend margin structures against third-party sensor dependency, while Chinese domestic brands exploit local lens assembly clusters to undercut import-heavy competitors on body-only pricing.
Pricing Analysis
Three-tier pricing structure across professional, enthusiast, and entry-level segments separates ecosystem-locked bundles from commodity body sales. Price differentiation hinges on sensor stack complexity and proprietary mount certification, with RF-mount and Z-mount optics commanding premiums over adapted legacy glass. Pricing pressure stems from smartphone substitution collapsing compact camera demand and forcing retreat upmarket. Casual users exhibit extreme price sensitivity and exit to computational photography, while wedding studios show inelastic demand for low-light resolution.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale sensor procurement for global camera assembly, with tiered distribution running through specialty retailers for enthusiast segments. Geographic supply concentration centers on Japan for precision optics, China for CMOS volume manufacturing, and Taiwan for semiconductor fabrication equipment. Raw material dependencies include silicon wafers, rare-earth glass elements, and lithium-ion cell chemistries. Single-source vulnerability in advanced photolithography equipment exposes sensor capacity expansion to cross-border export control risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component cost arbitrage between Chinese domestic supply chains and Japanese precision manufacturing creates margin expansion opportunities for manufacturers with dual-sourcing flexibility. MIIT certification streamlines domestic China retail entry, while METI tolerance requirements extend Japanese market development cycles and inflate compliance overhead.
For Market Incumbents: Deepen proprietary mount ecosystem lock-in through aggressive body-lens bundling and certified pre-owned marketplace infrastructure. Mirrorless sensor architecture leadership requires continuous stacked-CMOS R&D investment to outpace computational photography substitution. Defend against Chinese domestic brands by accelerating RF-mount and Z-mount lens roadmap completion. Vertical integration into precision optics grinding preserves margin capture that outsourced lens assembly erodes.
For New Entrants and Emerging Players: Tier-2 Indian wedding photographers represent an underserved buyer archetype with equipment leasing demand outpacing local rental infrastructure. Bridge devices combining smartphone connectivity with dedicated sensors offer white-space entry for content creator workflows prioritizing speed-to-publish. Computational-optical hybrid positioning avoids direct confrontation with entrenched full-frame mirrorless incumbents. Go-to-market through certified pre-owned platforms and subscription-based access models reduces capital barrier for freelance operator adoption.
For Investors and Strategic Acquirers: Roll-up economics work for regional equipment leasing platforms because wedding photography demand fragmentation across tier-2 Indian cities prevents national scale concentration. Long-term viability hinges on computational-optical convergence sustaining dedicated camera relevance against smartphone substitution. Acquisition targets include specialty optics manufacturers with wildlife and sports positioning, plus cloud-enabled workflow software bridging capture-to-publish latency. Watch stacked-CMOS readout speed benchmarks as inflection indicator for sensor technology leadership shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Stack Architecture Investment | Stacked-CMOS R&D leadership enables silent burst capture above 30fps for wildlife specialists. |
| Proprietary Mount Ecosystem Expansion | RF-mount and Z-mount lens roadmap completion locks enthusiast upgrade cycles. |
| Certified Pre-Owned Marketplace Launch | BIS-compliant refurbishment infrastructure addresses India tier-2 equipment access gaps. |
| Computational-Optical Hybrid Development | Real-time cloud editing workflows capture content creator speed-to-publish priorities. |
| EU Green Deal Circularity Compliance | Modular battery designs qualify for sustainability-linked European public procurement. |
Methodological Framework
Direct dialogue with camera hardware product managers, semiconductor equipment procurement leads, wedding studio operators, and specialty retail buyers grounded qualitative assessment in operational reality. Secondary validation drew from METI precision equipment standards documentation, MIIT electromagnetic compatibility directives, EU RoHS and REACH substance restriction filings, and customs trade data for CMOS sensor and lens assembly flows. Bottom-up equipment shipment analysis triangulated against top-down market sizing from component supply chain disclosures.
Segment-level volume and value trajectories across the projection horizon reflect modeled interactions between mirrorless adoption curves, smartphone substitution elasticities, and regional certification timelines. Segmentation dimensions included device type, end-user archetype, sensor architecture, and distribution channel, with geographic regulatory clusters capturing Japan METI, China MIIT, EU ECHA, and India BIS compliance pathways. CAGRs derived from regression against historical shipment data and forward-looking procurement survey responses, with stacked-CMOS yield rates and computational photography patent filings serving as technology diffusion inputs.
Underlying measurement precision varies by segment; professional photographer equipment expenditure carries tighter precision than casual user smartphone substitution estimates. Forecasts reflect base-case assumptions regarding semiconductor equipment export control stability and wedding photography demand elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Digital Camera Market
Imaging
Image Based Barcode Reader Market
Imaging
AI Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
CMOS Camera Market
Imaging
Mobile Imaging Services Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Handheld Imager Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
North America Image Sensors Market
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Electron Microscopy Market
Imaging
X Ray Tubes Market
Imaging
Digital Imaging Market
Imaging
Biophotonics Market