
 X-Ray Detectors Market | 2026-2036
X-Ray Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Detectors Market Intelligence
Increased manufacturing capacity in Asia-Pacific is rebalancing the supply chain away from historically dominant North American and European production centers. Varex Imaging leverages its extensive product portfolio to serve diverse end-markets, from medical diagnostics to industrial inspection. Thales Group competes on the basis of advanced technology for high-security screening applications in aviation and border control. Canon Inc. differentiates through its strong brand in medical imaging and captive supply of critical sensor components.
X-ray detectors are sophisticated devices that convert X-ray photons into measurable electrical signals, either directly or through an indirect conversion process. These systems typically utilize materials like amorphous silicon or scintillators to generate a high-resolution digital image for analysis. Flat Panel Detectors command the largest market share due to their widespread adoption in medical imaging and industrial non-destructive testing. Complementary Metal-Oxide Semiconductor (CMOS) detectors represent the fastest-growing product type, valued for superior speed and resolution in dental diagnostics.
Regulatory frameworks, including the US FDA's 510(k) clearance process and the EU's Medical Device Regulation (MDR), impose stringent quality and safety standards on all medical devices. In Japan, the PMDA's approval process governs market access for medical imaging equipment, directly shaping product development cycles and timelines. Vendor selection will increasingly hinge on the ability to navigate these complex, region-specific compliance pathways while demonstrating superior imaging performance and reliability.
Market Dynamics
The fundamental shift from analog and computed radiography to direct digital formats is the central force shaping the X-ray detectors market. This transition, driven by the superior performance of flat panel detectors, compels manufacturers to innovate on sensor materials and software integration.
Growth Catalysts
- Non-Destructive Testing Expansion:The mandate for stringent quality control in aerospace and electric vehicle battery manufacturing drives adoption of high-resolution detectors for identifying microscopic flaws and ensuring component integrity.
- Food Safety Regulations:Stricter regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) compel food processors to deploy X-ray inspection systems for contaminant detection, boosting detector demand.
- CMOS Technology Adoption:The inherent speed and lower electronic noise of CMOS sensors are accelerating their use in real-time applications like dental intraoral imaging and fluoroscopy, creating new performance tiers.
Market Restraints
- High Input Costs:The price volatility and supply concentration of key scintillator materials, such as cesium iodide and gadolinium oxysulfide, create significant cost pressures and margin sensitivity for detector manufacturers.
- Stringent Regulatory Hurdles:Lengthy and expensive approval pathways, including the FDA's 510(k) process and the EU's MDR, act as significant barriers to entry and slow the commercialization of new medical imaging devices.
- Technical Performance Trade-offs:A persistent trade-off exists between detector resolution, sensitivity, and readout speed, limiting performance in certain demanding applications like high-speed industrial scanning where all three are critical.
Strategic Opportunities
- Portable and Mobile Systems:Development of lightweight, ruggedized detectors opens new markets in mobile security screening, veterinary medicine, and field-based industrial inspection where portability is a primary requirement.
- Photon-Counting Detectors:Next-generation photon-counting technology offers the potential for dose reduction and improved material differentiation, creating significant opportunities in advanced medical diagnostics like spectral CT.
- Agricultural Inspection:Underpenetrated applications in agriculture, particularly for quality grading and contaminant detection in bulk goods in markets like Brazil and India, present a volume growth opportunity.
Industry Challenges
- Systems Integration Complexity:Integrating new digital detectors with legacy hospital IT infrastructure, particularly older Picture Archiving and Communication Systems (PACS), presents a significant technical and logistical challenge for healthcare providers.
- Talent Scarcity:A shortage of technicians and engineers with expertise in detector calibration, maintenance, and advanced image analysis software hampers service delivery and limits the effective use of sophisticated systems.
- Divergent Data Security Standards:Manufacturers must navigate a complex web of data privacy regulations, such as HIPAA in the US and GDPR in Europe, when developing cloud-connected detectors and associated software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Detectors Market |
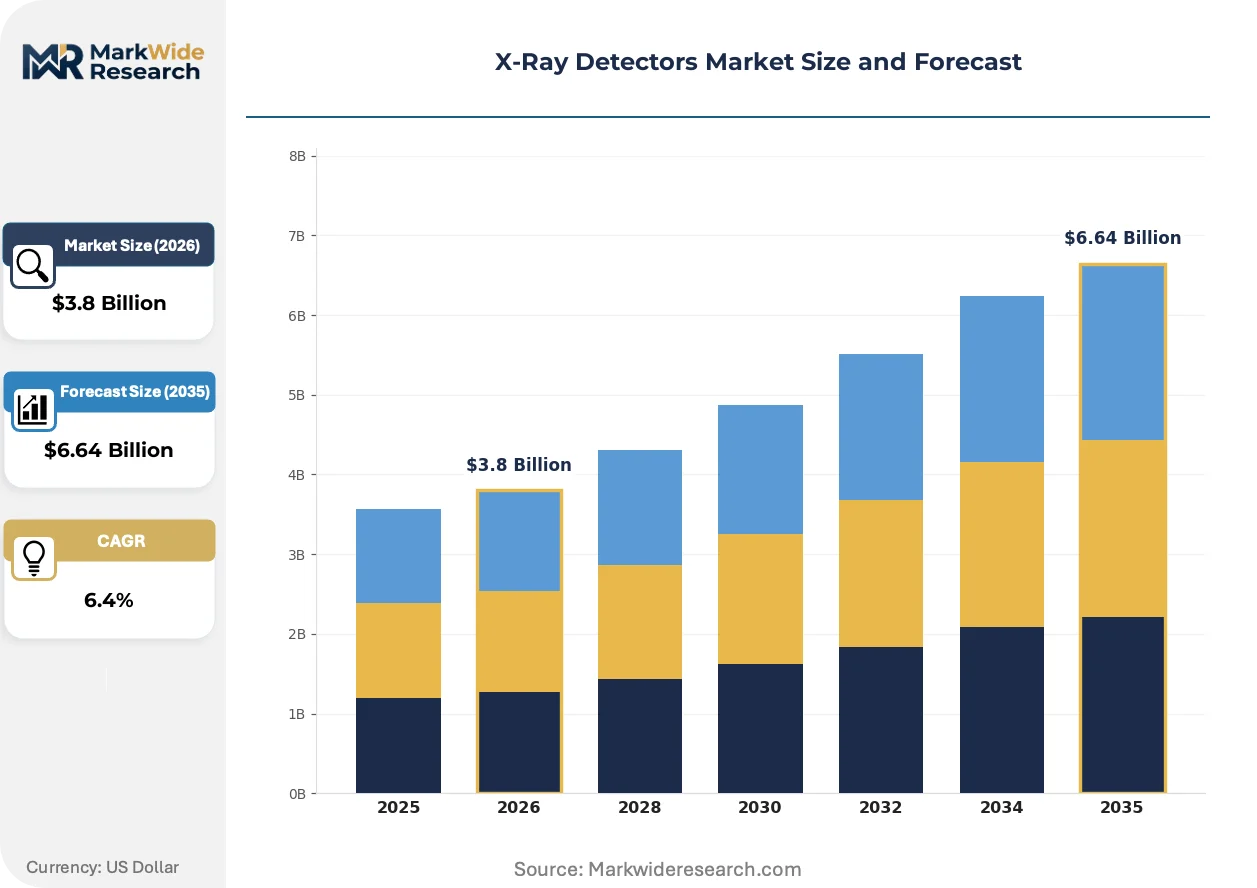
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Charge Coupled Devices, Computed Radiography Systems, Complementary Metal-Oxide Semiconductors Technology: Scintillator, Direct Conversion, Indirect Conversion, Amorphous Silicon, Phosphor Screen Application: Medical Imaging, Non-Destructive Testing, Security Screening, Dental Diagnostics, Veterinary Imaging End User: Hospitals, Diagnostic Laboratories, Manufacturing Plants, Security Agencies, Research Institutions |
| Companies Covered | Varex Imaging, Thales Group, Canon Inc., Fujifilm Holdings Corporation, Agfa-Gevaert Group, Carestream Health, Hamamatsu Photonics K.K., Analogic Corporation, Detection Technology Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Detectors Market Strategic Shifts & Innovations
Technological advancement is focused on embedding intelligence directly within the detector, transforming it from a simple capture device into an active component of the diagnostic or inspection workflow. This shift prioritizes speed, automation, and data quality at the point of acquisition.
Artificial intelligence algorithms are now being integrated directly onto detector hardware for on-device image processing. The industrial non-destructive testing and security screening sectors are early adopters, using this capability for real-time defect and threat recognition. This on-device processing is decentralizing analytical intelligence from central servers, enabling faster, autonomous decisions at the network edge.
New regulatory mandates, particularly the European Union's Medical Device Regulation (MDR), are imposing more rigorous requirements for clinical evidence and post-market surveillance. This directly increases the total cost and timeline of compliance for all medical-grade X-ray detectors sold in the EU. The diagnostic imaging segment is most affected, compelling vendors to overhaul their quality management systems and technical documentation to maintain market access.
A notable behavioral shift in procurement is the move away from outright capital purchases toward subscription-based or pay-per-use models. This trend disrupts the traditional sales cycle for equipment, especially for smaller dental offices and independent clinics preferring operational over capital expenses. This shift is most prominent within the private healthcare markets of North America and Western Europe.
X-Ray Detectors Market Segmentation
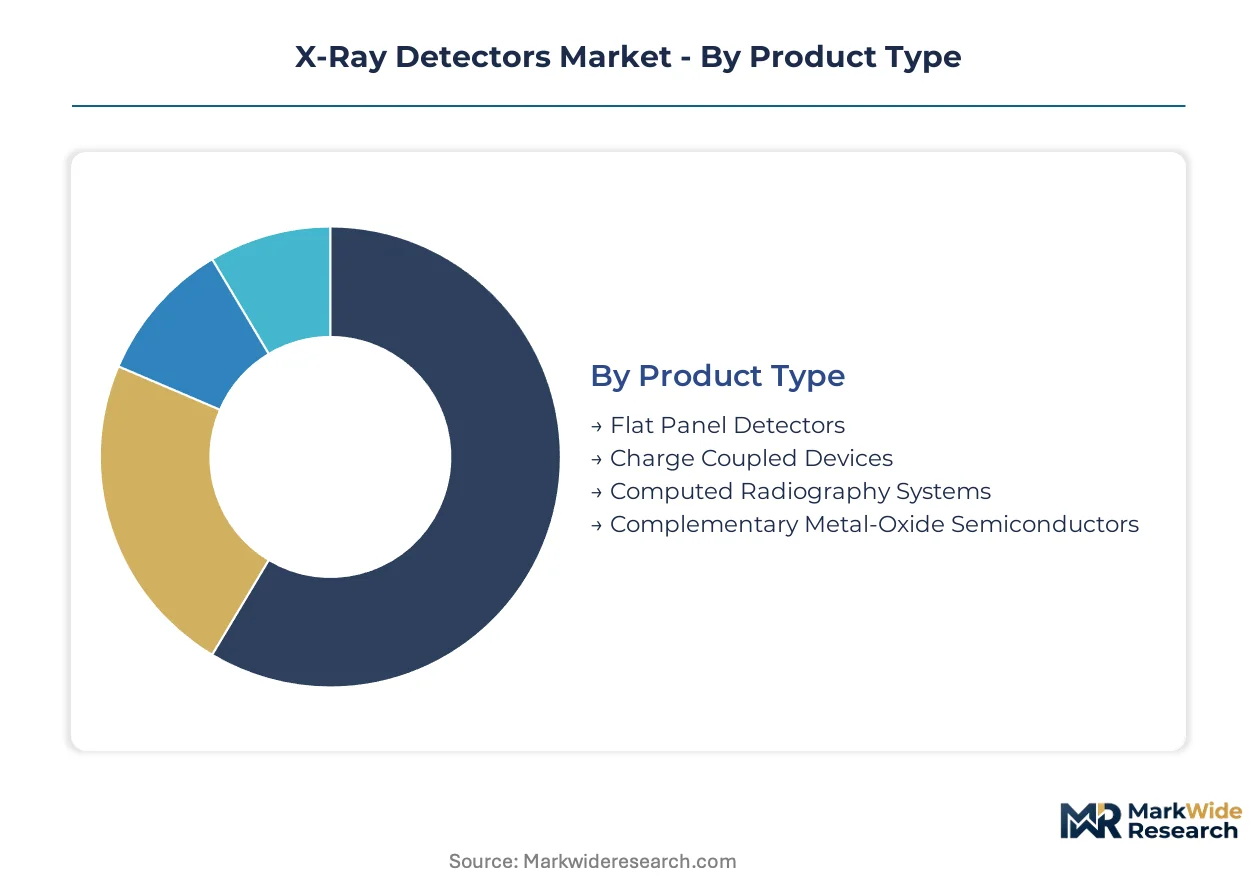
The X-ray detectors market exhibits diverse segmentation, reflecting varied technological capabilities, application requirements, and end-user needs. Understanding these distinctions is critical for manufacturers to tailor product development and for end-users to select optimal systems for specific diagnostic or inspection challenges. This granular view highlights areas of concentrated demand and emerging growth.
Product Type:
Buyers in the X-ray detectors market differentiate product selection based on required image quality, speed, and cost-efficiency for specific diagnostic or inspection tasks.
- Flat Panel Detectors:These devices convert X-ray photons directly or indirectly into digital electrical signals, offering high-resolution images and wide dynamic range. Demand concentrates in medical imaging and industrial non-destructive testing for their widespread adoption and performance.
- Complementary Metal-Oxide Semiconductors:CMOS detectors provide superior speed, lower electronic noise, and high-resolution imaging, making them ideal for real-time applications. Growth is concentrated in dental intraoral imaging and fluoroscopy due to their advanced performance tiers.
- Charge Coupled Devices:CCDs are light-sensitive integrated circuits that capture images, often used in scientific and specialized medical imaging applications requiring high sensitivity.
- Computed Radiography Systems:CR systems use reusable imaging plates that capture X-ray energy, later processed by a scanner to create a digital image.
Volume sits with Flat Panel Detectors; growth tilts toward Complementary Metal-Oxide Semiconductors.
Technology:
The underlying conversion mechanism significantly influences detector performance characteristics, impacting resolution, sensitivity, and radiation dose requirements.
- Indirect Conversion:This technology uses a scintillator material to first convert X-ray photons into visible light, which is then captured by a photodetector like amorphous silicon or a CCD array. Medical diagnostics, including mammography and general radiography, heavily utilize indirect conversion for its established performance.
- Direct Conversion:Direct conversion detectors use a semiconductor material, such as amorphous selenium, to directly convert X-ray photons into electrical charges, offering higher spatial resolution without light scattering. Advanced industrial inspection and high-resolution medical imaging drive demand for direct conversion systems.
- Scintillator:Scintillator materials like cesium iodide or gadolinium oxysulfide absorb X-rays and emit visible light, forming a critical component of indirect conversion detectors.
- Amorphous Silicon:Amorphous silicon panels serve as the photodetector array in many flat panel detectors, converting visible light from scintillators into electrical signals.
- Phosphor Screen:Phosphor screens are traditional X-ray image receptors that convert X-rays into visible light, typically used in older film-based radiography or as a component in CR systems.
Indirect Conversion technologies currently dominate, while photon-counting advancements are pushing Direct Conversion capabilities.
Application:
End-use applications dictate the specific performance metrics and regulatory compliance standards required from X-ray detector systems.
- Medical Imaging:This segment includes general radiography, fluoroscopy, mammography, and computed tomography, where detectors provide critical diagnostic information for patient care. Regulatory frameworks like the US FDA's 510(k) and EU MDR significantly influence product development in medical imaging.
- Non-Destructive Testing:NDT applications involve inspecting materials and components for flaws without causing damage, crucial for quality assurance in aerospace and automotive manufacturing. High-resolution detectors are essential for identifying microscopic imperfections in critical components.
- Security Screening:X-ray detectors are deployed in aviation, border control, and public venues for threat detection and contraband identification. Thales Group competes on the basis of advanced technology for high-security screening applications.
- Dental Diagnostics:This application utilizes X-ray detectors for intraoral, panoramic, and cephalometric imaging to diagnose dental conditions. CMOS detectors are gaining traction in dental diagnostics for superior speed and resolution.
- Veterinary Imaging:X-ray systems assist in diagnosing injuries and illnesses in animals, serving both companion animal clinics and large animal practices.
Medical Imaging represents the largest application area, with Non-Destructive Testing showing significant expansion in industrial sectors.
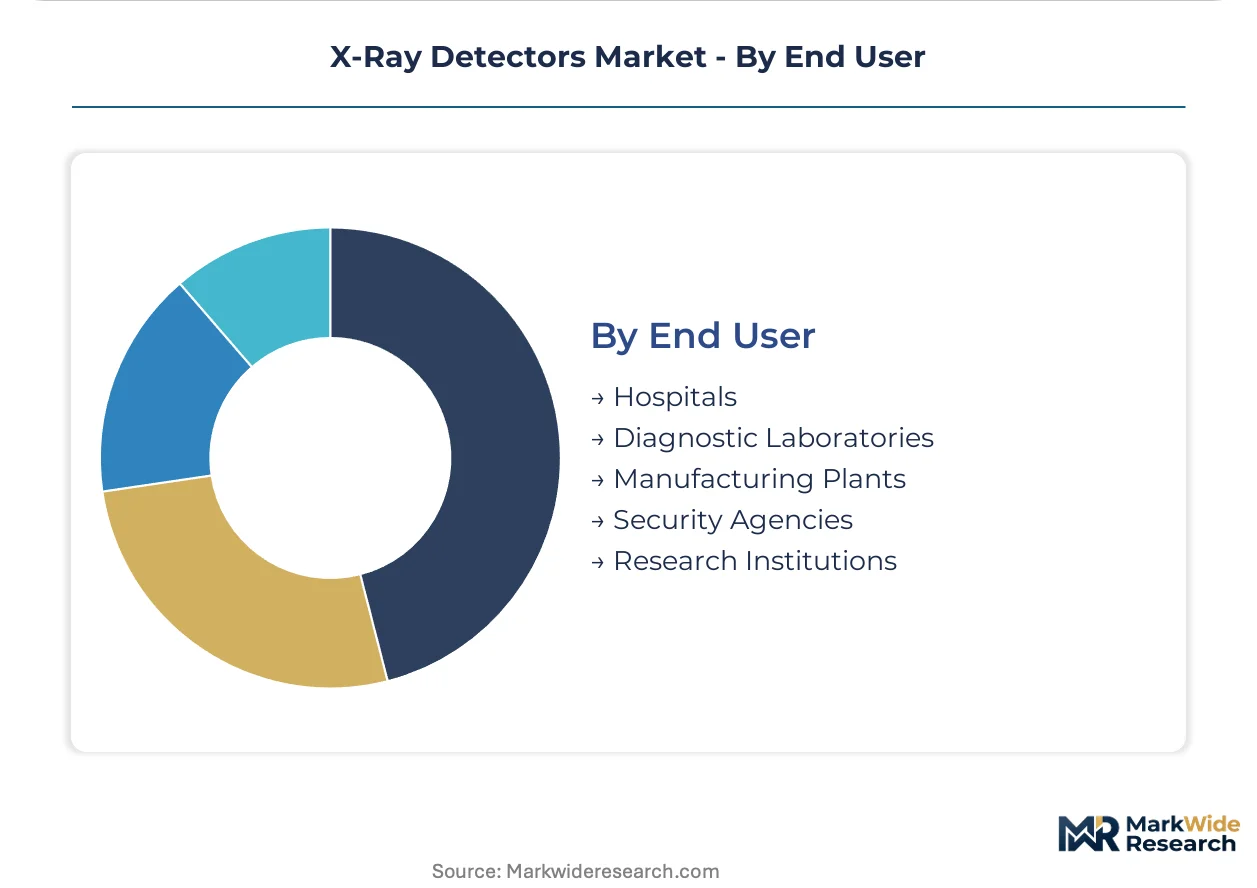
End User:
Different end-user environments possess distinct operational needs and budget constraints, influencing detector procurement and integration strategies.
- Hospitals:Hospitals are major consumers of X-ray detectors for a wide range of diagnostic procedures, requiring integration with existing PACS and IT infrastructure. Vendor selection hinges on navigating complex, region-specific compliance pathways like PMDA approval in Japan.
- Manufacturing Plants:These facilities utilize X-ray detectors for automated quality control, material inspection, and process optimization in industries like aerospace and electronics. Stringent quality control mandates in electric vehicle battery manufacturing drive detector adoption.
- Diagnostic Laboratories:Independent diagnostic labs perform specialized X-ray imaging services, often focusing on specific modalities or patient populations. These labs prioritize cost-effective and efficient imaging solutions.
- Security Agencies:Government and private security entities deploy X-ray systems for screening luggage, cargo, and personnel at airports, ports, and critical infrastructure. These agencies require robust systems for reliable threat detection.
- Research Institutions:Academic and private research institutions use X-ray detectors for scientific studies, materials analysis, and development of new imaging techniques.
Hospitals remain the primary end-user segment, though Manufacturing Plants are rapidly increasing their detector deployments for quality control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global X-ray detectors market finds its material anchor in regions with advanced manufacturing capabilities and specialized material suppliers. Key geographies like the United States, China, and Germany drive innovation and demand. These areas also host critical regulatory bodies shaping product development and market access.
United States
Demand for X-ray detectors in the United States stems from advanced medical diagnostics and aerospace non-destructive testing. The US FDA's 510(k) clearance process significantly impacts product development and market entry for medical devices. Silicon Valley and Boston's medical technology clusters foster innovation in detector design and software integration.
China
China's electronics and electric vehicle battery manufacturing clusters generate substantial demand for high-resolution X-ray detectors. The NMPA's approval process for medical devices influences market access and local production strategies. The Yangtze River Delta region, with its extensive industrial base, serves as a hub for both production and consumption of these systems.
Germany
Germany's robust automotive and industrial machinery sectors require advanced X-ray inspection for quality control and material analysis. The EU's Medical Device Regulation (MDR) sets stringent standards for medical X-ray detectors sold across the European Union. Bavaria and Baden-Württemberg, home to major industrial players, concentrate R&D and manufacturing activities.
Japan
Japan's medical imaging industry and precision manufacturing sectors drive demand for sophisticated X-ray detector technologies. The PMDA's approval process governs market access for medical imaging equipment, shaping product development cycles. The Kanto region, including Tokyo, hosts major technology companies and research institutions focused on detector innovation.
India
India's expanding healthcare infrastructure and growing industrial base, particularly in automotive, create new opportunities for X-ray detector deployment. The CDSCO's regulatory framework for medical devices guides product registration and market entry within the country. Major metropolitan centers like Mumbai and Bengaluru are emerging as key markets for both medical and industrial applications.
X-Ray Detectors Market Key Industry Players
Global majors compete with regional champions across technology development and market reach. The X-ray detectors market exhibits a tiered structure, with established players dominating high-value segments and specialized firms serving niche applications. Strategic archetypes include diversified imaging giants, industrial inspection specialists, and pure-play detector manufacturers. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand technological capabilities.
Within the diversified imaging giants archetype, Varex Imaging and Canon Inc. occupy significant positions, leveraging extensive product portfolios and strong brand recognition. Varex Imaging serves diverse end-markets, from medical diagnostics to industrial inspection, while Canon Inc. differentiates through its strong brand in medical imaging and captive supply of critical sensor components. Thales Group, representing an industrial inspection specialist, competes on the basis of advanced technology for high-security screening applications in aviation and border control.
| Leading Market Players |
|---|
| Varex Imaging |
| Thales Group |
| Canon Inc. |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert Group |
| Carestream Health |
| Hamamatsu Photonics K.K. |
| Analogic Corporation |
| Detection Technology Plc. |
| Others |
Cost & Logistics Intelligence
Cesium iodide and gadolinium oxysulfide price fluctuations directly impact detector manufacturing costs. These material cost shifts cascade through the supply chain, influencing final product pricing across different performance tiers.
Pricing Analysis
Warranty and service bundling increasingly define the total cost of ownership for X-ray detectors. The market primarily operates on a hybrid model, combining per-unit capital purchases with growing subscription-based options for software and maintenance. Price differentiation stems from detector performance tiers, regulatory compliance certifications, and the extent of after-sales support. Cost compression is intensifying in the medical imaging segment due to stringent regulatory requirements; smaller independent clinics exhibit the highest price sensitivity.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for X-ray detectors. Supply concentration for critical components centers on China for electronics and Japan for precision manufacturing. The industry relies heavily on amorphous silicon and specialized scintillator materials like cesium iodide. Price volatility and supply concentration of these key scintillator materials pose a significant structural risk; distribution runs through direct sales channels for major hospital systems and manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The X-ray detectors market is currently navigating a significant technology-transition phase. The shift from analog and computed radiography to direct digital formats, particularly flat panel detectors, is displacing legacy systems.
For Market Incumbents: Deploy portfolio diversification strategies to mitigate risks from technological shifts. Invest heavily in next-generation CMOS and photon-counting detector R&D to counter emerging performance threats. Expand market reach into non-destructive testing and food safety applications, leveraging existing industrial inspection expertise. This approach defends against margin erosion from commoditization in traditional medical imaging.
For New Entrants and Emerging Players: Begin with targeting underpenetrated applications like portable security screening or agricultural inspection. Focus on developing cost-effective, high-speed CMOS solutions for specialized dental intraoral imaging. A go-to-market strategy emphasizing ease of integration and lower total cost of ownership will attract smaller clinics and industrial users. This strategy avoids direct competition with established players in high-volume medical segments.
For Investors and Strategic Acquirers: The window for entry favors specialized technology firms with proven CMOS or photon-counting IP. The market exhibits strong long-term viability, driven by continuous digital transformation across medical and industrial sectors. Target acquisition candidates include mid-sized companies with established regulatory compliance pathways and niche application expertise. Watch for the acceleration of AI integration directly into detector hardware as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| CMOS Technology Licensing | Accelerates product development cycles for new dental and fluoroscopy applications. |
| Non-Destructive Testing Expansion | Captures demand from aerospace and electric vehicle battery manufacturing quality control. |
| Regulatory Compliance Streamlining | Reduces time-to-market for medical imaging devices under EU MDR and US FDA 510(k). |
| Portable System Development | Opens new markets in veterinary medicine and field-based industrial inspection requiring mobility. |
| AI-on-Device Integration | Enables real-time defect recognition in industrial settings and enhances diagnostic workflow efficiency. |
Research Approach
US FDA 510(k) databases, EU MDR guidelines, and industry association reports formed the secondary backbone for this analysis. Primary interviews with biomedical engineers, NDT specialists, and hospital procurement managers provided qualitative insights. This approach integrated bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Historical trendline analysis established the foundational growth trajectory across the analysis window. The forecast framework modeled segmentation dimensions including product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from a regression analysis of historical data and projected market drivers. Key inputs included technological advancement rates and capital expenditure in medical imaging.
Underlying measurement precision varies by segment; medical imaging and non-destructive testing carry tighter precision than others. Forecasts reflect assumptions regarding regulatory shifts and material supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Infrared Detection Chip Market
Detection and Regulation Devices
Hitoxic Gas Detector Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Pyro Electric Infrared Detectors Market
Detection and Regulation Devices
Electronic Article Surveillance Market
Detection and Regulation Devices
Global Portable Gas Detector Market
Detection and Regulation Devices
Europe Trace Detection Market
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Walk Through Metal Detector Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market