
 Global AI in Computer Vision Market | 2026-2036
Global AI in Computer Vision Market Size, Share, and Industry Trends Forecast 2026-2036
Global AI in Computer Vision Market Foresight
China's massive build-out of intelligent manufacturing zones and national AI computing centers is reshaping how computer vision infrastructure scales across industrial corridors. NVIDIA Corporation leverages its CUDA ecosystem and specialized silicon architectures to anchor high-performance training workloads for vision models. Microsoft Corporation sustains competitive pressure through cloud-native AI services that integrate computer vision APIs with enterprise data pipelines. Intel Corporation differentiates via OpenVINO tooling and edge-optimized chipsets that target on-premises deployment scenarios in regulated environments.
AI in computer vision denotes systems that apply artificial intelligence algorithms—primarily convolutional and transformer-based neural networks—to extract, classify, and interpret visual information from digital images or video streams, typically processing inputs at 30-60 frames per second for real-time applications. These systems serve industrial automation, medical diagnostics, autonomous navigation, and security screening by converting pixel data into structured, actionable metadata without human visual inspection. Deep learning architectures now dominate the technology segment because multilayer neural networks deliver superior accuracy in object detection and scene understanding compared to classical machine learning approaches. Edge computing deployments are gaining structural prominence as manufacturers and surveillance operators prioritize millisecond-latency inference over cloud round-trips, shifting margin pools toward embedded hardware and on-device optimization toolkits. Cloud-based platforms still occupy the largest revenue share among deployment modes due to elastic scalability and centralized model management for retail chains running multi-location vision analytics.
The FDA regulates AI-enabled diagnostic imaging software as Class II or III medical devices, requiring clinical validation and premarket notification that shapes product development timelines for healthcare computer vision vendors. The EU AI Act imposes conformity assessments and risk classification on biometric identification and critical infrastructure applications, directly affecting how European surveillance operators and automotive suppliers procure vision systems. China's SAMR and MIIT enforce algorithmic transparency and data security standards for commercial AI deployment, creating compliance costs that favor domestic platform providers. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Beijing fragment certification requirements and force region-specific product variants.
Market Dynamics
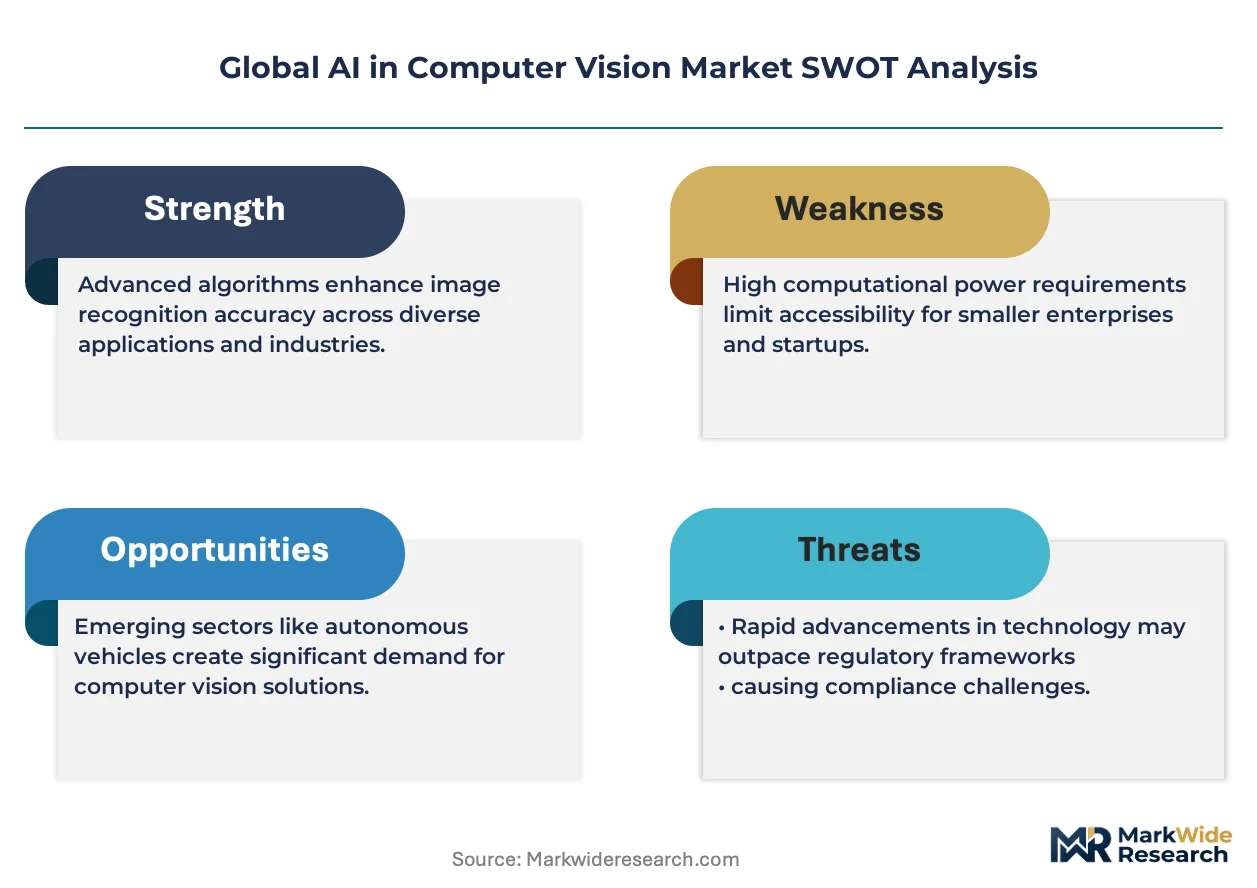
Edge-first deployment architectures are restructuring competitive advantage across the Global AI in Computer Vision Market as manufacturers prioritize sub-50ms inference latency over cloud scalability. This shift concentrates margin capture toward embedded silicon vendors and on-device optimization toolchains.
Growth Catalysts
- EU AI Act conformity mandates:Biometric identification and critical infrastructure classifications force European automotive suppliers and surveillance operators to upgrade vision systems, accelerating replacement cycles for non-compliant legacy installations.
- Intelligent manufacturing zones:China's national AI computing center build-out creates captive demand for industrial inspection systems across Shenzhen, Suzhou, and Chongqing industrial corridors.
- Transformer-based architectures:Vision transformers deliver superior scene understanding accuracy versus convolutional networks, pulling R&D investment from incumbent CNN-optimized hardware toward attention-mechanism silicon.
Market Restraints
- GPU supply concentration:Advanced training chip fabrication concentrates at TSMC's Taiwan facilities, exposing vision model developers to single-source foundry risk and allocation delays.
- FDA premarket notification timelines:Class II medical device pathways for diagnostic imaging software extend product commercialization by 18-24 months, compressing effective patent life for healthcare AI vendors.
- High-resolution sensor costs:Specialized CMOS and event-camera modules for autonomous navigation carry 3-4x premiums over standard industrial vision sensors, elevating bill-of-materials for automotive Tier-1 suppliers.
Strategic Opportunities
- Saudi Arabia's NEOM and Red Sea projects:Giga-project construction creates greenfield demand for construction-site safety monitoring and perimeter surveillance without legacy system integration burden.
- SAMR algorithmic transparency requirements:China's enforcement of data security and explainability standards favors domestic platform providers with localized compliance infrastructure, creating protected market share for compliant vendors.
- Hyperspectral-multimodal fusion:Convergence of spectral imaging with LiDAR and thermal sensors enables defect detection in semiconductor wafer inspection previously invisible to RGB-only systems.
Industry Challenges
- Embedded systems optimization expertise:Scarce talent capable of quantizing transformer models for ARM and RISC-V edge targets without accuracy degradation limits vendor deployment velocity.
- Multi-jurisdiction certification parallelism:Simultaneous FDA, EU MDR, and NMPA submissions for diagnostic imaging AI fragment engineering resources and delay revenue recognition.
- Legacy PLC integration friction:Brownfield manufacturing environments running Siemens S7 and Rockwell ControlLogix require custom protocol gateways to ingest vision system outputs, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global AI in Computer Vision Market |
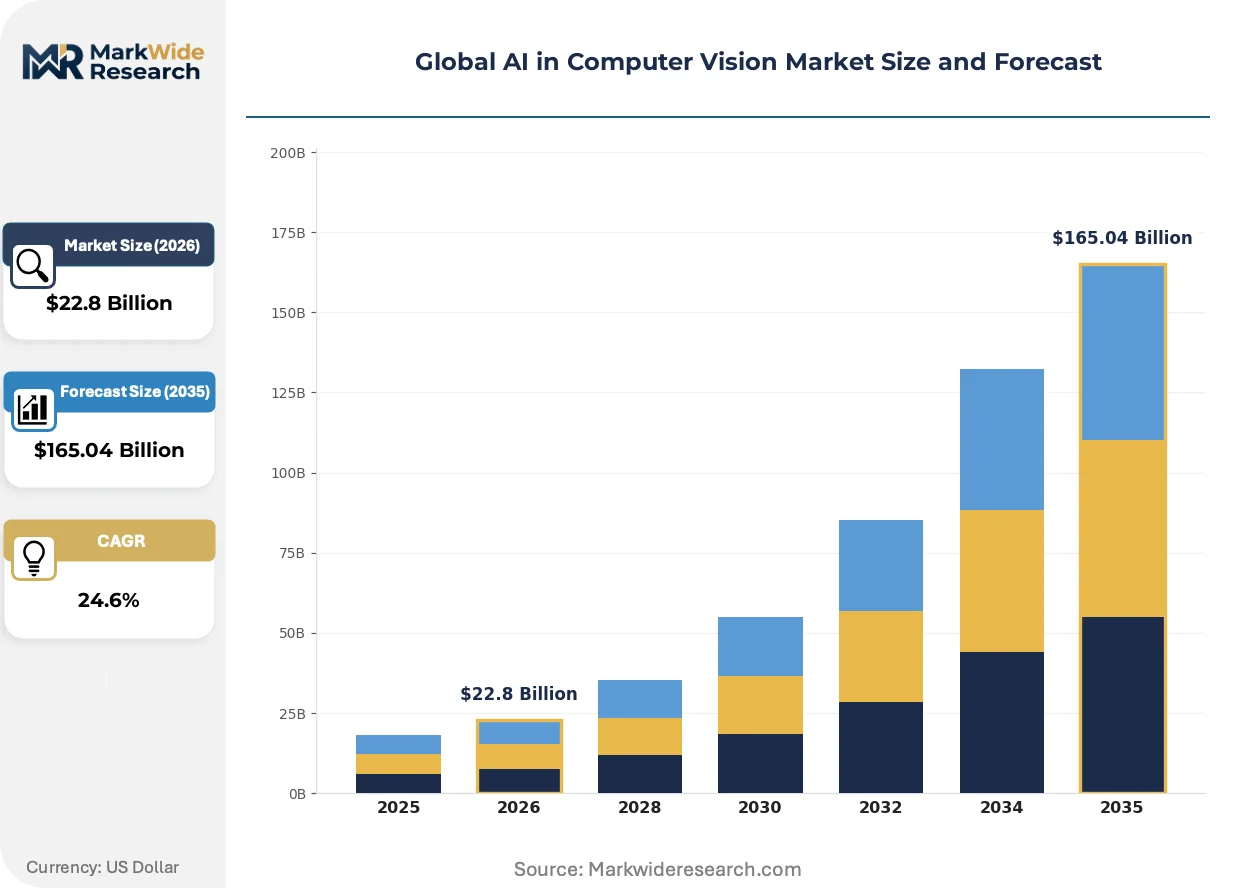
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $165.04 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Machine Learning, Neural Networks, Natural Language Processing, Computer Graphics Application: Facial Recognition, Object Detection, Gesture Recognition, Image Segmentation, Scene Reconstruction Deployment: Cloud-based, On-premises, Edge Computing, Hybrid, Mobile Platforms End User: Surveillance Operators, Manufacturing Units, Retail Chains, Automotive Suppliers, Agricultural Technicians |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, Intel Corporation, Google LLC, Amazon Web Services, IBM Corporation, Cognex Corporation, Teledyne Technologies, Qualcomm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global AI in Computer Vision Market Shifts & Advancements
Neural architecture search and automated model compression are compressing development cycles for production-grade vision systems. These capabilities are redistributing competitive advantage from model-scale toward deployment-efficiency optimization.
Neuromorphic event cameras that output pixel-level intensity changes rather than full frames are rendering obsolete frame-based inspection systems in high-speed manufacturing lines. Automotive battery cell producers and semiconductor wafer fabs are piloting these sensors for microsecond-latency defect detection. The technology is rendering obsolete the 30-60 FPS standard that has dominated machine vision for two decades, forcing incumbent camera vendors to retool product roadmaps or cede high-speed segments.
The EU AI Act's risk-classification framework for biometric identification systems is restructuring procurement specifications for European airport operators and municipal surveillance authorities. High-risk categorization triggers mandatory conformity assessments, third-party auditing, and human-in-the-loop requirements that cloud-native API providers struggle to satisfy. German automotive suppliers and French critical infrastructure operators are now specifying on-premise deployment with full data sovereignty as non-negotiable terms, reversing prior cloud-first preferences.
Subscription-based vision analytics are displacing perpetual-license models in multi-location retail chains and logistics networks. Buyers prefer operational expenditure alignment with transaction volumes over upfront capital deployment for edge hardware. This preference shift is most pronounced among US-based quick-service restaurant chains and third-party logistics providers operating 500-plus facility footprints, where centralized model management and elastic inference scaling outweigh ownership economics.
Global AI in Computer Vision Market Segmentation
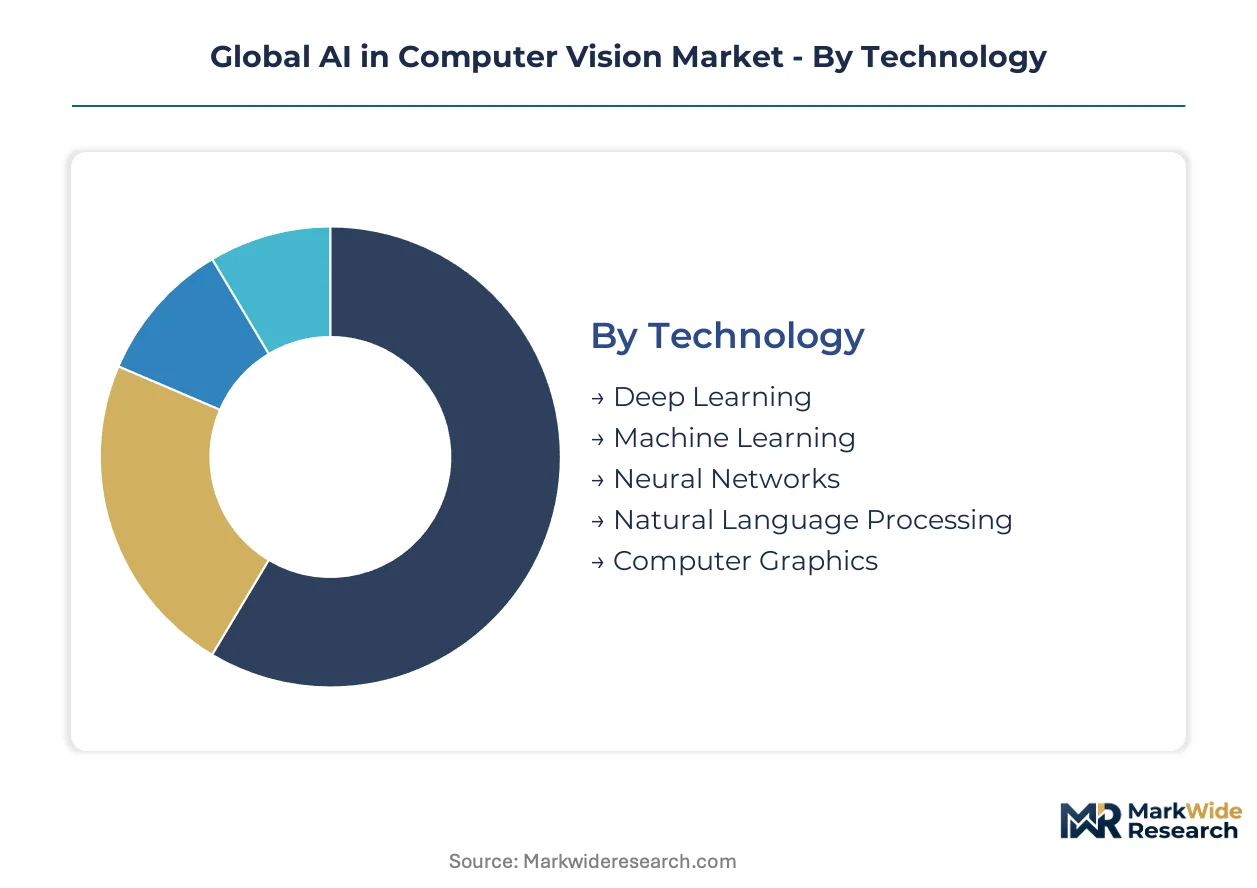
Segmentation in the Global AI in Computer Vision Market reveals how technology choices cascade through deployment architectures and end-use requirements. Understanding these dimensions exposes where margin pools concentrate and which capability combinations command pricing power.
Technology:
Cost tier separates foundational algorithms from specialized architectures that carry premium development overhead.
- Deep Learning:Multilayer neural networks process pixel data through convolutional and transformer architectures, achieving superior accuracy in object detection versus classical approaches. Manufacturing units in Germany and automotive suppliers in the United States concentrate procurement here for quality inspection and autonomous navigation systems.
- Machine Learning:Classical algorithms including SVM and decision trees persist in resource-constrained environments where interpretability requirements override accuracy gains. Agricultural technicians across India's precision farming corridors deploy these for crop health classification on low-power edge devices.
- Neural Networks:Feedforward and recurrent architectures provide baseline pattern recognition for legacy vision system upgrades.
- Natural Language Processing:Multimodal systems that fuse visual and textual understanding enable automated captioning and visual question answering for accessibility applications.
- Computer Graphics:Synthetic data generation and rendering pipelines supply training datasets for scenarios where real-world collection proves impractical or hazardous.
Deep Learning holds installed capacity. Neural Networks is rotating up the share rankings as quantization techniques mature.
Application:
Application focus determines hardware specification intensity and regulatory exposure across deployment scenarios.
- Facial Recognition:Biometric identification systems map facial geometry for access control and surveillance, processing 30-60 frames per second for real-time matching. Surveillance operators in France and airport authorities in Germany face EU AI Act high-risk classification mandates that trigger conformity assessments and human-in-the-loop requirements.
- Object Detection:Bounding box regression and instance segmentation localize and classify multiple entities within scenes. Automotive suppliers in China and the United States anchor demand here for pedestrian detection and collision avoidance in autonomous vehicle stacks.
- Gesture Recognition:Skeletal tracking and motion classification enable human-machine interaction without physical contact.
- Image Segmentation:Pixel-level classification separates foreground from background for medical imaging and industrial defect analysis.
- Scene Reconstruction:Multi-view geometry and depth estimation generate three-dimensional environmental models for robotics and augmented reality.
Object Detection dominates current deployment volume. Gesture Recognition is climbing the fastest as touchless interfaces proliferate in retail and healthcare settings.
Deployment:
Deployment mode reflects the latency-versus-scalability tradeoff that structures procurement decisions across end-use verticals.
- Cloud-based:Centralized inference on hyperscaler infrastructure delivers elastic scaling and consolidated model management. Retail chains operating 500-plus facility footprints in the United States prefer this mode for multi-location analytics where millisecond latency proves non-critical.
- Edge Computing:On-device processing eliminates network round-trips, achieving sub-50ms inference for time-sensitive applications. Manufacturing units across Shenzhen and Suzhou industrial corridors in China specify edge-first architectures for production line quality control.
- On-premises:Private data center deployment satisfies data sovereignty requirements for regulated environments.
- Hybrid:Tiered architectures route preliminary filtering to edge nodes and complex analysis to cloud backends.
- Mobile Platforms:Smartphone and tablet-embedded vision enables consumer augmented reality and field service documentation.
Cloud-based retains revenue concentration. Edge Computing is gaining share fastest as manufacturing automation accelerates.
End User:
Customer type shapes specification requirements from sensor resolution to certification burden and integration complexity.
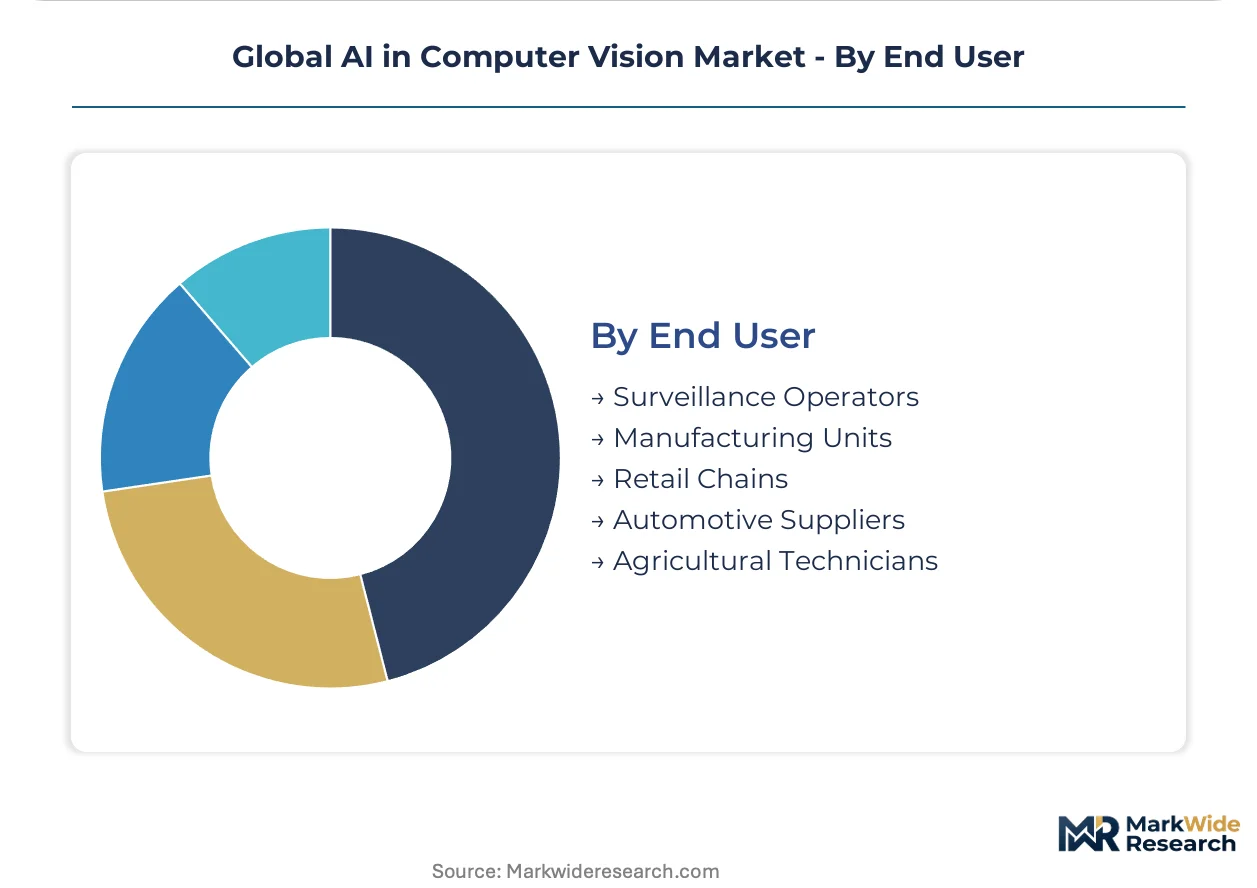
- Automotive Suppliers:Tier-1 and Tier-2 component manufacturers integrate vision systems for advanced driver assistance and autonomous driving platforms. Suppliers in Germany and the United States drive specification intensity around high-resolution CMOS and event-camera modules for navigation and cabin monitoring.
- Surveillance Operators:Municipal authorities and private security providers deploy biometric and behavioral analysis across public infrastructure. Operators in France and Germany navigate EU AI Act risk classifications that mandate third-party auditing and technical documentation.
- Manufacturing Units:Industrial facilities apply defect detection and robotic guidance for quality assurance and automation.
- Retail Chains:Multi-location merchants deploy footfall analytics and shelf monitoring for inventory and customer experience optimization.
- Agricultural Technicians:Precision farming operations utilize drone-mounted and tractor-embedded vision for crop monitoring and yield estimation.
Manufacturing Units command specification authority. Automotive Suppliers is expanding most quickly as autonomous vehicle development intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements for diagnostic imaging software shape vendor commercialization timelines across the United States, while the EU AI Act's conformity framework redirects procurement specifications for biometric systems throughout European surveillance and automotive sectors.
United States
Automotive Tier-1 suppliers and retail chains operating 500-plus facility footprints drive cloud-native vision analytics procurement. FDA Class II and III device pathways for AI-enabled diagnostic imaging extend product development cycles by 18-24 months. Greater Boston and Silicon Valley clusters concentrate healthcare AI validation labs and edge hardware startups.
China
National AI computing centers and intelligent manufacturing zones across Shenzhen, Suzhou, and Chongqing industrial corridors generate captive demand for industrial inspection systems. SAMR and MIIT enforce algorithmic transparency and data security standards that elevate compliance costs for foreign vendors. Yangtze River Delta and Pearl River Delta manufacturing belts anchor domestic platform provider expansion.
Germany
Automotive suppliers specify high-resolution CMOS and event-camera modules for advanced driver assistance platforms. KBA and EU AI Act risk classifications mandate third-party auditing and technical documentation for biometric identification deployments. Bavaria and Baden-Württemberg host concentrated automotive vision R&D and Tier-1 supplier headquarters.
France
Airport authorities and municipal surveillance operators navigate EU AI Act high-risk categorization for biometric systems. ANSM and CNIL oversight shapes data sovereignty requirements for healthcare and public sector vision deployments. Île-de-France and Provence-Alpes-Côte d'Azur concentrate critical infrastructure operators specifying on-premise deployment architectures.
Saudi Arabia
NEOM and Red Sea giga-project construction generates greenfield demand for construction-site safety monitoring and perimeter surveillance without legacy integration burden. SFDA emerging frameworks for medical device AI create early-mover certification opportunities. Riyadh and the Eastern Province anchor smart city vision system procurement at scale.
Global AI in Computer Vision Market Competitive Landscape
Cloud hyperscalers and specialized silicon vendors split the market along the latency-versus-scalability frontier. The vendor base concentrates around three strategic archetypes: CUDA-anchored GPU computing specialists, OpenVINO-tooling edge optimization providers, and API-integrated cloud service platforms. Competitive moves center on neuromorphic sensor partnerships and automated model compression toolchains.
Within the silicon-specialist tier, NVIDIA Corporation and Intel Corporation exemplify divergent architectural bets on training versus inference optimization. Microsoft Corporation occupies a position bridging cloud-native API delivery with enterprise data pipeline integration. These three entities anchor the competitive tension between centralized model management and millisecond-latency edge deployment that structures procurement decisions across automotive, manufacturing, and surveillance verticals.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| Intel Corporation |
| Google LLC |
| Amazon Web Services |
| IBM Corporation |
| Cognex Corporation |
| Teledyne Technologies |
| Qualcomm Technologies |
| Others |
Supply & Pricing Matrix
TSMC's Taiwan-based advanced foundry capacity anchors GPU supply for vision model training, concentrating pricing power with silicon vendors while compressing margins for downstream system integrators competing on deployment efficiency.
Pricing Analysis
Geographic price spreads of 15-25% separate North American from Asia-Pacific procurement for equivalent edge hardware specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by inference latency and certification grade, with FDA Class II medical device tiers commanding substantial premiums. Pricing pressure stems from hyperscaler cloud-native API competition eroding perpetual-license margins. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to safety-critical specifications, while retail chains operating multi-location footprints drive hardest bargain on per-camera analytics costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for CMOS sensor and GPU module procurement. Taiwan, South Korea, and the United States anchor advanced semiconductor fabrication, while specialized event-camera production concentrates in Japan and Germany. Raw material dependencies on high-purity silicon wafers, rare-earth dopants, and advanced packaging substrates create single-source vulnerability at multiple tiers. Distribution runs through direct OEM partnerships for automotive and medical verticals, with value-added resellers serving mid-market manufacturing and surveillance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in edge-first deployment architectures as latency requirements splinter procurement specifications across manufacturing corridors, creating protected niches for optimization specialists.
For Market Incumbents: Build switching-cost moats through embedded software toolchains that lock in manufacturing customers via proprietary quantization workflows and legacy PLC protocol gateways. Deepen backward integration into event-camera sensor supply to secure allocation priority during foundry constraints. Defensive priority centers on neutralizing neuromorphic camera startups through exclusive distribution partnerships with automotive battery cell producers.
For New Entrants and Emerging Players: Establish a beachhead in Saudi Arabian giga-project construction safety monitoring where greenfield deployment eliminates legacy integration barriers. Target explainable AI compliance tooling for China's SAMR algorithmic transparency enforcement, where foreign vendor restrictions create protected demand for localized solutions. Go-to-market angle emphasizes subscription-based vision analytics with elastic scaling terms that align opex with project milestone payments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across transformer-optimized edge silicon sub-segments as attention-mechanism architectures demand specialized inference hardware. Long-term viability favors vertically integrated specialists combining sensor hardware with on-device optimization toolchains over pure-software API providers facing hyperscaler commoditization. Acquisition target archetype: neuromorphic camera vendors with pilot deployments at semiconductor wafer fabs. Signal to watch: EU AI Act third-party auditor certification backlogs as indicator of compliance infrastructure scarcity premium.
| Strategic Initiative | Industry Significance |
|---|---|
| Neuromorphic Sensor Partnership | Event-camera integration secures microsecond-latency positioning in battery cell inspection lines at Tesla and CATL facilities. |
| Automated Model Compression Toolchain | Quantization-as-a-service reduces ARM edge deployment cycles for Siemens S7 manufacturing environments. |
| EU AI Act Conformity Infrastructure | Third-party auditing capability unlocks high-risk biometric procurement at Frankfurt Airport and SNCF perimeter systems. |
| Hybrid Cloud-Edge Architecture | Tiered inference routing captures retail chain demand for centralized model management with sub-50ms local response. |
| SAMR Compliance Localization | Domestic algorithmic transparency tooling captures protected share in Shenzhen and Suzhou intelligent manufacturing zones. |
Research Methodology
Operator-level perspectives from automotive Tier-1 procurement officers, manufacturing automation engineers, surveillance system integrators, and cloud platform solution architects anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings of NVIDIA and Intel, hyperscaler AI service capex disclosures, FDA 510(k) premarket notification databases, and EU AI Act implementation guidance documents. Bottom-up demand modeling across deployment modes and end-use verticals triangulated against top-down technology spend estimates from national AI computing center build-outs.
Scenario-bracketing around GPU supply allocation constraints and regulatory timeline divergence shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, deployment mode, end-use vertical, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement cycle acceleration from EU AI Act mandates, and content-per-vehicle trajectories in autonomous driving platforms. Industry-specific inputs incorporated event-camera pilot deployment scales and transformer model parameter growth curves.
Sensitivities concentrate around TSMC foundry allocation disruptions, FDA premarket notification timeline extensions for diagnostic imaging AI, and divergent EU-China-US regulatory enforcement calendars. Forecasts reflect assumptions on edge hardware cost curves and cloud API pricing elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Middle East and Africa Image Sensors Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Industrial Camera Market
Imaging
Global Ingaas Camera Market
Imaging
APAC Image Sensors Market
Imaging
Camcorder Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
CCD Image Sensors Market
Imaging
Specific Imaging Solution Market
Imaging
TDI Camera Market
Imaging
Global 3D Imaging Market
Imaging
Camera with Flip Screen Market
Imaging
Digital Movie Cameras Market
Imaging
Global Waterproof Camera Market
Imaging
Global Label-Free Array Systems Market
Imaging
Micro Computed Tomography Market