
 Europe IP Camera Market | 2026-2036
Europe IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IP Camera Market Insights
Modular camera configurations with edge-analytics software bundles is pivoting how European security directors evaluate total cost of ownership. Axis Communications AB leverages its Swedish R&D base to sustain firmware development for GDPR-compliant facial redaction. Bosch Security Systems GmbH anchors German industrial site deployments with explosion-protected dome variants. Hanwha Vision Co., Ltd. competes through AI chipset integration that differentiates its PTZ lineup from commodity hardware.
Europe IP Camera denotes a network-connected digital video capture device transmitting encrypted data packets over TCP/IP infrastructure, typically encoding H.265 streams at resolutions from 2MP to 8MP for remote monitoring and forensic analysis. Dome cameras dominate European retail banking branches where discrete form factors merge with vandal-resistant housings. The transportation application segment generates premium margins as rail operators in France and Germany mandate real-time crowd analytics. Wireless technology adoption accelerates in historic European city centers where cabling restrictions preserve architectural heritage.
GDPR enforcement by national data protection authorities across EU member states mandates explicit consent frameworks for biometric data collection, compressing deployment timelines for non-compliant legacy systems. The EU AI Act's prohibited-practices list for real-time remote biometric identification in public spaces forces vendors to re-engineer analytics pipelines for law enforcement clients. ETSI cybersecurity standards for consumer IoT devices extend certification burdens to residential IP camera shipments. Stakeholders must weigh compliance investment against feature differentiation as regulatory fragmentation between EU directives and member-state implementations deepens.
Market Dynamics
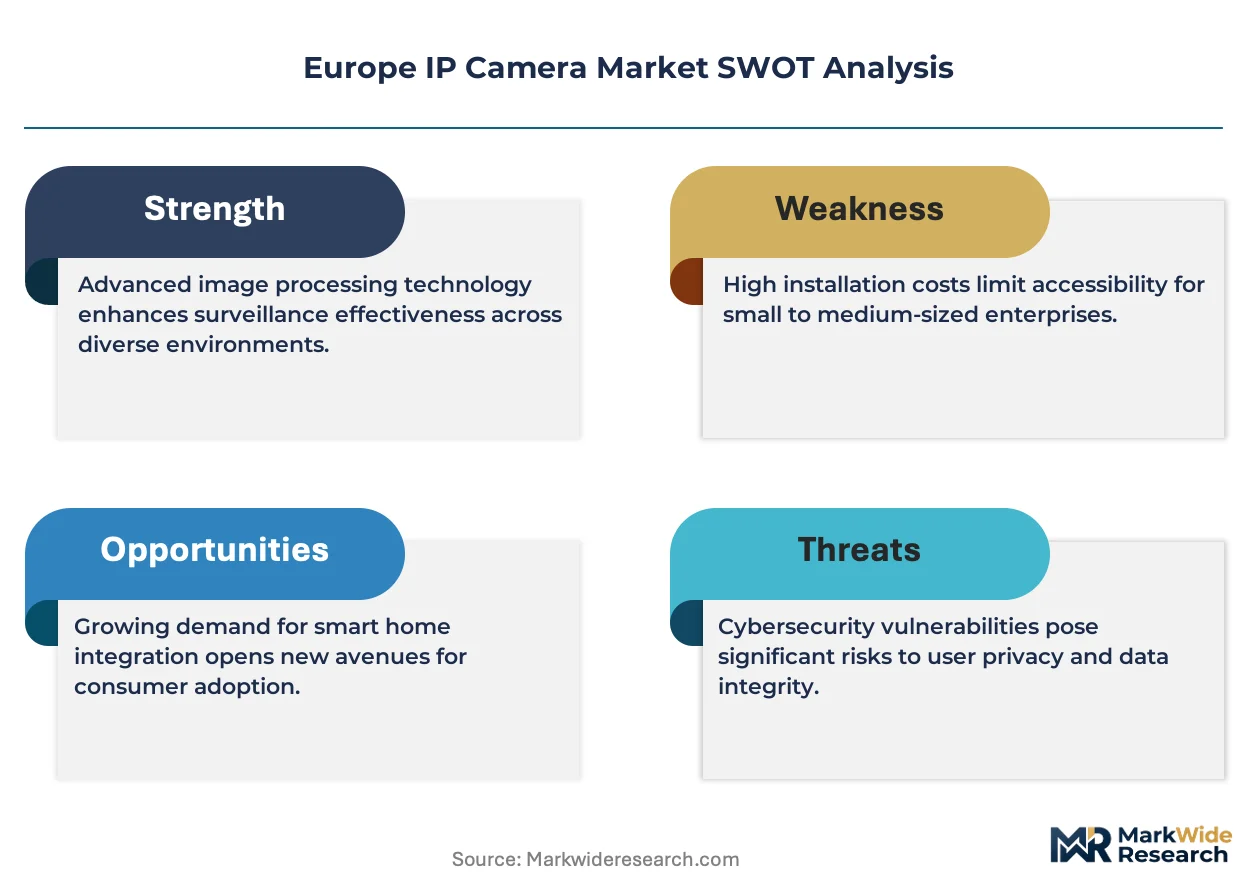
The EU AI Act's risk-tier classification for biometric surveillance is forcing European security vendors to re-engineer analytics pipelines and fragment product portfolios across compliance tiers.
Growth Catalysts
- Smart city infrastructure mandates:German municipal procurement programs for networked surveillance systems are accelerating deployments across transport hubs and public squares.
- GDPR-compliant edge analytics:Firmware-level facial redaction capabilities are unlocking law enforcement and retail banking segments previously blocked by consent requirements.
- Critical infrastructure protection:French energy facilities and rail operators are mandating high-resolution camera deployments with real-time crowd analytics.
Market Restraints
- Semiconductor supply concentration:AI chipset sourcing bottlenecks from East Asian foundries are compressing margins for European camera assemblers.
- ETSI certification burdens:Cybersecurity standards for consumer IoT devices are extending compliance timelines and testing costs for residential IP camera shipments.
- Wireless spectrum fragmentation:Historic city center cabling restrictions drive Wi-Fi/5G adoption, but national spectrum allocation differences complicate cross-border product standardization.
Strategic Opportunities
- Poland and Czech industrial corridors:Manufacturing site security upgrades present underpenetrated demand for explosion-protected dome variants.
- Healthcare facility integration:Convergence of video surveillance with patient monitoring systems is opening acute care and eldercare verticals.
- CSRD reporting alignment:Corporate sustainability disclosure requirements are creating procurement preference for vendors with documented supply chain carbon footprints.
Industry Challenges
- Embedded systems firmware talent:Scarce expertise in GDPR-compliant edge processing is elongating R&D cycles for mid-tier vendors.
- Legacy analog migration friction:Hybrid infrastructure requirements are complicating installation protocols and service margins for systems integrators.
- Cross-border data routing complexity:Member-state divergences in cloud footage storage regulations are fragmenting pan-European service architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IP Camera Market |
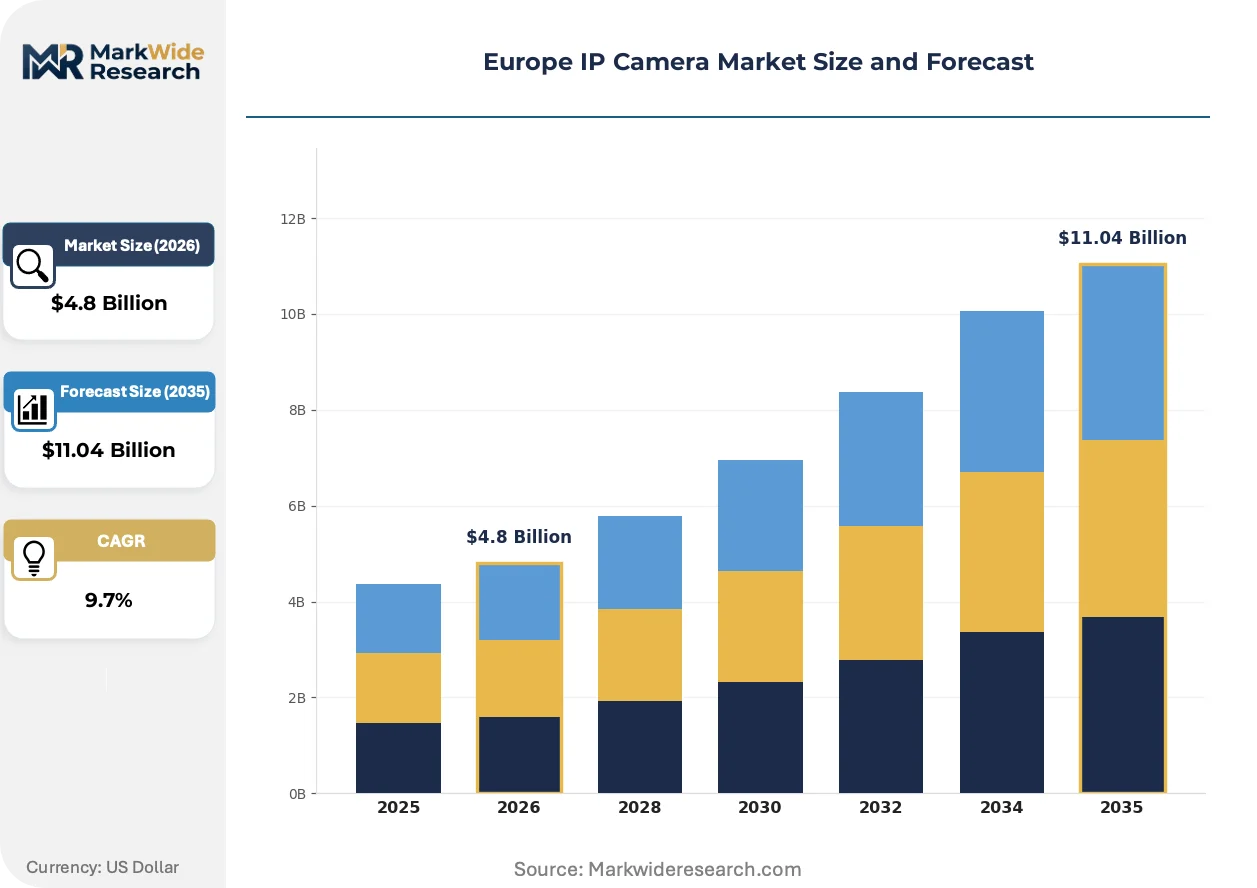
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Box Cameras Application: Retail, Transportation, Banking, Residential End User: Government, Commercial, Industrial, Healthcare Technology: Analog, Digital, Wireless, Hybrid |
| Companies Covered | Bosch Security Systems GmbH, Axis Communications AB, Hangzhou Hikvision Digital Technology Co., Ltd., Hanwha Vision Co., Ltd., Sony Corporation, Johnson Controls, Honeywell HBT, Dahua Technology, MOBOTIX AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IP Camera Market Trends and Innovations
Edge-native processing architectures are displacing centralized server dependency, while regulatory pressure on biometric data handling is reshaping how analytics capabilities are packaged and sold.
H.265+ codec optimization is expanding into forensic-grade storage applications across European transport operators. Rail networks in France and Germany are adopting these compression standards to extend retention periods without infrastructure expansion. This technology is expanding into smaller municipal deployments as storage cost differentials compress budget barriers for mid-sized security departments.
The EU AI Act's prohibited-practices list for real-time remote biometric identification in public spaces is forcing law enforcement-focused vendors to bifurcate product lines. Industrial consequence includes accelerated investment in post-event analytics that escape prohibition thresholds. French and German police procurement units are now requiring explicit compliance documentation for any facial recognition capability.
Security directors are unbundling hardware acquisition from software licensing and maintenance contracts. Large French retail banking groups now source cameras through procurement frameworks separate from video management platform decisions. This pattern is most visible in the Benelux region, where facility management outsourcing trends accelerate vendor-agnostic hardware standardization.
Europe IP Camera Market Segmentation
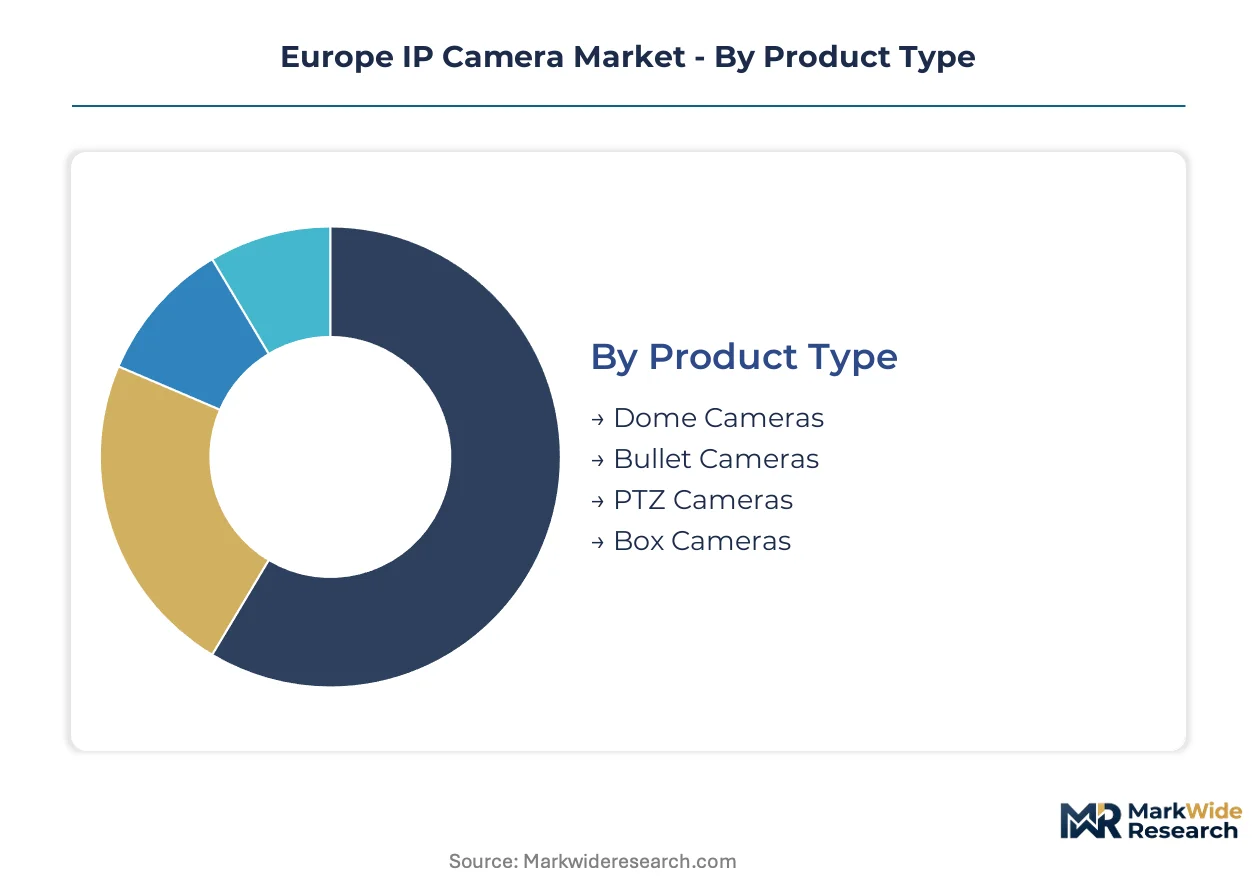
European procurement patterns diverge sharply across product form factors and deployment contexts. Security directors weight vandal resistance against discrete aesthetics, while regulatory pressure on biometric data handling fragments technology choices by end-use sensitivity.
Product Type:
Dome cameras command volume leadership through banking branch standardization, while PTZ variants capture premium pricing from transport analytics mandates.
- Dome Cameras:Vandal-resistant housings with discrete form factors suit retail banking lobbies and public transit platforms. French and German rail operators specify these for passenger-facing installations where aesthetic integration matters. GDPR-compliant firmware redaction capabilities are accelerating replacement cycles in consent-sensitive environments.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with AI chipset integration enable real-time crowd analytics at transport hubs. French energy facilities mandate these for perimeter monitoring where operator-controlled tracking replaces prohibited automated biometric identification. Edge-native processing architectures reduce bandwidth costs for remote industrial sites.
- Bullet Cameras:Weather-resistant cylindrical housings with fixed focal lengths dominate Polish and Czech manufacturing corridor deployments.
- Box Cameras:Modular lens-interchangeable designs serve forensic-grade applications requiring telephoto or wide-angle adaptability.
Today's leader: Dome Cameras. Tomorrow's challenger: PTZ Cameras.
Application:
Transportation commands margin premiums through real-time analytics requirements, while residential adoption accelerates on wireless retrofit demand.
- Transportation:Rail networks in France and Germany mandate H.265+ compression for extended footage retention without infrastructure expansion. Real-time crowd analytics capabilities attract premium pricing from operators managing safety compliance. The EU AI Act's prohibited-practices list forces explicit compliance documentation for any facial recognition deployment.
- Banking:Discrete dome configurations with firmware-level redaction unlock law enforcement cooperation previously blocked by consent requirements. Large French retail banking groups now unbundle hardware procurement from video management platform decisions.
- Retail:Loss prevention deployments concentrate in Benelux facility management outsourcing frameworks.
- Residential:ETSI cybersecurity certification burdens extend compliance timelines for consumer IoT shipments across member states.
Transportation claims steepest expansion trajectory. Banking offers defensive revenue stability.
End User:
Government procurement concentrates on compliance-heavy biometric surveillance, while healthcare convergence creates new vertical openings.
- Government:Smart city infrastructure mandates across German municipalities accelerate networked surveillance procurement for public squares. The EU AI Act's risk-tier classification fragments product portfolios across law enforcement compliance tiers. Explicit documentation requirements for facial recognition capabilities elongate sales cycles.
- Commercial:Corporate sustainability disclosure requirements under CSRD create procurement preference for vendors with documented supply chain carbon footprints.
- Industrial:Explosion-protected dome variants anchor German industrial site deployments with hazardous environment certifications.
- Healthcare:Video surveillance convergence with patient monitoring systems opens acute care and eldercare verticals previously isolated from security procurement.
Industrial segment deepens penetration fastest. Healthcare integration represents greenfield expansion.
Technology:
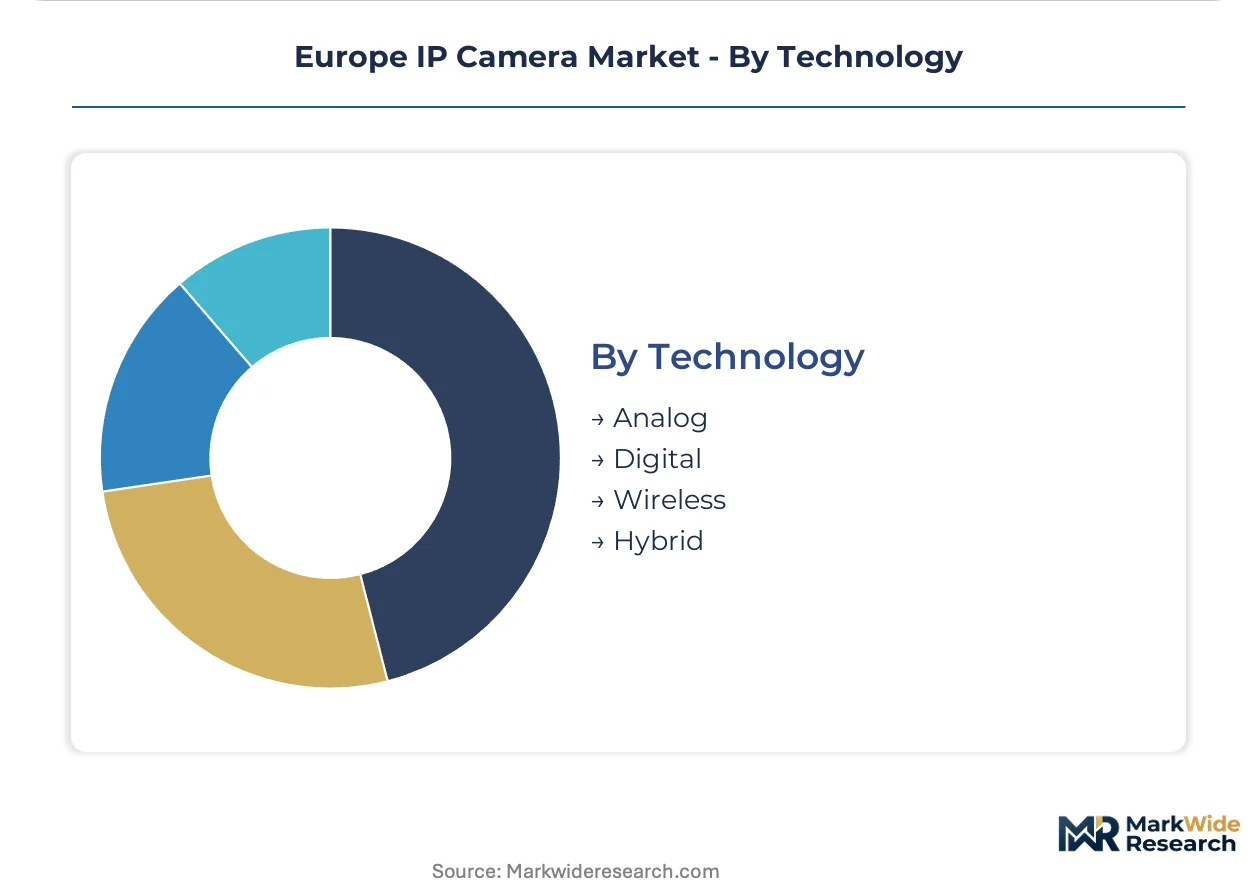
Digital encoding dominates new installations, while wireless adoption solves heritage preservation constraints in historic city centers.
- Digital:H.265 stream encoding at 2MP to 8MP resolutions enables forensic-grade remote monitoring and encrypted TCP/IP transmission. Edge-analytics software bundles are pivoting total cost of ownership evaluations among European security directors. Firmware development for GDPR-compliant facial redaction concentrates R&D investment.
- Wireless:Wi-Fi and 5G deployments accelerate where cabling restrictions preserve architectural heritage in historic European city centers. National spectrum allocation differences complicate cross-border product standardization for vendors.
- Analog:Legacy infrastructure persists in hybrid migration scenarios complicating installation protocols.
- Hybrid:Transitional architectures bridge analog retention with digital expansion for mid-tier municipal budgets.
Digital holds installed base dominance. Wireless is gaining share fastest on retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IP camera manufacturing scaled through Swedish engineering clusters before GDPR compliance requirements reshaped European vendor specialization. German industrial automation demand and French critical infrastructure protection now anchor regional procurement patterns.
Germany
Smart city infrastructure mandates accelerate municipal procurement of networked surveillance systems across transport hubs and public squares. The EU AI Act's risk-tier classification fragments product portfolios for law enforcement compliance. Bavaria's industrial corridor anchors explosion-protected dome deployments at manufacturing sites.
France
Critical infrastructure protection drives high-resolution camera deployments at energy facilities and rail networks. CNIL enforcement of GDPR biometric consent frameworks compresses deployment timelines for non-compliant legacy systems. The Île-de-France region concentrates transport operator demand for real-time crowd analytics.
United Kingdom
Retail banking branches standardize vandal-resistant dome configurations with firmware-level facial redaction. Post-Brexit regulatory divergence from EU AI Act timelines creates compliance uncertainty for biometric surveillance vendors. London's financial district leads unbundled hardware procurement separate from video management platforms.
Poland
Manufacturing site security upgrades present underpenetrated demand for explosion-protected variants across industrial corridors. ETSI cybersecurity certification burdens extend compliance timelines for consumer IoT shipments. The Silesian metropolitan area concentrates warehouse and logistics facility deployments.
Netherlands
Facility management outsourcing trends accelerate vendor-agnostic hardware standardization across Benelux retail networks. Historic city center cabling restrictions drive wireless adoption where architectural heritage preservation limits infrastructure. The Randstad urban cluster concentrates smart city pilot programs for edge-analytics integration.
Europe IP Camera Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and edge-analytics integration. The vendor base stratifies between GDPR-specialized European developers and scale-driven Asian manufacturers. Three archetypes dominate: firmware-compliance specialists, hazardous-environment engineers, and AI-chipset integrators. Portfolio diversification and strategic partnerships represent the dominant competitive moves as regulatory fragmentation deepens.
Within the firmware-compliance tier, Axis Communications AB and Bosch Security Systems GmbH exemplify European engineering anchorage. Hanwha Vision Co., Ltd. occupies a position among AI-chipset integrators competing through differentiated PTZ architectures. Hangzhou Hikvision Digital Technology Co., Ltd. and Dahua Technology represent scale-driven manufacturing depth from Chinese industrial bases.
| Leading Market Players |
|---|
| Bosch Security Systems GmbH |
| Axis Communications AB |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Hanwha Vision Co., Ltd. |
| Sony Corporation |
| Johnson Controls |
| Honeywell HBT |
| Dahua Technology |
| MOBOTIX AG |
| Others |
Pricing and Supply Chain Analysis
Backward integration into AI chipset design anchors both supply security and margin protection for European IP camera vendors navigating GDPR-compliant firmware development. This integration choice separates vendors who capture premium pricing through edge-analytics bundling from assemblers exposed to East Asian foundry bottlenecks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the European market by certification depth and analytics capability. Price differentiation rests on CE marking tier and firmware redaction sophistication, with premium tiers commanding multiples for EU AI Act-compliant biometric handling. Cost compression in the economy tier is intensifying because ETSI cybersecurity certification burdens extend testing timelines for residential shipments. Municipal procurement offices exhibit highest price sensitivity, while French critical infrastructure operators absorb premiums for real-time crowd analytics.
Supply Chain Analysis
Domestic-content mandates under EU procurement directives are reshaping sourcing patterns for public-sector deployments. Component sourcing draws from Taiwan and South Korea for AI chipsets, China for lens assemblies, and Germany for explosion-protected housings. Supply chain risk centers on single-source vulnerability for advanced image sensors from East Asian foundries. Distribution runs through systems integrators and security distributors with pan-European service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe IP Camera Market functions as a regulatory compounder where each compliance layer amplifies demand for certified solutions. The EU AI Act's prohibited-practices list for real-time biometric identification serves as the definitive demand catalyst across law enforcement and transport verticals.
For Market Incumbents: Anchor defensive positioning through captive firmware development capabilities that accelerate GDPR-compliant redaction cycles. Invest in German industrial site certifications for explosion-protected variants before Polish and Czech manufacturing corridors mature. Threat exposure concentrates in AI-chipset integrators from South Korea eroding PTZ premium tiers. For New Entrants and Emerging Players: The mid-tier price-point gap between Axis Communications AB premium positioning and Chinese economy imports offers white-space entry. Target Polish industrial security upgrades with explosion-protected dome variants before incumbent certification depth solidifies. Benelux facility management outsourcing frameworks provide the most penetrable channel for vendor-agnostic hardware standardization. For Investors and Strategic Acquirers: Roll-up economics work for GDPR-specialized firmware developers because member-state regulatory fragmentation prevents scale-player dominance. Five-to-ten year viability favors acquirers of edge-analytics engineering teams with CNIL and BfDI compliance track records. The inflection signal to watch is consolidation velocity among mid-tier municipal integrators losing margin to hybrid analog-digital migration friction.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR-Compliant Firmware Development | BfDI enforcement in Germany accelerates replacement cycles for legacy biometric systems. |
| Explosion-Protected Certification | Bavarian industrial corridors mandate hazardous-environment housing for manufacturing site deployments. |
| Edge-Native Processing Architecture | Transport operators in Île-de-France reduce bandwidth costs through on-device analytics. |
| Wireless Retrofit Solutions | Randstad historic center cabling restrictions drive Wi-Fi adoption where heritage preservation limits infrastructure. |
| CSRD Supply Chain Disclosure | Corporate sustainability reporting creates procurement preference for documented carbon footprint vendors. |
Research Methodology
Multiple input streams — security director interviews, systems integrator field assessments, regulatory filing analysis, and component supply chain mapping — were reconciled to construct segment-level demand estimates. Primary conversations engaged municipal procurement officers, critical infrastructure security managers, video management platform developers, and ETSI certification consultants. Secondary validation drew from EU AI Act implementation guidance, CNIL enforcement bulletins, German municipal procurement databases, and customs records for camera component trade flows. Bottom-up deployment tracking and top-down market sizing were cross-referenced for convergence.
Historical shipment patterns were cross-referenced against panel input from security integrators to model adoption curves across the projection horizon. Segmentation dimensions included product form factor, application vertical, end-user category, and technology architecture. CAGRs were derived from regression analysis of procurement cycle timing and regulatory compliance deadlines. Forecast inputs incorporated AI Act enforcement timelines and smart city infrastructure budget allocations.
The model assumes a particular technology adoption path; alternative pathways for wireless 5G deployment would alter the outlook if spectrum harmonization advances faster than baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and chipset supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision Camera Market
Imaging
Global Panoramic Camera Market
Imaging
Image Based Barcode Reader Market
Imaging
Electron Microscopy Market
Imaging
Digitizer Market
Imaging
IP Camera Market
Imaging
Global Computed Radiography Market
Imaging
Global Acoustic Cameras Market
Imaging
Uncooled Infrared Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Acoustic Microscopy Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Specific Imaging Solution Market
Imaging
IR and Thermal Imaging Systems Market