
 Ent Cameras Market | 2026-2036
Ent Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Ent Cameras Market Analytics
Hospital procurement of ENT visualization systems is tilting toward bundled service contracts that include maintenance, software updates, and training. Olympus Corporation leverages its endoscopy heritage to anchor premium digital imaging platforms in large academic medical centers. Karl Storz SE & Co. KG sustains dominance in rigid endoscope manufacturing through in-house production of optical components. Stryker Corporation competes by integrating camera systems with its broader surgical navigation portfolio.
ENT cameras are specialized medical imaging devices employing CMOS or CCD sensors, fiber optic light guides, and LED illumination to capture high-resolution visualization of the ear, nose, and throat anatomy for diagnostic examination and minimally invasive surgical intervention. The 4K product segment leads value generation as surgeons demand enhanced depth perception and tissue differentiation during complex procedures. CMOS technology is displacing CCD across mid-tier and premium systems due to lower power consumption, faster readout speeds, and superior low-light performance. Telemedicine application is expanding fastest among segments, propelled by remote consultation protocols and postoperative follow-up workflows in rural and underserved regions.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access pathways for ENT camera manufacturers. ISO 13485 quality management standards govern manufacturing processes, while IEC 60601-1 electrical safety specifications constrain design architectures. Stakeholders must monitor evolving reimbursement codes for office-based endoscopic procedures, as coverage determinations directly influence capital equipment purchasing decisions by clinics and private practices.
Market Dynamics
CMOS sensor technology is compressing product development cycles while EU MDR documentation requirements extend regulatory timelines, creating tension between innovation velocity and compliance burden for ENT camera manufacturers.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:Expanding patient populations requiring otolaryngology procedures drive replacement demand for visualization systems in hospital settings.
- ISO 13485 quality management certification:Standardized manufacturing protocols enable cross-border market access and reduce duplicate compliance costs for multi-regional suppliers.
- LED illumination modules:Superior energy efficiency and color rendering index performance compared to halogen alternatives reduce operating costs in high-volume surgical centers.
Market Restraints
- Optical glass supply concentration:German and Japanese specialty glass manufacturers control critical raw material inputs for rigid endoscope lenses, exposing producers to single-source risk.
- FDA 510(k) clearance timelines:Extended review periods for predicate device comparisons delay product launches and compress effective patent protection windows.
- CMOS sensor foundry capacity:Concentrated semiconductor fabrication in Taiwan and South Korea creates bottlenecks for mid-tier camera system production scaling.
Strategic Opportunities
- Rural telemedicine protocols in the United States:Remote consultation reimbursement codes create addressable demand for portable ENT camera systems with cloud connectivity.
- EU Green Deal circular economy requirements:Mandates for medical device recyclability favor modular camera designs with replaceable components over sealed units.
- Artificial intelligence integration:Convergence of real-time image analysis with 4K visualization enables automated polyp detection and surgical guidance features.
Industry Challenges
- Biomedical optics engineering talent:Scarce expertise in miniature lens design and fiber optic coupling constrains R&D throughput for specialized manufacturers.
- Legacy endoscope compatibility:Hospital capital equipment refresh cycles lag camera technology advancement, forcing backward-compatible interface development.
- EU MDR technical documentation:Expanded clinical evidence requirements for Class IIa devices strain regulatory affairs capacity and extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ent Cameras Market |
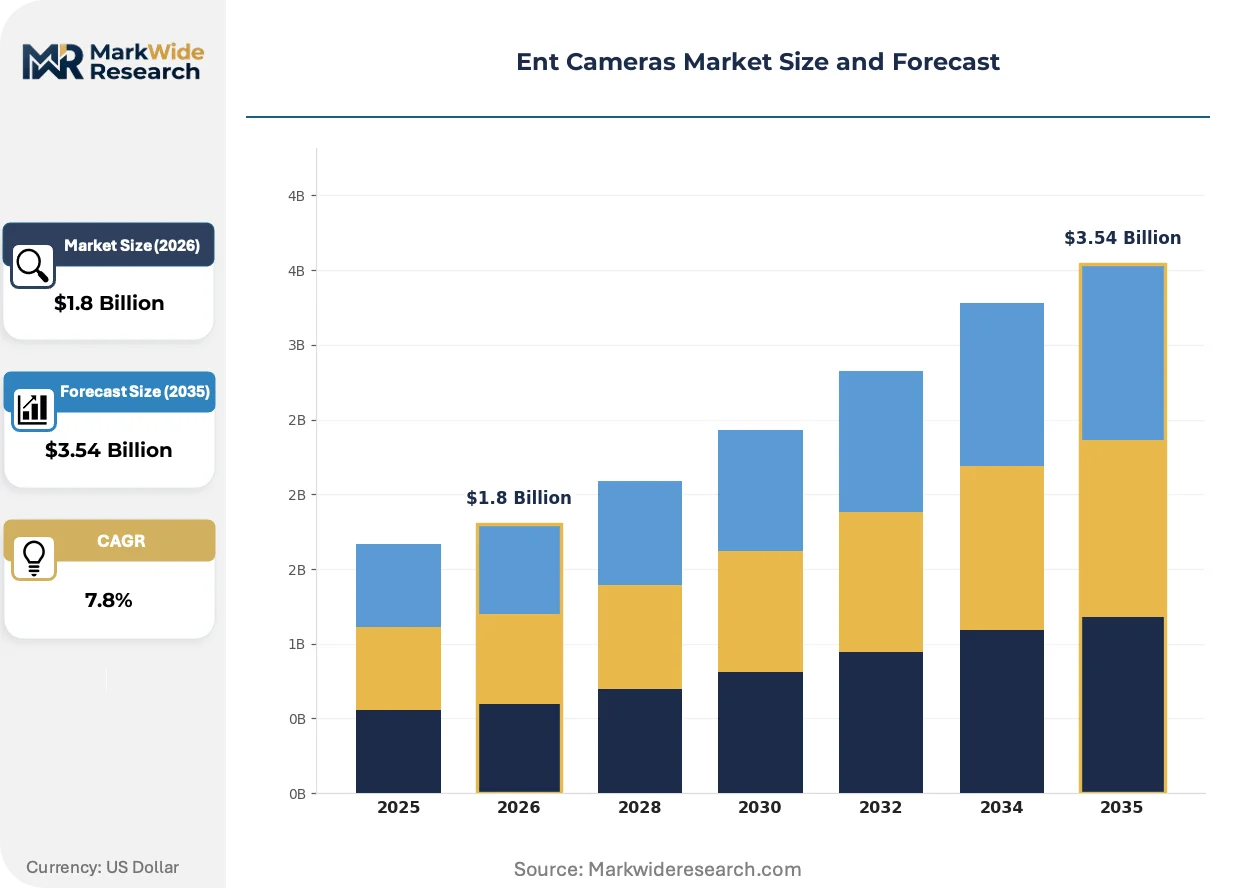
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, HD, 4K, Medical Application: Endoscopy, Otoscopy, Rhinology, Telemedicine Technology: Light Emitting Diodes, Fiber Optics, CMOS, CCD End User: Hospitals, Clinics, Ambulatory Surgery Centers, Private Practices |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Stryker Corporation, FUJIFILM Corporation, Boston Scientific Corporation, Medtronic, HOYA Corporation, Ambu A/S, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ent Cameras Market Evolving Landscape
Digital imaging pipelines are reconfiguring ENT visualization from standalone hardware into software-defined platforms, altering value capture toward recurring revenue models and remote service delivery.
CMOS sensor architecture is hybridizing with computational imaging algorithms to deliver real-time noise reduction and dynamic range expansion without hardware modification. Academic medical centers in the United States and Japan are piloting these systems for complex skull base procedures. The convergence is compressing upgrade cycles from equipment replacement to firmware deployment, shifting supplier economics toward subscription structures.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for approved ENT camera systems. Manufacturers must now maintain vigilance systems tracking device performance across installed bases. High-volume ambulatory surgery centers face the steepest compliance burden, driving consolidation toward suppliers with dedicated regulatory infrastructure.
Service contract unbundling is fragmenting traditional capital equipment purchasing into componentized arrangements for hardware, software, maintenance, and training. Large hospital systems in Germany and the United States are negotiating modular agreements that separate imaging platform acquisition from image management software licensing. The pattern concentrates negotiating leverage with procurement departments while eroding bundled margin structures for incumbent suppliers.
Ent Cameras Market Segmentation
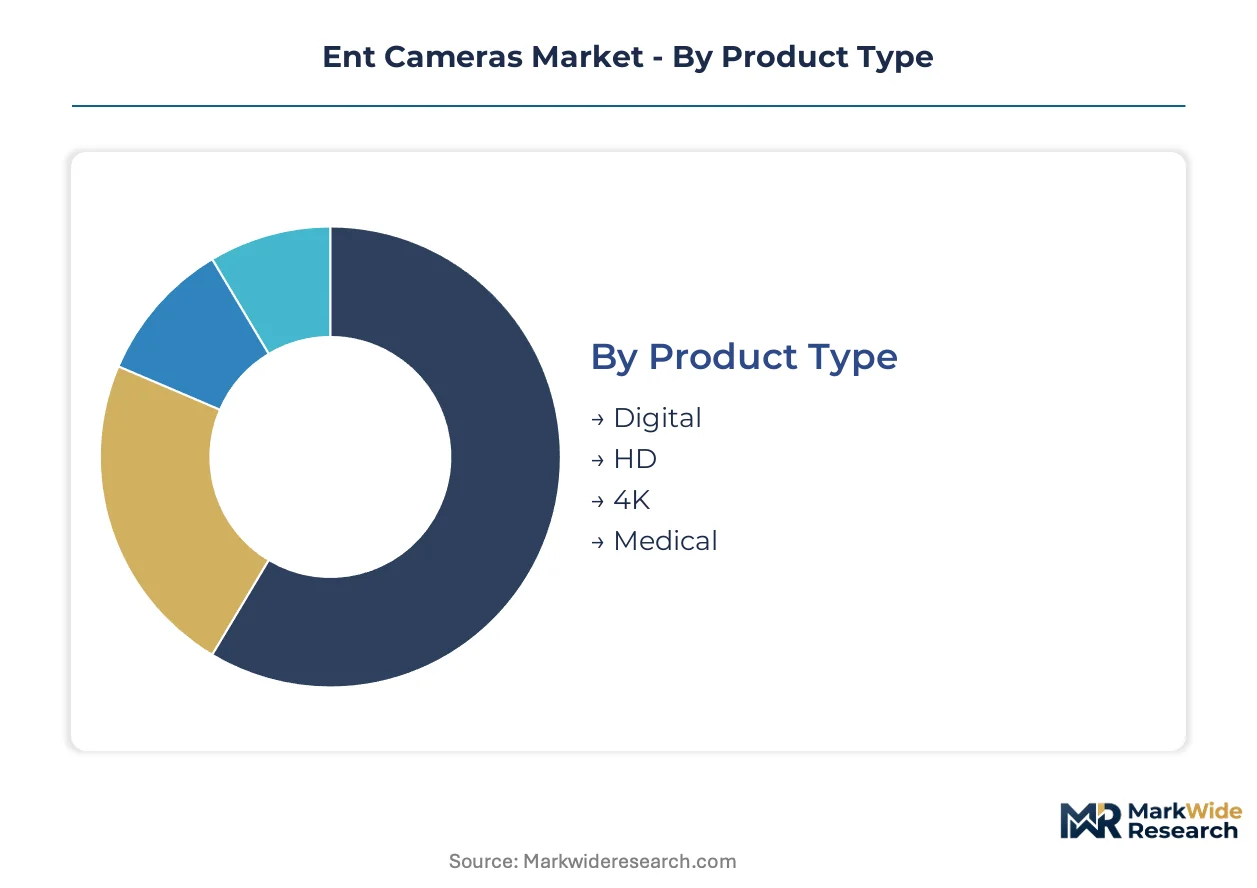
ENT camera segmentation reflects divergent clinical workflows across diagnostic screening, surgical intervention, and remote consultation. Procurement patterns vary sharply between capital-intensive hospital systems and volume-driven ambulatory settings, creating distinct performance requirements for each segment.
Product Type:
The use-case spectrum spans routine examination to complex surgical navigation, with resolution requirements scaling to procedure complexity.
- 4K:Ultra-high-definition imaging platforms deliver enhanced depth perception and tissue differentiation for skull base and sinus surgery. Large academic medical centers in the United States and Japan anchor demand as surgeons prioritize visualization precision over capital cost.
- HD:High-definition systems balance image quality with cost efficiency for general otolaryngology procedures. Clinics and private practices in Germany concentrate procurement here, constrained by reimbursement limitations on capital equipment.
- Digital:Software-defined imaging pipelines enable firmware upgrades without hardware replacement. Early adoption concentrates in integrated delivery networks negotiating modular service contracts.
- Medical:General-purpose ENT cameras meet baseline diagnostic requirements for primary care and rural health settings. Cost sensitivity drives procurement in developing markets and budget-constrained facilities.
Established volume favors HD; emerging adoption favors 4K.
Application:
Procedure-specific imaging demands shape sensor specifications, illumination intensity, and ergonomic design priorities.
- Telemedicine:Portable ENT cameras with cloud connectivity enable remote consultation and postoperative follow-up. Rural health networks in the United States expand fastest here, propelled by reimbursement code expansions for virtual care.
- Endoscopy:Flexible and rigid endoscopic visualization supports diagnostic examination and minimally invasive surgical access. Hospital systems in Japan and Germany sustain replacement cycles as procedure volumes rise with aging demographics.
- Otoscopy:Ear canal examination requires compact probe design and adjustable focal depth. Pediatric clinics and primary care integration drive volume.
- Rhinology:Nasal cavity and sinus visualization demands angled optics and high-flow irrigation compatibility. Academic centers anchor premium system deployment.
Endoscopy captures the largest installed base; telemedicine climbs the fastest.
Technology:
Sensor architecture and illumination engineering determine power consumption, heat generation, and color fidelity in confined anatomical spaces.
- CMOS:Complementary metal-oxide-semiconductor sensors deliver lower power draw, faster readout speeds, and superior low-light performance versus legacy alternatives. Mid-tier and premium system manufacturers in Taiwan and South Korea prioritize CMOS for next-generation platforms.
- CCD:Charge-coupled device technology persists in legacy installations and cost-optimized product lines. Replacement demand concentrates in developing markets with extended equipment refresh cycles.
- Light Emitting Diodes:LED illumination modules reduce energy consumption and heat output compared to halogen predecessors. Ambulatory surgery centers prioritize LED for high-volume procedural throughput.
- Fiber Optics:Fiber optic light guides enable compact distal tip design for rigid endoscopes. German and Japanese specialty glass manufacturers control critical supply inputs.
CCD retains legacy installed base; CMOS gains share fastest in new deployments.
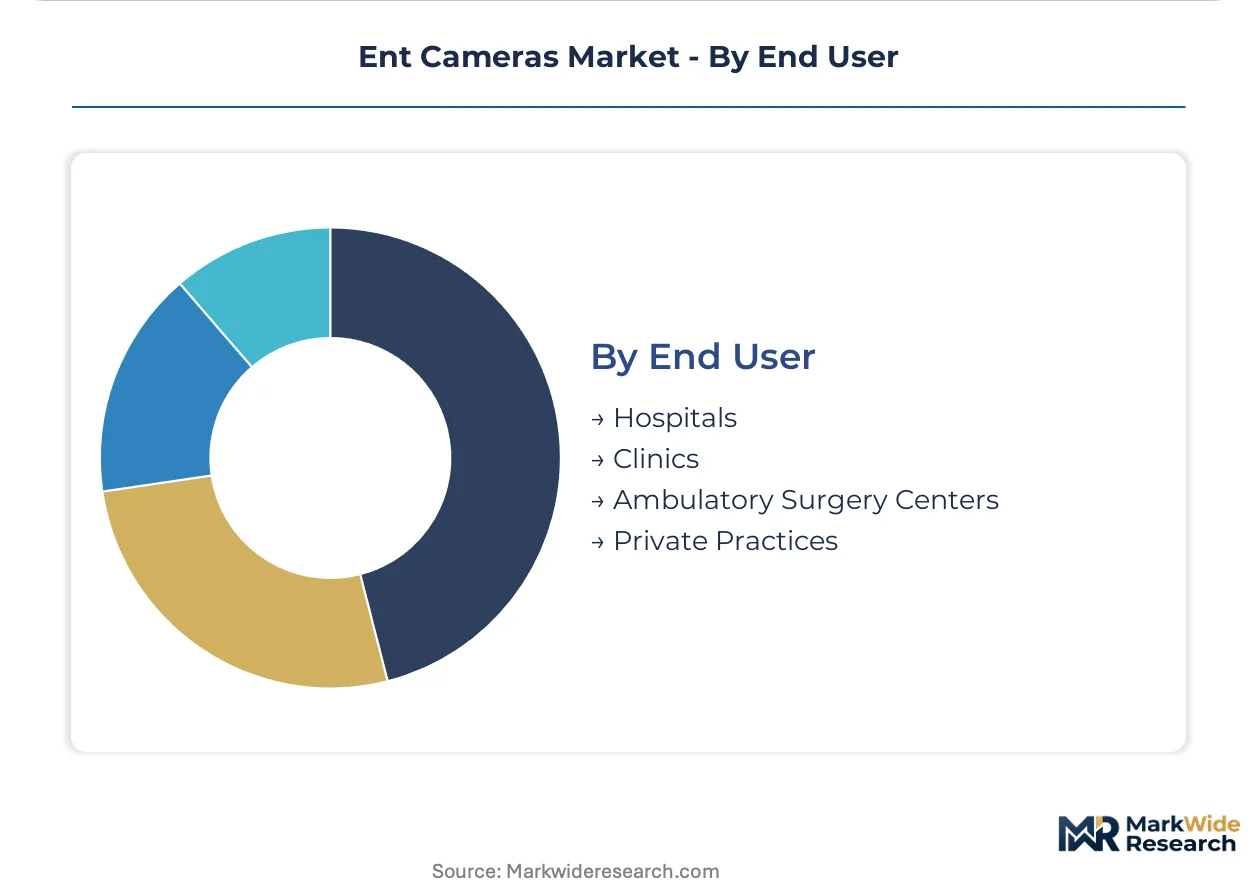
End User:
Capital availability and procedure volume create distinct purchasing patterns across facility types.
- Hospitals:Large health systems negotiate bundled contracts spanning hardware, software, maintenance, and training. Academic medical centers in the United States and Japan anchor premium 4K system adoption.
- Ambulatory Surgery Centers:High-volume outpatient facilities prioritize throughput efficiency and rapid turnover. Cost optimization and service contract unbundling reshape procurement here.
- Clinics:Community-based otolaryngology practices balance diagnostic capability with capital constraints. HD systems dominate with selective 4K upgrade paths.
- Private Practices:Solo and small-group physicians face reimbursement pressure on office-based procedures. Portable and telemedicine-compatible systems expand addressability.
Hospitals concentrate premium revenue; ambulatory surgery centers drive volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical technology logistics corridor underwrites Germany's central role in European ENT camera distribution, connecting Rhineland manufacturing clusters to Nordic hospital systems.
United States
Academic medical centers in Boston and Baltimore drive 4K system replacement cycles as skull base procedure volumes expand. FDA 510(k) clearance pathways shape product launch sequencing for manufacturers targeting hospital procurement cycles. The Research Triangle Park corridor in North Carolina concentrates regulatory affairs and clinical trial infrastructure for visualization device developers.
Germany
Tübingen and Berlin anchor rigid endoscope manufacturing through captive optical glass processing capabilities. EU MDR technical documentation requirements extend market access timelines for Class IIa visualization devices. The Mittelstand industrial belt around Stuttgart sustains precision machining supply chains for endoscope mechanical components.
Japan
Tokyo and Osaka metropolitan hospitals prioritize CMOS-based systems for low-light surgical performance in aging otolaryngology patient populations. PMDA consultation procedures govern software-as-medical-device classifications for AI-integrated imaging platforms. The Nagoya medical device cluster concentrates LED illumination module assembly for regional camera system suppliers.
South Korea
Seoul Capital Area health systems adopt telemedicine-compatible ENT cameras for rural network connectivity. MFDS quality system registration requirements align with ISO 13485 standards for export-oriented manufacturers. The Pangyo Techno Valley hosts digital imaging algorithm development for next-generation visualization software.
India
Maharashtra and Karnataka state hospitals expand diagnostic endoscopy capacity through government health scheme procurement. CDSCO medical device registration rules now require local authorized representation for imported visualization systems. The Hyderabad medical technology corridor attracts contract manufacturing for mid-tier camera assembly serving South Asian markets.
Ent Cameras Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in optical glass and sensor fabrication. Market structure consolidates around diversified medical technology conglomerates with endoscopy heritage, while mid-tier specialists occupy niche ergonomic and illumination subsystems. Two archetypes dominate: diversified conglomerates leveraging installed base lock-in, and focused endoscope specialists defending optical component margins. Competitive moves concentrate on service contract bundling and backward integration into LED illumination modules.
Within the diversified conglomerate tier, Olympus Corporation and Stryker Corporation exemplify platform strategies that couple hardware acquisition to recurring software and maintenance revenue. Karl Storz SE & Co. KG anchors the specialist archetype through in-house optical component production. These three represent the structural tension between scale-driven bundling and craftsmanship-focused component control.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| FUJIFILM Corporation |
| Boston Scientific Corporation |
| Medtronic |
| HOYA Corporation |
| Ambu A/S |
| Richard Wolf GmbH |
| Others |
Value Network & Pricing Analysis
CMOS sensor foundry undercapacity in Taiwan is compressing lead times for mid-tier camera system manufacturers while simultaneously hardening price discipline among premium 4K platform suppliers serving academic medical centers.
Pricing Analysis
Volume-discount tiering separates academic medical center procurement from ambulatory surgery center purchasing, with the former commanding 15-25% price reductions on bundled service contracts. Pricing stratifies across premium 4K systems, standard HD platforms, and economy digital cameras based on resolution certification and after-sales service bundling. Cost compression in the HD tier intensifies as reimbursement constraints tighten clinic capital budgets. Ambulatory surgery centers exhibit the highest price sensitivity, while large hospital systems prioritize performance specifications over unit economics.
Supply Chain Analysis
Extended payment terms from German and Japanese optical glass suppliers are filtering downstream to camera system assemblers, compressing working capital cycles for mid-tier manufacturers. Supply concentrates in Germany for specialty optical glass, Taiwan and South Korea for CMOS sensors, and Japan for LED illumination modules. Raw material dependencies include borosilicate glass rods, semiconductor wafers, and rare-earth phosphors. Single-source vulnerability in German optical glass exposes producers to supply interruption. Distribution runs through hospital GPO contracts and direct manufacturer sales forces serving academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ENT camera market functions as a service-attach opportunity where software licensing and preventive maintenance contracts expand faster than hardware replacement cycles, particularly in integrated delivery networks negotiating modular agreements.
For Market Incumbents: Harden installed base lock-in by embedding AI-powered image analysis into firmware subscription tiers, preventing displacement by lower-cost CMOS-based challengers. Deepen backward integration into LED illumination module production to defend margin position against component cost volatility. Prioritize regulatory affairs capacity expansion to navigate EU MDR post-market surveillance requirements without service disruption.
For New Entrants and Emerging Players: Rural telemedicine networks in the United States represent the most penetrable entry point, as reimbursement code expansion for remote consultation creates demand for portable, cloud-connected systems underserved by incumbent bundling strategies. Target ambulatory surgery centers in South Korea seeking cost-optimized CMOS platforms with unbundled service arrangements. Pursue white-label manufacturing partnerships with regional distributors lacking in-house visualization engineering.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined imaging pipelines as firmware upgrade cycles displace hardware replacement revenue. Long-term viability favors platform integrators with recurring revenue attachment above 40% of total contract value. Acquisition targets should display dedicated regulatory infrastructure for EU MDR compliance. The signal to watch is hospital procurement department consolidation of imaging platform decisions under centralized IT governance.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Embedded AI analysis in 4K platforms enables automated polyp detection for skull base surgeons at Johns Hopkins and Mayo Clinic networks. |
| CE Marking Pathway | EU MDR technical documentation for Class IIa devices requires systematic clinical evidence collection extending market access timelines. |
| Hospital System Partnership | Bundled contracts with Kaiser Permanente and Intermountain Healthcare concentrate purchasing leverage and lock in multi-year service revenue. |
| Backward Integration into LED Modules | In-house production of illumination components reduces dependency on Nagoya-based suppliers and captures margin from energy-efficient surgical lighting. |
| Reimbursement Strategy | Coverage determination advocacy for office-based endoscopic procedures directly influences capital equipment purchasing by private otolaryngology practices. |
Research Methodology
The analysis maps 4K, HD, digital, and medical camera sub-sectors, each validated through hospital purchasing committee interviews, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at visualization device manufacturers. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS reimbursement code updates. Bottom-up unit economics triangulated against top-down market sizing across sensor technology, illumination engineering, and end-user facility types.
Assumptions held fixed include regulatory pathway timelines for FDA 510(k) and EU MDR Class IIa devices, while CMOS sensor foundry capacity utilization and telemedicine reimbursement expansion were modeled as scenario variables. Segmentation dimensions span resolution tier, application workflow, sensor architecture, and end-user capital availability. CAGRs derived from procedure volume elasticity to aging demographics and replacement cycle compression from software-defined upgrade paths. Forecast inputs incorporated otolaryngology workforce density and ambulatory surgery center construction permits.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, semiconductor fabrication capacity, or EU MDR enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about reimbursement stability and regulatory pathway predictability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Backscatter X-Ray Devices Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Handheld Imaging Devices Market
Imaging
Pico Projector Market
Imaging
Uncooled Infrared Camera Market
Imaging
High Dynamic Range Market
Imaging
Uncooled Infrared Imaging Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Asia Pacific IP Camera Market
Imaging
Industrial Camera Market
Imaging
Micro Computed Tomography Market
Imaging
Digital X-Ray Technology Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Asia Pacific Industrial Computed Tomography Market