
 Europe Industrial Computed Tomography Market | 2026-2036
Europe Industrial Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Computed Tomography Market Foresight
Carbon-fiber-reinforced polymer is rebalancing component economics across European aerospace supply chains as manufacturers seek weight reduction without sacrificing structural integrity. ZEISS Group leverages its metrology heritage to dominate high-resolution CT systems for turbine blade inspection. Werth sustains competitive position through specialized multi-sensor platforms that integrate tactile and optical measurement with CT capability. Baker Hughes Company anchors its European presence through energy-sector CT services for pipeline integrity and additive manufacturing qualification.
Europe Industrial Computed Tomography encompasses non-destructive testing systems utilizing X-ray radiation and digital detector arrays to generate cross-sectional volumetric images of industrial components, typically achieving spatial resolution from micrometers to sub-micrometer scales depending on source geometry and detector pixel pitch. These systems enable internal defect detection, dimensional measurement, and material characterization without specimen destruction, serving critical quality assurance functions across precision manufacturing. 3D CT systems command the dominant share of installed base value due to their versatility in complex geometry analysis, while Nano CT represents the fastest-expanding technology tier as semiconductor and medical device manufacturers push toward sub-micron feature inspection. Quality Control applications absorb the largest revenue pool among end-use categories, though Research & Development segments exhibit superior margin profiles due to customization requirements and longer sales cycles.
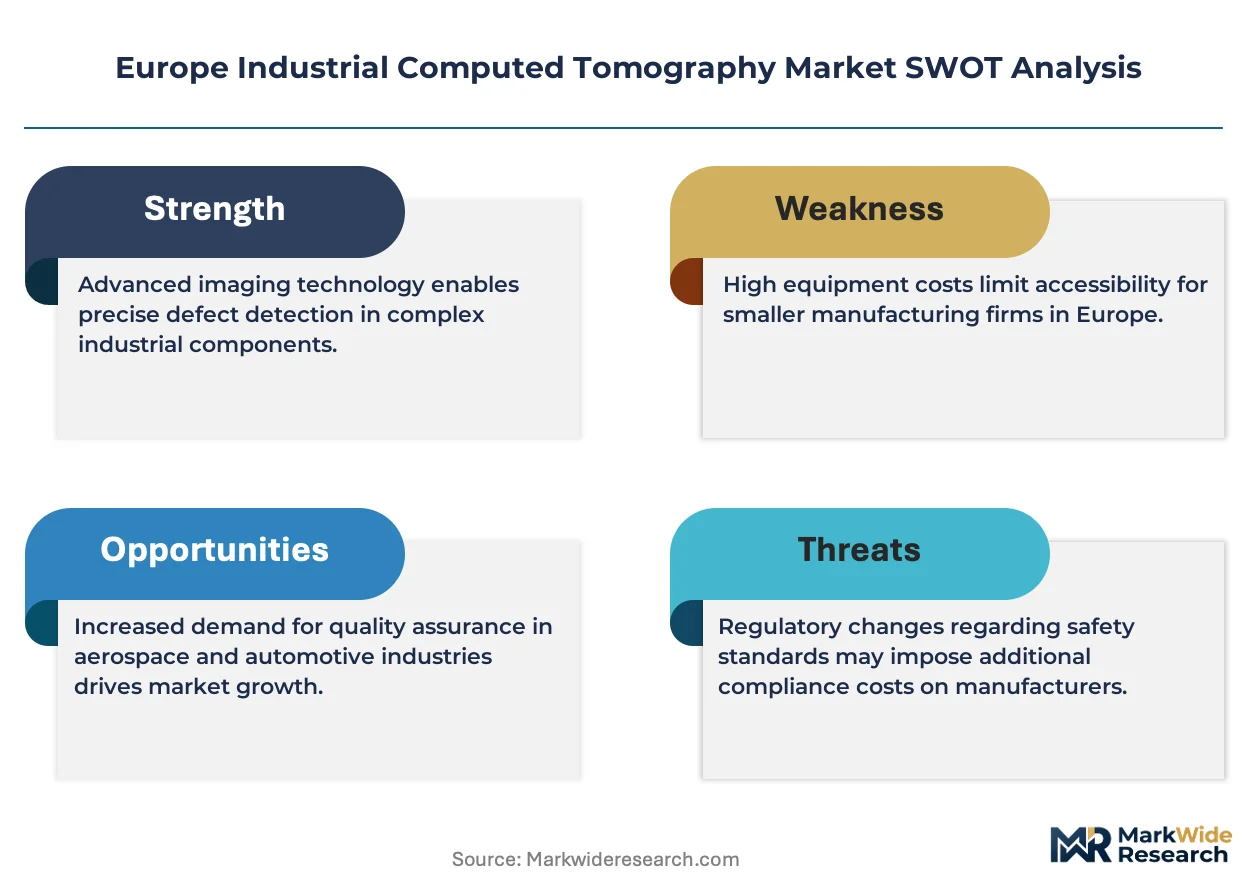
CE marking requirements under the EU Machinery Directive establish baseline safety and electromagnetic compatibility standards for CT system commercialization across member states, while REACH compliance obligations govern the handling and disposal of X-ray tube materials containing heavy metal constituents. Germany's KBA and France's ANSM enforce sector-specific inspection protocols that directly influence CT adoption thresholds in automotive and medical device manufacturing respectively. Stakeholders must monitor evolving CSRD disclosure mandates that will require documented non-destructive testing workflows for sustainability reporting across European supply chains.
Market Dynamics
The EU Green Deal's material efficiency mandates are forcing destructive sampling protocols out of aerospace and automotive quality assurance workflows, redirecting capital toward non-destructive testing infrastructure.
Growth Catalysts
- REACH compliance obligations:Heavy metal disposal restrictions under ECHA frameworks accelerate X-ray tube recycling investments, creating aftermarket service demand.
- Carbon-fiber-reinforced polymer inspection:Aerospace manufacturers in Germany and France require CT verification for composite turbine blade integrity without sectioning.
- Metrology cluster concentration:Germany's industrial heartland co-locates automotive OEMs with precision engineering service providers, reducing CT system deployment friction.
Market Restraints
- Detector supply concentration:Digital flat-panel detector manufacturing concentrates among Asian suppliers, exposing European system integrators to input cost volatility and lead time extension.
- CSRD disclosure complexity:Documented non-destructive testing workflows for sustainability reporting impose compliance overhead before revenue recognition.
- High-voltage X-ray source import dependency:Specialized tube technology remains captive to non-European component suppliers, constraining domestic value capture.
Strategic Opportunities
- France's ANSM medical device protocols:Stricter implant inspection thresholds create CT qualification demand in precision manufacturing sub-regions.
- Semiconductor packaging inspection:Sub-micron feature resolution requirements in advanced packaging drive Nano CT adoption among European foundry suppliers.
- Energy-sector additive manufacturing:Pipeline component qualification workflows in North Sea operations require CT-based porosity mapping for regulatory acceptance.
Industry Challenges
- Multi-physics simulation expertise:CT data integration with finite element analysis demands cross-trained metrology engineers scarce in European labor markets.
- CE marking timeline compression:Machinery Directive conformity assessment delays system commissioning, extending cash conversion cycles for capital equipment vendors.
- Legacy CMM interoperability:Coordinate measuring machine data formats conflict with CT volumetric outputs, complicating shop-floor software integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Computed Tomography Market |
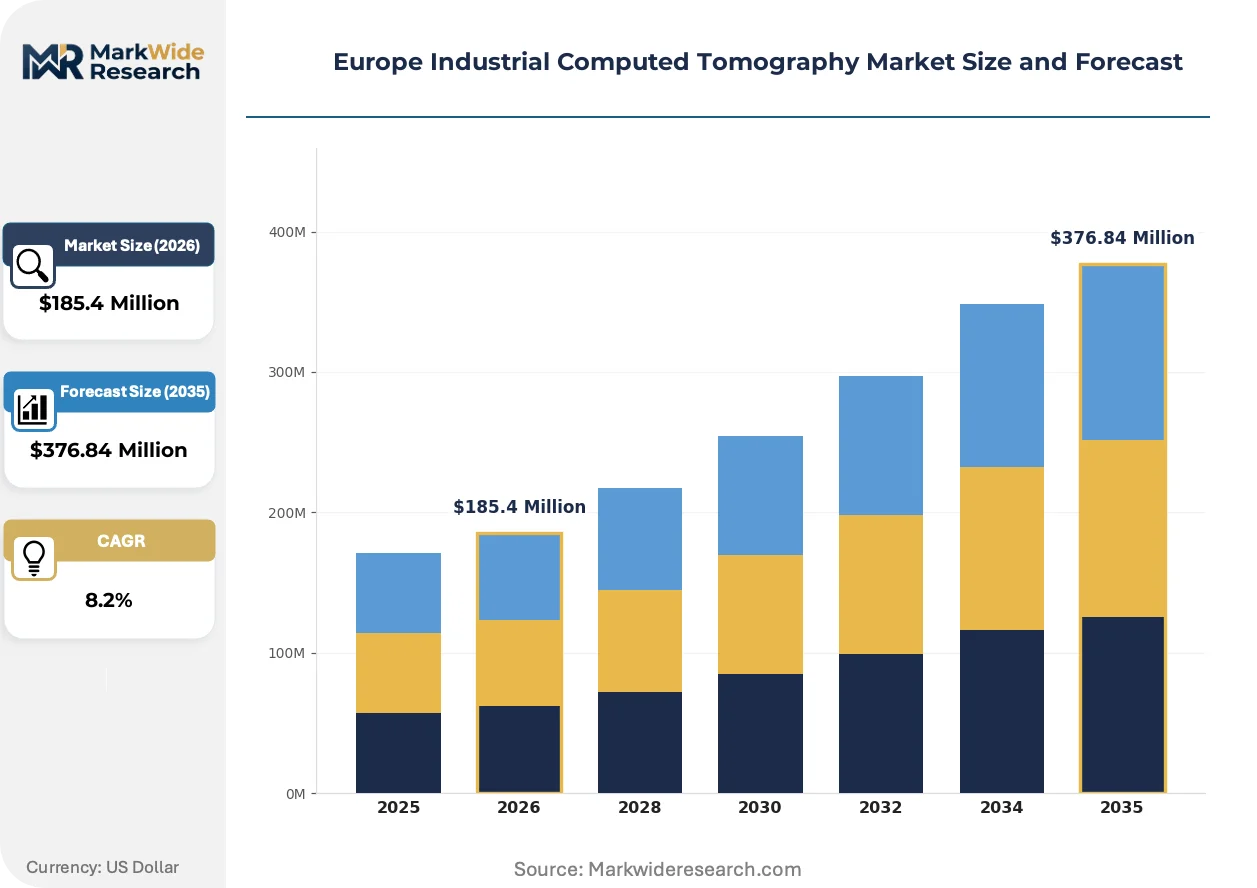
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $376.84 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D CT, 3D CT, Nano CT, Industrial CT End User: Aerospace, Automotive, Energy, Manufacturing Application: Quality Control, Reverse Engineering, Failure Analysis, Research & Development Technology: X-Ray, Digital Detectors, Software Algorithms, Image Reconstruction |
| Companies Covered | ZEISS Group, Werth, Baker Hughes Company, Wenzel Group, Comet, Nikon Corporation, VJ Group, Hamamatsu Photonics, Rigaku, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Computed Tomography Market Shifts & Advancements
Computational reconstruction algorithms and detector hardware advances are compressing scan times while expanding resolvable feature sizes, altering competitive positioning among European system suppliers.
Deep learning-based defect classification is overtaking rule-based image analysis in production-line CT systems. Automotive powertrain manufacturers in Stuttgart and Munich deploy neural networks for real-time casting void detection. This capability is compressing inspection cycle times from hours to minutes, enabling 100% part screening rather than statistical sampling.
CSRD disclosure mandates are mandating documented non-destructive testing workflows for sustainability reporting across European supply chains. Manufacturers must now certify material efficiency gains through verifiable inspection records rather than estimates. Medical device and aerospace segments face the steepest documentation burdens, driving CT system purchases with integrated audit trail functionality.
Service-based revenue models are displacing pure equipment sales among German and French metrology providers. End-users in precision engineering clusters prefer operational expenditure structures that bundle hardware, software, and application engineering support. This shift concentrates vendor relationships with full-stack capability holders while marginalizing component-only suppliers.
Europe Industrial Computed Tomography Market Segmentation
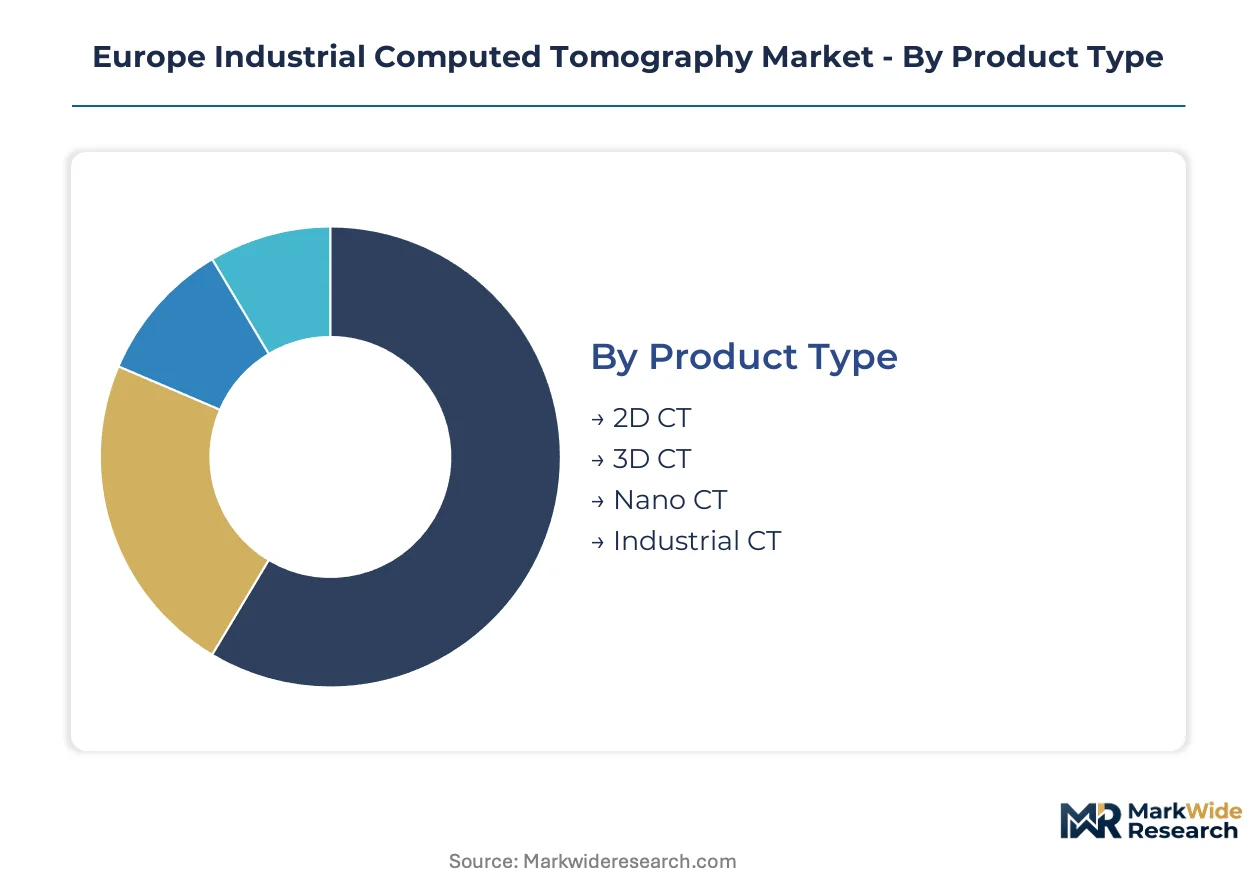
CT system configurations span a customization spectrum from standardized production-line units to bespoke laboratory installations. End-use requirements in European aerospace and automotive clusters drive divergence between volume-optimized and precision-engineered product tiers. Application workflows further fragment demand across destructive-replacement protocols versus R&D exploration modes.
Product Type:
Standardization concentrates in high-throughput systems for automotive powertrain inspection, while customization dominates sub-micron resolution platforms for semiconductor packaging verification.
- 2D CT:Linear detector arrays generate cross-sectional slices through rotational scanning of planar specimens. German automotive foundries deploy 2D CT for real-time casting void detection in Stuttgart manufacturing corridors. Demand concentrates where cycle time compression outweighs volumetric data requirements.
- 3D CT:Cone-beam geometry and flat-panel detectors reconstruct complete volumetric datasets with isotropic spatial resolution. Aerospace manufacturers in France and Germany specify 3D CT for turbine blade internal geometry verification without sectioning. France's ANSM protocols mandate this capability for implantable medical device qualification.
- Nano CT:Sub-micron feature resolution through nanofocus X-ray sources and high-magnification geometry. European foundry suppliers in semiconductor packaging segments drive qualification demand.
- Industrial CT:Ruggedized enclosures and automated part handling for shop-floor deployment. Metrology service providers across Germany's industrial heartland standardize on this configuration.
Leading the category by volume: 3D CT. Expanding most quickly: Nano CT.
End User:
Margin profiles diverge sharply between regulated medical-adjacent aerospace workflows and price-sensitive general manufacturing applications.
- Aerospace:Turbine blade and composite structure verification against EASA airworthiness directives. CFRP inspection protocols in Safran and MTU supply chains mandate CT substitution for destructive sampling. Germany's KBA enforces comparable standards for automotive-adjacent aerospace suppliers.
- Automotive:Powertrain casting and electric motor stator inspection across Stuttgart, Munich, and Wolfsburg production clusters. OEMs deploy 100% CT screening for safety-critical brake caliper and steering components.
- Energy:Pipeline integrity assessment and additive manufacturing qualification for North Sea operations. Baker Hughes anchors European service capacity for subsea component porosity mapping.
- Manufacturing:General precision engineering and subcontract metrology services. Smaller machine shops in Baden-Württemberg access CT through service bureau arrangements rather than capital purchase.
Highest margin capture: Aerospace. Steepest volume trajectory: Automotive.
Application:
Revenue recognition timing separates immediate production-line quality assurance from extended-cycle R&D engagements.
- Quality Control:Automated pass-fail classification integrated directly into manufacturing execution systems. Stuttgart automotive powertrain plants deploy neural network-based void detection compressing inspection cycles from hours to minutes.
- Reverse Engineering:Volumetric digitization of legacy components lacking original technical documentation. Aerospace aftermarket suppliers in France reconstruct obsolete turbine blade geometries for remanufacturing authorization.
- Failure Analysis:Root-cause investigation for warranty returns and field incidents. Germany's KBA mandates CT documentation for automotive component failure arbitration.
- Research & Development:Materials characterization and process development without production throughput constraints. European university laboratories and corporate R&D centers drive demand for highest-resolution configurations.
Largest revenue pool: Quality Control. Superior margin profile: Research & Development.
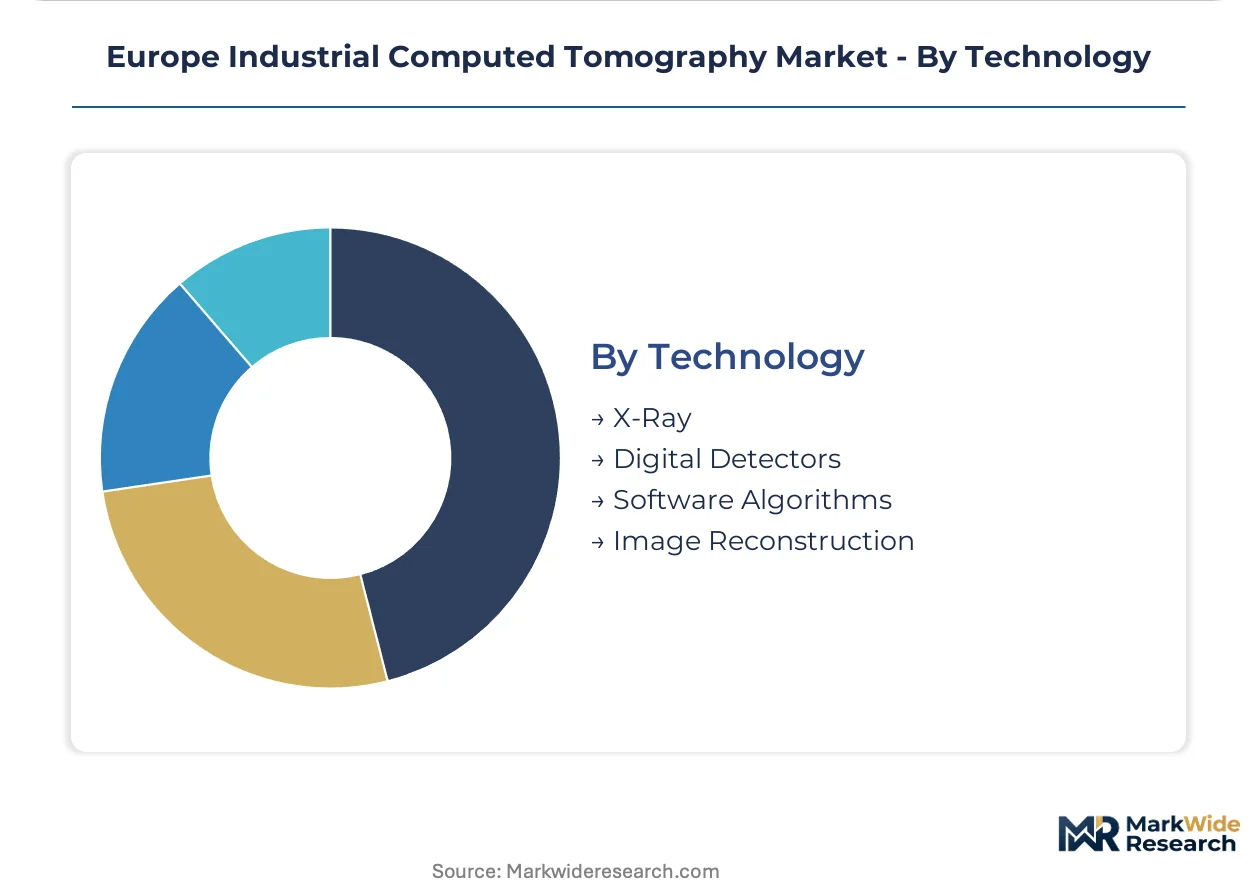
Technology:
Supply concentration in detector hardware constrains European system integrators while software differentiation offers domestic escape routes.
- X-Ray:Sealed microfocus and nanofocus tubes generating bremsstrahlung spectra optimized for penetration depth and spot size. High-voltage source technology remains captive to non-European component suppliers.
- Digital Detectors:Amorphous silicon and CMOS flat-panel arrays converting X-ray photons to electrical signals. Asian manufacturing concentration exposes European integrators to input cost volatility and lead time extension.
- Software Algorithms:Computational reconstruction and automated defect classification pipelines. ZEISS Group and Werth differentiate through proprietary reconstruction kernels and neural network training datasets.
- Image Reconstruction:Feldkamp-Davis-Kress cone-beam algorithms and iterative sparse-view techniques. Deep learning acceleration is compressing reconstruction times for real-time production deployment.
Deepest supply constraint: Digital Detectors. Fastest capability advance: Software Algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision engineering corridor anchors European CT demand through co-located automotive OEMs and metrology service providers. Stuttgart and Munich manufacturing clusters drive volume concentration. France's aerospace supply chains in Toulouse and Nantes create parallel demand centers for turbine blade verification.
Germany
Stuttgart automotive powertrain plants and Wolfsburg OEM facilities deploy 100% CT screening for safety-critical brake caliper and steering components. KBA enforcement of inspection documentation for failure arbitration tightens compliance thresholds. Bavaria's Munich-Wolfratshausen corridor concentrates metrology service bureaus serving mid-tier machine shops through operational expenditure contracts.
France
Safran and MTU supply chains mandate CT substitution for destructive sampling of carbon-fiber-reinforced polymer turbine blades. ANSM protocols for implantable medical device qualification create secondary demand in precision manufacturing sub-regions. Toulouse aerospace clusters and Nantes composite manufacturing facilities drive regional system deployment.
United Kingdom
North Sea energy operations require CT-based porosity mapping for subsea pipeline component qualification. EASA-aligned aerospace suppliers in Midlands manufacturing corridors adopt turbine blade verification protocols comparable to continental standards. Research universities in Oxford and Cambridge drive Nano CT adoption for materials characterization.
Italy
Emilia-Romagna automotive component suppliers integrate CT inspection into powertrain casting workflows serving German OEMs. Lombardy precision engineering clusters access CT capabilities through cross-border service arrangements with Swiss metrology providers. CE marking compliance timelines compress system commissioning schedules for capital equipment vendors.
Switzerland
Swissmedic medical device oversight creates inspection protocol demand comparable to ANSM thresholds in neighboring France. Precision watchmaking and medtech manufacturing in Jura Arc clusters deploy sub-micron resolution systems for miniaturized component verification. Basel pharmaceutical equipment suppliers extend CT qualification to packaging integrity applications.
Europe Industrial Computed Tomography Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack capability holders capturing service-based revenue streams while component-only suppliers face margin compression. The vendor base concentrates around metrology heritage players and energy-sector service anchors, creating tiered competitive dynamics. Three archetypes dominate: precision measurement heritage firms, diversified industrial conglomerates with CT divisions, and specialized multi-sensor platform builders. Capacity expansion in software algorithms and strategic partnerships for detector supply security represent the dominant competitive moves.
Among Germany-based precision measurement specialists, ZEISS Group and Werth occupy positions reflecting metrology heritage dominance in high-resolution turbine blade inspection. Wenzel Group represents the multi-sensor platform archetype integrating tactile and optical measurement with CT capability. Baker Hughes Company anchors the energy-sector service vector through North Sea pipeline integrity and additive manufacturing qualification workflows. These three exemplify how geographic clustering near demand centers reduces deployment friction for European end-users.
| Leading Market Players |
|---|
| ZEISS Group |
| Werth |
| Baker Hughes Company |
| Wenzel Group |
| Comet |
| Nikon Corporation |
| VJ Group |
| Hamamatsu Photonics |
| Rigaku |
| Others |
Supply & Pricing Matrix
Cross-trained metrology engineers concentrated in Baden-Württemberg and Bavaria command wage premiums that compress margins on standard CT system configurations while widening spreads between economy-tier shop-floor units and premium laboratory installations.
Pricing Analysis
Volume concentrates in automotive powertrain inspection systems where price erosion runs through Stuttgart and Wolfsburg procurement corridors, while margin capture concentrates in Nano CT configurations for semiconductor packaging verification. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by software algorithm sophistication and CE marking documentation depth. Automotive OEMs exhibit highest price sensitivity due to 100% screening volume requirements, whereas aerospace turbine blade verification tolerates premium positioning due to EASA airworthiness directive compliance thresholds.
Supply Chain Analysis
Regional distribution centers in Germany and France maintain hub-and-spoke patterns feeding metrology service bureaus across the industrial heartland. Manufacturing concentration in Japan and South Korea for high-voltage X-ray sources and digital flat-panel detectors exposes European system integrators to single-source vulnerability. Component dependencies center on amorphous silicon detector arrays, nanofocus tube assemblies, and computational reconstruction hardware. Distribution runs through direct OEM relationships for large installations and service bureau networks for mid-tier machine shop access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over detector supply security and proprietary reconstruction algorithms determines pricing power and margin sustainability.
For Market Incumbents: Acquire specialized multi-sensor platform capabilities to defend against pure-play CT specialists encroaching from adjacent metrology segments. Consolidate detector supply relationships through long-term offtake arrangements with Asian component suppliers, reducing exposure to lead time volatility that disrupts system commissioning schedules. CE marking timeline compression under Machinery Directive revisions threatens cash conversion cycles, requiring pre-certified modular architectures. For New Entrants and Emerging Players: Capture service-based revenue white space among mid-tier precision engineering subcontractors in Baden-Württemberg and Emilia-Romagna who prefer operational expenditure structures over capital purchase. Target energy-sector additive manufacturing qualification workflows in North Sea operations where Baker Hughes has not fully penetrated subsea component inspection. Lead with audit-trail-integrated software bundles that satisfy emerging CSRD disclosure mandates for sustainability reporting. For Investors and Strategic Acquirers: Re-rating potential sits with full-stack capability holders given service-based revenue model displacement and software algorithm differentiation. Long-term viability favors vendors controlling proprietary reconstruction kernels and neural network training datasets rather than component-only suppliers facing margin compression. Watch for inflection signals in semiconductor packaging inspection demand among European foundry suppliers, where Nano CT adoption trajectories indicate premium segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Supply Security Partnership | Long-term offtake agreements with Hamamatsu Photonics reduce input cost volatility for European system integrators. |
| Deep Learning Algorithm Development | Proprietary neural networks for real-time void detection differentiate ZEISS and Werth from rule-based competitors. |
| Service Bureau Network Expansion | Operational expenditure models in Bavaria capture mid-tier machine shops previously excluded from CT adoption. |
| CE Marking Pre-Certification | Modular system architectures compress Machinery Directive conformity assessment timelines for faster revenue recognition. |
| CSRD Audit Trail Integration | Documented non-destructive testing workflows embedded in software platforms satisfy emerging sustainability reporting mandates. |
Research Methodology
Document review covered EASA airworthiness directives, KBA inspection protocols, ANSM medical device guidance, and EU Machinery Directive implementing texts, complemented by interviews with metrology system engineering directors, aerospace quality assurance leads, automotive powertrain procurement managers, and precision engineering service bureau operators. Secondary validation drew from SEC filings of listed component suppliers, ECHA REACH substance restriction updates, and CSRD implementation guidance documents. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from system shipment tracking.
Segmented outputs span product type tiers, end-user industry verticals, application workflows, and technology component categories across the projection horizon. CAGRs derive from regression analysis of historical system deployment patterns against regulatory mandate timelines and manufacturing capital expenditure cycles. Industry-specific inputs include turbine blade inspection protocol adoption rates, automotive powertrain casting volume trends, and semiconductor packaging resolution requirement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to detector supply chain disruptions, X-ray tube material substitution under REACH restrictions, and CSRD disclosure mandate enforcement intensity. Outputs reflect documented assumptions regarding regulatory timeline adherence and manufacturing cluster expansion plans. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Machine Vision System and Services Market
Imaging
Handheld Retinal Scanners Market
Imaging
Latin America IP Camera Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
SDI Camera Market
Imaging
CMOS Camera Market
Imaging
Automotive 3D Imaging Market
Imaging
Electron Microscopy Market
Imaging
Image Signal Processor and Vision Processor Market
Imaging
Raman-Imaging System Market
Imaging
Global 4K Camera Market
Imaging
Machine Vision Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Global Label-Free Array Systems Market
Imaging
India CCTV Camera Market