
 Cleft Lip Surgery Market | 2026-2036
Cleft Lip Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Cleft Lip Surgery Market Intelligence
Procurement of cleft lip surgical supplies is shifting from single-source imports toward multi-vendor domestic contracts in emerging markets. Apollo Hospitals leverages its pan-Indian network to anchor high-volume cleft camps across tier-2 cities. Medanta competes through specialized craniofacial units with integrated orthodontic and speech therapy pathways. Great Ormond Street Hospital sustains its reputation by controlling referral channels for complex revision cases from the Middle East and Africa.
Cleft lip surgery encompasses the unilateral or bilateral repair of congenital orofacial clefts using mucoperiosteal flap techniques, typically performed between three and six months of age, with outcomes measured by vermillion border alignment and nasal symmetry. The procedure restores oral competence, speech articulation, and facial aesthetics while preventing feeding complications and middle ear infections. Surgical instruments and sutures command the largest product-type revenue pool due to recurring consumption per procedure, while 3D imaging is the fastest-growing technology segment as preoperative planning reduces revision rates. Hospitals dominate end-user demand because cleft repair requires general anesthesia, pediatric intensive care backup, and multidisciplinary teams that clinics cannot assemble.
The US FDA regulates craniofacial implants and surgical mesh under Class II medical device standards, while India's CDSCO mandates BIS certification for imported stainless steel instruments used in cleft procedures. The EU MDR requires enhanced clinical evidence for pediatric surgical devices, which extends approval timelines but raises safety benchmarks. Stakeholders must monitor how digital surgical planning tools integrate with existing reimbursement frameworks for congenital anomaly correction.
Market Dynamics
India's PLI scheme for medical devices is accelerating domestic production of surgical instruments, shifting procurement patterns from import dependence toward local manufacturing clusters in Gujarat and Tamil Nadu.
Growth Catalysts
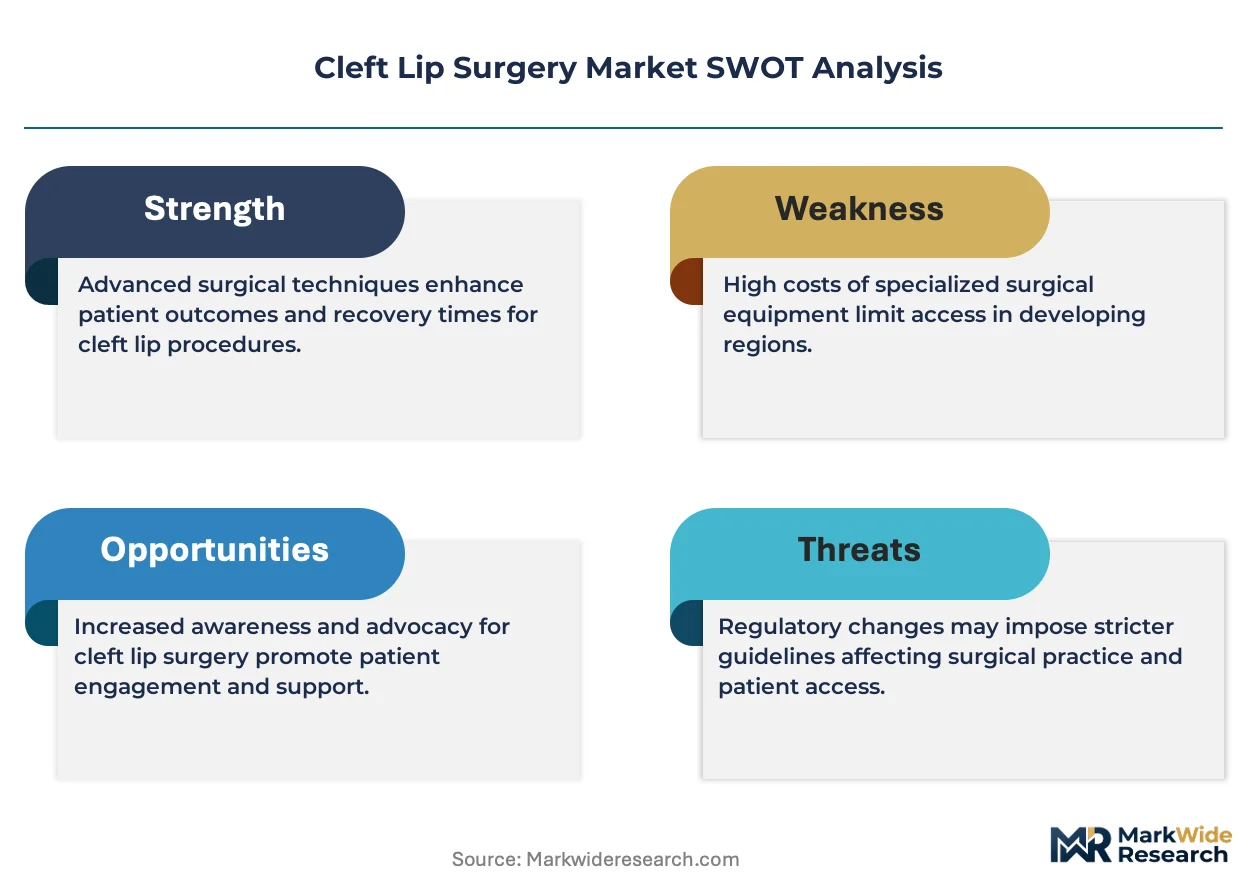
- India's PLI scheme:Production-linked incentives for medical device manufacturing reduce import tariffs on stainless steel surgical instruments used in cleft procedures.
- Pediatric hospital networks:Charitable surgical camps organized by Smile Train and Operation Smile expand access to cleft repair in tier-2 Indian cities.
- 3D surgical planning software:Preoperative simulation tools reduce revision rates and improve vermillion border alignment outcomes.
Market Restraints
- Stainless steel price volatility:Raw material cost fluctuations for surgical forceps and needle holders compress margins for instrument manufacturers.
- EU MDR compliance burden:Enhanced clinical evidence requirements for pediatric surgical devices extend approval timelines by 18-24 months.
- Bioresorbable suture substitution:Synthetic polymer alternatives threaten traditional silk and catgut suture demand in cosmetic closure applications.
Strategic Opportunities
- Rural India penetration:Mobile surgical units and telemedicine screening programs address underdiagnosed cleft prevalence in Bihar and Uttar Pradesh.
- AI-powered outcome prediction:Machine learning models trained on craniofacial imaging datasets enable personalized surgical planning.
- Integrated care pathways:Bundled reimbursement models combining surgery, orthodontics, and speech therapy create new revenue pools.
Industry Challenges
- Pediatric anesthesiologist shortage:Limited specialist availability constrains surgical camp capacity expansion in Southeast Asia.
- CDSCO-BIS dual certification:Parallel regulatory pathways for imported instruments create documentation bottlenecks.
- Legacy EMR integration:Digital surgical planning tools require costly interoperability upgrades with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cleft Lip Surgery Market |
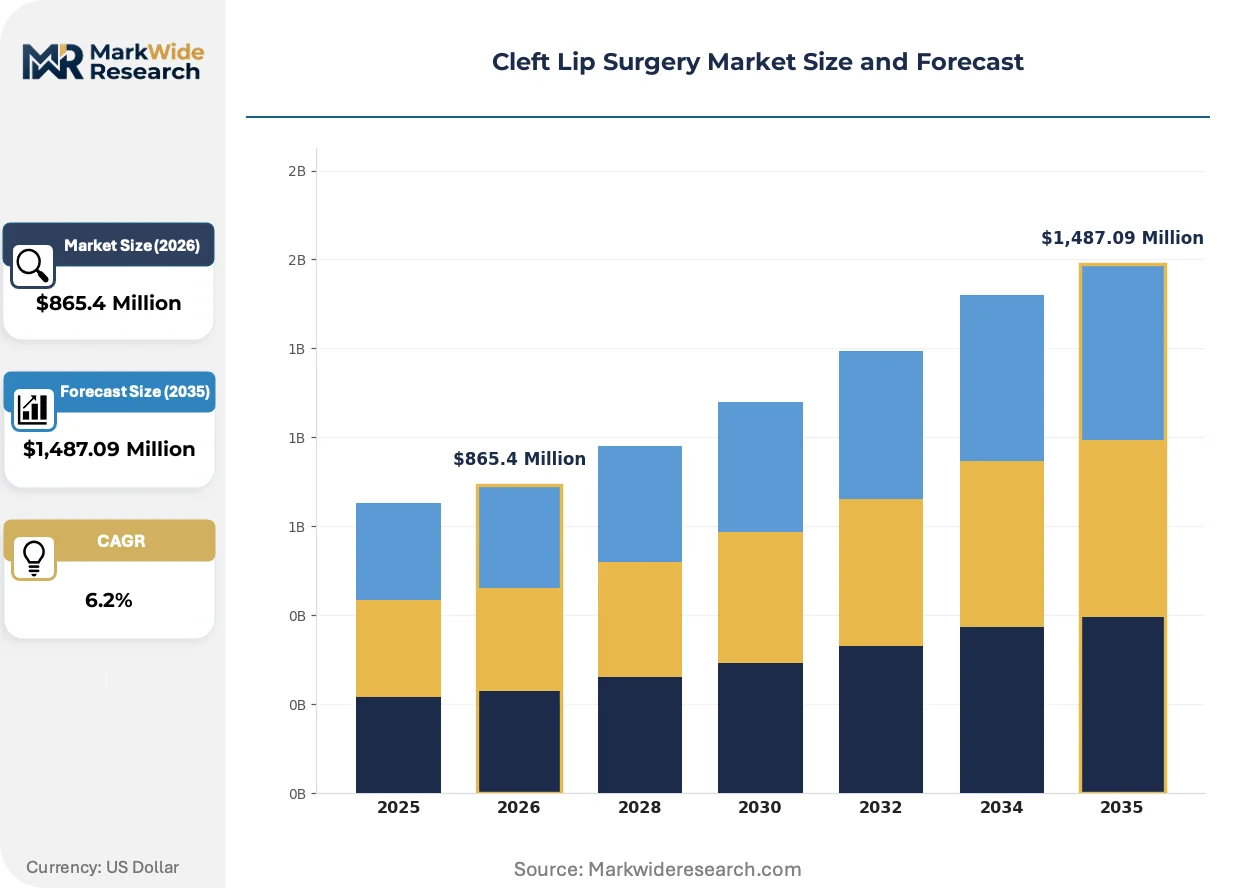
| Market Size in 2026 | $865.4 Million |
| Market Size in 2035 | $1,487.09 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Sutures, Implant Materials, Observation Tools Technology: Laser Surgery, Traditional Surgery, Minimally Invasive Techniques, 3D Imaging End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Practices Procedure Type: Primary Surgery, Revision Surgery, Secondary Surgery, Emergency Surgery |
| Companies Covered | Children’s Hospital of Philadelphia, Medanta, Apollo Hospitals, Great Ormond Street Hospital, The McIndoe Centre, University Hospital Bonn, Balaji Dental and Craniofacial Hospital, St. Louis Children’s Hospital, Care National Hospital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cleft Lip Surgery Market Strategic Shifts & Innovations
Digital workflows are compressing the gap between diagnosis and intervention, with three distinct forces reshaping how cleft repair is planned, delivered, and reimbursed.
Virtual surgical planning platforms are converging with intraoperative navigation systems to enable millimeter-precision flap positioning. Pediatric craniofacial centers in the United States and Germany adopt these combined workflows for complex bilateral cases. The technology is converging with conventional 2D imaging to displace freehand surgical approaches in high-volume hospitals.
The EU MDR's enhanced clinical evidence requirements for pediatric devices are extending approval timelines but raising safety benchmarks. Manufacturers must now submit post-market surveillance data for sutures and bone-fixation plates used in infants. European notified bodies are prioritizing submissions from firms with established ISO 13485 quality management systems.
Charitable foundations are consolidating procurement through centralized tendering platforms, displacing hospital-level purchasing for high-volume cleft camps. Smile Train's global supply chain now coordinates instrument kits across 75 countries. India and the Philippines exhibit the most pronounced concentration of foundation-directed procurement.
Cleft Lip Surgery Market Segmentation
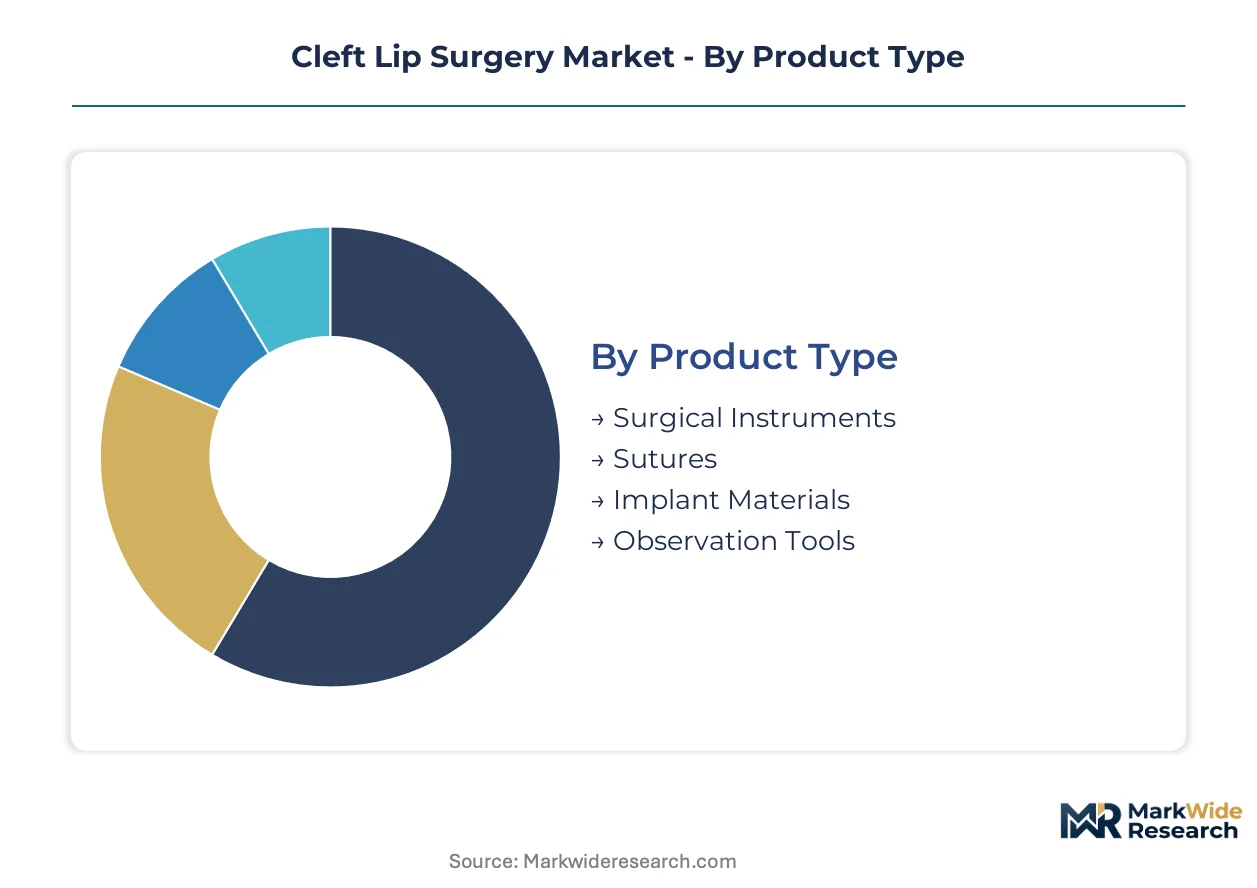
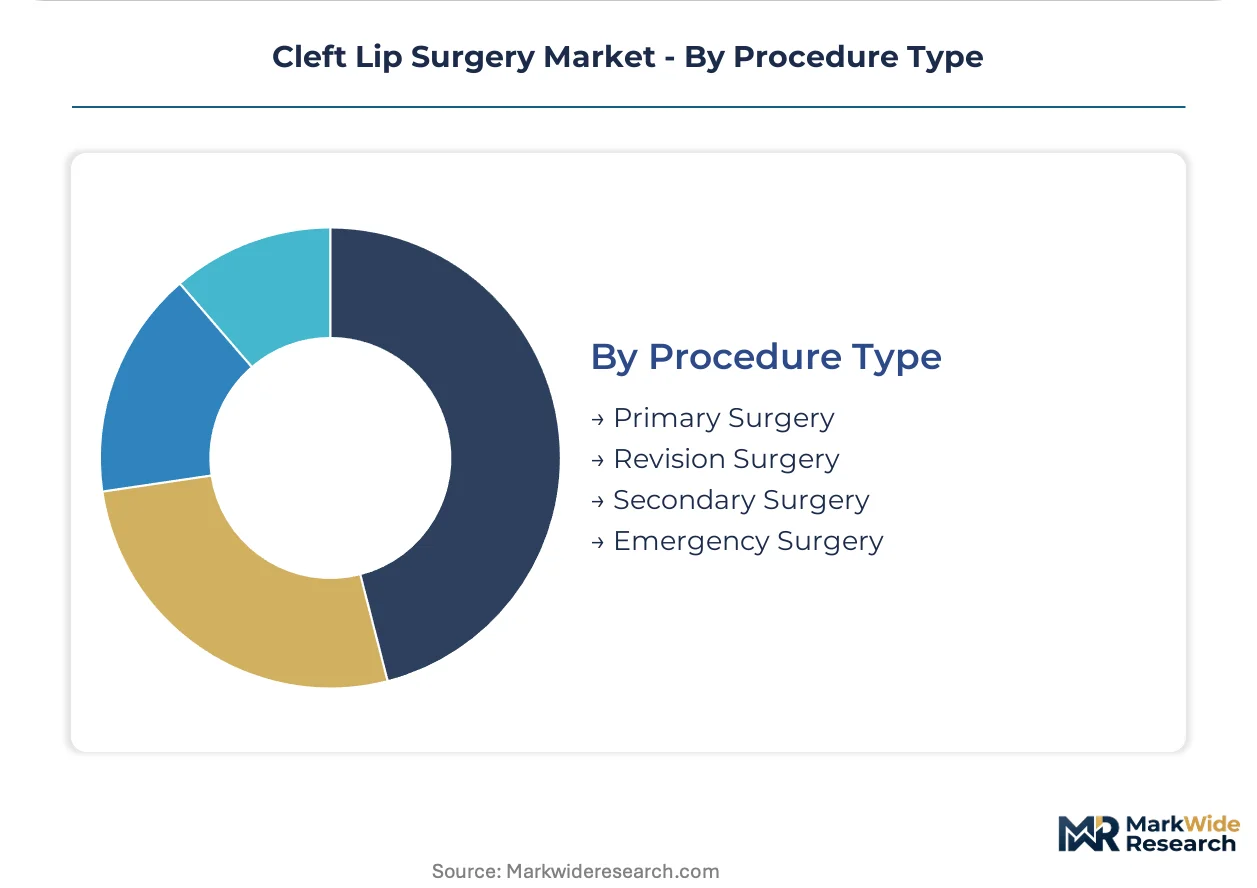
Cleft lip surgery markets fragment across equipment intensity, clinical setting requirements, and procedural complexity. Each dimension shapes procurement patterns and margin structures differently for manufacturers and providers.
Product Type:
Surgical instruments and implant materials demand the heaviest capital commitment due to precision manufacturing requirements and regulatory validation costs.
- Surgical Instruments:Stainless steel forceps, needle holders, and retractors manufactured to BIS and ISO 13485 standards. Apollo Hospitals and charitable networks in India consume high volumes through centralized tendering for cleft camps.
- Sutures:Absorbable polyglactin and non-absorbable silk threads for mucoperiosteal flap closure. CDSCO mandates sterility certification for all pediatric surgical applications.
- Implant Materials:Resorbable plates and screws for alveolar bone fixation in complex bilateral repairs. EU MDR clinical evidence requirements extend approval timelines for craniofacial implants used in infants.
- Observation Tools:Nasal speculums and oral retractors enabling intraoperative visualization.
Surgical instruments absorb the bulk of installed capacity; 3D imaging is expanding most quickly.
Technology:
Technology selection tracks hospital infrastructure maturity and surgeon training depth, with digital workflows commanding premium positioning.
- 3D Imaging:Preoperative craniofacial modeling using CT and stereophotogrammetry to simulate vermillion border alignment. German and US pediatric centers lead adoption for complex bilateral cases.
- Laser Surgery:Tissue ablation and hemostasis using CO2 and erbium lasers for precise mucosal incision. Limited penetration due to capital equipment costs and specialized training requirements.
- Traditional Surgery:Conventional scalpel and scissor techniques with direct visualization. Dominates charitable surgical camps in India and Southeast Asia where equipment portability matters.
- Minimally Invasive Techniques:Endoscope-assisted approaches through small intraoral incisions. Emerging application for revision cases with scar tissue from prior repairs.
Traditional surgery retains the deepest installed base; 3D imaging is climbing the fastest.
End User:
Facility type determines reimbursement pathways, multidisciplinary team requirements, and equipment amortization models.
- Hospitals:Pediatric tertiary centers with anesthesia backup and intensive care capacity. India's expanding charitable networks anchor high-volume cleft repair in tier-2 cities.
- Specialty Practices:Craniofacial surgery units with integrated orthodontic and speech therapy pathways. Medanta's Delhi facility exemplifies this concentrated expertise model.
- Ambulatory Surgical Centers:Same-day discharge facilities for uncomplicated unilateral repairs. Limited penetration due to pediatric anesthesia requirements.
- Clinics:Screening and referral nodes without surgical capability. Mobile units in rural Bihar and Uttar Pradesh extend diagnostic reach.
Hospitals command the deepest procedure volume; specialty practices are gaining share fastest.
Procedure Type:
Procedural complexity tiering shapes instrument kit configuration and surgeon specialization requirements.
- Primary Surgery:Initial unilateral or bilateral cleft lip repair performed between three and six months of age. Smile Train and Operation Smile coordinate the majority of volume in India and the Philippines.
- Revision Surgery:Secondary correction of vermillion border misalignment or nasal deformity from prior repair. Great Ormond Street Hospital controls referral channels for complex cases from the Middle East and Africa.
- Secondary Surgery:Alveolar bone grafting and rhinoplasty performed during mixed dentition. Requires coordinated orthodontic and surgical scheduling.
- Emergency Surgery:Urgent intervention for airway compromise or feeding failure in neonates. Rare indication concentrated in academic medical centers.
Primary surgery absorbs the bulk of annual procedures; revision surgery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs the deepest procedure volume for cleft lip repair, driven by high birth prevalence and expanding charitable surgical networks. Smile Train and Operation Smile coordinate high-volume camps across tier-2 cities. The country's PLI scheme for medical devices accelerates domestic production of surgical instruments.
India
Apollo Hospitals leverages its pan-Indian network to anchor high-volume cleft camps across tier-2 cities, while Medanta competes through specialized craniofacial units. CDSCO mandates BIS certification for imported stainless steel instruments, creating dual regulatory pathways. Manufacturing clusters in Gujarat and Tamil Nadu supply forceps and needle holders to charitable procurement platforms.
United States
Pediatric craniofacial centers in Philadelphia and St. Louis adopt 3D surgical planning for complex bilateral cases. FDA regulates craniofacial implants under Class II medical device standards, requiring substantial equivalence demonstrations. Academic medical centers in the Midwest and Northeast control referral channels for revision surgery from international patients.
Germany
University hospitals in Bonn and Berlin integrate virtual surgical planning with intraoperative navigation for millimeter-precision flap positioning. EU MDR extends approval timelines for pediatric surgical devices by demanding enhanced clinical evidence. Industrial clusters in Baden-Württemberg manufacture precision instruments to ISO 13485 standards.
United Kingdom
Great Ormond Street Hospital sustains its reputation by controlling referral channels for complex revision cases from the Middle East and Africa. The NHS funds multidisciplinary cleft teams combining surgery, orthodontics, and speech therapy. London-based centers attract international patients through bundled care pathways.
Philippines
Charitable foundations concentrate procurement through centralized tendering platforms for high-volume surgical camps. Operation Smile coordinates instrument kits across archipelago-based programs. Metro Manila hospitals serve as training hubs for Southeast Asian surgical teams.
Cleft Lip Surgery Market Key Industry Players
Capacity expansion dominates the current landscape as pediatric hospital networks extend cleft repair programs into underserved regions. The vendor base separates into three tiers: academic medical centers with international referral dominance, multi-hospital chains with charitable camp infrastructure, and specialized craniofacial units with integrated therapy pathways. Competitive positioning hardens around M&A activity consolidating regional anesthesia and pediatric intensive care capabilities, alongside strategic partnerships linking surgical providers with orthodontic and speech therapy networks.
Within the academic medical center tier, Children's Hospital of Philadelphia and Great Ormond Street Hospital exemplify international referral anchoring for complex revision cases. Apollo Hospitals and Medanta occupy positions as scale-driven multi-hospital operators in India, with the former leveraging camp infrastructure and the latter concentrating specialized expertise. Balaji Dental and Craniofacial Hospital represents the focused specialist archetype, integrating dental and surgical disciplines within a single-site model.
| Leading Market Players |
|---|
| Children's Hospital of Philadelphia |
| Medanta |
| Apollo Hospitals |
| Great Ormond Street Hospital |
| The McIndoe Centre |
| University Hospital Bonn |
| Balaji Dental and Craniofacial Hospital |
| St. Louis Children's Hospital |
| Care National Hospital |
| Others |
Cost & Logistics Intelligence
EU MDR's enhanced clinical evidence requirements for pediatric surgical devices gate qualified supply access and premium-tier pricing for craniofacial implants, forcing manufacturers to absorb extended validation costs or cede high-margin segments to ISO 13485-certified competitors with established post-market surveillance infrastructure.
Pricing Analysis
Volume-vs-margin split concentrates in charitable procurement networks versus academic medical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and after-sales service bundling. Cost compression in economy-tier instrument kits is intensifying because Smile Train's centralized tendering consolidates purchasing power across tier-2 Indian cities. Charitable foundations exhibit highest price sensitivity; German university hospitals show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese stainless steel forging for surgical forceps and Indian silk suture processing. Manufacturing clusters in Gujarat and Tamil Nadu draw from German precision-machining equipment and Japanese nickel-titanium alloys. Tariff exposure on imported raw materials threatens margin stability for domestic instrument producers. Distribution runs through charitable foundation procurement platforms and hospital GPO contracts in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital surgical planning software is displacing freehand approaches in high-volume pediatric centers, compressing the technology adoption cycle from academic reference sites to charitable camp settings.
For Market Incumbents: Hedge against bioresorbable suture substitution by securing backward integration into polymer R&D or captive supply of traditional silk and catgut lines. Defend instrument kit margins through ISO 13485 certification investment that accelerates EU MDR approval timelines. Anchor capacity in Tamil Nadu manufacturing clusters to exploit PLI scheme incentives and reduce import tariff exposure. For New Entrants and Emerging Players: Launch via mobile surgical unit partnerships in rural Bihar and Uttar Pradesh, where underdiagnosed cleft prevalence meets absent charitable infrastructure. Target AI-powered outcome prediction tools as the most penetrable white-space segment, with machine learning models trained on Indian craniofacial imaging datasets. Pursue telemedicine screening integration as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA 510(k) clearance for 3D surgical planning software is the leading indicator that digital workflow adoption has crossed from academic early adopters to high-volume charitable networks. Long-term viability rests on platforms combining preoperative simulation with intraoperative navigation. Acquisition targets should display ISO 13485 quality systems and established charitable foundation procurement relationships. Watch for EU MDR approval timeline compression as the signal that regulatory moats are widening.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend approval timelines for pediatric craniofacial implants. |
| Hospital System Partnership | Apollo Hospitals' pan-Indian network anchors high-volume cleft camps with centralized instrument procurement. |
| Software Companion Development | Virtual surgical planning platforms converge with intraoperative navigation for millimeter-precision flap positioning. |
| Reimbursement Strategy | Bundled care pathways combining surgery, orthodontics, and speech therapy create new revenue pools. |
| FDA Submission | Class II medical device standards for craniofacial implants require substantial equivalence demonstrations. |
Research Approach
Independent corroboration across craniofacial surgeons, hospital purchasing committees, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with pediatric anesthesiologists and charitable foundation supply chain directors combined with secondary validation from CDSCO device registration databases, EU MDR notified body filings, and hospital procurement tender records. Bottom-up procedure volume estimates triangulate with top-down market sizing across product type, technology, and end user segments.
Comparable-period anchoring to historical charitable surgical camp volumes and academic medical center admission rates establishes the forecast baseline across the analysis window. Segmentation dimensions modeled include product type intensity, technology adoption maturity, facility infrastructure tier, and procedural complexity. CAGRs derive from trend extrapolation adjusted for PLI scheme acceleration and EU MDR approval friction. Industry-specific inputs incorporate stainless steel price volatility indices and pediatric anesthesiologist workforce density.
Regulatory timeline slippage, raw material cost spikes, and charitable funding discontinuation are the dominant revision risks. Forecasts reflect documented assumptions about technology adoption curves and reimbursement pathway evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Liver Transplantation Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Endovenous Laser Therapy Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Ringworm Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Otoplasty Market