
 Severe Asthma Treatment Market | 2026-2036
Severe Asthma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Severe Asthma Treatment Market Analytics
FDA accelerated approval pathways for biologics is broadening the cost-of-entry calculus for manufacturers seeking to commercialize novel monoclonal antibodies against IL-5, IL-4/13, and TSLP targets. Novartis leverages its established neurology and immunology infrastructure to sustain commercial traction for its severe asthma biologic portfolio across North American and European markets. AstraZeneca anchors its respiratory franchise through deep specialization in inhaled and injectable biologic combinations. Sanofi competes aggressively through differentiated positioning in the pediatric and adolescent severe asthma segments.
Severe asthma treatment encompasses pharmacological interventions targeting Type 2 and non-Type 2 inflammatory pathways in patients with uncontrolled disease despite high-dose inhaled corticosteroid and long-acting beta-agonist combination therapy, with biologics typically administered via subcutaneous injection at 2-4 week intervals and corticosteroids delivered through metered-dose or dry-powder inhalers achieving lung deposition rates of 10-40%. Monoclonal antibodies command the dominant value share as physician familiarity with anti-IgE, anti-IL-5, and anti-IL-4/13 mechanisms deepens and payer formularies expand coverage criteria. Injectable delivery modes generate premium pricing relative to inhalation and nebulization routes due to cold-chain requirements, specialist administration protocols, and superior efficacy data in refractory populations. Homecare settings represent the fastest-growing end-user channel as self-administration training programs and remote patient monitoring reduce hospital dependency.
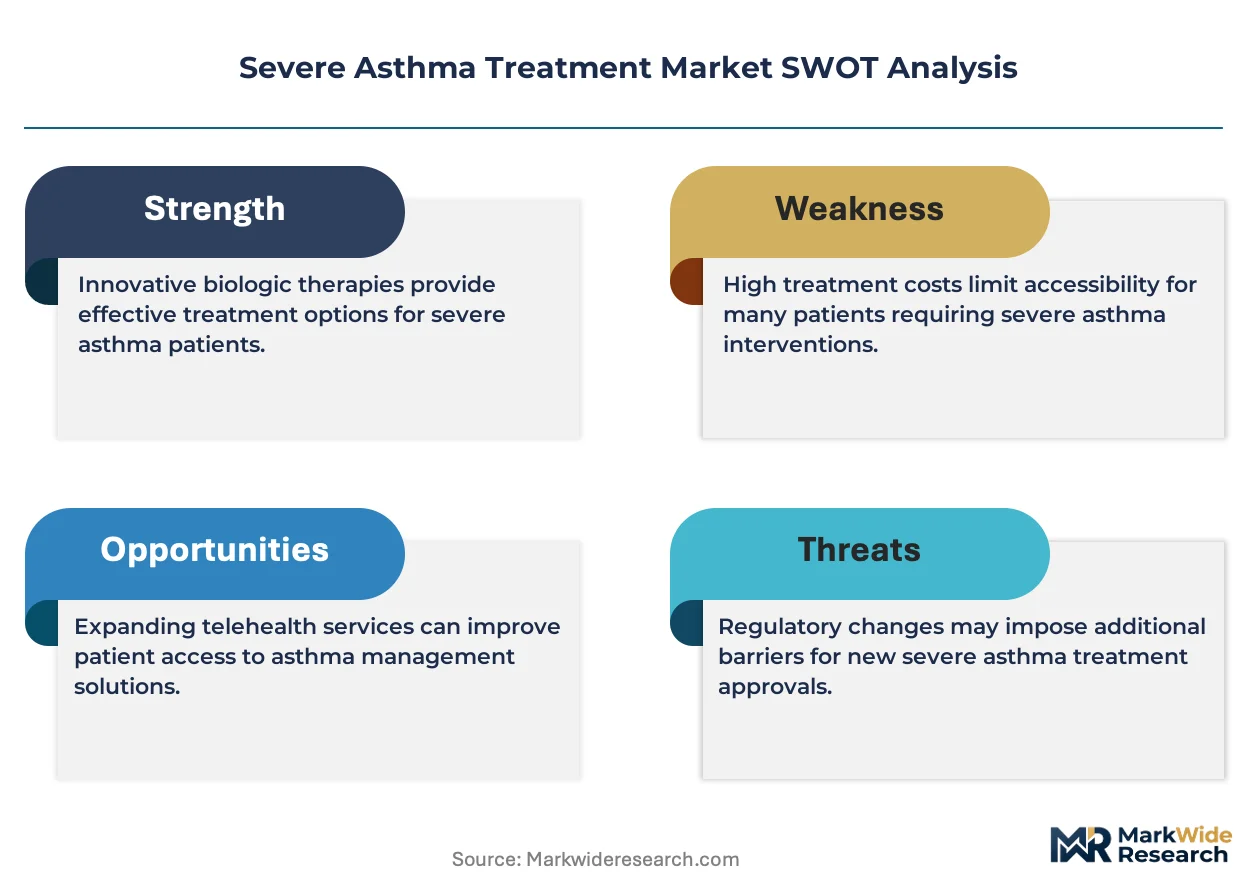
The FDA, EMA, and WHO collectively govern severe asthma treatment standards through biologics licensing requirements, Good Manufacturing Practice for active pharmaceutical ingredients, and Global Initiative for Asthma guideline harmonization. These frameworks shape demand by mandating extensive Phase III exacerbation reduction endpoints, post-marketing safety registries, and controlled distribution networks that favor established manufacturers with regulatory affairs scale. Stakeholders must monitor evolving payer evidence requirements for comparative effectiveness against standard-of-care triple therapy, as health technology assessment bodies tighten reimbursement conditions for biologic eligibility criteria.
Market Dynamics
Biologic therapy administration is migrating from hospital infusion centers toward patient-managed subcutaneous delivery, compressing the traditional specialist-dependent care model and redistributing clinical oversight toward remote monitoring platforms.
Growth Catalysts
- IL-4/13 and TSLP pathway expansion:Pulmonology departments in the United States are building dedicated severe asthma units to accommodate rising biologic patient volumes. Specialist training programs accelerate physician familiarity with monoclonal antibody selection protocols.
- FDA accelerated approval pathways:Reduced Phase III timeline requirements enable faster commercialization of novel biologics targeting refractory Type 2 inflammation. Post-marketing safety registries satisfy residual evidentiary obligations.
- Homecare infrastructure maturation:Self-administration training programs and cold-chain logistics networks enable patient-managed injection protocols. Remote patient monitoring platforms reduce hospital dependency for routine dosing.
Market Restraints
- Biologic manufacturing concentration:Active pharmaceutical ingredient production for monoclonal antibodies concentrates among contract manufacturers in Switzerland and Ireland. Single-source dependencies create supply vulnerability.
- Reimbursement eligibility stringency:Health technology assessment bodies in Germany and England tighten prior authorization requirements for biologic access. Blood eosinophil thresholds and exacerbation history mandates exclude borderline patients.
- Specialist workforce scarcity:Fellowship-trained pulmonologists with biologic prescribing authority remain concentrated in urban academic medical centers. Rural and suburban access gaps persist.
Strategic Opportunities
- Pediatric severe asthma specialization:Adolescent patient populations remain underpenetrated relative to adult biologic adoption. Sanofi and AstraZeneca are building dedicated pediatric trial infrastructure.
- Non-Type 2 inflammation targeting:Neutrophilic and paucigranulocytic severe asthma phenotypes lack approved biologic options. Small molecule and antisense programs address this white space.
- Integrated respiratory-dermatology-allergy care models:Atopic comorbidity clusters create opportunity for cross-specialty biologic prescribing. United States health systems are piloting multidisciplinary severe asthma centers.
Industry Challenges
- Comparative effectiveness evidence generation:Payer formularies demand head-to-head data against standard-of-care triple therapy. Clinical trial design complexity slows evidence accumulation.
- Cold-chain distribution integrity:Temperature excursion risks during last-mile delivery to patient homes threaten product stability. Logistics providers must validate continuous monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Severe Asthma Treatment Market |
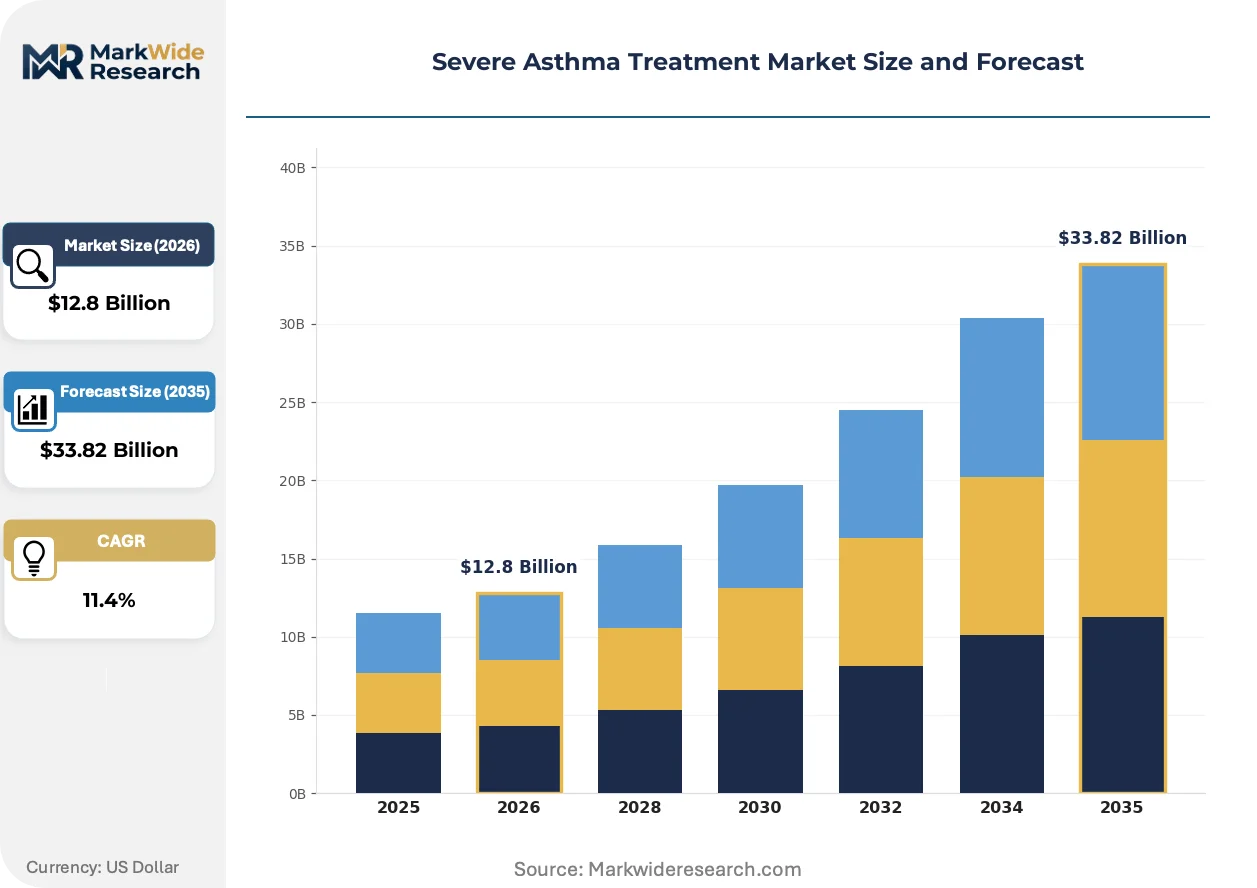
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Corticosteroids, Bronchodilators, Leukotriene Modifiers Delivery Mode: Inhalation, Oral, Injectable, Nebulization End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Respiratory Disorders, Immunology, Allergy Management, Emergency Care |
| Companies Covered | Novartis, Merck, GlaxoSmithKline, Regeneron Pharmaceuticals, Boehringer Ingelheim, Sanofi, Teva Pharmaceutical Industries, Johnson & Johnson, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Severe Asthma Treatment Market Evolving Landscape
Digital biomarker integration and patient-reported outcome capture are restructuring how treatment response gets measured and reimbursed in severe asthma management.
Next-generation IL-5 and IL-4 receptor antagonists with extended half-lives are absorbing quarterly dosing intervals previously reserved for small-molecule maintenance therapy. Adult severe asthma patients with high treatment burden prioritize reduced injection frequency. This compression of administration cadence is absorbing market share from earlier biologic entrants requiring monthly clinic visits.
EMA's evolving guidance on extrapolation of pediatric efficacy from adult trials is reshaping development timelines for adolescent indications. Manufacturers must now generate dedicated pharmacokinetic data in patients aged 12-17 rather than relying on bridging studies. European severe asthma programs are responding by establishing parallel pediatric trial cohorts earlier in Phase II.
Specialist prescribing decisions increasingly incorporate pharmacy benefit manager real-time formulary data at the point of care. Electronic health record integration with payer prior authorization platforms compresses approval timelines from weeks to hours. This behavioral shift is most visible in United States integrated delivery networks where biologic access coordinators manage administrative burden.
Severe Asthma Treatment Market Segmentation
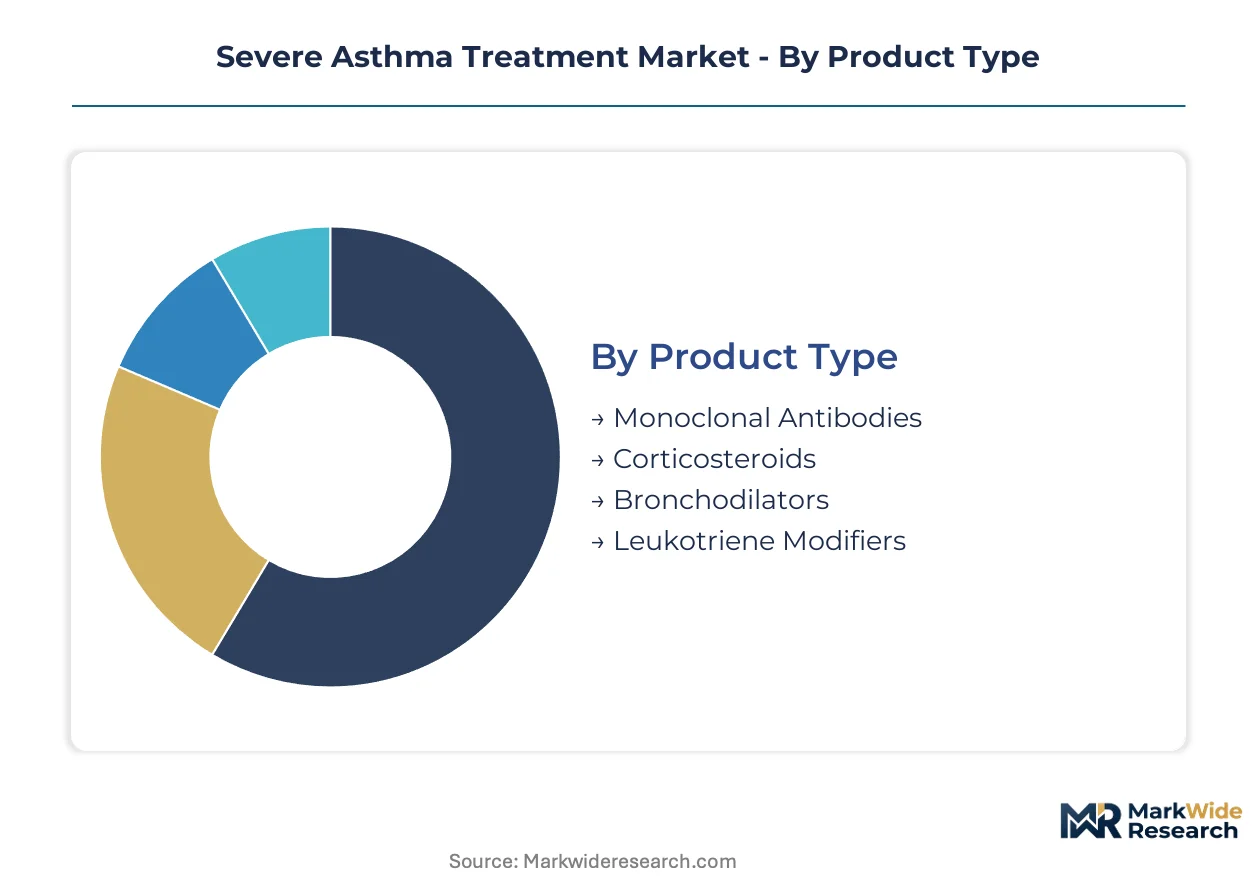
Severe asthma treatment segmentation reveals distinct value capture mechanisms across biological versus small-molecule interventions, with administration route and care setting determining reimbursement tiers and patient access pathways. Understanding these divisions enables precise targeting of uncontrolled Type 2 and non-Type 2 inflammatory phenotypes.
Product Type:
Standardization dominates corticosteroid and bronchodilator formulations while monoclonal antibodies demand extensive biomarker-driven customization for eosinophil and IgE stratification.
- Monoclonal Antibodies:Engineered immunoglobulins targeting IL-5, IL-4/13, IgE, and TSLP pathways require cold-chain handling and specialist administration protocols. United States pulmonology departments prioritize these agents for refractory patients meeting blood eosinophil thresholds, though prior authorization delays constrain access.
- Corticosteroids:Inhaled formulations achieve 10-40% lung deposition rates through metered-dose and dry-powder devices, serving as foundational maintenance therapy across all severity levels. German and English health technology assessment bodies scrutinize step-up timing to biologics.
- Bronchodilators:Long-acting beta-agonists and muscarinic antagonists provide symptomatic relief through smooth muscle relaxation.
- Leukotriene Modifiers:Oral small-molecule inhibitors of cysteinyl leukotriene receptors address mild-to-moderate persistent disease.
Leading the category by volume: Corticosteroids. Growing fastest: Monoclonal Antibodies.
Delivery Mode:
Cost tier stratification separates premium injectable biologics from commoditized inhalation generics, with nebulization occupying a mid-tier hospital niche.
- Injectable:Subcutaneous monoclonal antibodies command premium pricing due to cold-chain logistics, specialist oversight requirements, and superior exacerbation reduction data in refractory populations. United States homecare programs now train patients for self-administration at 2-4 week intervals.
- Inhalation:Metered-dose and dry-powder inhalers dominate maintenance therapy volume through convenient daily dosing, with lung deposition efficiency varying by device engineering and patient technique.
- Oral:Systemic corticosteroids and leukotriene modifiers address acute exacerbations and maintenance in resource-constrained settings.
- Nebulization:Aerosolized delivery suits hospitalized acute presentations and pediatric populations with coordination limitations.
Highest margin capture: Injectable. Steepest volume expansion: Inhalation.
End User:
Patient acuity and reimbursement sophistication determine channel selection, with integrated delivery networks consolidating purchasing power.
- Hospitals:Academic medical centers anchor severe asthma unit development, administering initial biologic doses and managing acute exacerbations requiring intensive care. United States urban centers concentrate fellowship-trained pulmonologists with biologic prescribing authority.
- Homecare:Remote patient monitoring platforms and self-administration training programs redistribute routine biologic dosing away from infusion centers, compressing costs and improving adherence in stable patients.
- Clinics:Community pulmonology and allergy practices manage maintenance therapy and biologic continuation.
- Pharmacies:Retail and specialty pharmacies handle oral medication dispensing and device distribution.
Leading the category by volume: Hospitals. Expanding most quickly: Homecare.
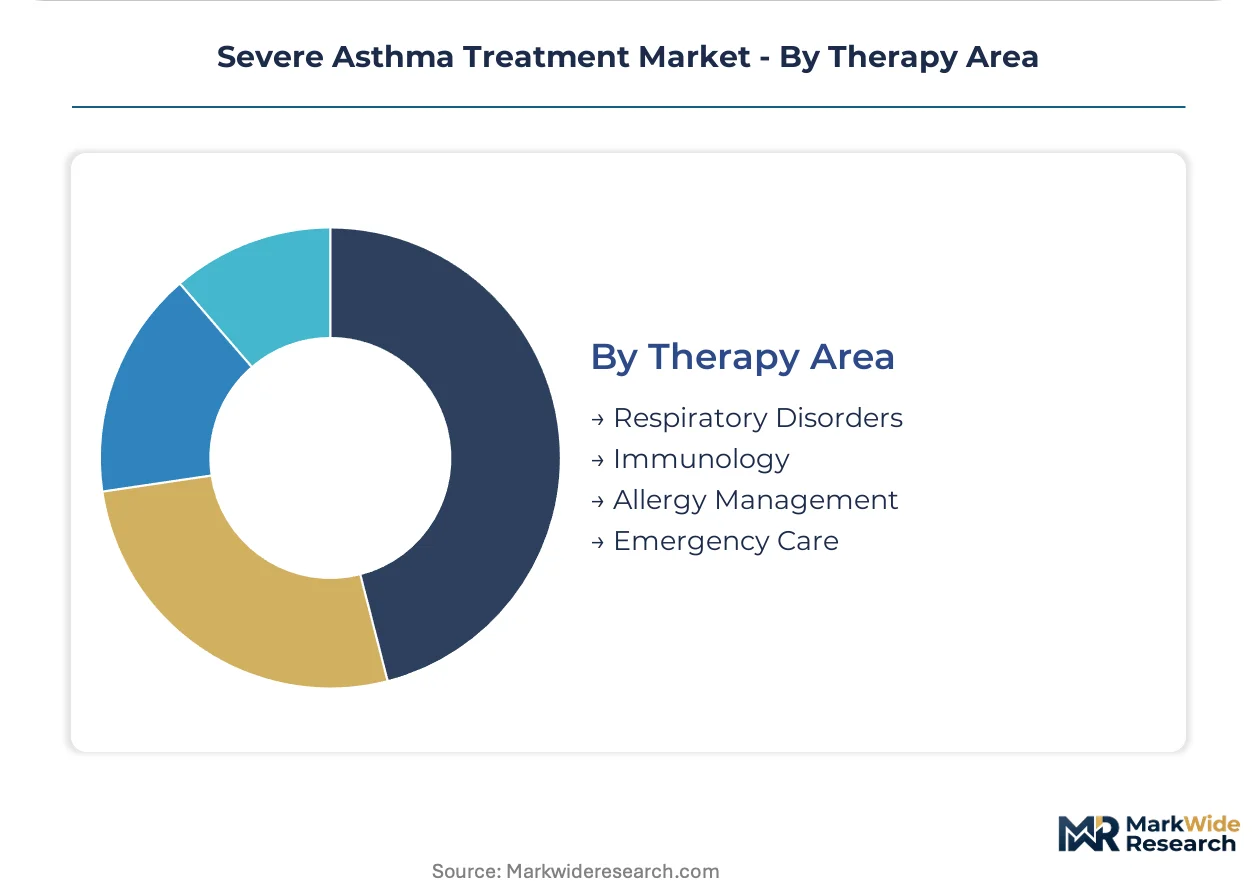
Therapy Area:
Application breadth ranges from single-specialty respiratory management to multidisciplinary atopic disease clusters requiring cross-functional coordination.
- Respiratory Disorders:Dedicated pulmonology programs target Type 2 inflammation through eosinophil-guided biologic selection, with exacerbation reduction serving as the primary efficacy endpoint in Phase III trials mandated by FDA and EMA.
- Immunology:Cross-specialty prescribing addresses systemic inflammation comorbidities including atopic dermatitis and chronic rhinosinusitis with nasal polyps, creating opportunity for biologic therapy expansion beyond traditional respiratory indications.
- Allergy Management:Allergist-directed care emphasizes IgE-mediated mechanisms and allergen immunotherapy integration.
- Emergency Care:Acute exacerbation management prioritizes rapid bronchodilation and systemic corticosteroid initiation.
Largest addressable population: Respiratory Disorders. Fastest indication expansion: Immunology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States patients generate the dominant share of biologic therapy demand, with reimbursement density and specialist concentration creating asymmetric market pull. Germany and England shape European access through health technology assessment stringency. Japan and Australia represent high-value smaller markets with distinct regulatory pathways.
United States
Commercial insurers and Medicare Part D cover biologic therapies for patients meeting blood eosinophil thresholds, driving hospital-based severe asthma unit expansion. FDA accelerated approval pathways enable faster market entry for IL-4/13 and TSLP inhibitors. Boston and New York academic medical centers anchor specialist training programs that diffuse prescribing protocols nationally.
Germany
The Institute for Quality and Efficiency in Health Care mandates comparative effectiveness evidence against triple therapy for biologic reimbursement. Bavaria and North Rhine-Westphalia concentrate pulmonology departments with biologic prescribing authority. German hospitals participate in post-marketing registries that satisfy EMA pharmacovigilance requirements.
United Kingdom
NICE technology appraisals restrict biologic access to patients with documented exacerbation histories and elevated biomarkers. London and Manchester severe asthma centers pilot integrated respiratory-dermatology-allergy care models. NHS England's specialized commissioning framework centralizes high-cost drug funding decisions.
Japan
PMDA reviews require Japan-specific exacerbation endpoint data rather than extrapolation from Western trials. Tokyo and Osaka academic hospitals lead severe asthma biologic adoption in Asia-Pacific. Japanese insurers reimburse biologics under the high-cost medical care benefit system with patient copayment caps.
Australia
The Pharmaceutical Benefits Scheme subsidizes biologics through restricted benefit listings requiring specialist application. Melbourne and Sydney severe asthma clinics manage patient enrollment in PBS-subsidized therapy programs. The Therapeutic Goods Administration aligns biologics registration requirements with FDA and EMA precedents.
Severe Asthma Treatment Market Competitive Landscape
Swiss and Anglo-American pharmaceutical conglomerates anchor the premium biologic tier; mid-cap specialty biotech firms hold development-stage positions. Market structure concentrates around five to seven entities with approved monoclonal antibodies, creating high barriers for novel entrants. Two strategic archetypes dominate: diversified respiratory franchises leveraging inhaled-to-biologic patient transitions, and immunology-specialized developers targeting Type 2 inflammation across multiple indications. Competitive dynamics center on pediatric label expansion and quarterly-dosing formulation development.
Within the diversified respiratory archetype, AstraZeneca and GlaxoSmithKline occupy positions spanning inhaled maintenance through injectable biologic portfolios. Novartis anchors the immunology-specialized tier with cross-indication biologic development capabilities. Sanofi represents the pediatric-focused vector with dedicated adolescent trial infrastructure. These three entities exemplify how manufacturer scale and therapeutic area concentration shape competitive positioning in severe asthma biologics.
| Leading Market Players |
|---|
| Novartis |
| Merck |
| GlaxoSmithKline |
| Regeneron Pharmaceuticals |
| Boehringer Ingelheim |
| Sanofi |
| Teva Pharmaceutical Industries |
| Johnson & Johnson |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract manufacturing organizations in Switzerland and Ireland concentrate active pharmaceutical ingredient production for monoclonal antibodies, tightening supply discipline while enabling premium pricing for biologics with validated cold-chain integrity. This ownership pattern reinforces pricing power at the top tier while compressing margins for undifferentiated small-molecule inhalation generics.
Pricing Analysis
Short lead-time premiums for cold-chain biologics with validated distribution records command 15-25% markups over standard delivery windows, while spot inventory of inhalation devices trades at discounts. Three-tier pricing structure across premium biologics, standard maintenance inhalers, and economy oral generics dominates the market. Price differentiation rests on FDA approval tier and biomarker stratification requirements. Cost compression in the economy oral tier is intensifying because of Indian API import competition. Hospital procurement committees exhibit highest price sensitivity for maintenance therapies, while homecare channels accept premium pricing for self-administered biologics.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital systems and European health technology assessment bodies mandate multi-supplier qualification for monoclonal antibody active pharmaceutical ingredients. Supply concentration centers on Switzerland, Ireland, and Singapore for biologic drug substance production. Raw material dependencies include Chinese-sourced recombinant cell culture media, German-engineered single-use bioreactor systems, and Swiss-controlled fill-finish capacity. Single-source vulnerability in IgG purification resin supply threatens continuity. Distribution runs through validated cold-chain logistics providers with continuous temperature monitoring to patient homes and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration race dynamics dominate severe asthma biologics as manufacturers pursue captive control over fill-finish capacity to secure supply continuity and margin defense against contract manufacturing price escalation.
For Market Incumbents: Acquire dedicated pediatric trial infrastructure and adolescent patient registry databases to preempt Sanofi's positioning in this underpenetrated segment. Consolidate backward integration into single-use bioreactor manufacturing to reduce dependency on German engineering suppliers facing extended lead times. Regulatory shifts toward EMA pediatric extrapolation requirements threaten late entrants without existing 12-17 age cohort data. For New Entrants and Emerging Players: The premium-economy price-point gap in homecare-administered biologics creates entry space for biosimilar developers with validated cold-chain partnerships. Target rural and suburban pulmonology clinics lacking biologic prescribing authority as the most penetrable channel. A go-to-market angle anchored in remote patient monitoring platform bundling differentiates against hospital-dependent incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biotech firms with Phase II-ready TSLP inhibitors in the United States and European markets. Long-term viability across the analysis window hinges on quarterly-dosing formulation moats and pediatric label expansion timing. Watch FDA breakthrough therapy designation grants as the signal for inflection in competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II pediatric cohort initiation satisfies EMA extrapolation guidance and accelerates label expansion timelines. |
| Manufacturing Scale-Up | Captive fill-finish capacity in Switzerland or Ireland insulates against contract manufacturer pricing power. |
| Regulatory Approval Pathway | FDA accelerated approval leveraging biomarker-enriched designs compresses commercialization timelines for IL-4/13 inhibitors. |
| Pipeline Diversification | Non-Type 2 inflammation programs address neutrophilic phenotypes lacking approved biologic options. |
| Strategic Partnership | Remote patient monitoring platform alliances enable homecare channel expansion and reduce hospital dependency. |
Research Methodology
Multi-period observation of biologic patient enrollment rates, prior authorization approval timelines, and hospital severe asthma unit expansion anchored the trend analysis, supplemented by interviews with drug development executives at top-ten respiratory franchises, regulatory affairs leads managing FDA and EMA submissions, formulary directors at United States pharmacy benefit managers, and hospital procurement managers overseeing biologic contracting. Secondary validation drew from FDA biologics licensing application filings, EMA European public assessment reports, ClinicalTrials.gov protocol registries, and IQVIA formulary impact data. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation cross-checked volume estimates.
Segment-weighting approaches applied differential growth assumptions across monoclonal antibodies, corticosteroids, bronchodilators, and leukotriene modifiers, with further stratification by injectable versus inhalation versus oral delivery modes. Treatment line positioning, biomarker stratification requirements, patient age cohorts, and regional regulatory clusters shaped the analytical framework across the projection horizon. CAGRs derived from log-linear trend fitting to historical biologic adoption curves, adjusted for pipeline entry probability and health technology assessment reimbursement stringency indices.
Underlying measurement precision varies by segment; monoclonal antibody value estimates carry tighter precision than emerging non-Type 2 small-molecule categories with sparse clinical data. Forecasts reflect assumptions regarding FDA approval timelines, EMA pediatric guidance stability, and United States Medicare Part D reimbursement continuity. Deviation in health technology assessment body stringency or biologic manufacturing concentration events would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Penile Cancer Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
Global Rotator Cuff Treatment Market