
 Europe Nerve Repair and Regeneration Market | 2026-2036
Europe Nerve Repair and Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nerve Repair and Regeneration Market Analytics
Rehabilitation centers is redrawing procurement priorities as post-surgical nerve recovery protocols expand across Europe. Medtronic leverages its neurostimulation portfolio to anchor positions in peripheral nerve repair workflows. Stryker competes through specialized conduit geometries that address brachial plexus reconstruction. Polyganics B.V. differentiates with bioresorbable nerve wraps that reduce secondary explantation procedures.
Nerve repair and regeneration encompasses surgical interventions and biological products that restore structural continuity and functional signaling across damaged neural tissue, typically employing collagen matrices, synthetic polymers, or autologous grafts with porosity calibrated to support Schwann cell migration and axonal sprouting. The primary commercial purpose centers on restoring motor and sensory function following traumatic injury, oncological resection, or compressive neuropathies. Nerve conduits command the largest revenue pool among product types due to standardized deployment in gap injuries under three centimeters, while cell therapy represents the fastest-expanding segment as allogeneic Schwann cell platforms advance through European trial networks. Neurostimulation technology dominates procedural volume in hospitals, though tissue engineering approaches are capturing margin concentration through premium-priced bioengineered grafts.
The EU Medical Device Regulation and EMA oversight of advanced therapy medicinal products impose escalating clinical evidence burdens that filter market access for novel cell-based approaches. CE marking requirements under MDR extend conformity assessment timelines, compressing commercialization windows for academic spinouts and mid-tier manufacturers. Stakeholders must monitor reimbursement negotiations between national health technology assessment bodies and biomaterial suppliers, as divergent valuation methodologies across France, Germany, and Italy will determine which nerve regeneration modalities achieve sustainable adoption.
Market Dynamics
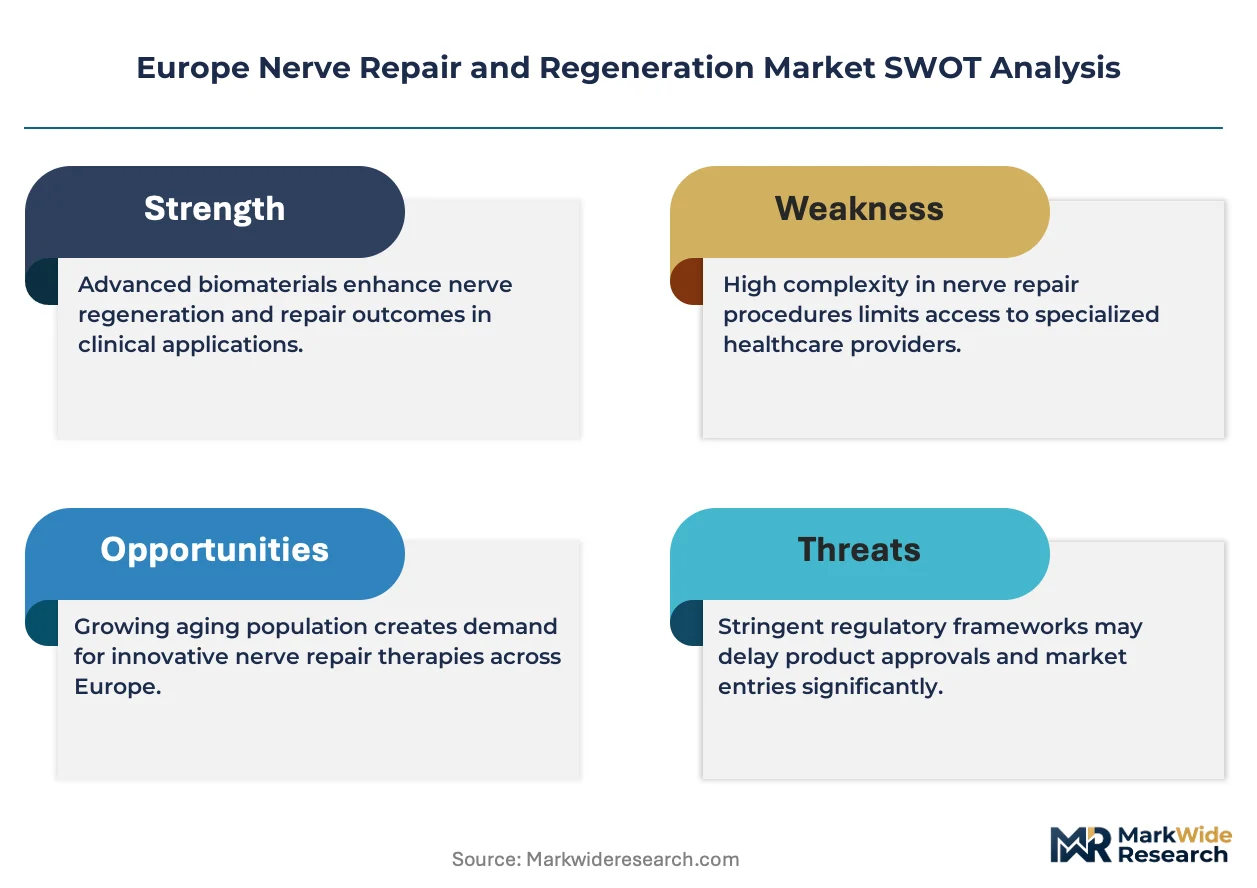
The EU Medical Device Regulation is compressing commercialization timelines for nerve repair manufacturers while simultaneously elevating clinical evidence thresholds that academic spinouts struggle to meet. This regulatory recalibration favors established biomaterial suppliers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Bioresorbable polymer platforms:Germany's orthopedic clusters are accelerating procurement of nerve wraps that eliminate secondary explantation procedures, reducing total episode costs for hospital systems.
- EMA advanced therapy pathways:The centralized marketing authorization procedure for allogeneic Schwann cell products is creating harmonized access across member states that previously required fragmented national approvals.
- Trauma center consolidation:France and the United Kingdom are concentrating peripheral nerve repair volumes in designated supra-regional centers, standardizing uptake of conduit-based reconstruction protocols.
Market Restraints
- Collagen raw material volatility:Bovine-derived scaffold inputs face supply uncertainty from BSE-related import restrictions and slaughterhouse capacity constraints in Eastern Europe.
- CE marking timeline extension:MDR conformity assessment procedures now average 18-24 months for Class III implantable devices, straining cash reserves of development-stage manufacturers.
- Autograft persistence:Sural nerve harvesting remains the default for gap injuries exceeding 3 centimeters in Italian and Spanish public hospitals with limited biomaterial reimbursement.
Strategic Opportunities
- Poland and Romania hospital networks:Underpenetrated Eastern European markets present first-mover advantages for conduit suppliers establishing distributor relationships ahead of reimbursement formalization.
- Neurostimulation-tissue engineering convergence:Combined electrical stimulation and biological scaffold protocols are opening premium-priced procedural categories in German university hospitals.
- EU Green Deal procurement criteria:Sustainability-linked tender requirements are favoring manufacturers with biodegradable polymer supply chains and reduced sterilization energy footprints.
Industry Challenges
- Schwann cell manufacturing scale-up:GMP-compliant expansion of allogeneic cell banks requires capital-intensive cleanroom infrastructure that exceeds typical orthopedic device manufacturing footprints.
- Clinical investigator network scarcity:Qualified European sites capable of executing nerve function outcome studies are concentrated in Germany, France, and the Netherlands, creating recruitment bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nerve Repair and Regeneration Market |
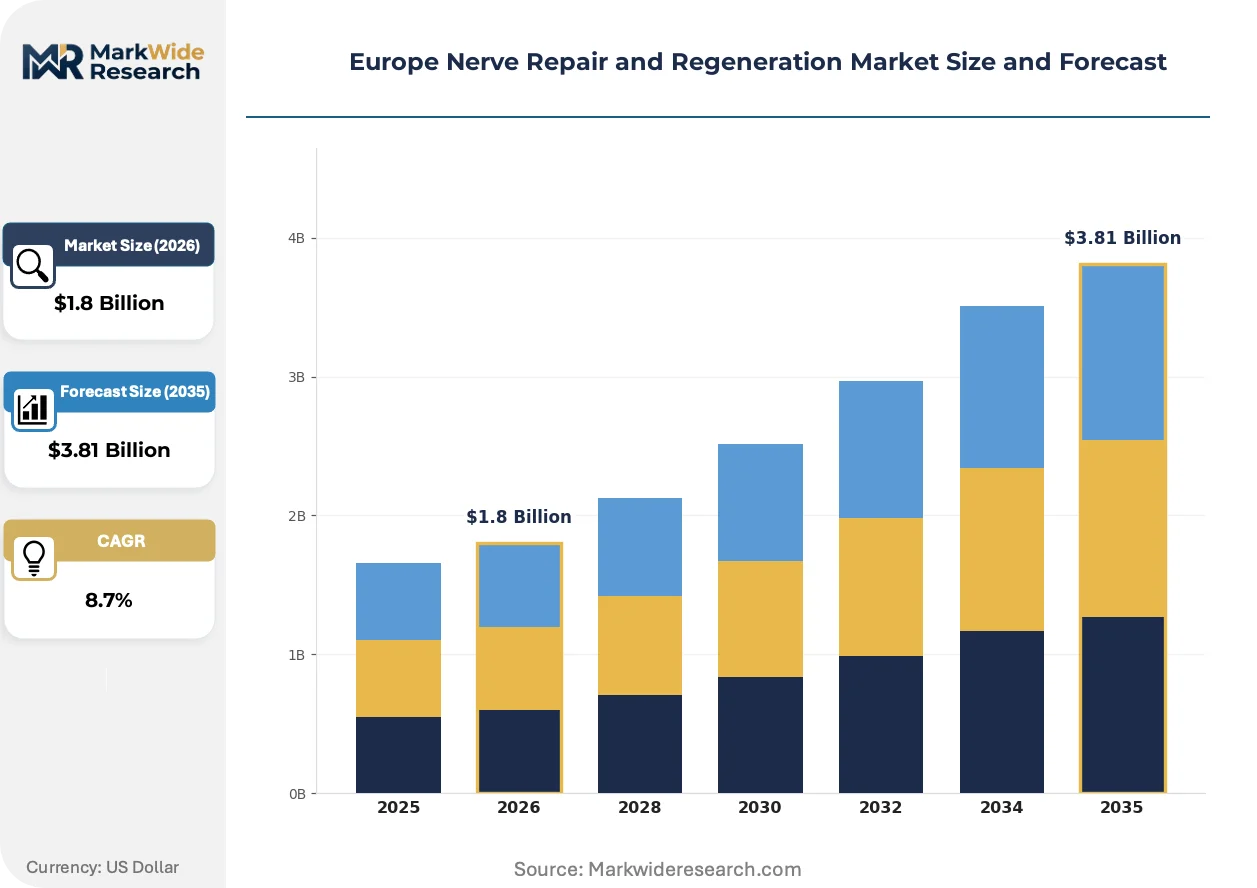
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Grafts, Nerve Conduits, Nerve Wraps, Cell Therapy End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Application: Peripheral Nerve Repair, Central Nerve Repair, Cranial Nerve Repair, Nerve Reconstruction Technology: Neurostimulation, Tissue Engineering, Biomaterials, Cell-Based Approaches |
| Companies Covered | Medtronic, Axogen Corporation, Boston Scientific Corporation, Integra LifeSciences Corporation, Polyganics B.V., Stryker, LivaNova PLC, Abbott Laboratories, Checkpoint Surgical, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nerve Repair and Regeneration Market Evolving Landscape
Peripheral nerve repair is undergoing material science transformation as synthetic polymer platforms challenge collagen dominance while regulatory frameworks force evidence generation at unprecedented scale. Three interconnected developments are restructuring competitive positioning.
Multichannel synthetic nerve conduits with oriented internal topography are bifurcating the gap injury market between premium bioengineered options and commodity hollow tubes. German trauma centers are adopting these platforms for brachial plexus reconstruction at accelerating velocity. The technology is bifurcating procurement committees into specialized peripheral nerve units distinct from general orthopedic implant evaluation.
MDR Article 54 expert panel consultations for novel biomaterial implants are extending time-to-revenue for European manufacturers by 12-18 months. The industrial consequence is consolidation of regulatory expertise within larger diversified medical device corporations. Cell therapy developers with ATMP classification face the steepest delays, redirecting investment toward notified body relationship cultivation.
Hospital purchasing committees are unbundling nerve repair procurement from bundled payment orthopedic contracts, creating standalone category management. Specialized peripheral nerve coordinators are displacing general surgical buyers in France and the United Kingdom. This shift is most visible in German university hospital clusters where dedicated nerve reconstruction service lines command independent capital allocation authority.
Europe Nerve Repair and Regeneration Market Segmentation
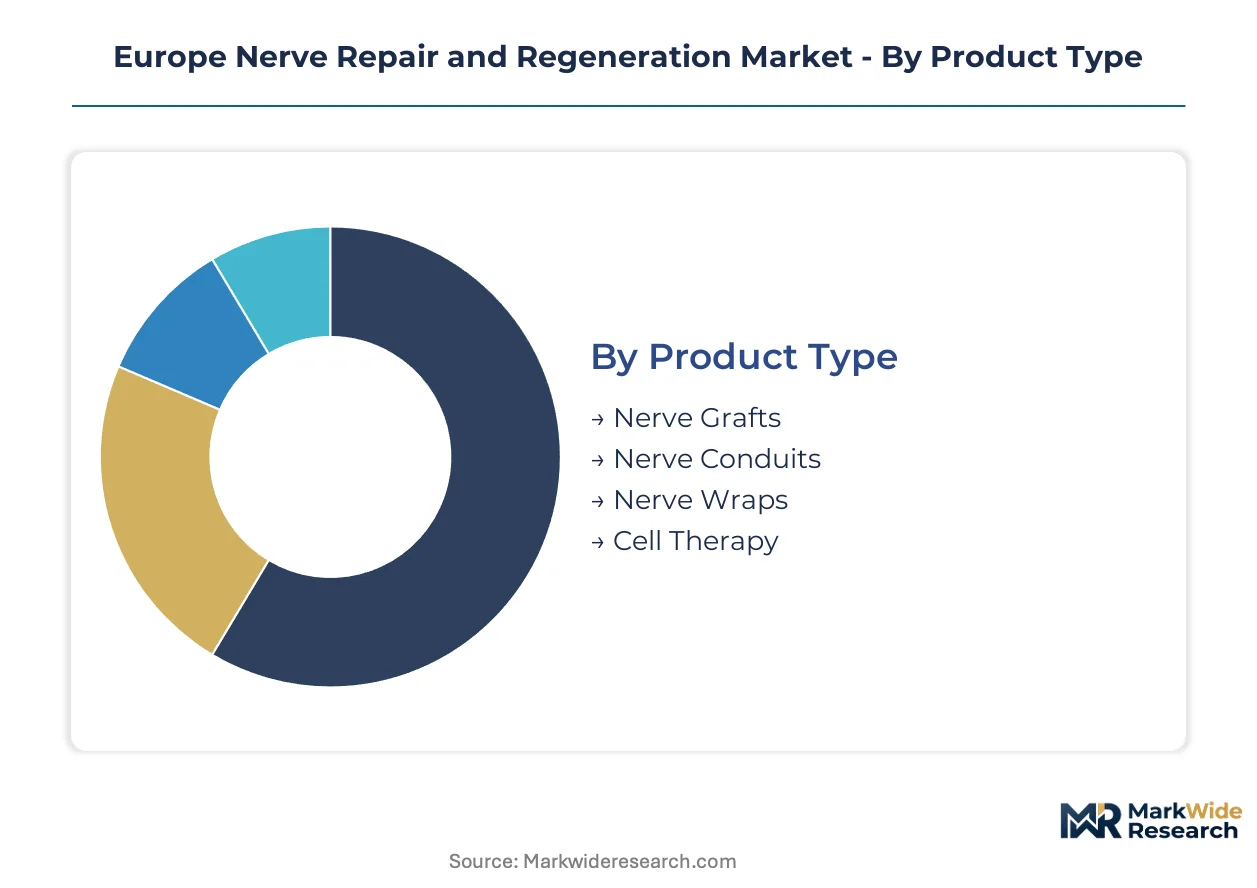
Nerve repair procurement in Europe fragments across four intersecting dimensions that determine reimbursement pathways and clinical adoption velocity. Product type distinctions govern hospital budget allocation, while end-user concentration shapes distributor channel economics.
Product Type:
Autograft substitution pressure falls heaviest on commodity nerve conduits as synthetic polymer platforms close the performance gap at lower total episode cost.
- Nerve Grafts:Autologous sural nerve segments remain the structural gold standard for gap injuries exceeding three centimeters, though harvest-site morbidity drives procurement committees toward alternatives in German trauma centers.
- Nerve Conduits:Hollow collagen and synthetic polymer tubes dominate gap injuries under three centimeters, with multichannel internal topography variants capturing premium positioning in French and UK peripheral nerve units.
- Nerve Wraps:Bioresorbable polymer sheaths for nerve coaptation and protection are displacing autologous vein grafts in German orthopedic clusters seeking reduced secondary procedure burden.
- Cell Therapy:Allogeneic Schwann cell platforms under EMA advanced therapy pathways face the steepest regulatory burden but command concentrated investment from university hospital networks.
Nerve conduits anchor the volume base while cell therapy gains share at the steepest rate.
End User:
Procurement authority is migrating toward specialized coordinators as service line unbundling accelerates across European hospital systems.
- Hospitals:Supra-regional trauma centers in France and the United Kingdom concentrate peripheral nerve repair volumes, with dedicated nerve reconstruction service lines commanding independent capital allocation authority.
- Clinics:Private hand surgery and orthopedic clinics in Germany and Switzerland drive outpatient conduit adoption where reimbursement pathways for biomaterial implants have matured.
- Research Institutions:Academic medical centers in the Netherlands and Belgium host EMA-registered clinical trial networks for cell-based approaches, creating investigator site scarcity.
- Rehabilitation Centers:Post-surgical recovery protocols in German and Austrian neurorehabilitation facilities are redrawing procurement priorities for adjunctive neurostimulation devices.
Hospitals dominate current revenue concentration while rehabilitation centers are expanding most quickly as bundled episode payments extend into post-acute phases.
Application:
Volume distribution reflects the anatomical burden of traumatic injury and oncological resection across European surgical caseloads.
- Peripheral Nerve Repair:Upper extremity trauma and iatrogenic injury reconstruction command the largest procedure count, with brachial plexus cases driving adoption of premium conduit geometries in German university hospitals.
- Central Nerve Repair:Spinal cord and cauda equina interventions remain constrained by blood-brain barrier limitations, though scaffold-based approaches are advancing through French neurosurgical trial networks.
- Cranial Nerve Repair:Facial nerve reconstruction following parotidectomy and skull base surgery concentrates in specialized head and neck centers in the United Kingdom and Italy.
- Nerve Reconstruction:Complex multilevel injuries requiring combined graft and conduit strategies are capturing disproportionate margin concentration in German and Austrian referral networks.
Peripheral nerve repair holds the established volume position while cranial nerve applications are climbing the fastest as microsurgical technique diffusion expands addressable caseloads.
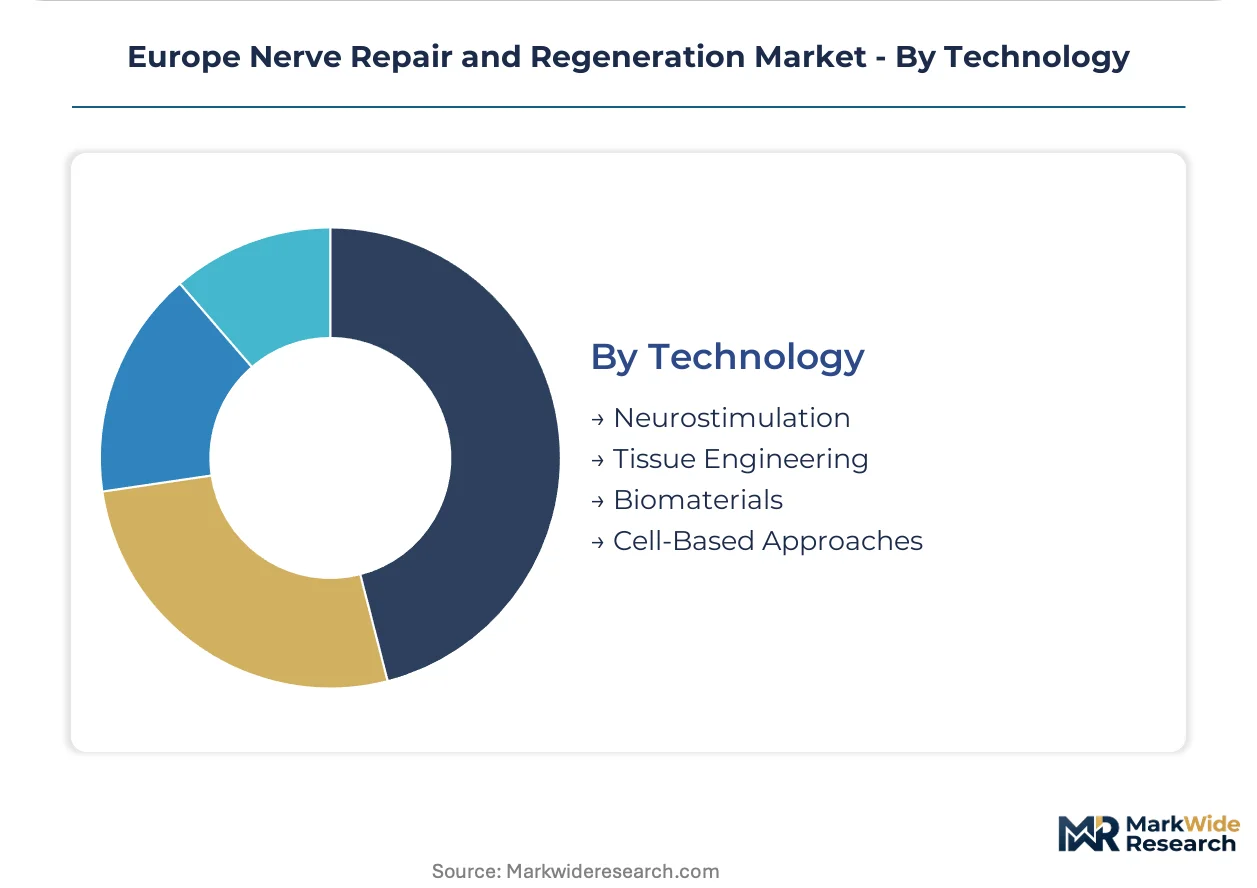
Technology:
Margin capture is bifurcating between commoditized stimulation hardware and premium biological platforms requiring GMP manufacturing infrastructure.
- Neurostimulation:Peripheral and transcutaneous electrical stimulation devices dominate procedural volume in acute and rehabilitation settings, with German hospitals leading combined stimulation-conduit protocol adoption.
- Tissue Engineering:Decellularized matrices and oriented scaffold architectures are displacing commodity collagen in French and UK procurement committees seeking functional outcome differentiation.
- Biomaterials:Synthetic polymer platforms with tunable degradation kinetics are challenging bovine-derived collagen dominance as EU Green Deal procurement criteria elevate sustainability-linked tender evaluation.
- Cell-Based Approaches:Allogeneic Schwann cell and induced pluripotent stem cell products face the longest MDR and ATMP approval timelines but command the highest price positioning in pre-commercial European networks.
Neurostimulation technology captures the broadest installed base while tissue engineering approaches are expanding most quickly as material science platforms mature through notified body conformity assessment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine rail freight corridor underwrites Germany's dominance in European nerve repair logistics, connecting industrial clusters from Rotterdam through Basel to Milan with dedicated pharmaceutical cold-chain capacity.
Germany
Bavarian university hospitals and North Rhine-Westphalian trauma centers drive procurement of multichannel nerve conduits for brachial plexus reconstruction. The BfArM and DIMDI coordinate national reimbursement dossiers for biomaterial implants through the G-BA benefit assessment process. Berlin-Brandenburg hosts the densest concentration of EMA-registered clinical trial sites for cell-based approaches.
France
Supra-regional trauma center consolidation in Île-de-France and Auvergne-Rhône-Alpes concentrates peripheral nerve repair volumes under standardized procurement protocols. ANSM oversight of Class III implantable devices operates alongside HAS health technology assessment for hospital reimbursement. The Lyon-Grenoble medical technology corridor anchors specialized peripheral nerve coordinator roles.
United Kingdom
NHS England specialized commissioning for complex nerve injuries funnels cases to designated supra-regional centers in London and the Midlands. The MHRA's post-Brexit regulatory framework maintains CE marking recognition while building UKCA capacity for novel conduit platforms. Greater Manchester and Sheffield teaching hospitals lead adoption of combined neurostimulation-conduit protocols.
Netherlands
Academic medical centers in Amsterdam and Leiden host investigator networks for EMA advanced therapy medicinal product trials. The Dutch Healthcare Authority (NZa) negotiates outcome-based reimbursement for nerve regeneration modalities through conditional coverage frameworks. The Eindhoven-Tilburg biomedical cluster concentrates cleanroom manufacturing infrastructure for resorbable polymer platforms.
Switzerland
Swissmedic's streamlined marketing authorization for breakthrough devices attracts development-stage manufacturers seeking faster European access. Zurich and Geneva university hospitals command premium pricing for complex nerve reconstruction through supplemental insurance channels. The Basel pharmaceutical corridor provides contract GMP manufacturing capacity for allogeneic cell therapy scale-up.
Europe Nerve Repair and Regeneration Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates possessing dedicated MDR regulatory infrastructure. The vendor base separates into three functional tiers: multinational platform suppliers with neurostimulation portfolios, specialized biomaterial developers with notified body relationships, and academic spinouts advancing cell therapy candidates. Consolidation pressure favors acquisition of conduit geometry IP and GMP manufacturing capabilities over greenfield capacity expansion.
Among the diversified technology tier, Medtronic and Stryker occupy positions spanning neurostimulation hardware and biological scaffold platforms. Polyganics B.V. exemplifies the specialized biomaterial archetype with its Dutch-registered focus on resorbable nerve wraps. These three represent the competitive spectrum from scale-driven conglomerate to focused conduit innovator.
| Leading Market Players |
|---|
| Medtronic |
| Axogen Corporation |
| Boston Scientific Corporation |
| Integra LifeSciences Corporation |
| Polyganics B.V. |
| Stryker |
| LivaNova PLC |
| Abbott Laboratories |
| Checkpoint Surgical |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with German trauma centers lock in supply access for multichannel nerve conduit manufacturers while anchoring price visibility across the MDR conformity assessment window. These arrangements buffer academic spinouts from cash flow strain during extended CE marking timelines.
Pricing Analysis
Volume-discount tiering separates premium multichannel conduits from standard hollow tubes and economy collagen segments in French and UK procurement committees. Price differentiation hinges on GMP certification grade and after-sales clinical training bundling. Cost compression in the economy tier is intensifying as Eastern European distributors enter with synthetic polymer alternatives. Public hospital systems in Italy and Spain exhibit the sharpest price sensitivity, while German university hospitals prioritize functional outcome metrics over unit cost.
Supply Chain Analysis
Bovine collagen purification capacity in Eastern European slaughterhouses constitutes a chokepoint for scaffold manufacturers serving the European market. Raw material sourcing draws from cattle operations in Poland, Romania, and Hungary, with sterilization packaging inputs anchored in German industrial clusters. Single-source vulnerability concentrates in GMP-certified cleanroom infrastructure for allogeneic Schwann cell expansion. Distribution runs through specialized orthopedic distributor networks with cold-chain capability, bypassing general surgical implant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The convergence of neurostimulation hardware and biological scaffolds is creating platform-economics dynamics where interoperability standards will determine winner-take-most positioning. EMA's centralized ATMP pathway is accelerating this ecosystem consolidation.
For Market Incumbents: Fortify regulatory affairs infrastructure ahead of MDR Article 54 expert panel consultations, which now extend time-to-revenue by 12-18 months for novel biomaterial implants. Acquire GMP manufacturing capabilities for allogeneic cell therapy scale-up before cleanroom capacity scarcity hardens. The threat of academic spinouts with breakthrough conduit geometries demands preemptive IP consolidation in oriented scaffold architectures. For New Entrants and Emerging Players: Lead with specialized peripheral nerve coordinator relationships in French and UK supra-regional trauma centers, where procurement authority has unbundled from general orthopedic contracts. Poland and Romanian hospital networks present the most penetrable geography ahead of reimbursement formalization. A go-to-market angle combining biodegradable polymer platforms with EU Green Deal sustainability credentials opens tender pathways closed to incumbent suppliers. For Investors and Strategic Acquirers: Dutch-registered resorbable polymer specialists with established notified body relationships represent the most defensible acquisition archetype in a market filtering for MDR compliance capability. Long-term viability rests on convergence plays bridging electrical stimulation and biological scaffold protocols. Watch for inflection when German university hospitals standardize combined-modality reimbursement codes.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Acceleration | Compresses time-to-revenue for Class III implantable devices in German notified body pipelines. |
| EMA Advanced Therapy Pathway Navigation | Harmonizes allogeneic Schwann cell access across member states via centralized marketing authorization. |
| Peripheral Nerve Coordinator Partnership | Captures procurement authority migration in French and UK hospital systems unbundling service lines. |
| GMP Cleanroom Infrastructure Buildout | Resolves manufacturing scale-up bottlenecks for cell therapy platforms exceeding typical orthopedic footprints. |
| EU Green Deal Certification Positioning | Aligns biodegradable polymer supply chains with sustainability-linked tender evaluation criteria in German clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the European nerve repair ecosystem, including peripheral nerve surgeons, hospital purchasing committee coordinators, biomedical engineers at trauma centers, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from EMA submission databases, MDR conformity assessment records, hospital procurement databases, and G-BA benefit assessment dossiers. Bottom-up procedure volume estimates triangulated against top-down biomaterial implant expenditure flows.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, end-user concentration, application anatomy, and technology platform maturity. CAGRs derived from logistic diffusion curves calibrated to reimbursement pathway adoption velocity and surgical volume trajectories in German, French, and UK trauma center networks. Industry-specific inputs incorporated MDR transition timelines and EMA ATMP registration progressions.
Forecasts assume regulatory continuity in EU MDR and EMA advanced therapy frameworks; material policy shifts would require re-modeling of commercialization timelines and market access probabilities. Practitioners should keep alternative scenarios live as national health technology assessment methodologies and reimbursement negotiation outcomes evolve across France, Germany, and Italy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Corneal Transplant Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Global Acromegaly Treatment Market