
 Iris Retractors Market | 2026-2036
Iris Retractors Market Size, Share, and Industry Trends Forecast 2026-2036
Iris Retractors Market Insights
Ambulatory surgical centers is restructuring the Iris Retractors Market as outpatient ophthalmic procedures shift away from traditional hospital settings. Alcon leverages its integrated surgical platform to bundle retractors with phacoemulsification systems, locking in recurring consumable revenue. Katalyst Surgical specializes in premium titanium and stainless steel reusable lines that appeal to cost-conscious European clinics. ASICO LLC competes through deep catalog breadth across fixed and self-retaining configurations.
Iris retractors are mechanical devices designed to dilate and stabilize the pupil during intraocular surgery, typically manufactured from stainless steel, polypropylene, or silicone with hook counts ranging from four to six and engagement angles calibrated to minimize sphincter trauma. Disposable polypropylene variants dominate volume due to elimination of reprocessing liability, while reusable stainless steel retains margin concentration in academic medical centers with sterile processing infrastructure. Silicone and biocompatible material segments are gaining traction where surgeons prioritize reduced corneal endothelial touch rates. Application demand clusters heavily in cataract surgery, though glaucoma surgery represents a faster-growing pocket as microinvasive techniques proliferate.
FDA 510(k) premarket notification requirements govern US market entry, while EU MDR and CE marking obligations impose expanded clinical evidence burdens on manufacturers seeking European access. Japan's PMDA enforces Japan Industrial Standards compatibility for metallic instruments, creating a separate qualification track. Stakeholders must monitor how tightening single-use device sustainability scrutiny in Germany and France reshapes material selection roadmaps and reimbursement positioning.
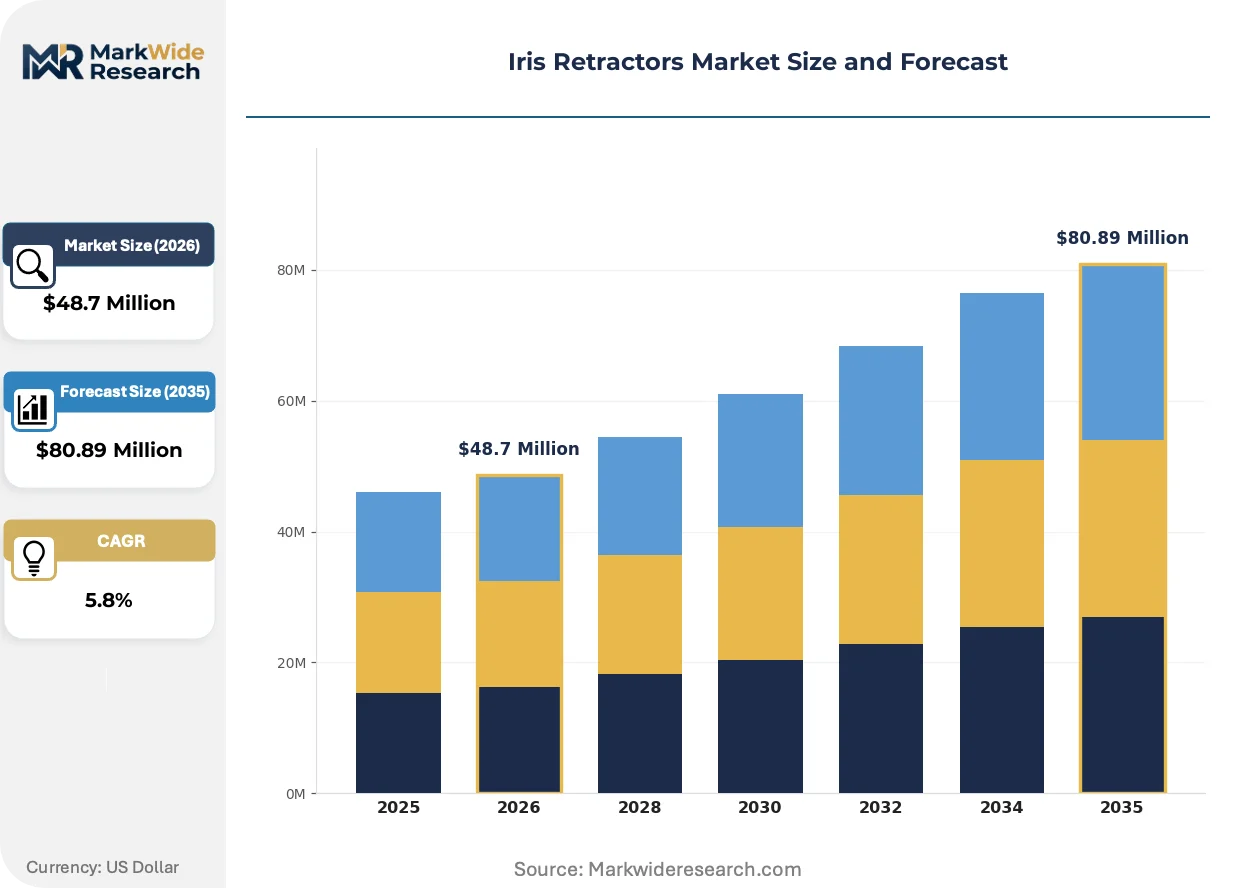
Market Dynamics
Ambulatory surgical centers are consolidating procurement power for single-use iris retractors, compressing vendor margins while elevating sterility assurance and traceability requirements across outpatient ophthalmology networks.
Growth Catalysts
- Aging Demographics in Developed Economies:The United States, Germany, and Japan are expanding their populations over 65, enlarging the surgical pool requiring intraoperative pupil management during cataract procedures.
- EU MDR Compliance Pathways:Stricter clinical evidence requirements for Class IIa medical devices are filtering out marginal competitors, concentrating market share among validated manufacturers with robust quality systems.
- Microinvasive Glaucoma Surgery (MIGS):Proliferation of combined phaco-MIGS procedures is creating incremental demand for six-hook retractor configurations that accommodate wider surgical fields.
Market Restraints
- Stainless Steel Input Volatility:Nickel price fluctuations directly impact reusable retractor manufacturing costs, squeezing margins for European clinics dependent on premium titanium alternatives.
- Single-Use Device Sustainability Scrutiny:Germany and France are imposing extended producer responsibility frameworks on disposable polypropylene retractors, threatening volume economics.
- Silicone Material Substitution Limits:Biocompatible silicone variants reduce corneal endothelial touch rates but command 40-60% price premiums, constraining adoption outside academic medical centers.
Strategic Opportunities
- Underpenetrated Japanese ASC Networks:Japan's PMDA is streamlining 510(k)-equivalent pathways for foreign-manufactured devices, opening ambulatory channels previously dominated by domestic suppliers.
- Phacoemulsification Platform Bundling:Integrated surgical system vendors can capture recurring consumable revenue by embedding proprietary retractor designs within equipment lease agreements.
- Reusable Line Revival in European Academic Centers:Sterile processing infrastructure investments at university hospitals in France and Italy create pull for premium stainless steel configurations with validated reprocessing protocols.
Industry Challenges
- EU MDR Technical Documentation Burden:Clinical evaluation report requirements for legacy retractor designs are extending certification timelines by 12-18 months, freezing product portfolio refreshes.
- Corneal Endothelial Cell Count Protocol Integration:Surgeons demand retractors with pre-calibrated engagement angles, requiring precision manufacturing tolerances that strain quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iris Retractors Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Iris Retractors, Reusable Iris Retractors, Self-Retaining Iris Retractors, Fixed Iris Retractors Material: Stainless Steel, Plastic, Silicone, Biocompatible Materials Application: Cataract Surgery, Corneal Surgery, Glaucoma Surgery, Oculoplastics End User: Hospitals, Eye Clinics, Surgical Centers, Research Laboratories |
| Companies Covered | Alcon, Bausch + Lomb, Katalyst Surgical, ASICO LLC, Beaver-Visitec International, OASIS Medical, FCI Ophthalmics, Rumex International Corporation, Geuder AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iris Retractors Market Trends and Innovations
Material science advances and regulatory harmonization pressures are converging to redefine product validation standards and procurement criteria across ophthalmic surgery settings.
Silicone-coated polypropylene hybrids are rewriting performance benchmarks for disposable iris retractors by combining the structural rigidity of thermoplastics with reduced tissue trauma profiles. Academic medical centers in the United States are piloting these configurations for complex cataract cases with small pupils. The technology is compressing demand for traditional uncoated variants while forcing incumbent manufacturers to accelerate coating process investments.
Japan's PMDA enforcement of JIS standards for metallic surgical instruments is creating a parallel qualification track distinct from FDA 510(k) pathways. Foreign manufacturers must establish domestic testing partnerships or license local production to access Japanese ASC networks. Stainless steel retractor suppliers with existing JIS certifications are capturing share from European competitors lacking in-country validation infrastructure.
Buying committees at United States ambulatory surgical centers are consolidating vendor relationships to reduce sterilization liability exposure and simplify supply chain management. Single-source agreements for comprehensive ophthalmic procedure kits are displacing standalone retractor purchases. This concentration is most visible in the Southeast and Southwest regions where ASC chains have achieved sufficient scale to dictate custom kit configurations.
Iris Retractors Market Segmentation
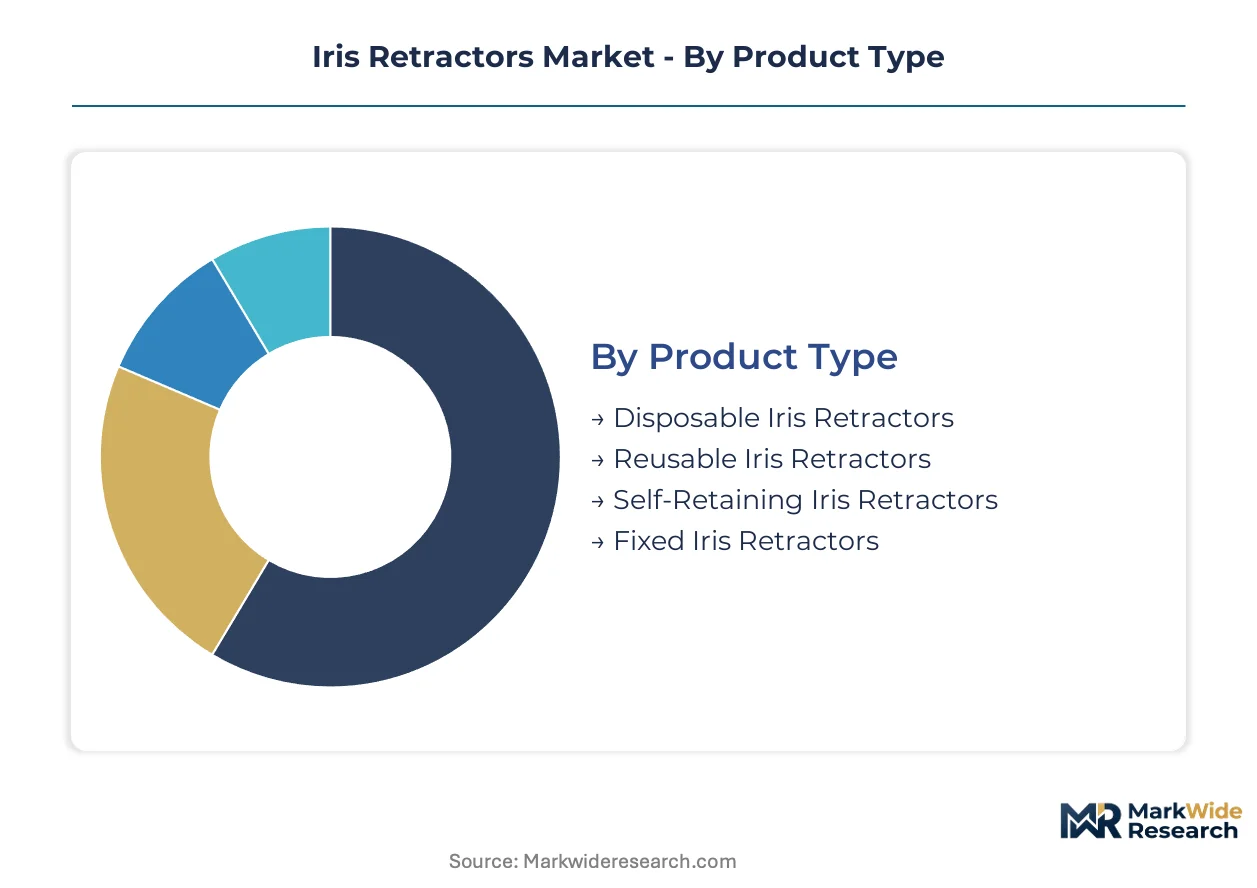
Segmentation in the Iris Retractors Market reveals how procurement decisions split between cost-driven disposable adoption and capital-intensive reusable infrastructure. Material selection and surgical setting dictate margin structures across vendor portfolios.
Product Type:
Supply concentration clusters around manufacturers with dual sterile processing and polymer molding capabilities.
- Disposable Iris Retractors:Polypropylene single-use devices eliminate reprocessing liability for ambulatory surgical centers. United States ASC chains favor these for cataract volume throughput where sterility assurance trumps per-unit cost.
- Reusable Iris Retractors:Stainless steel and titanium configurations withstand hundreds of sterilization cycles. European academic medical centers in Germany and France absorb higher upfront capital for validated reprocessing protocols.
- Self-Retaining Iris Retractors:Integrated tension mechanisms reduce surgical assistant dependency.
- Fixed Iris Retractors:Manual positioning variants retain niche use in cost-constrained settings.
Today's leader: Disposable Iris Retractors. Tomorrow's challenger: Self-Retaining Iris Retractors.
Material:
Cost tier stratification separates premium biocompatible grades from commodity thermoplastics.
- Stainless Steel:Surgical-grade alloys dominate reusable retractor fabrication with validated fatigue resistance. Japan's PMDA enforces JIS standards for metallic instruments, creating qualification barriers for non-compliant foreign suppliers.
- Silicone:Elastomer coatings reduce corneal endothelial touch rates in complex cases. Academic medical centers in the United States pilot these for small-pupil cataract procedures despite 40-60% price premiums over uncoated alternatives.
- Plastic:Polypropylene substrates enable high-volume disposable production.
- Biocompatible Materials:Advanced surface treatments target reduced inflammatory response.
Stainless Steel commands current volume. Silicone is climbing the fastest on trauma-reduction claims.
Application:
Procedure volume distribution concentrates in settings with aging patient throughput.
- Cataract Surgery:Phacoemulsification protocols generate the bulk of iris retractor demand. United States, Germany, and Japan demographics expand the surgical pool requiring intraoperative pupil management.
- Glaucoma Surgery:Microinvasive techniques proliferate combined phaco-MIGS procedures. Six-hook retractor configurations accommodate wider surgical fields in these hybrid interventions.
- Corneal Surgery:Penetrating keratoplasty and endothelial transplantation use specialized stabilization.
- Oculoplastics:Orbital and lid procedures represent incidental retractor deployment.
Cataract Surgery anchors procurement budgets. Glaucoma Surgery offers the steepest expansion trajectory.
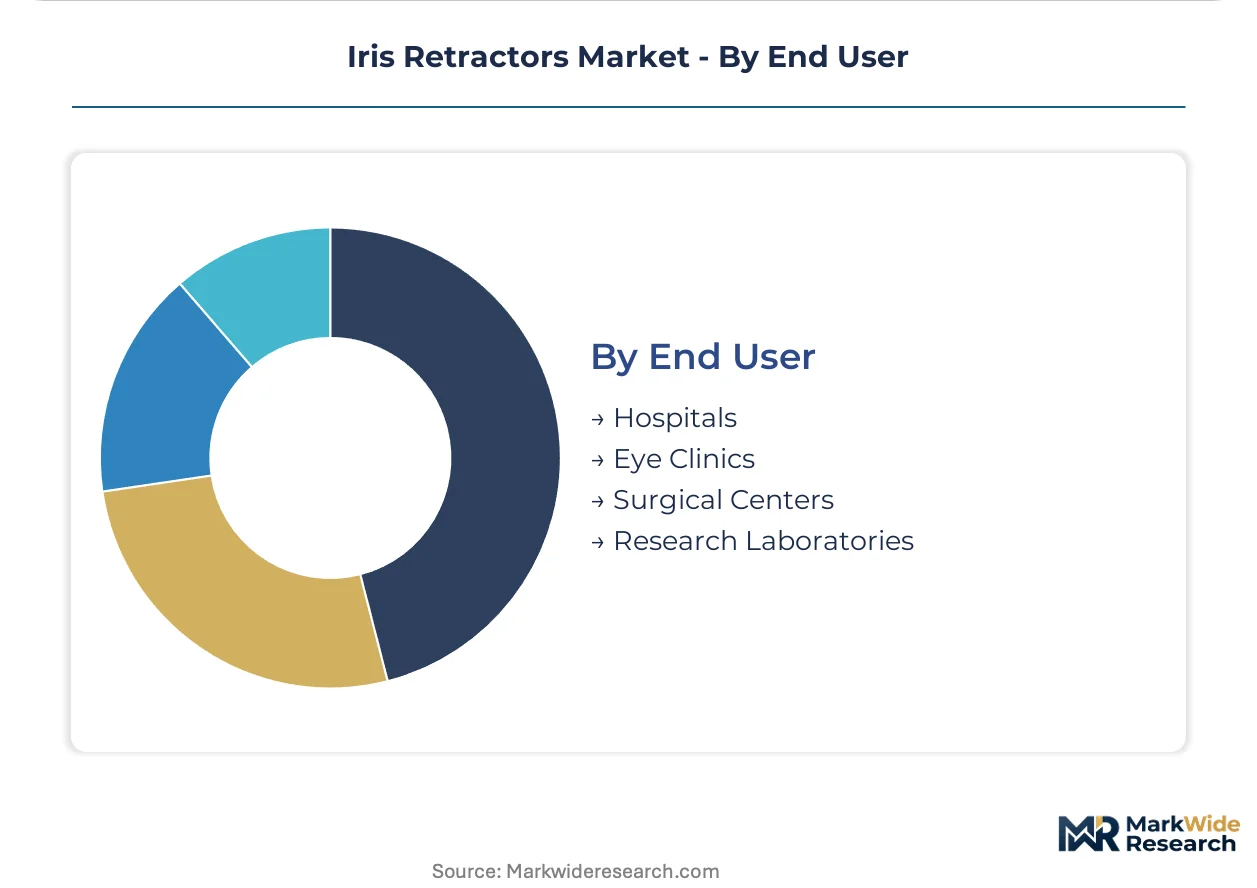
End User:
Customer type determines whether vendors pursue capital equipment leases or consumable bulk contracts.
- Surgical Centers:Ambulatory networks consolidate vendor relationships to reduce sterilization liability. United States ASC chains in the Southeast and Southwest dictate custom kit configurations bundling retractors with phacoemulsification platforms.
- Hospitals:Integrated delivery networks balance disposable convenience against sterile processing economies of scale.
- Eye Clinics:Independent ophthalmology practices prioritize single-source simplicity.
- Research Laboratories:Preclinical validation studies drive small-batch precision requirements.
Surgical Centers drive current volume concentration. Hospitals retain latent reusable infrastructure potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting iris retractor manufacturing toward jurisdictions with streamlined medical device pathways, while procurement concentration in high-volume ambulatory networks favors suppliers with localized validation infrastructure. The United States, Germany, and Japan anchor demand through aging demographics and established ophthalmic surgical volumes.
United States
Cataract procedure volumes at ambulatory surgical centers in Florida and Texas are compressing vendor margins through consolidated kit purchasing. FDA 510(k) premarket notification requirements govern market entry for polypropylene disposable variants. Southeast ASC chains now dictate custom configurations bundling retractors with phacoemulsification platforms.
Germany
Extended producer responsibility frameworks in Bavaria and Baden-Württemberg are threatening volume economics for single-use polypropylene devices. EU MDR compliance pathways for Class IIa devices filter out marginal competitors lacking robust quality systems. Stuttgart-based sterile processing infrastructure investments at university hospitals create pull for premium stainless steel configurations.
Japan
PMDA enforcement of JIS standards for metallic instruments creates qualification barriers for non-compliant foreign suppliers seeking ambulatory network access. Tokyo and Osaka metropolitan areas concentrate demand for six-hook retractor configurations in combined phaco-MIGS procedures. Domestic testing partnerships remain essential for foreign manufacturers targeting Japanese ASC channels.
France
Sustainability scrutiny in Île-de-France and Auvergne-Rhône-Alpes imposes material selection roadmaps on disposable retractor suppliers. ANSM oversight of clinical evidence requirements elevates validation standards for silicone-coated variants. Lyon-based academic medical centers pilot biocompatible configurations for small-pupil cataract cases despite price premiums.
United Kingdom
NHS procurement frameworks in London and the Southeast favor single-source agreements reducing sterilization liability exposure. MHRA post-Brexit regulatory alignment with EU MDR maintains elevated technical documentation burdens. Midlands-based ophthalmology networks balance disposable convenience against sterile processing economies of scale.
Iris Retractors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated surgical platform vendors capturing recurring consumable revenue through equipment lease bundling. The vendor base concentrates among validated manufacturers with dual sterile processing and polymer molding capabilities. Three archetypes dominate: diversified ophthalmic conglomerates with phacoemulsification ecosystems, premium reusable instrument specialists, and disposable-focused catalog breadth players. Competitive moves center on strategic partnerships with ASC chains and backward integration into polymer molding capacity.
Among diversified ophthalmic conglomerates, Alcon anchors the integrated platform tier through phacoemulsification system bundling. Katalyst Surgical occupies a position within the premium reusable instrument archetype. ASICO LLC exemplifies the catalog breadth model across fixed and self-retaining configurations. These three represent distinct competitive vectors rather than direct substitution, with each archetype serving divergent procurement priorities across ambulatory and academic settings.
| Leading Market Players |
|---|
| Alcon |
| Bausch + Lomb |
| Katalyst Surgical |
| ASICO LLC |
| Beaver-Visitec International |
| OASIS Medical |
| FCI Ophthalmics |
| Rumex International Corporation |
| Geuder AG |
| Others |
Pricing and Supply Chain Analysis
Ambulatory surgical center buying committees in the United States Southeast and Southwest are consolidating vendor relationships into single-source kit agreements, compressing standalone retractor pricing power while elevating bundled contract values across phacoemulsification platforms.
Pricing Analysis
Distributor margins on disposable polypropylene retractors are compressing as United States ASC chains negotiate direct manufacturer relationships for comprehensive ophthalmic procedure kits. Three-tier pricing structure across premium silicone-coated, standard polypropylene, and economy uncoated variants separates academic medical centers from high-volume ambulatory networks. Pricing pressure stems from Germany's extended producer responsibility frameworks imposing material cost burdens on single-use devices. High-volume ASC chains exhibit greatest price sensitivity, while Japanese academic centers absorbing JIS-certified stainless steel premiums show least elasticity.
Supply Chain Analysis
Precision polymer molding workforce availability in Massachusetts and Minnesota anchors domestic disposable retractor fabrication, while surgical-grade stainless steel forging expertise concentrates in Solingen, Germany and Seki, Japan. Raw material draws from medical-grade polypropylene resin suppliers, nickel-alloy steel mills, and platinum-cured silicone compounders. Supply chain risk centers on single-source vulnerability for FDA-validated polymer grades following recent plant consolidation. Distribution runs through GPO contracts at integrated delivery networks and direct-to-ASC kit assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through silicone-coated premium tier migration and sterile processing infrastructure cost-downs at European academic centers.
For Market Incumbents: Cement platform bundling advantages by embedding proprietary six-hook retractor designs within phacoemulsification equipment lease agreements, neutralizing standalone disposable competitors. Deepen backward integration into polymer molding capacity to capture margin currently lost to contract manufacturers serving ASC kit assemblers. For New Entrants and Emerging Players: The premium-economy price gap in Japanese ambulatory surgical centers creates entry opportunity for mid-tier silicone-coated variants with streamlined PMDA qualification pathways. Target underpenetrated phaco-MIGS combination procedures with six-hook configurations, leveraging domestic testing partnerships to bypass JIS certification barriers. For Investors and Strategic Acquirers: Integrated ophthalmic surgical platform vendors are the most active acquirers in this space, seeking consumable attach-rate expansion. Over the medium-term horizon, prioritize targets with validated EU MDR technical documentation and existing sterile processing service contracts. Watch FDA 510(k) clearance velocity for silicone-coated hybrids as inflection indicator for premium tier shift.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance filters marginal competitors, concentrating share among validated manufacturers with robust quality systems. |
| Hospital System Partnership | United States ASC chains dictate custom kit configurations bundling retractors with phacoemulsification platforms. |
| Silicone Coating Process Investment | Academic medical centers pilot hybrid configurations for small-pupil cataract cases despite price premiums. |
| JIS Certification Licensing | Foreign manufacturers must establish domestic testing partnerships to access Japanese ambulatory network channels. |
| Reimbursement Strategy Alignment | Germany's extended producer responsibility frameworks reshape material selection roadmaps and pricing positioning. |
Research Methodology
Multiple input streams — structured interviews with ophthalmic surgeons and ASC purchasing directors, hospital procurement database analysis, and regulatory filing review — were reconciled against secondary validation from FDA 510(k) clearances, EU MDR technical documentation, and Japanese PMDA registration records. Bottom-up procedure volume modeling triangulated with top-down vendor revenue estimates.
Data-stream reconciliation across product type, material grade, application setting, and end-user channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from surgical volume elasticity to aging demographic expansion and phaco-MIGS procedure mix shifts. Forecast inputs incorporated sterile processing infrastructure investment cycles and single-use device sustainability policy trajectories.
Caveats apply where EU MDR certification timeline extensions or nickel price volatility could materially shift the outlook. Forecasts reflect assumptions about ambulatory surgical center consolidation velocity and silicone coating adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Disposable Surgical Devices Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Endoscopic Spinal Surgery Market