
 Skull Deformity Implants Market | 2026-2036
Skull Deformity Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Skull Deformity Implants Market Analytics
Single-source reliance on external cranial implant manufacturers is restructuring into hybrid in-house and outsourced production models. Zimmer Biomet leverages centralized manufacturing scale to serve high-volume hospital systems across North America. KLS Martin specializes in patient-specific titanium cranioplasty solutions through direct digital manufacturing workflows. Stryker competes by controlling distribution networks that link academic medical centers with rapid-turnaround implant fabrication.
Skull deformity implants are custom or semi-custom medical devices engineered to restore cranial contour and protect underlying neural tissue following trauma, congenital deformity, or oncologic resection; titanium alloys and polyether ether ketone dominate material selection due to biocompatibility, radiolucency, and fatigue resistance under physiological loading. Plate systems anchor the mature revenue base where standardized geometries and established surgical technique sustain predictable demand, while patient-specific mesh reconstructions represent the fastest-expanding segment as computed-tomography-based design workflows and additive manufacturing reduce operative time and improve aesthetic outcomes. Screw and anchor fixation modalities occupy narrower margin pools tied to revision procedures and pediatric applications where bone quality constraints limit hardware selection.
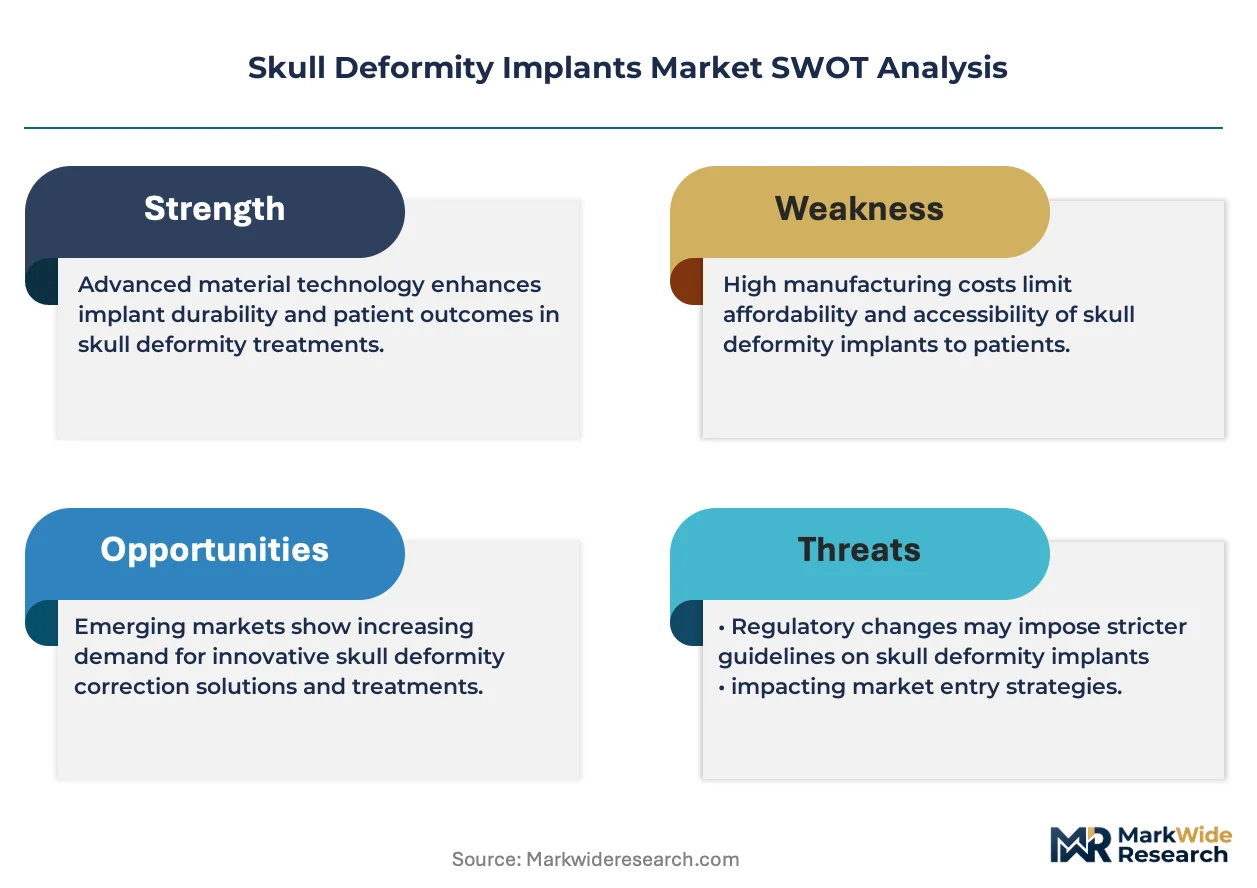
FDA 510(k) premarket notification requirements govern commercial entry for titanium and polymer cranial implants in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for custom-made device classifications across European markets. ISO 13485 quality management systems and ASTM F136 specifications for surgical-grade titanium alloy provide the foundational compliance architecture that manufacturers must maintain for market access. Stakeholders must monitor evolving reimbursement policies for patient-specific additive-manufactured implants and the pace of regulatory harmonization between FDA breakthrough device pathways and European notified body conformity assessments.
Market Dynamics
Patient-specific additive manufacturing is compressing the traditional 12-week implant production cycle into 72-hour turnaround windows, forcing cranial implant suppliers to reconfigure quality systems around digital design-to-sterilization workflows rather than conventional machining and inventory models.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's expanded recognition of ASTM F136 titanium specifications for additive-manufactured cranial implants accelerates premarket notification reviews for patient-specific devices.
- Level I Trauma Center Expansion:United States academic medical centers are consolidating neurosurgical services into high-volume craniofacial units that standardize custom implant protocols.
- PEEK Polymer Biocompatibility:Radiolucent polyether ether ketone formulations enable postoperative MRI surveillance without artifact interference, expanding oncologic resection applications.
Market Restraints
- Titanium Powder Supply Concentration:Plasma-atomized Ti-6Al-4V ELI powder for electron beam melting concentrates among three qualified suppliers in Germany and the United States.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation's custom-made device classification requires patient-level clinical follow-up that extends conformity assessment timelines.
- Autologous Bone Graft Persistence:Cost-conscious payers in emerging markets continue favoring cranioplasty with cryopreserved autograft over alloplastic reconstruction.
Strategic Opportunities
- Pediatric Cranial Vault Remodeling:Underpenetrated demand exists for resorbable polymer implants in syndromic craniosynostosis correction across Latin American referral centers.
- India CDSCO Harmonization:India's Medical Device Rules alignment with ISO 13485 quality standards creates pathway for imported patient-specific titanium implants.
- AI-CT Segmentation Convergence:Machine learning-based anatomical segmentation paired with generative design software collapses preoperative planning from days to hours.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Electron beam melting operators with medical device GMP experience command premium wages that inflate per-unit labor costs.
- Bioburden Validation Complexity:Porous titanium lattice structures challenge steam sterilization cycle validation under AAMI TIR12 guidance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skull Deformity Implants Market |
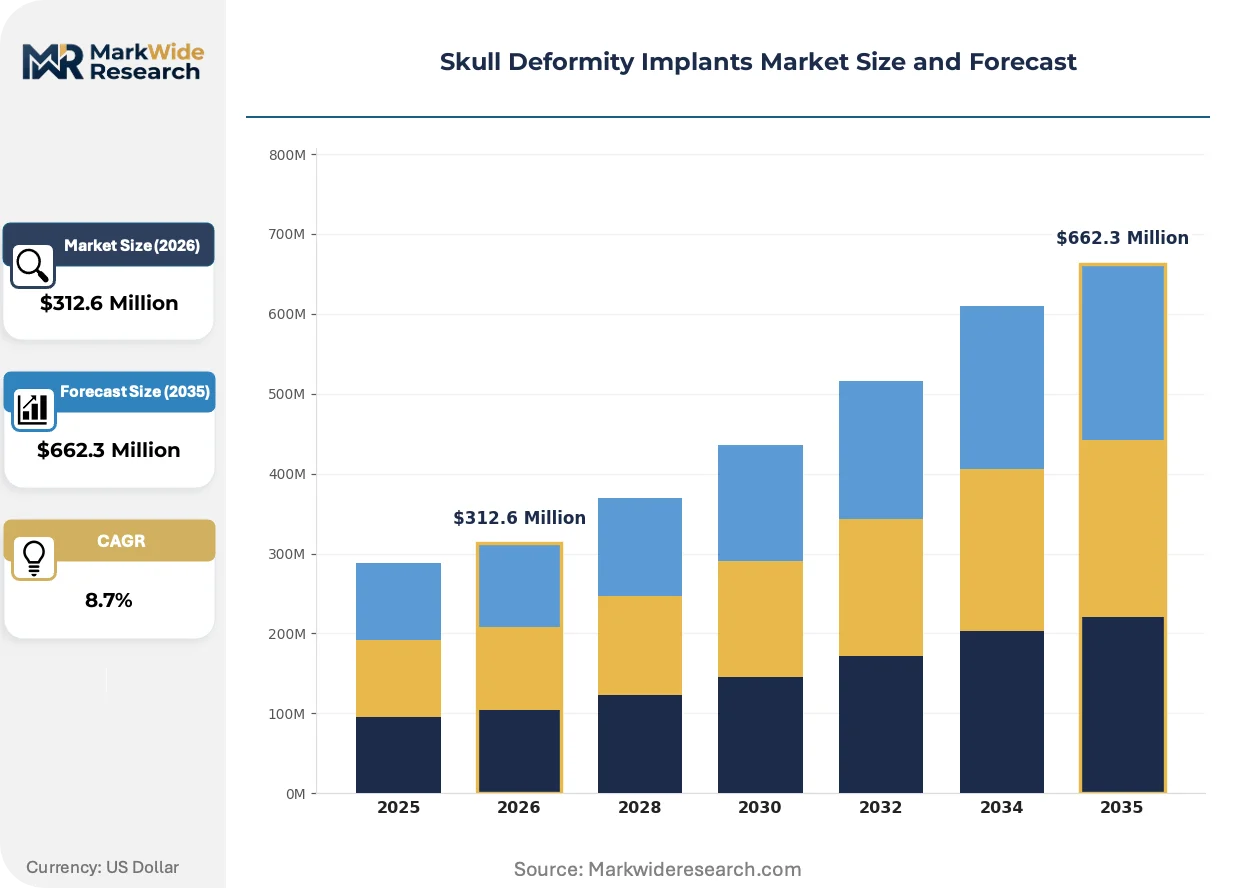
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate, Mesh, Screw, Anchor Material: Titanium, Polyether Ether Ketone, Biocompatible Polymer, Stainless Steel End User: Hospitals, Surgical Centers, Clinics, Research Institutes Application: Cosmetic Surgery, Trauma Cases, Reconstructions, Correction Procedures |
| Companies Covered | Zimmer Biomet, B. Braun Melsungen, KLS Martin, OssDsign, DePuy Synthes, Stryker, Medtronic, Xilloc, Medartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skull Deformity Implants Market Evolving Landscape
Distributed manufacturing networks and point-of-care 3D printing installations are fragmenting the traditional centralized production model for cranial implants, creating new competitive terrain around software-enabled design services rather than physical inventory.
Topology optimization software is unifying stress-mapping algorithms with patient-specific anatomical constraints to generate titanium lattice structures that match native cranial stiffness while reducing material volume. Academic medical centers in the United States are deploying these tools intraoperatively for trauma cases requiring immediate cranioplasty. This capability is compressing the addressable market for standardized plate geometries by shifting surgeon preference toward functionally graded implants.
The European Union's Medical Device Regulation is tightening notified body scrutiny of patient-specific device technical documentation, particularly for additive-manufactured titanium with as-built surface roughness exceeding 12 micrometers. Manufacturers must now submit mechanical testing protocols for each lattice topology variant rather than generic material certificates. Cranial implant suppliers are responding by consolidating European product portfolios around fewer validated design families.
Surgeon procurement committees are consolidating vendor relationships into single-source agreements that bundle preoperative planning software, implant fabrication, and revision warranty coverage. Hospital systems in the United States are replacing transactional purchase orders with multi-year partnerships that lock in per-procedure pricing. This shift is most visible in consolidated neurosurgery service lines across Midwestern health systems.
Skull Deformity Implants Market Segmentation
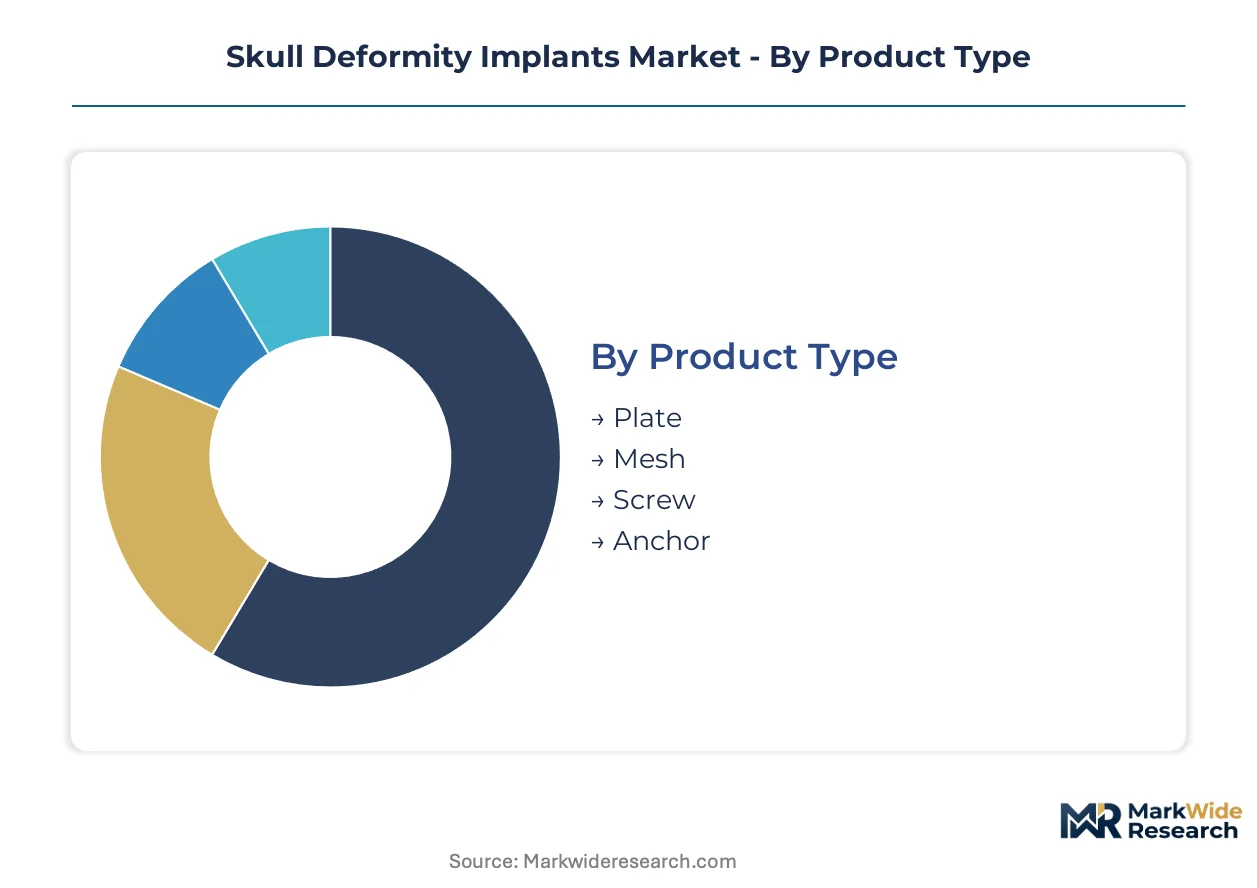
Segmentation in skull deformity implants reveals how supply chain configuration, material science trajectories, and clinical workflow integration determine competitive positioning. Manufacturers must align production capabilities with the specific technical and regulatory demands of each category.
Product Type:
Supply concentration for cranial implant fabrication clusters around electron beam melting capacity for titanium lattices and injection molding lines for polymer formulations.
- Plate:Standardized titanium geometries with established screw fixation patterns dominate high-volume trauma protocols at Level I centers. United States academic medical centers sustain demand through bundled procurement agreements that lock in multi-year supply.
- Mesh:Patient-specific additive-manufactured titanium reconstructions with topology-optimized lattice structures reduce operative time for complex oncologic resections. Demand concentrates in craniofacial surgery programs where CT-based design workflows integrate with surgical navigation systems.
- Screw:Self-tapping titanium fixation hardware with cortical thread profiles addresses revision procedures and pediatric applications where bone quality varies.
- Anchor:Low-profile titanium or resorbable polymer devices secure soft tissue attachments in secondary aesthetic revisions with limited bone stock.
Plate systems absorb the bulk of installed capacity; Mesh is expanding most quickly.
Material:
Cost tier differentiation separates aerospace-grade titanium feedstock from commodity polymer resins, with biocompatibility certification premiums stratifying supplier margins.
- Titanium:Ti-6Al-4V ELI alloy meeting ASTM F136 specifications provides fatigue resistance and osseointegration surface topology for permanent cranioplasty. Germany and United States powder atomization facilities control qualified feedstock supply.
- Polyether Ether Ketone:Radiolucent thermoplastic with modulus matching native bone enables postoperative MRI surveillance without artifact interference. Oncologic resection applications at United States cancer centers drive specification requirements.
- Biocompatible Polymer:Resorbable polylactic acid formulations address pediatric craniosynostosis where subsequent skull growth necessitates temporary support.
- Stainless Steel:Lower-cost 316LVM alloy retains niche use in emerging market trauma settings where cost constraints override radiolucency requirements.
Titanium commands the majority of production investment; Polyether Ether Ketone is climbing the fastest.
End User:
Customer type determines service intensity, with hospital systems requiring embedded design engineers versus clinics accepting standardized catalog geometries.
- Hospitals:Academic medical centers with consolidated neurosurgery service lines deploy patient-specific implant protocols with 72-hour turnaround requirements. United States Level I trauma centers anchor demand through standardized custom cranioplasty pathways.
- Surgical Centers:Ambulatory facilities with limited sterilization infrastructure favor pre-sterilized single-use polymer implants for select cosmetic indications.
- Clinics:Private craniofacial practices in metropolitan United States markets access design software licenses for direct-to-manufacturer implant ordering.
- Research Institutes:Academic engineering laboratories validate novel lattice topologies and resorbable material formulations under FDA investigational device exemptions.
Hospitals absorb the bulk of installed capacity; Research Institutes are gaining share fastest.
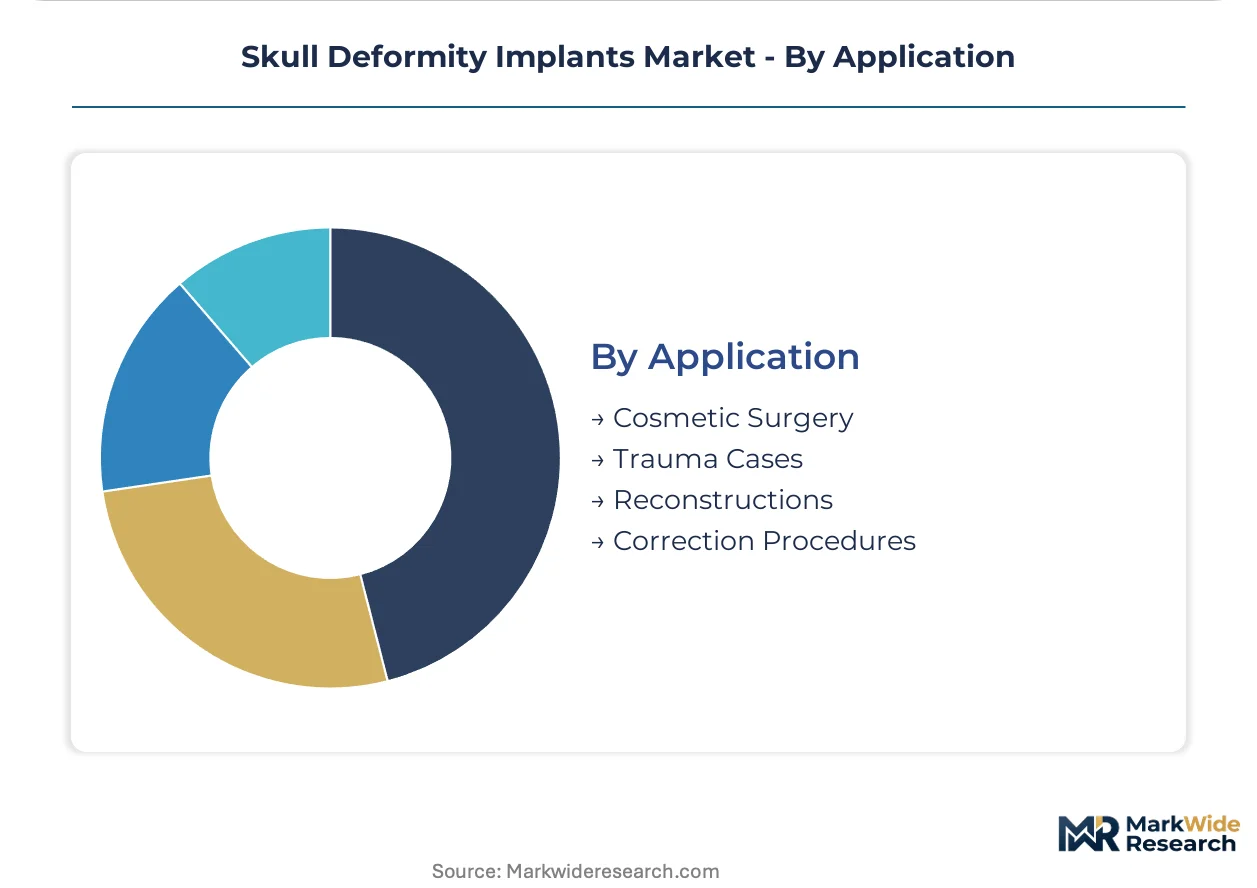
Application:
Volume concentration in trauma reconstruction creates margin pressure, while cosmetic and oncologic segments support premium pricing through outcome-based procurement.
- Cosmetic Surgery:Secondary cranioplasty for aesthetic contour refinement following primary trauma or congenital repair. United States metropolitan practices with direct-to-consumer marketing sustain elective procedural volume.
- Trauma Cases:Emergency decompressive craniectomy with delayed alloplastic reconstruction dominates United States Level I center caseload. Standardized protocols favor rapid-turnaround titanium plate fabrication.
- Reconstructions:Oncologic skull base resection with immediate cranioplasty requires patient-specific PEEK or titanium implants matched to dural replacement grafts.
- Correction Procedures:Syndromic craniosynostosis vault remodeling in pediatric populations drives resorbable polymer demand across Latin American referral centers.
Trauma Cases absorb the bulk of installed capacity; Correction Procedures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Level I trauma centers and academic medical centers concentrate procedural volume for patient-specific cranial implants, with demand clustering around consolidated neurosurgery service lines that standardize custom fabrication protocols.
United States
FDA 510(k) clearance pathways for additive-manufactured titanium devices accelerate commercial entry for patient-specific implants. The agency's expanded recognition of ASTM F136 specifications compresses premarket notification timelines. Cleveland Clinic and Johns Hopkins craniofacial surgery programs anchor demand through bundled procurement agreements with 72-hour turnaround requirements.
Germany
Plasma-atomized Ti-6Al-4V ELI powder suppliers concentrate qualified feedstock production for electron beam melting applications. EU MDR custom-made device classifications impose stricter clinical evidence standards that extend conformity assessment timelines. Tübingen and Berlin academic medical centers drive adoption of topology-optimized lattice structures for complex oncologic resections.
India
CDSCO harmonization with ISO 13485 quality standards creates regulatory pathways for imported patient-specific titanium implants. Cost-conscious payers in emerging markets favor standardized plate geometries over custom additive-manufactured solutions. Mumbai and Delhi referral centers expand pediatric cranial vault remodeling capacity for syndromic craniosynostosis correction.
Japan
PMDA regulatory frameworks govern commercial entry for permanent cranioplasty devices with stringent biocompatibility validation requirements. Tokyo and Osaka academic medical centers integrate CT-based design workflows with surgical navigation systems for patient-specific mesh reconstructions. Domestic manufacturers emphasize PEEK polymer formulations for postoperative MRI surveillance applications.
Brazil
ANVISA medical device regulations align with Mercosur technical standards for imported cranial implants. Autologous bone graft persistence in cost-constrained settings limits alloplastic reconstruction adoption. São Paulo craniofacial surgery programs represent the primary demand concentration for premium titanium plate systems in Latin America.
Skull Deformity Implants Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers reconfigure around digital design-to-sterilization workflows rather than conventional machining and inventory models. The vendor base separates into three tiers: diversified orthopedic conglomerates with centralized manufacturing scale, mid-cap specialists with direct digital manufacturing capabilities, and emerging point-of-care fabrication service providers. Competitive positioning hinges on FDA 510(k) clearance velocity, electron beam melting capacity access, and surgeon procurement committee consolidation into single-source agreements.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker occupy positions defined by distribution network control and academic medical center linkages. KLS Martin represents the mid-cap specialist archetype with concentrated exposure to patient-specific titanium cranioplasty workflows. These three entities exemplify the competitive tension between scale-driven centralized production and rapid-turnaround custom fabrication capabilities.
| Leading Market Players |
|---|
| Zimmer Biomet |
| B. Braun Melsungen |
| KLS Martin |
| OssDsign |
| DePuy Synthes |
| Stryker |
| Medtronic |
| Xilloc |
| Medartis AG |
| Others |
Value Network & Pricing Analysis
Electron beam melting adoption for patient-specific titanium lattices is simultaneously compressing per-unit production costs and concentrating qualified feedstock demand among plasma-atomization facilities in Germany and the United States. This dual effect creates pricing power asymmetries where powder suppliers capture margin while implant fabricators compete on turnaround velocity.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from transactional competitors, with multi-year revision coverage and embedded design software licenses commanding price premiums at United States academic medical centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ASTM F136 certification grade and electron beam melting capacity access. Pricing pressure stems from hospital procurement committee consolidation into single-source agreements that lock in per-procedure rates. Ambulatory surgical centers exhibit highest price sensitivity due to limited sterilization infrastructure and elective case mix.
Supply Chain Analysis
Single-source vulnerability sits with plasma-atomized Ti-6Al-4V ELI powder production concentrated in Germany and the United States, with qualified electron beam melting feedstock drawing from three atomization facilities. Raw material dependencies center on aerospace-grade titanium sponge, argon gas for inert processing, and electron beam melting chamber components. Tariff exposure on German-sourced powder creates margin risk for North American fabricators lacking qualified domestic alternatives. Distribution runs through direct manufacturer-to-hospital partnerships with embedded design engineers, bypassing traditional orthopedic distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The skull deformity implants market functions as a cost-of-compliance story where EU MDR custom-made device classifications and FDA 510(k) premarket notification requirements erect barrier-to-entry moats that favor incumbent manufacturers with established quality management systems.
For Market Incumbents: Extend electron beam melting capacity into point-of-care installations at United States Level I trauma centers to preempt emerging fabrication service providers. Consolidate European product portfolios around fewer validated lattice topologies to reduce EU MDR conformity assessment burden. Deepen backward integration into plasma-atomized powder supply through captive offtake agreements with German atomization facilities.
For New Entrants and Emerging Players: Pediatric cranial vault remodeling programs at Latin American referral centers represent an underserved buyer archetype with limited incumbent penetration. Target resorbable polymer formulations for syndromic craniosynostosis correction where cost-conscious payers favor temporary support over permanent titanium. Pursue CDSCO registration pathway for imported patient-specific implants into Indian metropolitan markets.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with direct digital manufacturing capabilities and concentrated craniofacial surgery program relationships. Long-term viability hinges on electron beam melting operator talent pipelines and FDA 510(k) clearance velocity rather than scale economies. Monitor AI-CT segmentation convergence adoption rates as inflection indicator for design workflow automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Fabrication Partnership | Embedding electron beam melting capacity at Cleveland Clinic and Johns Hopkins locks in 72-hour turnaround commitments. |
| EU MDR Consolidation Pathway | Reducing lattice topology variants streamlines notified body scrutiny under stricter custom-made device classifications. |
| Powder Supply Captive Arrangement | Long-term offtake with German plasma-atomization facilities mitigates single-source vulnerability for Ti-6Al-4V ELI feedstock. |
| AI-CT Segmentation Integration | Machine learning-based anatomical segmentation collapses preoperative planning timelines for trauma emergency protocols. |
| Pediatric Resorbable Portfolio | Polylactic acid formulations for syndromic craniosynostosis address underpenetrated Latin American referral center demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with craniofacial surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) premarket notification databases, EU MDR technical documentation, and ISO 13485 quality management audit records provided structured secondary validation. Bottom-up procedure volume estimates from United States Level I trauma centers reconciled with top-down manufacturer shipment data across the analysis window.
Data-stream reconciliation combined patient-specific implant order flows with electron beam melting capacity utilization metrics from qualified facilities. Segmentation modeling incorporated product type, material formulation, end-user facility tier, and application indication dimensions throughout the forecast period. CAGRs derived from logarithmic trend fitting to reconstructed historical shipment series, with PEEK polymer and pediatric correction procedure trajectories receiving distinct growth assumptions based on MRI surveillance demand and syndromic craniosynostosis referral expansion.
Revisions become necessary when EU MDR notified body capacity constraints extend conformity assessment timelines or when titanium powder supply disruptions materialize from geopolitical trade restrictions. Forecasts reflect assumptions about FDA breakthrough device pathway harmonization with European standards and hospital procurement committee vendor consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Recanalization System Market
Medical Devices
Annuloplasty System Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Micro Syringes Market
Medical Devices
Global Hernia Repair Devices Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Cardioscope Market
Medical Devices
Neuro Ablation Devices Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Cervical Fusion Market
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Intraoral Scanners Market