
 Global Thyroid Disorder Treatment Market | 2026-2036
Global Thyroid Disorder Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thyroid Disorder Treatment Market Foresight
Modular dosing regimens is decoupling fixed-combination thyroid therapies into titratable single-agent protocols, giving physicians granular control over hormone replacement precision. GSK Plc leverages its established endocrinology portfolio to sustain brand loyalty across European hospital networks. Pfizer Inc. competes through manufacturing scale that anchors cost-efficient levothyroxine supply chains. RLC Labs specializes in desiccated thyroid formulations that differentiate its niche position among patients seeking natural hormone alternatives.
Thyroid disorder treatment encompasses pharmacological and interventional modalities targeting dysregulated thyroid hormone production, with levothyroxine sodium—a synthetic T4 hormone—remaining the cornerstone of hypothyroidism management due to its predictable bioavailability and narrow therapeutic index requiring precise microgram dosing. Radioactive iodine therapy serves as a definitive treatment for hyperthyroidism and select thyroid cancers, exploiting iodine-131's selective thyroid tissue ablation. Levothyroxine dominates the product type landscape as the most prescribed thyroid medication globally, while radioactive iodine commands premium reimbursement in oncology-aligned therapy areas. The end user segment shows structural momentum at specialty endocrinology centers, where concentrated expertise drives complex case referrals and higher-margin combination therapy adoption.
FDA orphan drug designations and EMA's centralized marketing authorization procedures shape competitive access for novel thyroid therapeutics, with both agencies enforcing stringent bioequivalence standards for hormone replacement generics. ISO 15189 accreditation requirements for diagnostic centers directly influence treatment initiation rates by standardizing TSH assay reliability across clinical settings. Stakeholders must monitor evolving pharmacogenomic guidance from FDA and EMA regarding levothyroxine dosing algorithms, as personalized medicine frameworks begin integrating TPO gene variant data into clinical decision support tools.
Market Dynamics
Modular dosing regimens are decoupling fixed-combination thyroid therapies into titratable single-agent protocols, giving physicians granular control over hormone replacement precision. This structural shift is concentrating demand at specialty endocrinology centers where concentrated expertise drives complex case referrals.
Growth Catalysts
- EMA Centralized Marketing Authorization:Streamlined approval pathways for hormonal therapies are compressing product development timelines across European hospital networks.
- Specialty Endocrinology Centers:Concentrated expertise at these facilities is driving complex case referrals and higher-margin combination therapy adoption in the United States, Germany, and Japan.
- ISO 15189 Accreditation:Standardized TSH assay reliability across clinical settings is directly influencing treatment initiation rates by reducing diagnostic variability.
Market Restraints
- Narrow Therapeutic Index of Levothyroxine:Precise microgram dosing requirements create formulation complexity and heighten liability exposure for generic manufacturers.
- Stringent Bioequivalence Standards:FDA and EMA enforcement of rigorous equivalence criteria for hormone replacement generics limits rapid market entry for new suppliers.
- Radioactive Iodine Supply Concentration:Iodine-131 production depends on a limited number of nuclear reactors, creating geographic supply vulnerability for definitive hyperthyroidism treatment.
Strategic Opportunities
- Pharmacogenomic Integration:FDA and EMA guidance on levothyroxine dosing algorithms incorporating TPO gene variant data is creating clinical decision support tool opportunities.
- Desiccated Thyroid Formulations:Natural hormone alternatives represent underpenetrated demand among patient segments seeking non-synthetic options in North American and European markets.
- Diagnostic Infrastructure Expansion:Aging demographics in Japan and Germany are supporting sustained volume growth through expanded screening programs and specialist referral networks.
Industry Challenges
- Specialized Endocrinology Talent Pipeline:The shortage of board-certified specialists capable of managing complex thyroid cases is constraining patient intake capacity at referral centers.
- Legacy Assay System Integration:TSH testing platforms in community hospital settings require costly upgrades to meet evolving ISO 15189 reliability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thyroid Disorder Treatment Market |
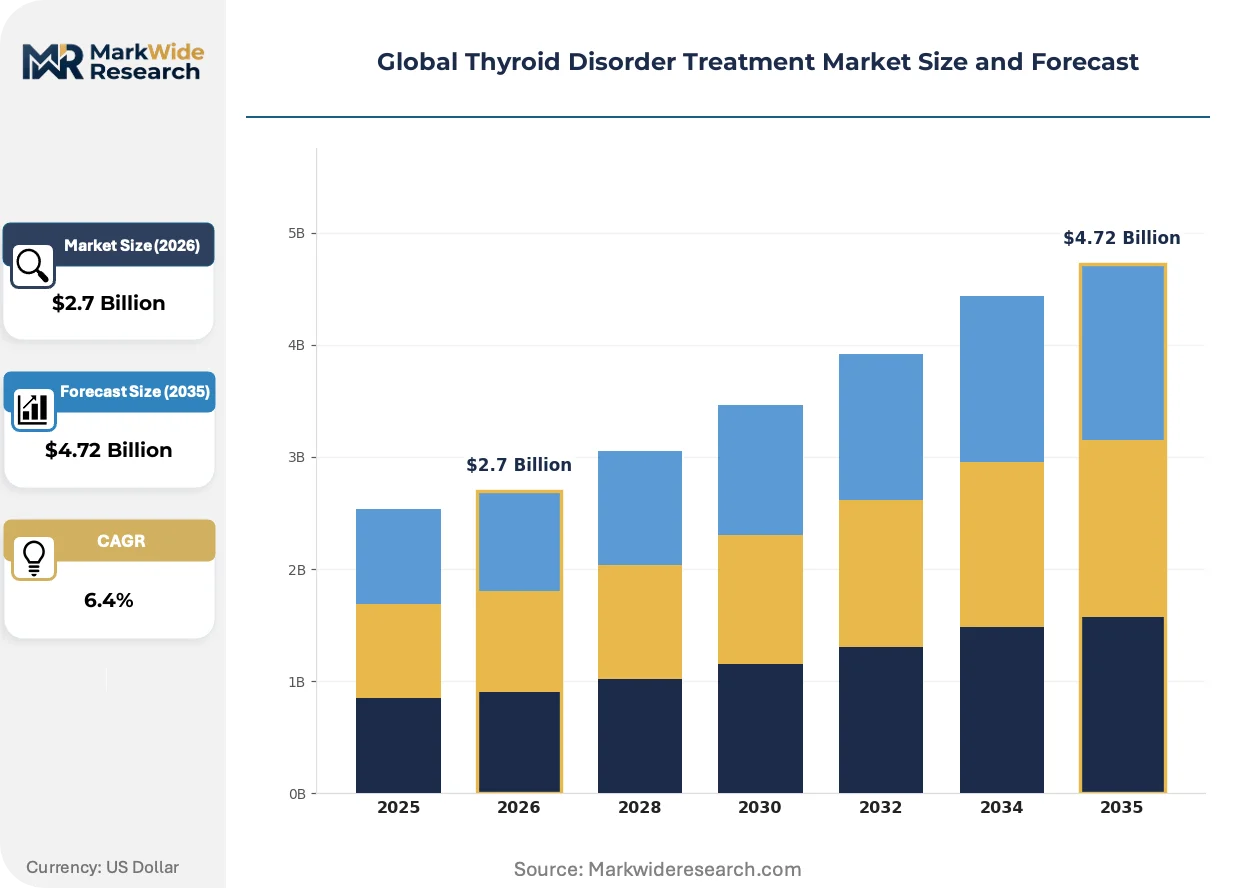
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Levothyroxine, Propylthiouracil, Methimazole, Radioactive Iodine, Liothyronine, Beta Blockers Therapy Area: Hypothyroidism, Hyperthyroidism, Thyroid Nodules, Goiter, Thyroid Cancer, Thyroiditis End User: Hospitals, Clinics, Diagnostic Centers, Specialty Endocrinology Centers, Home Healthcare Providers, Pharmacies Delivery Mode: Oral Medication, Injectable Therapy, Radioactive Therapy, Surgical Intervention, Combination Therapy, Nutritional Supplementation |
| Companies Covered | GSK Plc, Viatris Inc., Pfizer Inc., Takeda Pharmaceutical Company Limited, Novartis AG, AbbVie Inc., Amgen Inc., RLC Labs, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thyroid Disorder Treatment Market Shifts & Advancements
Precision medicine frameworks are integrating genetic biomarkers into thyroid hormone replacement protocols, compressing the gap between diagnostic identification and individualized therapeutic response. This evolution is reshaping how clinicians titrate dosing across patient subpopulations.
Continuous glucose monitoring-derived metabolic profiling is unifying real-time patient data streams with thyroid function assessment, enabling dynamic hormone adjustment protocols. Endocrinology practices in the United States and Germany are piloting these integrated monitoring systems at accelerating adoption rates. The technology is unifying previously siloed metabolic indicators into single-dashboard clinical decision workflows, reducing time-to-optimal-dosing from months to weeks.
REACH regulation amendments governing pharmaceutical manufacturing excipients are tightening purity specifications for levothyroxine tablet formulations across European supply chains. Manufacturers serving EMA-authorized markets face reformulation requirements to eliminate specified residual solvents. German and Swiss production facilities are responding by retrofitting active pharmaceutical ingredient synthesis lines ahead of compliance deadlines.
Direct-to-patient pharmacy fulfillment models are displacing traditional hospital-based dispensing for maintenance thyroid therapies, fragmenting historical channel concentration. Specialty endocrinology centers in Japan are unbundling prescription fulfillment from consultation services, redirecting stable patients to verified mail-order platforms. This channel shift is most visible in urban Japanese markets where aging patient populations prioritize convenience over facility-based pickup.
Global Thyroid Disorder Treatment Market Segmentation
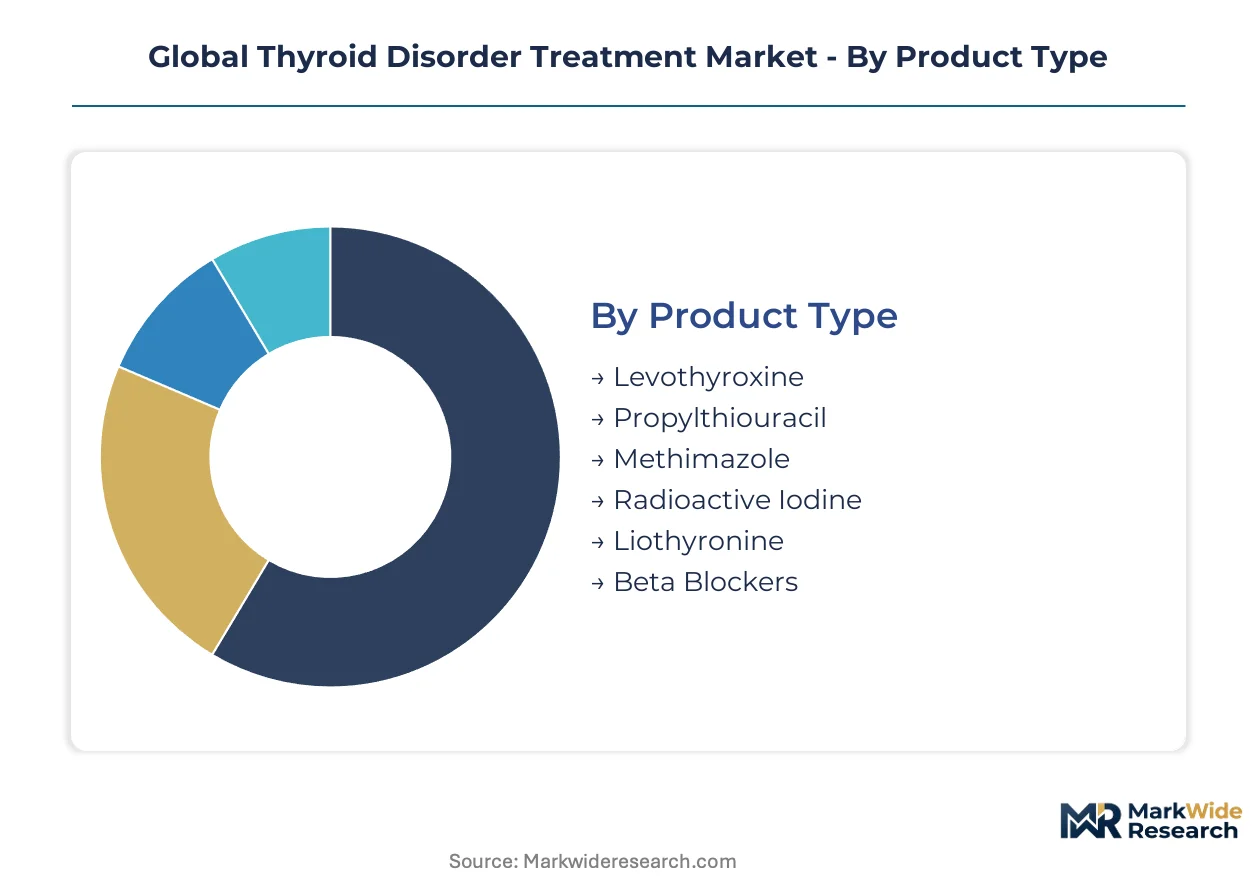
Thyroid disorder treatment segments fracture along pharmacological mechanism, clinical setting, and intervention intensity. Supply concentration in synthetic hormone manufacturing and radioactive isotope production creates divergent margin profiles across each dimension.
Product Type:
Active pharmaceutical ingredient synthesis capacity concentrates among a handful of contract manufacturers, with synthetic thyroid hormones commanding premium pricing against natural alternatives.
- Levothyroxine:Synthetic T4 hormone with predictable bioavailability and narrow therapeutic index requiring precise microgram dosing. Demand concentrates in the United States and Germany where aging demographics drive sustained volume growth through expanded diagnostic screening.
- Radioactive Iodine:Iodine-131 exploits selective thyroid tissue ablation for definitive hyperthyroidism and select cancer treatment. Production depends on limited nuclear reactors, creating geographic supply vulnerability that elevates reimbursement premiums in oncology-aligned therapy areas.
- Propylthiouracil:Thionamide antithyroid agent blocking peripheral T4-to-T3 conversion for acute hyperthyroidism management.
- Methimazole:Preferred first-line thionamide for Graves' disease due to favorable hepatotoxicity profile versus propylthiouracil.
- Liothyronine:Synthetic T3 hormone reserved for refractory cases and myxedema coma where rapid hormone elevation proves critical.
- Beta Blockers:Symptomatic control agents managing adrenergic manifestations without altering underlying hormone dysregulation.
Today's leader: Levothyroxine. Tomorrow's challenger: Radioactive Iodine.
Therapy Area:
Clinical presentation determines reimbursement tier and treatment duration, with malignant conditions accessing premium oncology pathways absent in benign hormone deficiency management.
- Hypothyroidism:Chronic hormone deficiency requiring lifelong replacement therapy. Patient volumes concentrate in Japan and Germany where diagnostic infrastructure expansion supports sustained screening program growth.
- Hyperthyroidism:Excess hormone production managed through antithyroid drugs, ablation, or surgery. Radioactive iodine therapy commands definitive treatment status in the United States where patient preference favors single-intervention resolution over chronic medication.
- Thyroid Nodules:Focal lesions requiring cytological evaluation to exclude malignancy before therapeutic intervention selection.
- Goiter:Diffuse or nodular gland enlargement often managed surgically when compressive symptoms or cosmetic concerns predominate.
- Thyroid Cancer:Malignant neoplasms accessing specialized oncology reimbursement and multidisciplinary care coordination.
- Thyroiditis:Inflammatory conditions spanning infectious, autoimmune, and postpartum etiologies with variable therapeutic intensity.
Hypothyroidism anchors current revenue. Thyroid Cancer commands the steepest expansion trajectory through premium oncology alignment.
End User:
Channel fragmentation accelerates as direct-to-patient fulfillment models displace hospital-based dispensing for maintenance therapies.
- Specialty Endocrinology Centers:Concentrated expertise driving complex case referrals and higher-margin combination therapy adoption. These facilities in the United States, Germany, and Japan capture premium pricing through differentiated clinical decision support.
- Hospitals:Acute care settings managing thyroid storm, postoperative complications, and malignancy staging.
- Clinics:Community-based providers handling stable maintenance therapy and routine monitoring.
- Diagnostic Centers:ISO 15189-accredited facilities standardizing TSH assay reliability to reduce diagnostic variability and accelerate treatment initiation.
- Home Healthcare Providers:Emerging channel for infirm patients requiring administration assistance.
- Pharmacies:Retail and mail-order platforms capturing stable patient volumes through convenience-driven channel shift.
Specialty Endocrinology Centers dominate margin capture. Pharmacies represent the volume expansion frontier.
Delivery Mode:
Intervention intensity correlates with reimbursement tier and regulatory oversight burden, with radioactive and surgical modalities facing distinct approval pathways.
- Oral Medication:Dominant maintenance therapy route for chronic hormone replacement and antithyroid pharmacotherapy. Formulation complexity from levothyroxine's narrow therapeutic index creates manufacturing entry barriers that protect incumbent suppliers.
- Radioactive Therapy:Definitive ablation requiring specialized handling licenses and nuclear medicine infrastructure concentrated in tertiary centers.
- Injectable Therapy:Reserved for myxedema coma and perioperative management where enteral absorption proves unreliable.
- Surgical Intervention:Thyroidectomy for malignancy, compressive goiter, or failed medical management.
- Combination Therapy:Multi-modal approaches integrating pharmacologic, radioactive, and surgical elements for refractory cases.
- Nutritional Supplementation:Adjunctive iodine and selenium protocols supporting synthetic hormone optimization.
Oral Medication sustains volume leadership. Radioactive Therapy claims the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thyroid disorder treatment scaled from mid-20th century synthetic hormone development in Switzerland and the United States, with European pharmaceutical chemistry establishing the foundational manufacturing protocols that persist across contemporary supply chains.
United States
Aging demographics drive diagnostic screening expansion through Medicare-funded TSH testing programs. FDA orphan drug incentives compress development timelines for novel hormonal therapies. Boston and San Francisco anchor specialized endocrinology referral networks where complex case volumes concentrate.
Germany
EMA centralized marketing authorization streamlines pan-European product launches from German headquarters. REACH regulation amendments tighten levothyroxine excipient purity specifications. Bavarian and North Rhine-Westphalian production facilities retrofit API synthesis lines ahead of compliance deadlines.
Japan
PMDA accelerated approval pathways support thyroid cancer therapeutic innovation. METI diagnostic infrastructure subsidies expand specialist referral networks in Tokyo and Osaka. Direct-to-patient pharmacy fulfillment models fragment traditional hospital-based dispensing channels.
Switzerland
Swissmedic maintains stringent bioequivalence standards that protect incumbent hormone replacement suppliers. Precision medicine frameworks integrate pharmacogenomic guidance into clinical practice. Basel and Zurich host concentrated pharmaceutical R&D clusters advancing personalized dosing algorithms.
India
CDSCO streamlined generic approval processes attract contract manufacturing investment for levothyroxine export markets. PLI scheme incentives bolster active pharmaceutical ingredient synthesis capacity. Hyderabad and Ahmedabad emerge as cost-efficient production hubs serving European and North American supply chains.
Global Thyroid Disorder Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established endocrinology portfolios. Market concentration remains moderate, with incumbent manufacturers leveraging narrow therapeutic index expertise to deter generic entry. Three archetypes dominate: synthetic hormone specialists commanding formulation precision premiums, nuclear medicine providers controlling radioactive iodine supply, and natural alternative formulators serving niche patient segments. Strategic moves center on manufacturing scale expansion and diagnostic-pharmacy vertical integration to capture channel margin.
Within the diversified pharmaceutical tier, GSK Plc and Pfizer Inc. exemplify scale-driven market presence, while RLC Labs occupies a distinct position among natural formulation specialists. GSK leverages its established European hospital network relationships to sustain brand loyalty across maintenance therapy segments. Pfizer anchors cost-efficient supply chains through manufacturing volume that supports generic levothyroxine market penetration. RLC Labs differentiates through desiccated thyroid formulations that attract patients seeking non-synthetic hormone alternatives in North American markets.
| Leading Market Players |
|---|
| GSK Plc |
| Viatris Inc. |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Novartis AG |
| AbbVie Inc. |
| Amgen Inc. |
| RLC Labs |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
REACH regulation amendments governing pharmaceutical manufacturing excipients are tightening purity specifications for levothyroxine tablet formulations across European supply chains. This environmental mandate gates qualified supply to manufacturers with retrofitting capacity while segmenting pricing access between compliant premium-tier suppliers and non-compliant standard-tier alternatives facing market exclusion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates thyroid therapeutics, with ISO 15189 accreditation status and brand heritage driving differentiation between tiers. Cost compression in the economy segment intensifies as Indian contract manufacturers expand levothyroxine API export capacity. Specialty endocrinology centers exhibit lowest price sensitivity due to bundled clinical decision support, while retail pharmacies face margin pressure from direct-to-patient fulfillment competition.
Supply Chain Analysis
Single-source vulnerability sits with iodine-131 production, which draws from limited nuclear reactors in the United States, Canada, and South Africa. Synthetic T4 hormone manufacturing rests on Chinese and Indian API synthesis capacity, with German and Swiss facilities handling high-purity formulation. Tariff exposure on pharmaceutical excipients creates supply risk for European manufacturers. Distribution runs through hospital procurement networks for radioactive therapies, while oral medications fragment toward mail-order platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as patient demand shifts toward pharmacogenomic-guided precision dosing that commands premium reimbursement. Modular therapy protocols favor suppliers with diagnostic-pharmacy integration capabilities.
For Market Incumbents: Lock in specialty endocrinology center relationships through clinical decision support tool partnerships that embed TPO gene variant algorithms into prescribing workflows. Defend against desiccated thyroid insurgents by certifying synthetic hormone formulations under evolving EMA bioequivalence standards. Backward integration into diagnostic assay platforms captures upstream margin from ISO 15189-accredited testing expansion.
For New Entrants and Emerging Players: Pharmacogenomic testing platforms offer a technology-first wedge into the thyroid management value chain, with lowest penetration in German and Japanese specialist networks. Target natural hormone alternative segments in North American retail pharmacy channels where patient self-advocacy drives brand switching. Pursue white-label API supply agreements with Indian CDSCO-registered manufacturers to bypass formulation complexity barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialty endocrinology practice networks because fragmented physician ownership creates consolidation arbitrage against hospital system acquisition premiums. Long-term viability hinges on exposure to oncology-aligned radioactive iodine reimbursement tiers rather than commoditized levothyroxine maintenance volumes. Watch FDA orphan drug designation velocity as an inflection indicator for novel hormonal therapy pipeline value.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Decision Support Integration | Embedding TPO pharmacogenomic algorithms into EHR workflows captures specialist prescribing loyalty at German and US centers. |
| Diagnostic-Pharmacy Vertical Integration | Controlling ISO 15189-accredited TSH testing accelerates treatment initiation and locks in downstream therapy selection. |
| Natural Formulation Differentiation | Desiccated thyroid positioning in North American retail channels exploits patient preference for non-synthetic alternatives. |
| Radioactive Isotope Supply Security | Long-term offtake agreements with Canadian and South African reactor operators mitigate iodine-131 geographic vulnerability. |
| EMA Centralized Authorization Pathway | Streamlined pan-European marketing authorization from German headquarters compresses novel therapy launch timelines. |
Research Methodology
Bottom-up patient volume modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with endocrinology practice administrators, hospital formulary directors, nuclear medicine procurement managers, and CDSCO regulatory consultants combined with secondary validation against FDA orphan drug filings, EMA centralized authorization databases, ClinicalTrials.gov thyroid therapy protocols, and ISO 15189 accreditation registries. Triangulation between demand-side patient flow analysis and supply-side manufacturing capacity assessments ensures cross-verified output integrity.
Historical trendline analysis of treatment initiation rates, therapy switching patterns, and reimbursement code utilization established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type, therapy area, end-user channel, and delivery mode dimensions, with regional regulatory clusters treated as distinct forecast strata. CAGRs derived from curve-fitting procedures applied to diagnosed prevalence expansion, screening program penetration, and specialty referral network maturation trajectories. Pharmacogenomic adoption curves and direct-to-patient pharmacy fulfillment velocity served as industry-specific demand modifiers.
The model holds under stable regulatory reimbursement conditions; deviation in FDA bioequivalence standard tightening or EMA REACH enforcement intensity would shift volume trajectories between synthetic and natural hormone alternatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Microwave Ablation Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market