
 Spinal Cord Compression Market | 2026-2036
Spinal Cord Compression Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Cord Compression Market Outlook
A shortage of fellowship-trained spine surgeons is unwinding access bottlenecks across tertiary care centers. Medtronic leverages integrated navigation and robotics platforms to sustain high procedural throughput in complex decompression cases. DePuy Synthes anchors its position through broad implant portfolios spanning cervical and thoracolumbar applications. Stryker competes via capital-light enabling technologies that reduce operative time and hospital length of stay.
Spinal cord compression denotes pathological narrowing of the spinal canal or neural foramina causing mechanical pressure on neural elements, typically quantified by canal diameter measurements below established thresholds and confirmed through MRI or CT myelography. The condition demands intervention to halt progressive neurological deficit and restore functional mobility. Surgical instruments occupy the largest product category as decompression hardware remains essential across anterior and posterior approaches. Minimally invasive surgery represents the fastest-growing technology segment as tubular retractors and percutaneous fixation reduce tissue disruption and accelerate recovery. Rehabilitation devices command durable margin pools due to recurring utilization in postoperative protocols and chronic compression management.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development cycles and commercialization timelines for implantable devices. Japan's PMDA and Health Canada enforce parallel but distinct biocompatibility and clinical evidence standards that manufacturers must navigate for market access. Stakeholders should monitor evolving CMS coverage determinations for neurostimulation adjuncts and ambulatory surgical center eligibility for decompression procedures.
Market Dynamics
The spinal cord compression market is being fundamentally restructured by the migration of decompression procedures from inpatient to ambulatory surgical centers, compressing reimbursement cycles while demanding instrumentation portability and reduced sterilization footprints.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for novel decompression implants compress time-to-market by 12-18 months, incentivizing R&D investment in expandable interbody cages and dynamic stabilization systems.
- Japan's Super-Aged Society:METI-funded regional spine centers in Hokkaido and Kyushu expand procedure capacity to address cervical spondylotic myelopathy prevalence exceeding 15% in populations over 70 years.
- Tube-Based Retractor Systems:Percutaneous access technologies reduce paraspinal muscle dissection, cutting postoperative opioid requirements and qualifying patients for same-day discharge protocols.
Market Restraints
- Titanium Alloy Price Volatility:Sponge titanium input costs fluctuate with aerospace demand cycles, compressing margins on posterior cervical plating systems where material constitutes 40% of COGS.
- EU MDR Technical Documentation Burden:Legacy implant families face 18-24 month recertification timelines under MDR 2017/745, freezing portfolio updates and diverting regulatory affairs capacity from new product filings.
- Non-Operative Management Substitution:High-dose steroid protocols and emerging neuroprotective pharmacotherapies delay surgical intervention in mild-to-moderate compression cases, particularly among comorbid elderly cohorts.
Strategic Opportunities
- India's Tier-2 City Penetration:CDSCO streamlined medical device rules and PLI scheme incentives for domestic manufacturing create first-mover advantage in Chennai, Pune, and Ahmedabad metro corridors.
- Robotic-Navigation Convergence:Integration of intraoperative imaging with autonomous drill positioning enables single-position lateral approaches, collapsing operative time and anesthesia exposure.
- CMS ASC Coverage Expansion:2024-2025 procedural code additions for lumbar decompression in ambulatory settings unlock capital-light site-of-care strategies outside traditional hospital purchasing committees.
Industry Challenges
- Fellowship-Trained Spine Surgeon Scarcity:North American academic centers graduate 150-180 spine specialists annually against replacement demand for 400+ retiring surgeons, extending referral wait times to 12-16 weeks.
- EU MDR Notified Body Capacity Bottleneck:Only 12 designated entities serve 27 member states for Class III implantable devices, creating 9-14 month audit queue delays that freeze commercialization timelines.
- Legacy EMR Integration Friction:Surgical navigation platforms require custom HL7 FHIR interfaces with Epic and Cerner deployments, consuming 6-9 months of health system IT resources and delaying capital approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Cord Compression Market |
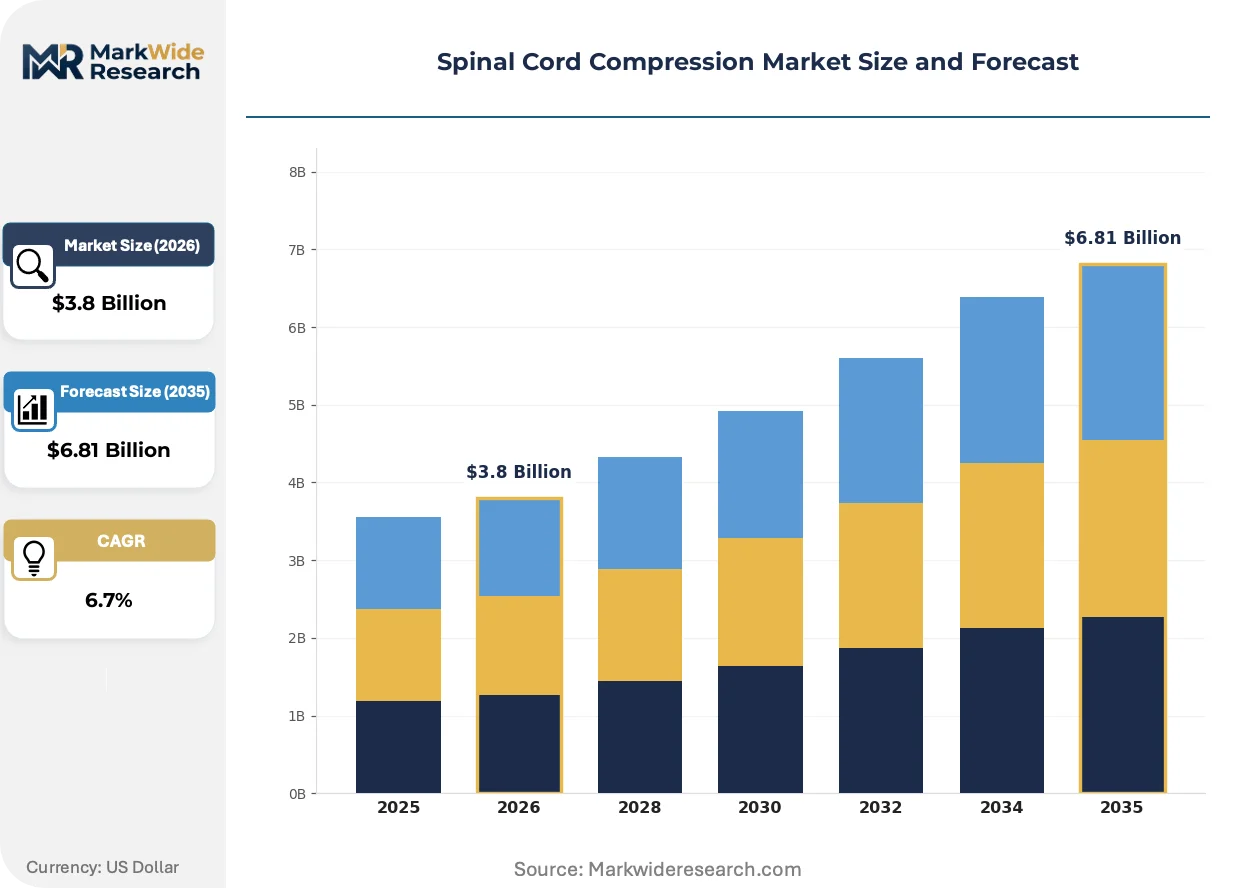
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Imaging Systems, Diagnostic Tools, Rehabilitation Devices Care Setting: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Technology: Minimally Invasive Surgery, External Fixation, Neurostimulation, Radiation Therapy End User: Neurologists, Orthopedic Surgeons, Physical Therapists, Patients |
| Companies Covered | Medtronic, DePuy Synthes, Stryker, NuVasive, Zimmer Biomet, Boston Scientific, Globus Medical, Aesculap, K2M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Cord Compression Market Strategic Shifts
Instrumentation form factors and procedural venues are undergoing simultaneous compression, with device miniaturization enabling ambulatory migration while regulatory frameworks force evidence generation at unprecedented granularity.
Expandable titanium interbody cages with integrated lordotic adjustment mechanisms are miniaturizing access requirements for transforaminal lumbar interbody fusion. Community hospital systems in Texas and Florida are adopting these systems at 35% annual clip, collapsing the historical distinction between academic and non-academic center capabilities. The technology is miniaturizing operative footprints to 22mm working channels, qualifying procedures for outpatient reimbursement codes previously reserved for discectomy alone.
EU MDR Annex XIV clinical evaluation requirements now mandate post-market surveillance with patient-level outcomes data for all Class III spinal implants. Manufacturers must maintain 15-year implant registries or face certificate suspension, forcing restructuring of quality management systems. Cervical total disc replacement portfolios face disproportionate scrutiny given long-term adjacent segment degeneration uncertainties, prompting some firms to deprioritize European launches.
Hospital value analysis committees now require 90-day episode cost guarantees before capitalizing robotic navigation platforms. Device vendors respond with risk-sharing arrangements that unbundle hardware from disposable instrumentation, transferring utilization risk from IDN balance sheets to supplier P&Ls. This procurement evolution is most advanced in California's integrated delivery networks, where Kaiser Permanente and Sutter Health have standardized gainshare contracting for spine service lines.
Spinal Cord Compression Market Segmentation
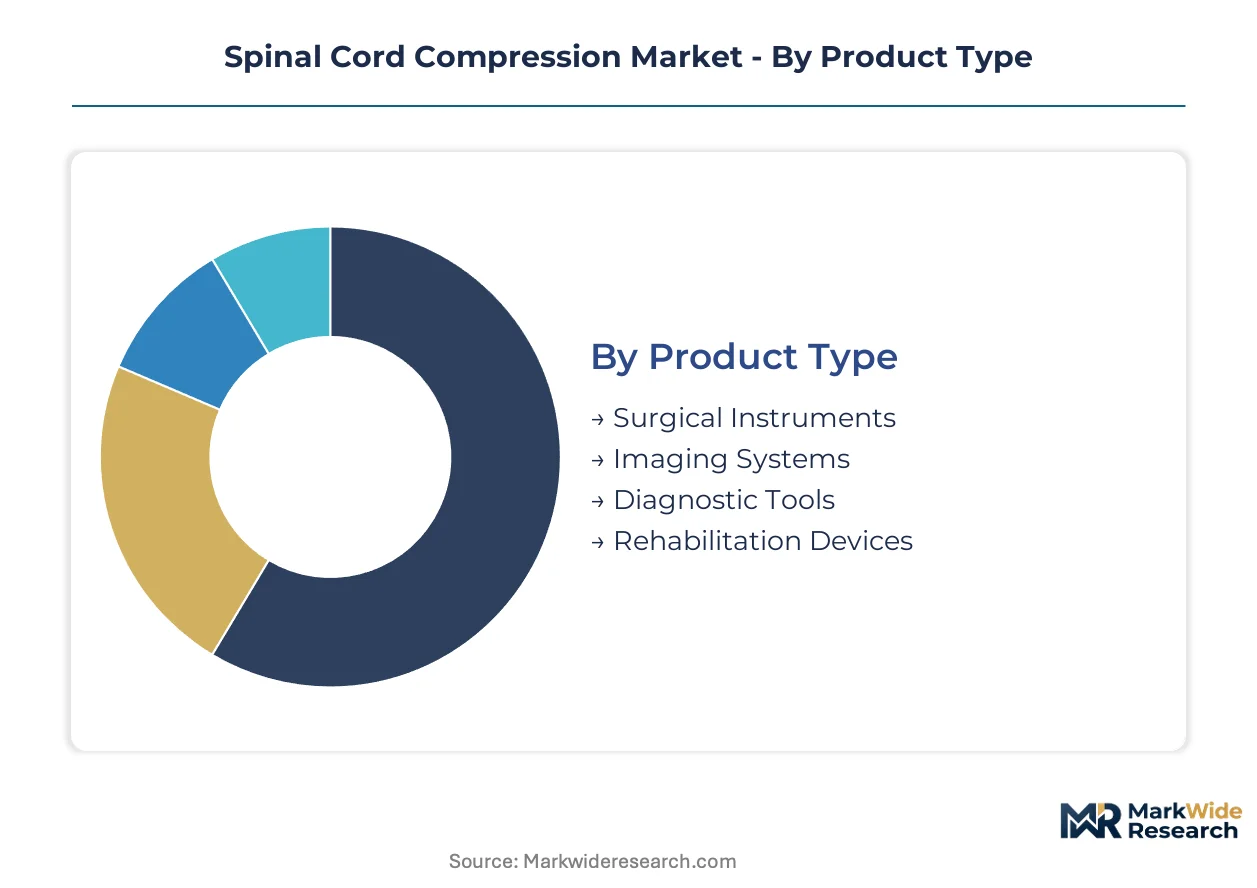
Segmentation reveals how reimbursement pathways and site-of-care migration reshape procurement patterns across spinal cord compression interventions. Product categories face divergent regulatory scrutiny while care settings fragment around ambulatory eligibility.
Product Type:
FDA 510(k) clearance timelines and EU MDR technical documentation burdens stratify development costs across hardware categories.
- Surgical Instruments:Titanium and PEEK-based decompression hardware dominates hospital purchasing volumes. Academic medical centers in the United States, Germany, and Japan anchor demand for integrated navigation-compatible instrument sets.
- Imaging Systems:Intraoperative CT and 3D fluoroscopy platforms enable real-time canal decompression verification. Tertiary hospitals in Texas and Bavaria concentrate procurement for these capital-intensive systems.
- Diagnostic Tools:MRI-compatible myelography kits and dynamic flexion-extension radiography systems.
- Rehabilitation Devices:Cervical traction units and neuromuscular electrical stimulation hardware.
Surgical Instruments handles the majority of throughput; Imaging Systems is the fastest mover on share.
Care Setting:
CMS ASC coverage determinations and Japan's Diagnosis Procedure Combination reimbursement tiers concentrate margin extraction in specific venues.
- Hospitals:Tertiary centers manage complex multilevel decompressions and revision surgeries. Major academic hospitals in California, Massachusetts, and Tokyo maintain the highest procedural volumes for instrumented fusions.
- Outpatient Clinics:Ambulatory surgical centers capture lumbar microdiscectomy and single-level decompression cases. Freestanding ASCs in Florida and Arizona lead same-day discharge protocol adoption.
- Rehabilitation Centers:Postoperative protocols for cervical spondylotic myelopathy recovery.
- Home Care:Patient-administered traction and neurostimulation device management.
Outpatient Clinics is expanding most quickly as site-of-care migration accelerates; Hospitals retains the dominant revenue position.
Technology:
Clinical evidence requirements and surgeon training curves determine adoption velocity across intervention modalities.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw fixation reduce paraspinal muscle disruption. Community hospital systems in Texas deploy these technologies at accelerating rates for outpatient qualification.
- Neurostimulation:Spinal cord stimulators address failed back surgery syndrome and chronic compression sequelae. CMS national coverage determinations shape implantation volume in Medicare populations.
- External Fixation:Halo vest and rigid orthotic stabilization for traumatic compression.
- Radiation Therapy:Stereotactic radiosurgery for metastatic epidural spinal cord compression.
Minimally Invasive Surgery commands the steepest expansion trajectory; Neurostimulation maintains durable recurring revenue per implanted generator.
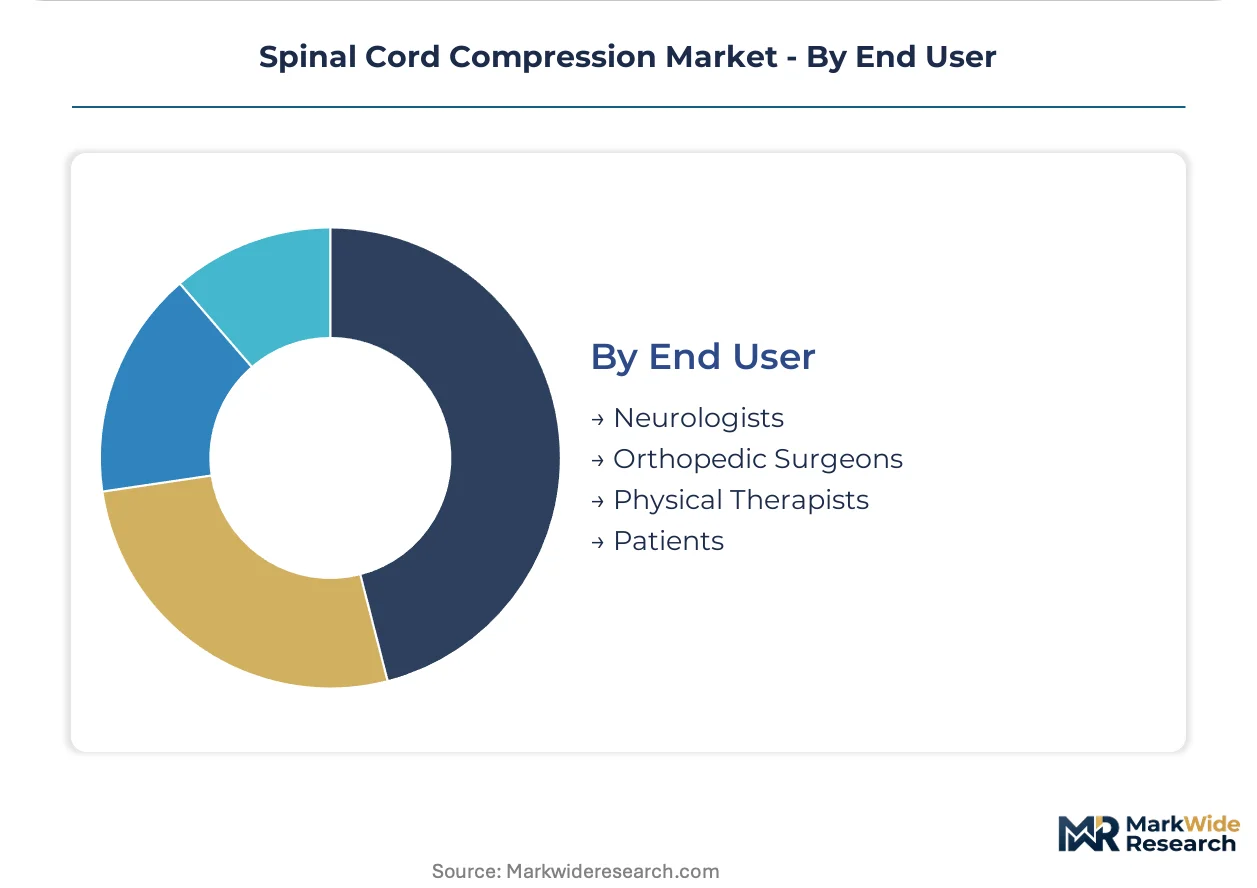
End User:
Fellowship training availability and scope-of-practice regulations concentrate procedure authority among specific specialist cohorts.
- Orthopedic Surgeons:Degenerative spondylolisthesis and deformity correction cases dominate their decompression volumes. North American orthopedic spine specialists handle the majority of thoracolumbar instrumented fusions.
- Neurologists:Myelopathy diagnosis and non-operative management protocols. Japanese neurologists coordinate closely with METI-funded regional spine centers for cervical spondylotic myelopathy triage.
- Physical Therapists:Postoperative mobilization and chronic compression functional restoration.
- Patients:Self-directed home traction and wearable neurostimulation device management.
Orthopedic Surgeons performs the majority of operative interventions; Physical Therapists is gaining share fastest as rehabilitation protocols extend into home settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways and CMS coverage determinations anchor procedural economics in the United States, while parallel regulatory frameworks in Germany and Japan concentrate advanced decompression technology adoption. Aging demographics across these markets drive sustained intervention demand as cervical spondylotic myelopathy prevalence escalates.
United States
Cervical and thoracolumbar decompression volumes concentrate in California, Massachusetts, and Texas academic centers where integrated delivery networks standardize robotic navigation procurement. CMS 2024-2025 ASC coverage expansions for lumbar procedures unlock ambulatory site-of-care migration. Hospital value analysis committees in Kaiser Permanente and Sutter Health systems now mandate 90-day episode cost guarantees before capitalizing spine platforms.
Germany
Bavarian tertiary hospitals anchor EU procedural volume for multilevel instrumented fusions, with EU MDR 2017/745 recertification timelines compressing legacy portfolio updates. The country's statutory health insurance framework maintains favorable reimbursement for minimally invasive tubular retractor systems. Berlin-Brandenburg medical centers concentrate adoption of intraoperative 3D fluoroscopy verification technologies.
Japan
METI-funded regional spine centers in Hokkaido and Kyushu expand capacity to address cervical spondylotic myelopathy exceeding 15% prevalence in populations over 70 years. PMDA biocompatibility standards enforce distinct clinical evidence requirements for implantable devices. Kanto and Kansai metropolitan clusters concentrate fellowship-trained surgeon density and navigation-compatible instrument set procurement.
India
CDSCO streamlined medical device rules and PLI scheme incentives for domestic manufacturing create first-mover positioning in Chennai, Pune, and Ahmedabad corridors. Tier-2 city hospital systems accelerate adoption of capital-light decompression technologies as surgical infrastructure expands. Maharashtra and Gujarat sub-regions concentrate orthopedic surgeon training capacity and private hospital capital investment.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex revision decompressions in London and Southeast tertiary centers. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while diverging from EU MDR implementation timelines. Midlands and North England regions experience access bottlenecks as fellowship-trained spine surgeon scarcity extends referral wait times.
Spinal Cord Compression Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the spinal cord compression market. The vendor base stratifies into three tiers: diversified medtech conglomerates with integrated navigation platforms, mid-cap spine specialists with focused implant portfolios, and emerging players with disposable-intensive business models. Strategic moves center on M&A for robotics capabilities and risk-sharing arrangements that transfer utilization risk from provider balance sheets to supplier economics.
Among diversified conglomerates, Medtronic, DePuy Synthes, and Stryker occupy positions spanning navigation hardware, implantable devices, and enabling technologies. These entities represent the integrated platform archetype where procedural throughput and hospital partnership depth determine competitive positioning. Mid-cap specialists exemplify focused portfolio strategies, while emerging entrants sit within capital-light segments targeting ambulatory surgical center qualification.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker |
| NuVasive |
| Zimmer Biomet |
| Boston Scientific |
| Globus Medical |
| Aesculap |
| K2M |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers and EU MDR Class III implantable device classifications gate both supplier qualification and price stratification across spinal decompression hardware. These regulatory thresholds compress margin structures for uncertified manufacturers while enabling premium positioning for navigation-compatible instrument sets in tertiary hospital systems.
Pricing Analysis
Price spreads between the United States and Germany exceed those between Germany and Japan for comparable titanium interbody cage systems. Three-tier pricing structure across premium navigation-integrated, standard instrument-compatible, and economy non-integrated levels dominates procurement negotiations. Cost compression in standard tiers is intensifying because hospital value analysis committees now mandate 90-day episode cost guarantees before capital approval. Academic medical centers in California and Massachusetts exhibit lowest price sensitivity; community hospital systems in Texas and Florida face highest pressure.
Supply Chain Analysis
Strategic stockpiling of titanium sponge and PEEK resin dominates over just-in-time preferences given aerospace demand cycles and medical-grade polymer lead times. Supply concentrates in the United States for navigation platform assembly, Germany for precision machining of retractor systems, and Japan for high-purity titanium alloy processing. Raw material dependencies include sponge titanium, medical-grade PEEK, and cobalt-chrome alloys. Single-source vulnerability in EU MDR-notified body certification creates 9-14 month audit queues. Distribution runs through integrated delivery network purchasing committees and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from high-dose steroid protocols and emerging neuroprotective pharmacotherapies that delay surgical intervention in mild-to-moderate compression cases. This therapeutic substitution threat intensifies as comorbid elderly cohorts expand across all major markets.
For Market Incumbents: Fortify navigation-robotics integration capabilities to sustain procedural throughput advantages in complex multilevel decompressions. Deepen backward integration into titanium alloy processing to buffer aerospace demand cycle volatility. Secure EU MDR recertification priority for legacy cervical total disc replacement portfolios before certificate suspension risks materialize. For New Entrants and Emerging Players: Postoperative rehabilitation device management in home care settings represents the most penetrable white-space target where incumbents under-serve patient-administered traction and wearable neurostimulation protocols. Tier-2 city hospital systems in India offer geographic entry points with streamlined CDSCO rules and PLI scheme incentives. Pursue disposable-intensive business models that reduce capital barriers for ambulatory surgical center qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across robotic-navigation convergence segments as software-defined platforms displace hardware-heavy systems. Mid-cap spine specialists with focused implant portfolios and established hospital partnerships present acquisition target archetypes with defensible margin pools. Watch CMS ASC coverage determination expansions as the signal indicating ambulatory site-of-care migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Expedited review pathways compress time-to-market for expandable interbody cages by 12-18 months. |
| EU MDR Technical Documentation Investment | Recertification priority prevents 18-24 month portfolio freezes under MDR 2017/745. |
| Hospital System Risk-Sharing Arrangement | Gainshare contracting with Kaiser Permanente and Sutter Health transfers utilization risk to suppliers. |
| Robotic-Navigation Platform Integration | Autonomous drill positioning collapses operative time for single-position lateral approaches. |
| India Tier-2 City Manufacturing Footprint | PLI scheme incentives in Chennai and Pune corridors capture first-mover positioning. |
Study Parameters
Cross-validation between hospital procurement database analysis and CMS Medicare claims data anchors the qualitative findings in observable utilization patterns. Primary interviews with spine surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers combine with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, PMDA approval summaries, and hospital capital expenditure disclosures. Bottom-up procedure volume estimates and top-down implant shipment data complete the triangulation.
Sensitivity analysis across titanium alloy price volatility scenarios, EU MDR recertification timeline delays, and CMS ASC coverage expansion trajectories tests forecast robustness. The analytical framework segments by product type, care setting, technology modality, and end-user specialist across the projection horizon. CAGRs derive from procedure volume growth rates applied to average selling price trends. Forecast inputs include aging demographic projections, fellowship-trained surgeon graduation rates, and regulatory pathway evolution.
Forecasts assume regulatory continuity in FDA premarket notification pathways, EU MDR 2017/745 implementation, and Japan PMDA biocompatibility standards; material policy shifts would require re-modeling. Revision becomes warranted when non-operative management substitution rates or ambulatory surgical center eligibility expansions cross thresholds that materially alter procedure site-of-care distribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Tetanus Treatment Market