
 Squamous Cell Carcinoma Treatment Market | 2026-2036
Squamous Cell Carcinoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Squamous Cell Carcinoma Treatment Market Analytics
Precision-medicine-grade biomarker stratification is bifurcating the Squamous Cell Carcinoma Treatment Market into premium-tier and standard-care pathways. Regeneron Pharmaceuticals leverages its bispecific antibody platform to compete in head and neck indications. Merck & Co. anchors its position through sustained dominance in PD-1 checkpoint inhibition across multiple SCC sites.
Squamous Cell Carcinoma Treatment encompasses therapeutic interventions targeting malignant epithelial neoplasms arising from squamous cell differentiation, encompassing systemic agents with specific molecular targets such as EGFR inhibitors and anti-PD-1/PD-L1 monoclonal antibodies designed to interrupt immune evasion mechanisms. These interventions serve the primary commercial purpose of extending progression-free survival and overall survival in patients with locally advanced or metastatic disease across anatomical subsites. Immunotherapy commands the dominant margin pool as hospitals prioritize checkpoint inhibitor protocols, while targeted therapy segments specializing in EGFR-directed agents occupy faster-expanding niches in lung and head and neck applications where genomic profiling guides therapy selection.
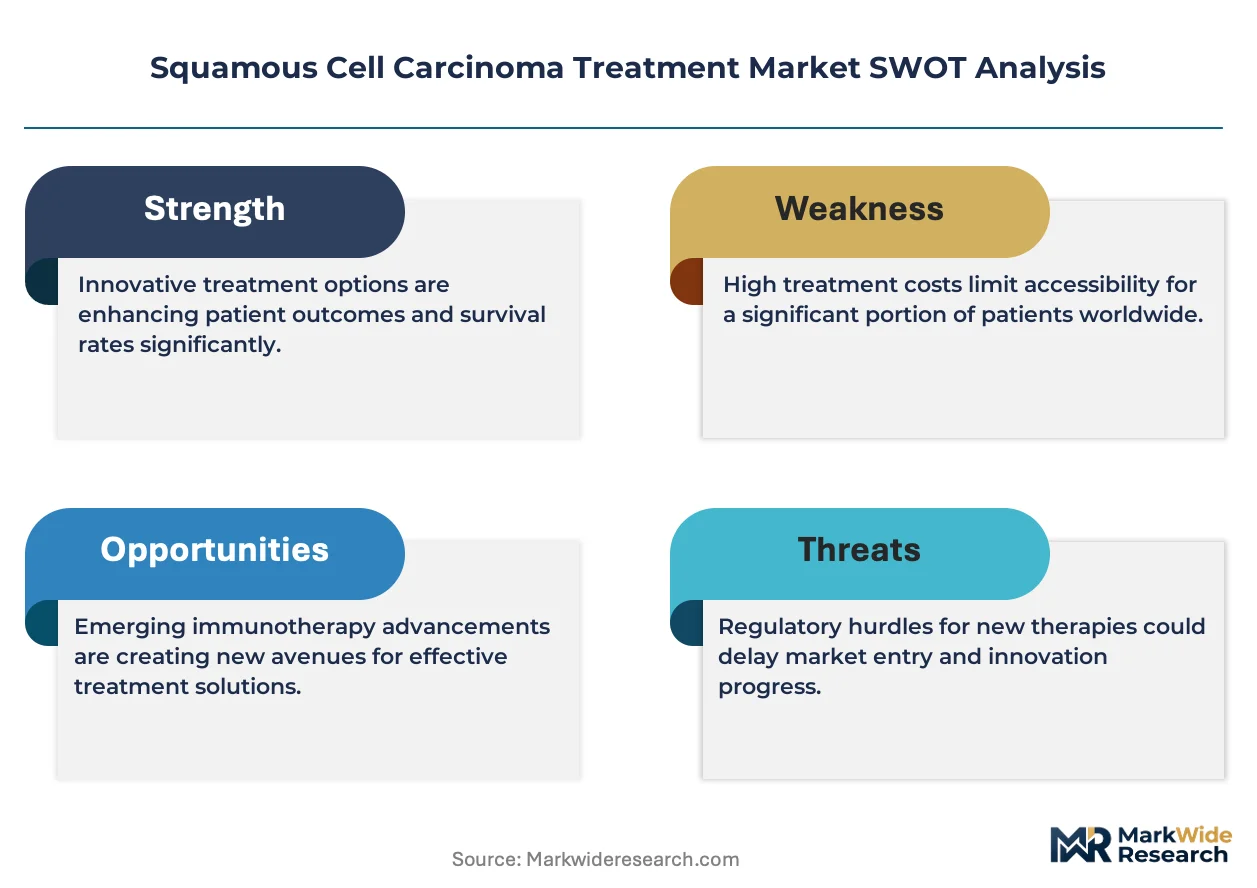
The FDA's Breakthrough Therapy designation and the EMA's Priority Medicines scheme are accelerating market access for novel SCC therapeutics by compressing review timelines and enabling earlier patient exposure. The EU's MDR framework imposes stricter clinical evidence requirements on companion diagnostics that co-determine treatment eligibility, reshaping how manufacturers align drug-device submissions. Stakeholders must monitor evolving reimbursement thresholds for combination regimens as health technology assessment bodies tighten budget-impact criteria across major markets.
Market Dynamics
Checkpoint inhibitor therapy is miniaturizing treatment protocols across hospital oncology departments, compressing infusion center footprints while expanding patient throughput. This structural compression is forcing capital reallocation toward ambulatory care infrastructure and remote monitoring capabilities.
Growth Catalysts
- FDA Accelerated Approval Pathways:The Breakthrough Therapy designation compresses development timelines for novel immunotherapies, enabling earlier commercial access for patients with limited treatment options.
- Biomarker-Driven Stratification:PD-L1 expression testing and tumor mutational burden profiling are routing patients toward precision-matched regimens in academic medical centers.
- China:The NMPA's priority review channels for innovative oncology drugs are expanding market access for domestic and multinational manufacturers targeting head and neck indications.
Market Restraints
- Platinum Supply Concentration:Cisplatin and carboplatin production concentrates in a limited supplier base, exposing combination therapy protocols to API shortage risk.
- Cold Chain Infrastructure Gaps:Temperature-sensitive biologics require specialized logistics networks that remain underdeveloped in secondary metropolitan markets.
- EMA MDR Compliance Burden:Stricter clinical evidence requirements for companion diagnostics are extending co-approval timelines and raising submission costs.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered checkpoint inhibitors would displace infusion-dependent protocols and unlock home-based care models.
- India:CDSCO's streamlined oncology drug approval processes and expanding health insurance penetration are creating accessible volume pools for biosimilar entrants.
- Digital Therapeutic Integration:Remote patient monitoring platforms combined with AI-adverse event detection are enabling decentralized trial participation and real-world evidence generation.
Industry Challenges
- Immuno-oncology Specialist Scarcity:Qualified investigators capable of managing complex combination toxicities remain concentrated in tertiary referral centers.
- Cross-Border Trial Harmonization:Divergent informed consent requirements between FDA and EMA jurisdictions complicate multi-regional study execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squamous Cell Carcinoma Treatment Market |
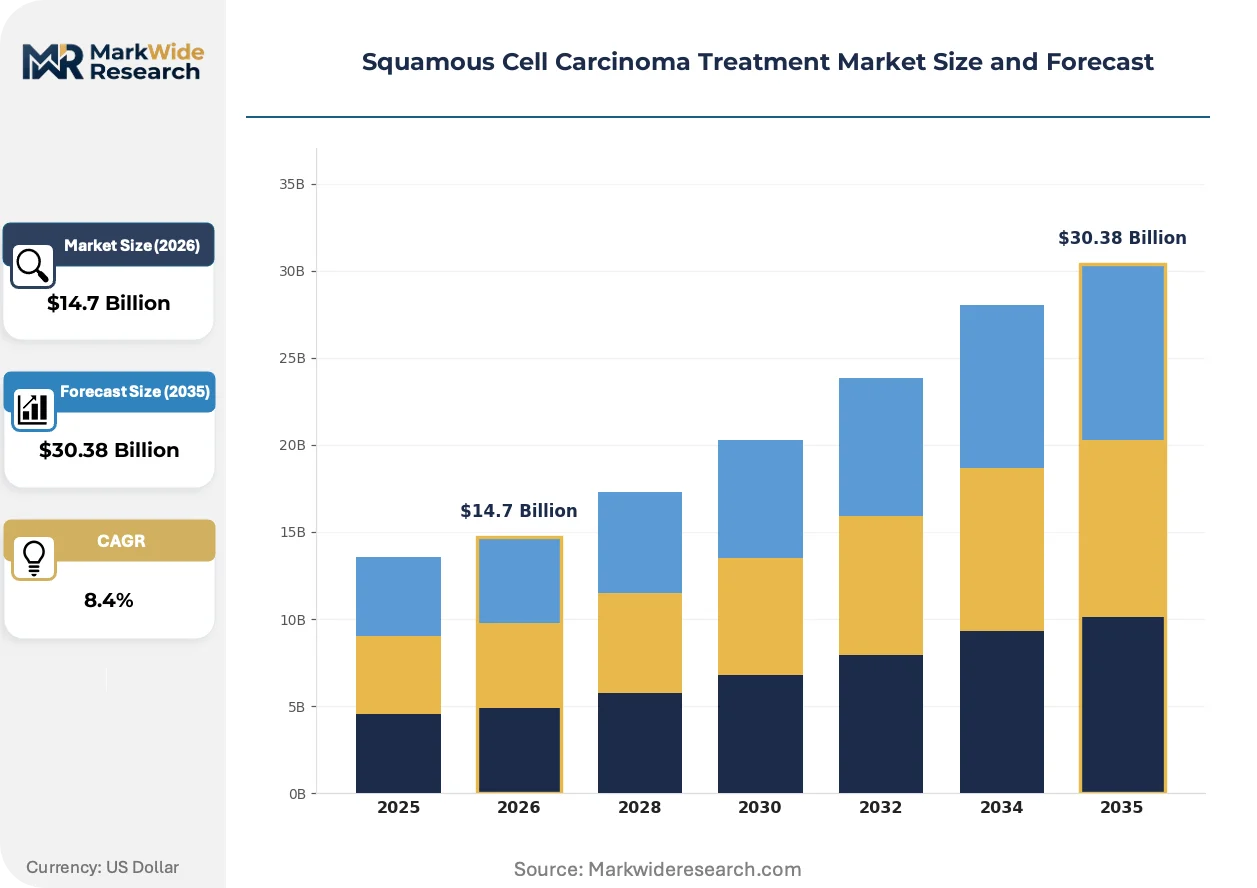
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy Application: Head and Neck, Skin, Lung, Esophagus End User: Hospitals, Clinics, Research Institutions, Homecare Settings Delivery Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | Regeneron Pharmaceuticals, Merck & Co., Bristol-Myers Squibb Company, AbbVie Inc., Johnson & Johnson Private Limited, Pfizer Inc, AstraZeneca, Incyte Corporation, GSK plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squamous Cell Carcinoma Treatment Market Evolving Landscape
Bispecific antibody engineering is compressing the therapeutic window between efficacy and toxicity, enabling novel mechanism combinations previously excluded by overlapping adverse event profiles. These molecular advances are reshaping competitive positioning across head and neck, lung, and cutaneous indications.
Next-generation sequencing panels are miniaturizing genomic profiling from tissue-intensive workflows to liquid biopsy platforms, reducing turnaround from weeks to days. Community oncology practices are adopting these streamlined assays to retain patients who would otherwise transfer to academic centers for molecular triage. This decentralization is compressing referral network dependencies and redistributing treatment initiation across care settings.
The EU's MDR framework is elevating clinical evidence standards for companion diagnostic co-submissions, requiring prospective validation studies that parallel drug development timelines. Manufacturers are responding by integrating device strategy earlier into therapeutic program planning, with some pursuing separate PMA tracks to de-risk approval sequencing. Head and neck applications face the steepest compliance burden given the fragmented biomarker landscape across anatomical subsites.
Hospital purchasing consortiums are consolidating oncology drug procurement through centralized specialty pharmacy arrangements, displacing traditional wholesaler relationships. These aggregated buying structures favor manufacturers with robust patient support programs and transparent pricing mechanisms. The United States exhibits the most advanced concentration, with several regional health systems establishing captive specialty pharmacies for infused immunotherapy administration.
Squamous Cell Carcinoma Treatment Market Segmentation
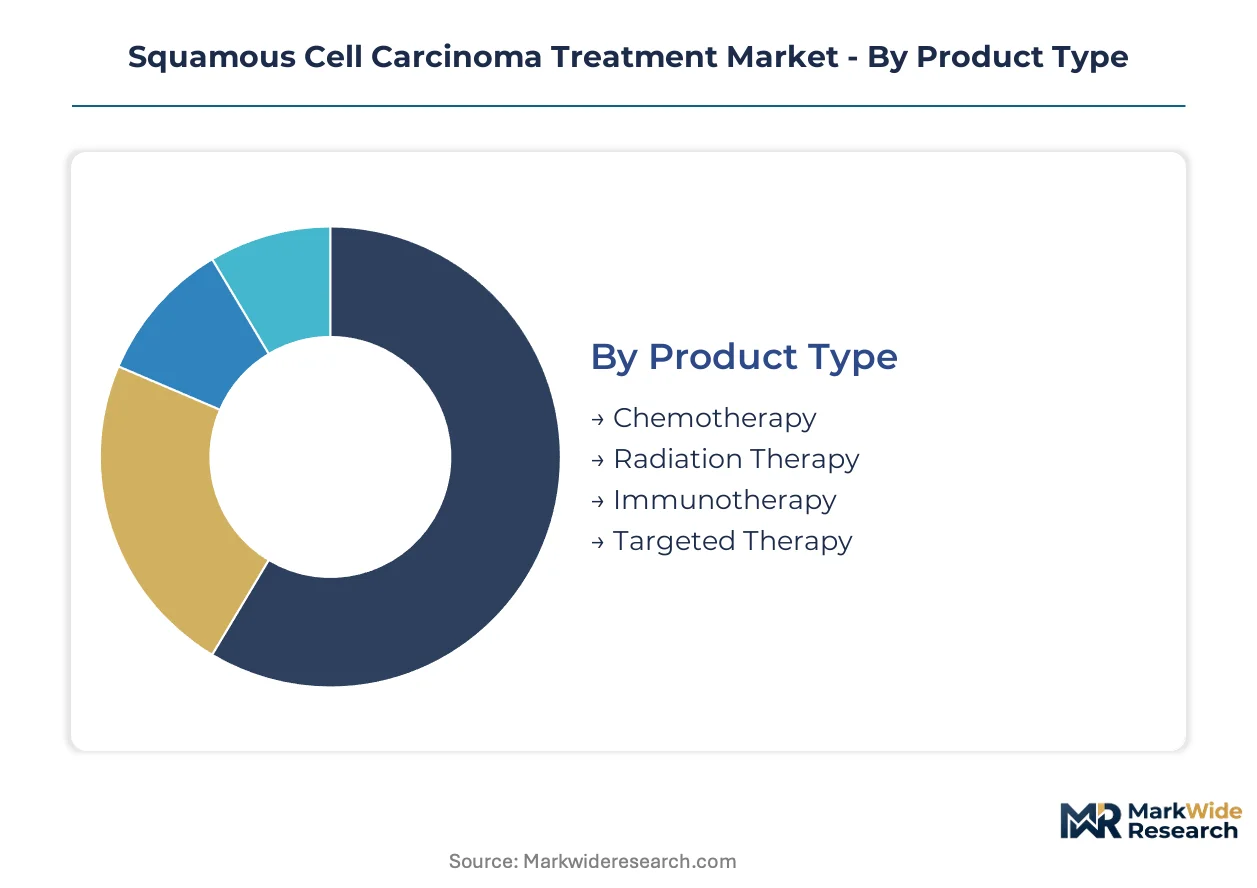
Squamous cell carcinoma treatment segments diverge sharply in reimbursement intensity and clinical infrastructure requirements. Molecular stratification is compressing traditional modality boundaries as hospitals reallocate capacity toward precision-matched protocols.
Product Type:
Substitution pressure intensifies as immunotherapy displaces cytotoxic agents in first-line protocols across major markets.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways command premium reimbursement through Medicare's outpatient prospective payment system. Academic medical centers concentrate infusion capacity for combination regimens while community practices face capital constraints.
- Targeted Therapy:EGFR-directed small molecules and monoclonal antibodies serve biomarker-selected populations in lung and head and neck indications. Companion diagnostic requirements under FDA and EMA frameworks extend co-approval timelines.
- Chemotherapy:Platinum-based regimens retain utility in combination protocols despite margin compression.
- Radiation Therapy:External beam and brachytherapy approaches integrate with systemic agents in locoregional disease management.
Immunotherapy anchors the volume base while targeted therapy gains share at the steepest rate.
Application:
Cost tier stratification separates curative-intent protocols from palliative care pathways across anatomical subsites.
- Head and Neck:Multidisciplinary care coordination demands specialized surgical, radiation, and medical oncology integration. Medicare reimbursement favors consolidated academic center delivery over fragmented community settings.
- Lung:Non-small cell histologies with squamous differentiation drive biomarker testing volume through next-generation sequencing panels. FDA breakthrough designations accelerate access for PD-L1-high populations.
- Skin:Cutaneous squamous cell carcinoma presents lower acuity profiles amenable to outpatient surgical and topical management.
- Esophagus:Esophageal squamous cell carcinoma concentrates in East Asian populations with distinct genomic profiles.
Head and neck applications dominate reimbursement value while lung indications expand most quickly through biomarker adoption.
End User:
Customer type fragmentation reflects divergent capital intensity and regulatory compliance burdens across care settings.
- Hospitals:Inpatient and outpatient oncology departments aggregate infusion capacity, clinical trial access, and multidisciplinary tumor boards. 340B drug pricing programs distort procurement economics for eligible institutions.
- Clinics:Community oncology practices compete through convenience and patient retention despite limited molecular profiling capabilities.
- Research Institutions:NCI-designated cancer centers anchor early-phase trial infrastructure and investigator networks.
- Homecare Settings:Subcutaneous formulation advances could displace infusion-dependent protocols.
Hospitals retain the dominant patient volume while homecare settings present the steepest expansion trajectory through administration innovation.
Delivery Mode:
Supply concentration in cold chain biologics creates infrastructure barriers for route-of-administration substitution.
- Intravenous:Infusion center capacity constraints limit patient throughput for checkpoint inhibitor protocols. Hospital construction pipelines prioritize ambulatory expansion.
- Oral:Small molecule tyrosine kinase inhibitors enable decentralized administration with adherence monitoring requirements.
- Subcutaneous:Formulation development targets displacement of IV checkpoint inhibitors through patient convenience and cost reduction.
- Topical:Localized cutaneous disease management avoids systemic toxicity profiles.
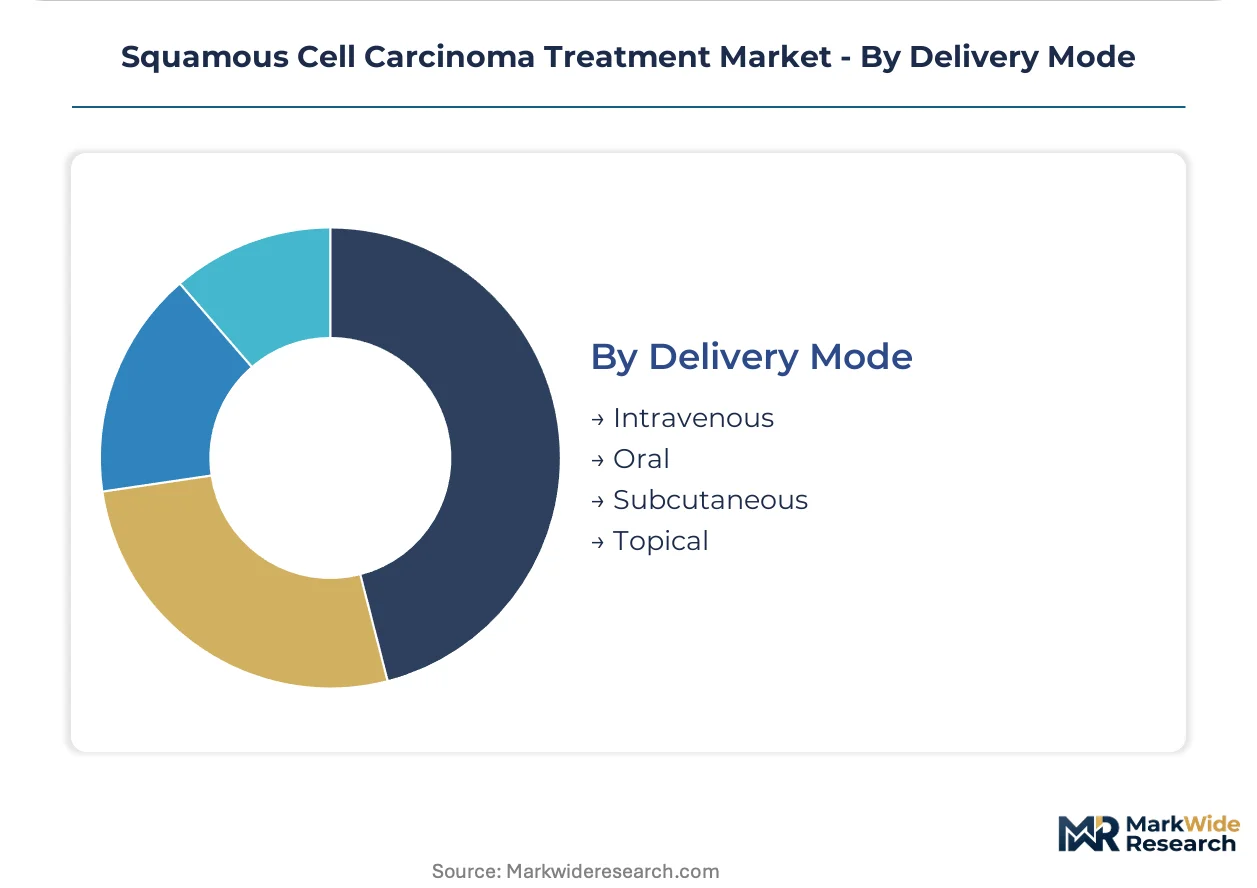
Intravenous delivery anchors current practice patterns while subcutaneous routes climb the fastest through pipeline investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in oncology biologics while importing specialized platinum-based API intermediates from concentrated European and Asian suppliers. Germany and Switzerland anchor European export capacity for checkpoint inhibitor manufacturing. China's NMPA approval pathways are accelerating domestic production of biosimilar immunotherapies.
United States
Medicare's outpatient prospective payment system drives hospital consolidation of infusion capacity into academic medical centers. FDA Breakthrough Therapy designations compress review timelines for PD-1 inhibitors targeting head and neck indications. The Greater Boston cluster anchors early-phase trial infrastructure alongside NCI-designated cancer centers in Houston and New York Metro.
Germany
EMA centralized marketing authorizations enable German manufacturers to serve EU-wide distribution networks for combination oncology regimens. The country's national pharmaceutical regulator enforces stringent GMP standards for cold chain biologics manufacturing. The Rhine-Main biotech corridor concentrates formulation facilities for subcutaneous checkpoint inhibitor development.
China
NMPA priority review channels for innovative oncology drugs are expanding market access for domestic manufacturers targeting esophageal squamous cell carcinoma. The regulator's conditional approval framework enables earlier commercialization based on single-arm trial data. Shanghai's Zhangjiang Hi-Tech Park anchors multinational R&D centers alongside domestic biotech incubators.
Japan
PMDA's Sakigake designation system accelerates access for novel immuno-oncology combinations in lung squamous histologies. The national health insurance price listing process creates predictable reimbursement pathways for biomarker-selected therapies. The Kansai region around Osaka maintains specialized manufacturing capacity for antibody-drug conjugates.
India
CDSCO's streamlined oncology drug approval processes are attracting biosimilar manufacturers seeking volume expansion in immunotherapy segments. Expanding private health insurance penetration creates accessible patient pools for outpatient infusion protocols. Hyderabad's Genome Valley anchors contract research and manufacturing organizations serving multinational clinical trial programs.
Squamous Cell Carcinoma Treatment Market Competitive Landscape
Listed leaders compete with private specialists across checkpoint inhibitor development and companion diagnostic alignment. The market structure concentrates around three to five multinational pharmaceutical groups controlling PD-1/PD-L1 franchise assets, with mid-cap biotech specialists occupying bispecific antibody and targeted therapy niches. Strategic archetypes include integrated immunotherapy platforms, precision medicine specialists with biomarker capabilities, and regional biosimilar manufacturers. Competitive moves center on combination regimen patent estates and subcutaneous formulation differentiation.
Among the integrated platform tier, Merck & Co. and Bristol-Myers Squibb Company occupy positions anchoring first-line checkpoint inhibition across multiple squamous cell carcinoma subsites. Regeneron Pharmaceuticals exemplifies the bispecific antibody specialist archetype competing in head and neck indications through mechanism-of-action diversification. These three entities represent distinct competitive vectors: scale-driven immunotherapy dominance, combination regimen leadership, and novel platform engineering.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| Merck & Co. |
| Bristol-Myers Squibb Company |
| AbbVie Inc. |
| Johnson & Johnson Private Limited |
| Pfizer Inc |
| AstraZeneca |
| Incyte Corporation |
| GSK plc. |
| Others |
Value Network & Pricing Analysis
Batch-scale manufacturing economies in monoclonal antibody production concentrate supply among three dominant CDMO networks, compressing cost floors for checkpoint inhibitors while elevating price premiums for subcutaneous formulations. This scale asymmetry bifurcates procurement negotiations between academic medical centers with 340B pricing access and community oncology practices facing wholesale acquisition cost exposure.
Pricing Analysis
Hospital purchasing consortiums anchor pricing structure through centralized specialty pharmacy arrangements that aggregate immunotherapy volume. Three-tier pricing separates breakthrough-designated biologics from standard-of-care agents and biosimilar alternatives, with PD-1 inhibitors commanding premium positioning based on progression-free survival data. Cost compression in platinum-based chemotherapy stems from API oversupply in Asian manufacturing hubs. Community oncology practices exhibit highest price sensitivity due to limited 340B eligibility and capital constraints for cold chain infrastructure.
Supply Chain Analysis
Single-source fermentation capacity for PD-1 antibody production in Puerto Rico creates vulnerability for US infusion center networks. Active pharmaceutical ingredient supply draws from Switzerland, Ireland, and Singapore for biologic drug substance, while platinum salts source from South African and Russian mining operations. Tariff exposure on Chinese-sourced diagnostic reagents complicates companion diagnostic co-approval timelines. Distribution runs through specialty pharmacy networks with temperature-controlled logistics rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform interoperability between electronic health records and next-generation sequencing portals is reconfiguring prescriber behavior around biomarker-directed therapy selection, concentrating patient flow toward integrated health systems with embedded molecular profiling capabilities.
For Market Incumbents: Compound defensive moats through backward integration into companion diagnostic development, securing co-approval sequencing control against emerging bispecific antibody competitors. Prioritize subcutaneous formulation investments to displace infusion-dependent protocols before biosimilar checkpoint inhibitors erode margin pools in Medicare reimbursement channels.
For New Entrants and Emerging Players: Post-treatment surveillance services represent underserved white space where incumbents lack dedicated remote monitoring infrastructure. Target community oncology practices in secondary metropolitan markets lacking embedded clinical trial access, deploying decentralized trial platforms as differentiated patient recruitment mechanisms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform biotechs with approved companion diagnostic franchises and established hospital system partnerships. Five-to-ten year viability favors precision medicine specialists with validated liquid biopsy platforms over single-asset developers. Watch FDA Breakthrough Therapy designation velocity as inflection signal for portfolio reallocation toward immuno-oncology combination regimens.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Parallel FDA submission timelines compress market access delays for biomarker-selected patient populations. |
| Subcutaneous Formulation Investment | Home administration capability displaces infusion center dependency and expands addressable patient geography. |
| 340B Contract Pharmacy Expansion | Captive specialty pharmacy arrangements optimize procurement economics for eligible academic medical centers. |
| Decentralized Clinical Trial Infrastructure | Remote patient monitoring platforms enable community site participation in registrational studies. |
| Biosimilar Manufacturing Scale-Up | CDMO partnerships in India and South Korea unlock cost-competitive supply for post-patent markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oncology drug development executives, hospital formulary directors, payer access specialists, and cold chain logistics coordinators. Secondary validation drew from FDA Breakthrough Therapy designation records, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and CMS Medicare outpatient prospective payment system files. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored volume estimates.
Across the analysis window, the forecasting framework modeled treatment line stratification, administration route substitution curves, regional regulatory cluster adoption patterns, and biomarker testing penetration rates. CAGRs were derived from log-linear regression of historical approval velocity and reimbursement expansion trajectories, calibrated against health technology assessment body budget-impact thresholds. Forecast inputs included PD-L1 testing volume projections and subcutaneous formulation pipeline advancement milestones.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA conditional marketing authorization frameworks; material policy shifts would require re-modeling of commercial access timelines. Practitioners should keep alternative scenarios live as Medicare reimbursement compression and biosimilar entry dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Sciatica Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Hypercoagulability Treatment Market