
 Systemic Mastocytosis Treatment Market | 2026-2036
Systemic Mastocytosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Mastocytosis Treatment Market Analytics
North American biopharmaceutical manufacturing capacity is reconfiguring around precision oncology for rare mast cell disorders. Blueprint Medicines leverages its KIT inhibitor platform to anchor clinical development in advanced systemic mastocytosis. Novartis competes through broad hematology infrastructure and established hospital formulary access. AB Science sustains European development momentum with masitinib in niche patient subsets.
Systemic mastocytosis treatment encompasses pharmacologic interventions targeting mast cell proliferation, mediator release, and organ infiltration in a clonal hematopoietic disorder driven primarily by KIT mutations. Biologicals such as avapritinib achieve deep molecular responses by selectively inhibiting mutant KIT signaling, while corticosteroids manage acute mediator symptoms through broad immunosuppression. The biologicals segment commands premium positioning due to orphan pricing and durable responses in advanced disease, whereas intravenous administration routes concentrate in hospital settings where anaphylaxis monitoring and infusion reactions require clinical supervision.
The FDA Orphan Drug program and EMA's Committee for Orphan Medicinal Products shape development economics through market exclusivity and protocol assistance, while the EU MDR intensifies post-market surveillance requirements for implantable and combination delivery devices. Health Canada's PMRA aligns with FDA breakthrough pathways to accelerate access for life-threatening rare disease indications. Stakeholders must monitor biomarker-driven trial designs and companion diagnostic partnerships that determine reimbursement and prescribing segmentation.
Market Dynamics
KIT D816V mutation testing penetration is concentrating demand for precision-targeted therapies among advanced systemic mastocytosis patients, compressing the addressable population for conventional symptom management while elevating molecular response endpoints as the standard of care.
Growth Catalysts
- FDA Orphan Drug Designation:The program grants seven-year market exclusivity and tax credits for clinical trials, incentivizing biopharmaceutical developers to pursue novel kinase inhibitors for this rare indication despite limited patient pools.
- Specialty clinic expansion:Oncology infusion centers across the United States are adding dedicated mast cell disorder units with anaphylaxis monitoring capabilities, expanding access site capacity for biological administration.
- Companion diagnostic integration:KIT mutation profiling is becoming standard practice in academic medical centers, creating a defined prescriber pathway for targeted therapy selection and reimbursement alignment.
Market Restraints
- Biological manufacturing concentration:Active pharmaceutical ingredient production for kinase inhibitors concentrates among a limited set of contract manufacturing organizations in Switzerland and Germany, creating single-source vulnerability.
- Orphan pricing resistance:Payers in Germany and France are applying stricter health technology assessment criteria to ultra-rare disease therapies, extending reimbursement negotiation timelines.
- Corticosteroid substitution:Low-cost generic immunosuppressants remain first-line for indolent disease, limiting biological penetration in non-advanced patient segments.
Strategic Opportunities
- Pediatric indication expansion:The FDA's Rare Pediatric Disease Priority Review Voucher program creates additional value capture for developers pursuing mastocytosis treatments in adolescent populations.
- Home administration models:Subcutaneous formulation development would shift delivery from hospital infusion suites to specialty pharmacy distribution, capturing margin from site-of-care differentials.
- Smoldering disease interception:Earlier therapeutic intervention in patients with bone marrow involvement but stable organ function represents an unlabeled clinical opportunity with biomarker-defined enrollment.
Industry Challenges
- Mast cell biology expertise scarcity:Clinical investigators with deep experience in mast cell neoplasm trial design are concentrated at fewer than fifteen academic centers globally, constraining site activation velocity.
- Long-term safety surveillance infrastructure:The EU MDR mandates extended follow-up for combination delivery devices, requiring pharmacovigilance systems that many emerging developers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Mastocytosis Treatment Market |
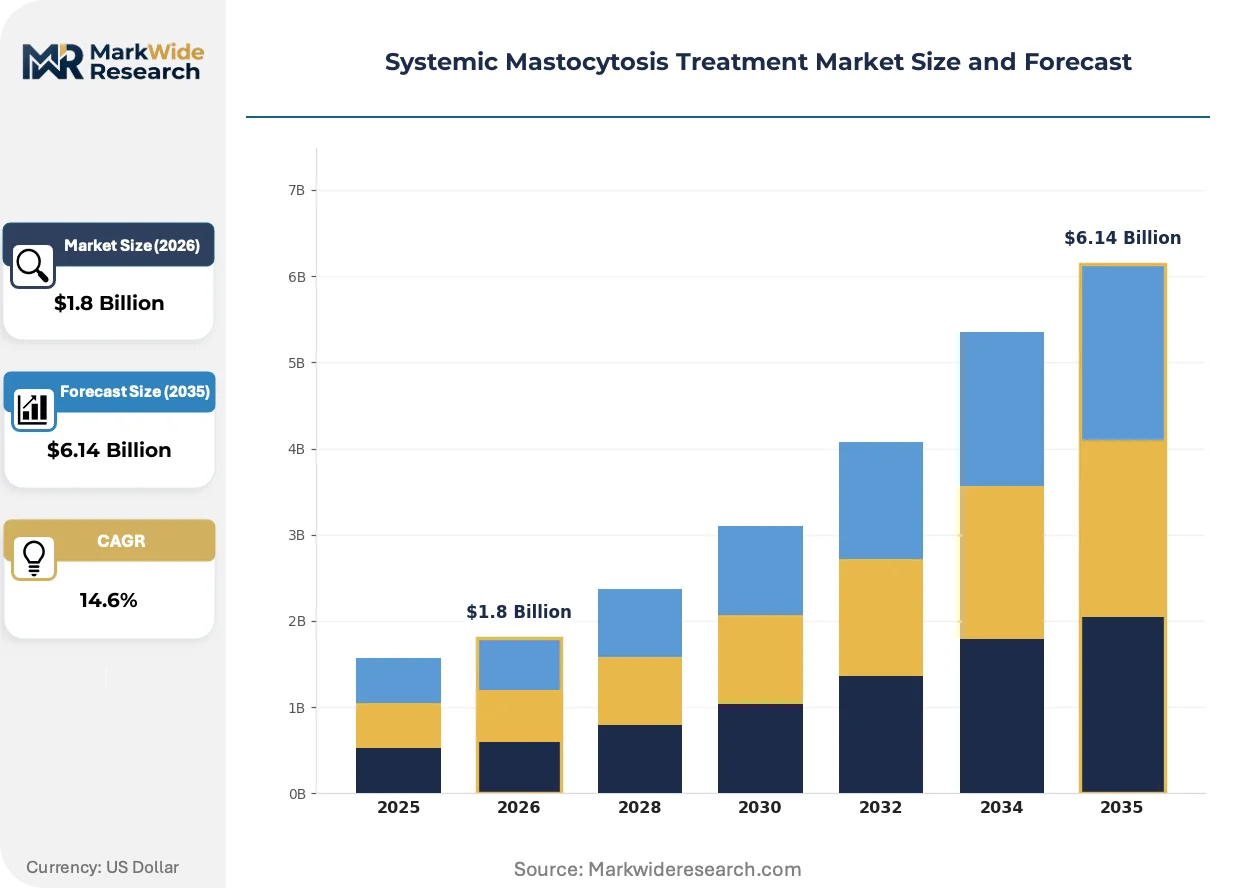
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Biologicals, Chemotherapy End User: Hospitals, Ambulatory Surgical Centers, Homecare, Specialty Clinics Administration Route: Oral, Injectable, Topical, Intravenous Distribution Channel: Pharmacies, Online Retail, Hospital Pharmacy, Specialty Distributors |
| Companies Covered | Sanofi S.A., AB Science, Novartis AG, Teva Pharmaceutical Industries Ltd, Bausch Health Companies Inc, Blueprint Medicines, Deciphera Pharmaceuticals, Arog Pharmaceuticals, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Mastocytosis Treatment Market Evolving Landscape
Next-generation KIT inhibitors are digitizing clinical trial endpoints through real-time molecular monitoring, while regulatory frameworks and care delivery models compress development timelines and shift administration settings.
Digital biomarker platforms are digitizing disease activity tracking in systemic mastocytosis by integrating patient-reported symptom scores with continuous wearable data streams. Academic medical centers in the United States and Germany are piloting these systems to reduce reliance on intermittent bone marrow biopsies. The technology is digitizing response assessment protocols, enabling adaptive trial designs that accelerate dose optimization and label expansion decisions.
The EU MDR intensifies post-market surveillance requirements for implantable and combination delivery devices used in oncology settings, mandating extended follow-up periods and enhanced adverse event reporting. Manufacturers must reconfigure quality management systems to accommodate periodic safety update reports and unique device identification tracking. Advanced systemic mastocytosis therapies with subcutaneous delivery mechanisms face the steepest compliance burden, driving partnerships with notified bodies in Germany and the Netherlands.
Site-of-care economics are compressing hospital-based infusion revenues as payers in the United States implement medical policy edits favoring outpatient administration. Specialty pharmacy networks are capturing biological dispensing volume through white-bag and buy-and-bill arrangements that separate drug acquisition from administration reimbursement. This shift is most pronounced in Medicare Advantage plans and integrated delivery networks in California and Texas, where risk-bearing entities optimize total cost of care through preferred pharmacy designations.
Systemic Mastocytosis Treatment Market Segmentation
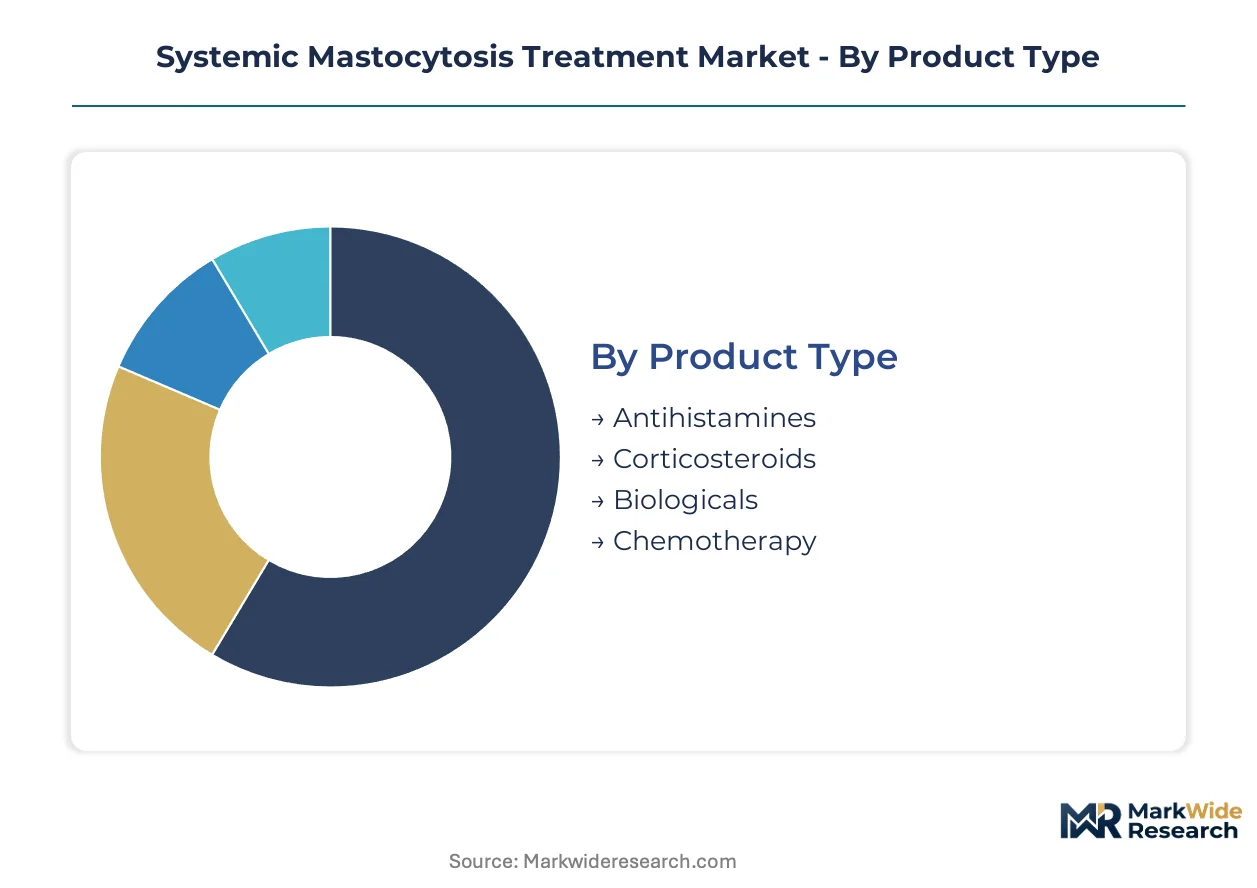
Segmentation in systemic mastocytosis treatment reveals how therapy selection tracks disease severity, care setting capabilities, and reimbursement pathways. Each dimension shapes prescribing decisions, site-of-care economics, and manufacturer channel strategy.
Product Type:
Cost tier differentiation separates symptom management from disease-modifying interventions across the treatment continuum.
- Biologicals:Selective KIT inhibitors target the D816V mutation with precision mechanism. Academic medical centers in the United States concentrate demand for these agents, driven by companion diagnostic integration and orphan drug pricing frameworks.
- Corticosteroids:Broad immunosuppressants modulate acute mediator release through non-specific pathways. First-line prescribing in community oncology settings sustains volume, constrained by long-term toxicity profiles and biological substitution in advanced disease.
- Antihistamines:H1 and H2 receptor antagonists manage cutaneous and gastrointestinal symptoms.
- Chemotherapy:Cytotoxic agents address aggressive mast cell leukemia variants.
Biologicals command the established base. The steepest expansion runs through targeted kinase inhibitors with molecular response endpoints.
End User:
Application setting determines monitoring intensity, administration infrastructure, and prescriber specialization depth.
- Specialty Clinics:Dedicated mast cell disorder units combine infusion capacity with anaphylaxis preparedness. The United States leads site expansion, propelled by Medicare reimbursement for hospital-based outpatient administration and risk-bearing entity preference for controlled settings.
- Hospitals:Comprehensive oncology departments manage advanced systemic mastocytosis with organ involvement. Tertiary centers in Germany and the Netherlands anchor European trial enrollment, supported by EMA protocol assistance for orphan indications.
- Ambulatory Surgical Centers:Limited procedure volume restricts penetration to diagnostic biopsies.
- Homecare:Subcutaneous formulation gaps currently constrain adoption.
Hospitals retain the complexity burden. Specialty clinics are gaining share fastest through focused infrastructure investment.
Administration Route:
Volume concentration reflects bioavailability requirements, patient acuity, and site-of-care economics.
- Intravenous:Infusion delivery achieves rapid systemic exposure for acute exacerbations and biological loading doses. Hospital outpatient departments in Texas and California capture volume through buy-and-bill arrangements, shaped by Medicare Advantage medical policy edits.
- Oral:Daily tablet regimens enable chronic maintenance with patient convenience. Community hematology practices in the United States drive prescriptions, contingent on prior authorization requirements from commercial payers.
- Injectable:Subcutaneous options remain under development for site-of-care shift.
- Topical:Localized symptom management addresses limited cutaneous manifestations.
Oral administration commands the established base. Intravenous delivery sustains premium positioning through biological necessity.
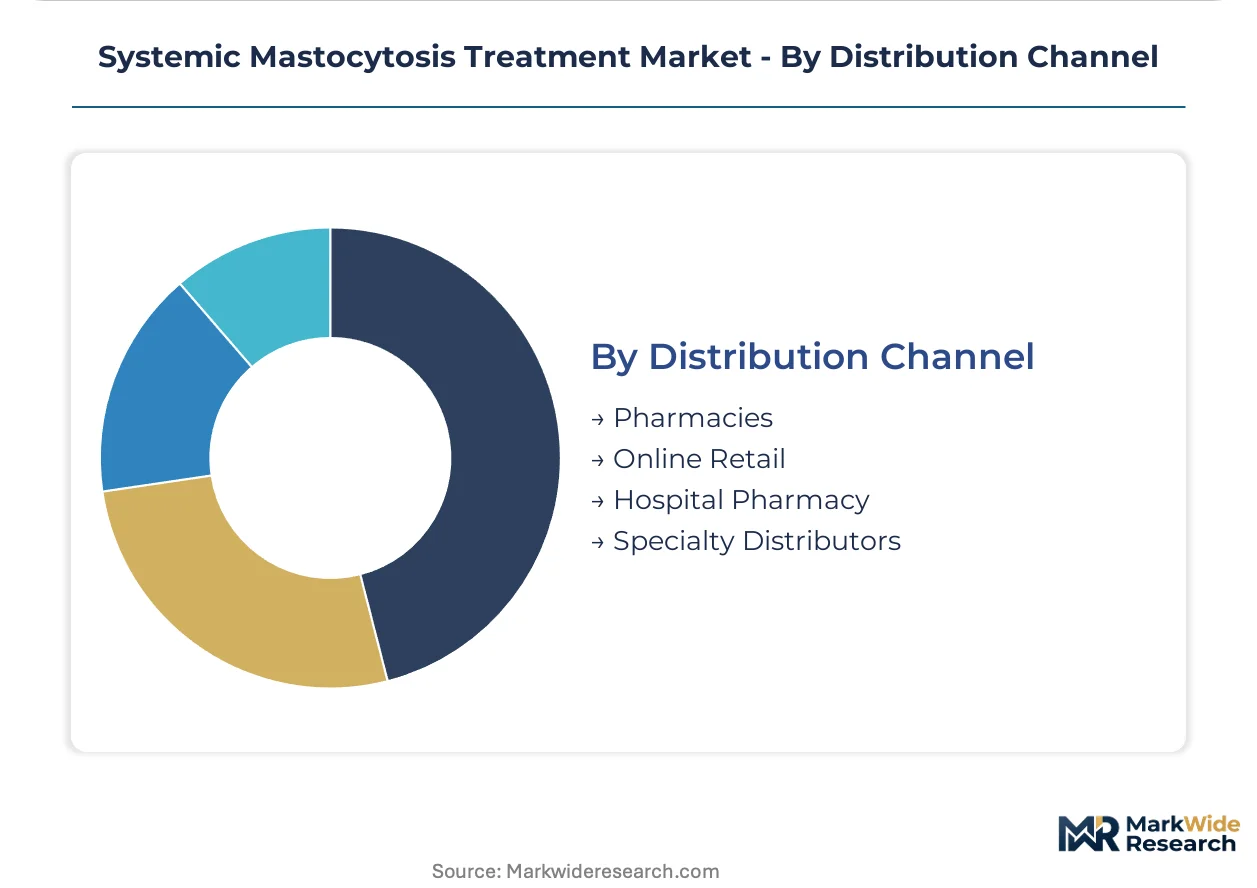
Distribution Channel:
Customer type segmentation maps how product flow separates dispensing from clinical supervision.
- Specialty Distributors:Limited distribution networks handle cold-chain biologicals with patient registry requirements. White-bag arrangements through oncology-focused distributors dominate United States commercial dispensing, separating drug acquisition from infusion reimbursement.
- Hospital Pharmacy:Captive dispensing integrates with electronic health record protocols and formulary controls. Integrated delivery networks in California optimize total cost of care through preferred pharmacy designations.
- Pharmacies:Retail channels manage oral generic corticosteroids and antihistamines.
- Online Retail:Limited to over-the-counter symptom management products.
Hospital pharmacy commands the established base. Specialty distributors are expanding fastest through biological volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient production for kinase inhibitors concentrates among contract manufacturing organizations in Switzerland and Germany, creating geographic dependencies that shape regional market access patterns. The United States anchors demand concentration through KIT D816V testing penetration and orphan drug pricing frameworks. Germany, France, and the United Kingdom sustain European development momentum through EMA protocol assistance and health technology assessment pathways.
United States
Academic medical centers in Boston, New York, and Houston drive KIT mutation profiling adoption, creating defined prescriber pathways for targeted therapy selection. The FDA's Orphan Drug Designation program grants seven-year market exclusivity and tax credits for clinical trials. Specialty oncology infusion centers in Texas and California expand capacity through Medicare Advantage medical policy edits favoring outpatient administration.
Germany
Tertiary centers in Berlin, Munich, and Heidelberg anchor European trial enrollment for advanced systemic mastocytosis therapies. The Federal Joint Committee applies stricter health technology assessment criteria to ultra-rare disease therapies, extending reimbursement negotiation timelines. Bavaria-based contract manufacturers supply active pharmaceutical ingredients for kinase inhibitors, concentrating production risk in southern industrial clusters.
Switzerland
Basel and Zurich host concentrated biological manufacturing infrastructure for precision oncology compounds. Swissmedic aligns regulatory pathways with EMA orphan designation frameworks while maintaining distinct national pricing negotiations. The Lake Geneva region sustains clinical research coordination across French and German-speaking trial sites.
France
Paris and Lyon academic hospitals maintain deep expertise in mast cell neoplasm trial design, though investigator scarcity constrains site activation velocity. ANSM oversees post-market surveillance requirements for combination delivery devices under EU MDR mandates. The Haute Autorité de Santé evaluates ultra-rare therapies through distinct economic modeling frameworks that compress pricing flexibility.
United Kingdom
London, Manchester, and Edinburgh hematology centers participate in adaptive trial designs enabled by real-time molecular monitoring platforms. The MHRA operates a recognized reliance procedure with FDA breakthrough pathways to accelerate access for life-threatening rare disease indications. NHS England's specialized commissioning framework concentrates biological prescribing in designated supra-regional centers.
Systemic Mastocytosis Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with targeted mechanism expertise. The competitive structure organizes around three archetypes: large-cap pharmaceutical conglomerates with broad hematology infrastructure, mid-cap biotech developers with kinase inhibitor platforms, and emerging specialists pursuing niche indication expansion. Consolidation pressure operates through strategic partnerships for companion diagnostic integration and geographic licensing arrangements for market access.
Among large-cap developers, Novartis AG and Pfizer Inc occupy positions anchored by established hospital formulary access and global commercial infrastructure. Blueprint Medicines and Deciphera Pharmaceuticals exemplify the platform-specialist archetype with concentrated investment in mutant KIT signaling inhibition. AB Science sustains European development momentum through distinct regulatory pathways. These named entities represent competitive positioning patterns rather than exhaustive market coverage, with each archetype pursuing differentiated routes to reimbursement alignment and prescriber segmentation.
| Leading Market Players |
|---|
| Sanofi S.A. |
| AB Science |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| Bausch Health Companies Inc |
| Blueprint Medicines |
| Deciphera Pharmaceuticals |
| Arog Pharmaceuticals |
| Pfizer Inc |
| Others |
Value Network & Pricing Analysis
Basel and Zurich anchor active pharmaceutical ingredient production for kinase inhibitors, concentrating manufacturing capacity that translates into premium pricing power for biological developers serving orphan indications. FDA Orphan Drug Designation frameworks reinforce this dynamic by granting seven-year market exclusivity that insulates manufacturers from immediate generic competition.
Pricing Analysis
FDA Orphan Drug Designation dictates the pricing tier structure for systemic mastocytosis therapies, creating a three-tier pricing structure across premium biologicals, standard corticosteroids, and economy symptom management. Price differentiation rests on molecular response capability and companion diagnostic integration, with academic medical centers showing lowest price sensitivity due to reimbursement alignment through Medicare outpatient prospective payment systems. Cost compression in corticosteroid tiers is intensifying because generic substitution pressures first-line indolent disease management.
Supply Chain Analysis
Extended payment terms from Swiss and German contract manufacturing organizations are becoming standard for emerging biotech developers lacking captive production capacity. Geographic supply concentration centers on Switzerland, Germany, and the United States for active pharmaceutical ingredients, with dependencies on specialized fermentation capacity and chromatography resin inputs. Single-source vulnerability runs through Bavaria-based API facilities, while distribution runs through specialty distributors with cold-chain capabilities and patient registry integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision oncology disruption is accelerating as real-time molecular monitoring platforms compress clinical trial timelines and elevate biomarker-defined endpoints as reimbursement prerequisites.
For Market Incumbents: Harden formulary position through companion diagnostic partnerships that lock in prescriber pathways before next-generation KIT inhibitors reach label expansion. Deepen backward integration into Swiss API manufacturing to reduce single-source exposure from Bavaria-based contract manufacturers. Channel control through specialty pharmacy networks represents the critical defensive lever against site-of-care shift.
For New Entrants and Emerging Players: Build out pediatric indication infrastructure to capture Rare Pediatric Disease Priority Review Voucher value, as adolescent systemic mastocytosis remains clinically underaddressed. Smoldering disease interception represents the most penetrable white-space segment, with biomarker-defined enrollment enabling adaptive trial designs. Go-to-market positioning through academic medical center partnerships in Texas and California accelerates KIT mutation profiling integration.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because kinase inhibitor expertise concentrates among fewer than fifteen global academic investigators, creating scarcity value for developers with established clinical networks. Acquisition targets should display companion diagnostic integration capabilities and EMA protocol assistance relationships. Monitor FDA breakthrough therapy designation velocity as the signal indicating competitive positioning inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Locks prescriber pathways and aligns reimbursement with molecular response endpoints. |
| Pediatric Indication Expansion | Captures Rare Pediatric Disease Priority Review Voucher value from FDA designation programs. |
| Subcutaneous Formulation Development | Shifts delivery from hospital infusion to specialty pharmacy, capturing site-of-care margin differentials. |
| EMA Protocol Assistance Engagement | Accelerates European market access through orphan designation frameworks and scientific advice. |
| Real-Time Molecular Monitoring Platforms | Enables adaptive trial designs that compress dose optimization and label expansion timelines. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down epidemiological estimates were triangulated to anchor market sizing across the treatment continuum.
Demand-supply balance dynamics shaped the analytical framework, with segmentation modeled across treatment line, administration route, patient population severity, and regional regulatory clusters. CAGRs were derived from epidemiological progression rates, pricing trajectory assumptions, and penetration curve analysis for molecularly targeted therapies. Forecast inputs incorporated KIT D816V testing penetration curves and orphan drug pricing elasticity parameters.
Practitioners should monitor biomarker adoption velocity, payer policy edits on site-of-care administration, and EU MDR compliance timelines for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Tennis Elbow Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Acute Migraine Treatment Market