
 Influenza Treatment Market | 2026-2036
Influenza Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Influenza Treatment Market Analytics
Active pharmaceutical ingredient sourcing is rebalancing from single-source reliance toward qualified secondary suppliers across the influenza treatment supply chain. Roche Holding AG leverages its vertically integrated manufacturing network to sustain oseltamivir production at scale. GlaxoSmithKline plc anchors its position through differentiated intranasal delivery platforms. Sanofi competes on seasonal vaccine strain-matching speed and manufacturing yield.
Influenza treatment encompasses pharmacological interventions designed to inhibit viral replication, modulate immune response, or alleviate symptomatic burden in infected patients; neuraminidase inhibitors such as oseltamivir phosphate function by blocking viral release from host cells, while newer polymerase inhibitors target cap-dependent endonuclease activity with shorter dosing regimens. Antivirals occupy the largest margin pool due to pandemic stockpiling contracts and retail pharmacy distribution scale. Vaccines generate the highest absolute volume through government immunization programs. Combination therapies represent the fastest-expanding category as clinicians seek to reduce resistance emergence and shorten symptom duration.
The FDA accelerates influenza antiviral reviews through emergency use authorization frameworks, while the EMA's rolling review procedures compress market access timelines for pandemic-ready therapies. Japan's PMDA maintains stringent stability requirements for intranasal formulations, shaping regional product development priorities. Stakeholders must monitor regulatory divergence between accelerated approval pathways and post-market confirmatory trial obligations.
Market Dynamics
Government stockpiling contracts for pandemic preparedness are compressing development timelines and reshaping competitive positioning across antiviral manufacturing networks.
Growth Catalysts
- FDA Emergency Use Authorization:Accelerated review pathways compress time-to-market for novel polymerase inhibitors, enabling faster pandemic response capacity.
- Hospital formulary expansion:Acute care facilities in the United States and Japan are broadening antiviral coverage protocols to reduce ICU admission rates.
- Neuraminidase inhibitor resistance monitoring:Surveillance networks in Germany are driving demand for next-generation cap-dependent endonuclease inhibitors with shorter dosing regimens.
Market Restraints
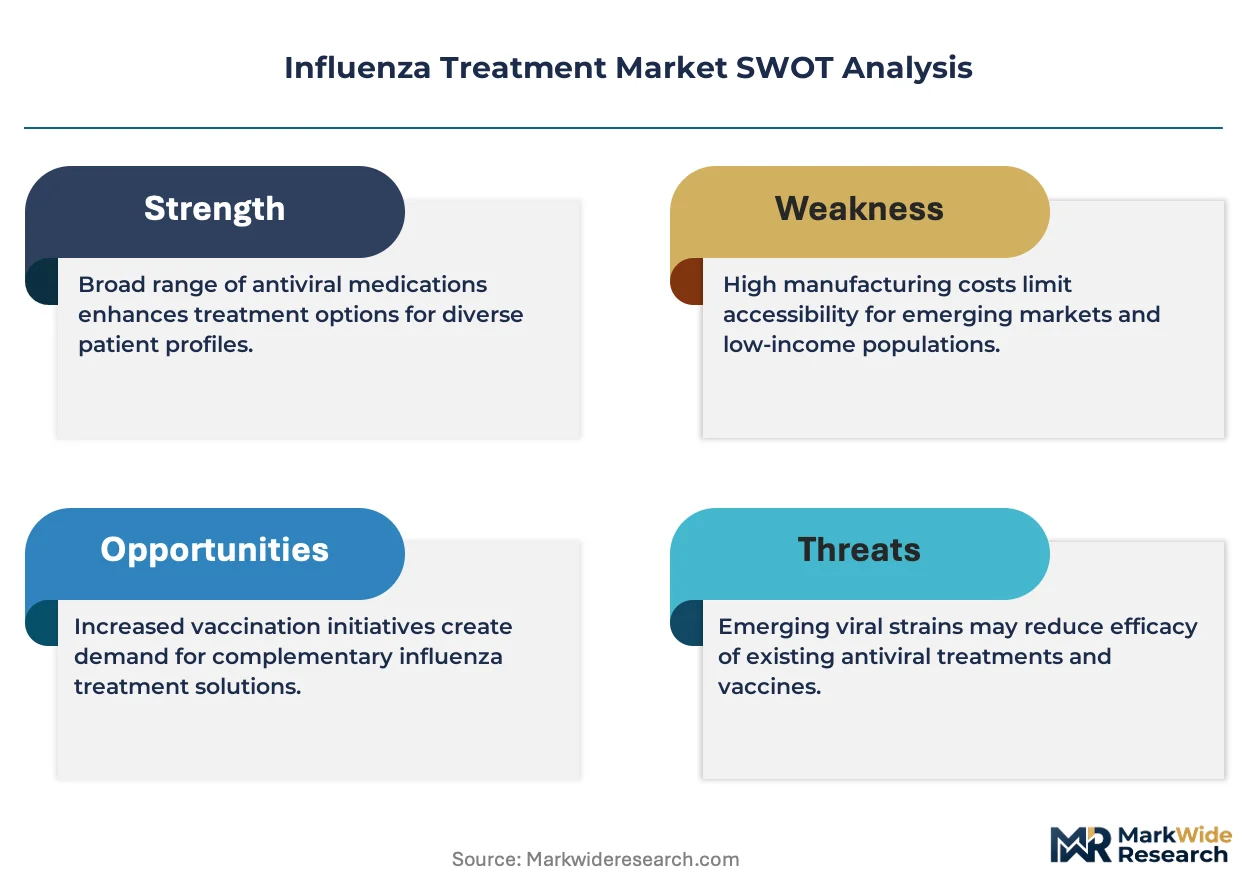
- API concentration risk:Active pharmaceutical ingredient production for oseltamivir concentrates in a limited number of qualified suppliers, creating vulnerability to single-source disruption.
- PMDA stability requirements:Japan's stringent shelf-life mandates for intranasal formulations extend validation timelines and elevate manufacturing costs.
- Generic substitution pressure:Patent-expired neuraminidase inhibitors face commoditization in retail pharmacy channels, compressing margin pools for originator products.
Strategic Opportunities
- Combination therapy protocols:Clinicians in the United States are adopting dual-mechanism regimens pairing polymerase and neuraminidase inhibitors to suppress resistance emergence.
- Rolling review procedures:The EMA's compressed assessment timelines create first-mover advantages for pandemic-ready therapies in European markets.
- Point-of-care diagnostics integration:Rapid molecular testing platforms in Germany are enabling same-day antiviral initiation, expanding addressable patient populations.
Industry Challenges
- Confirmatory trial obligations:Accelerated approval pathways require post-market efficacy studies that strain clinical operations and regulatory affairs capacity.
- Strain-matching velocity:Vaccine manufacturers must compress antigen selection-to-distribution cycles to align with shifting seasonal influenza variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Influenza Treatment Market |
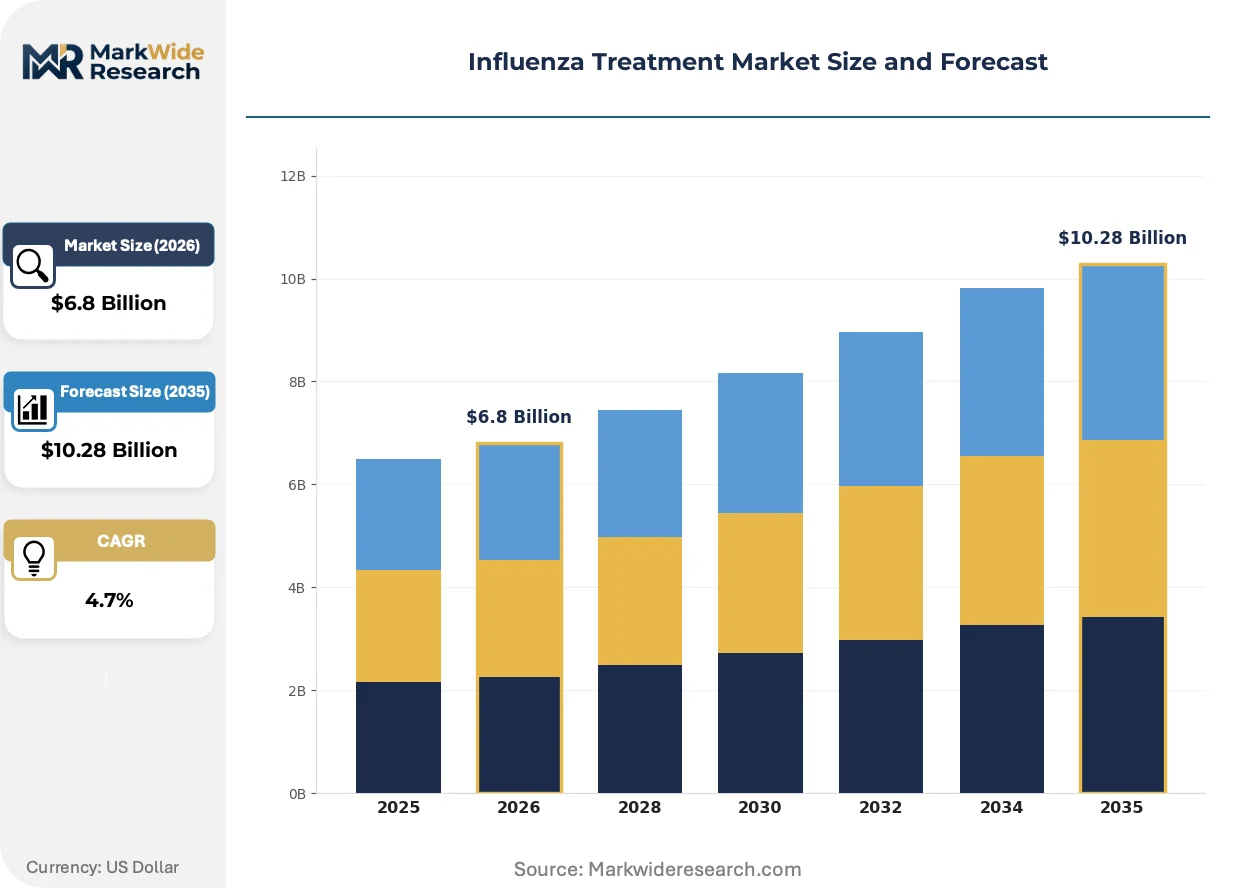
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Vaccines, Symptomatic Relief, Combination Therapies Administration Route: Oral, Intranasal, Intravenous, Subcutaneous End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Direct Sales, Retail Pharmacy, E-commerce, Wholesale |
| Companies Covered | Roche Holding AG, GlaxoSmithKline plc, AstraZeneca plc, Sanofi, Novartis AG, BioCryst Pharmaceuticals, Inc., Pfizer Inc., Daiichi Sankyo Company, Limited, Seqirus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Influenza Treatment Market Evolving Landscape
Antiviral development is pivoting toward mechanism diversification and delivery innovation as resistance patterns and patient convenience requirements reshape product specifications.
Cap-dependent endonuclease inhibitors are integrating into standard-of-care protocols through once-daily oral regimens that reduce treatment duration from five days to one or two. Hospital systems in the United States are adopting these compounds for high-risk patient populations, compressing average length-of-stay metrics and freeing bed capacity during seasonal peaks.
The FDA's emergency use authorization framework is compressing development-to-deployment cycles for pandemic influenza therapies, creating permanent infrastructure for rapid response. Pharmaceutical developers are restructuring clinical trial designs to accommodate rolling data submission, while manufacturing networks maintain warm-base production capacity for surge activation.
Retail pharmacy channels are displacing hospital-based antiviral dispensing for low-risk ambulatory patients through telehealth-integrated prescription workflows. This pattern is most visible in the United States, where major pharmacy chains have deployed rapid diagnostic co-locations that enable same-day treatment initiation without primary care visits.
Influenza Treatment Market Segmentation
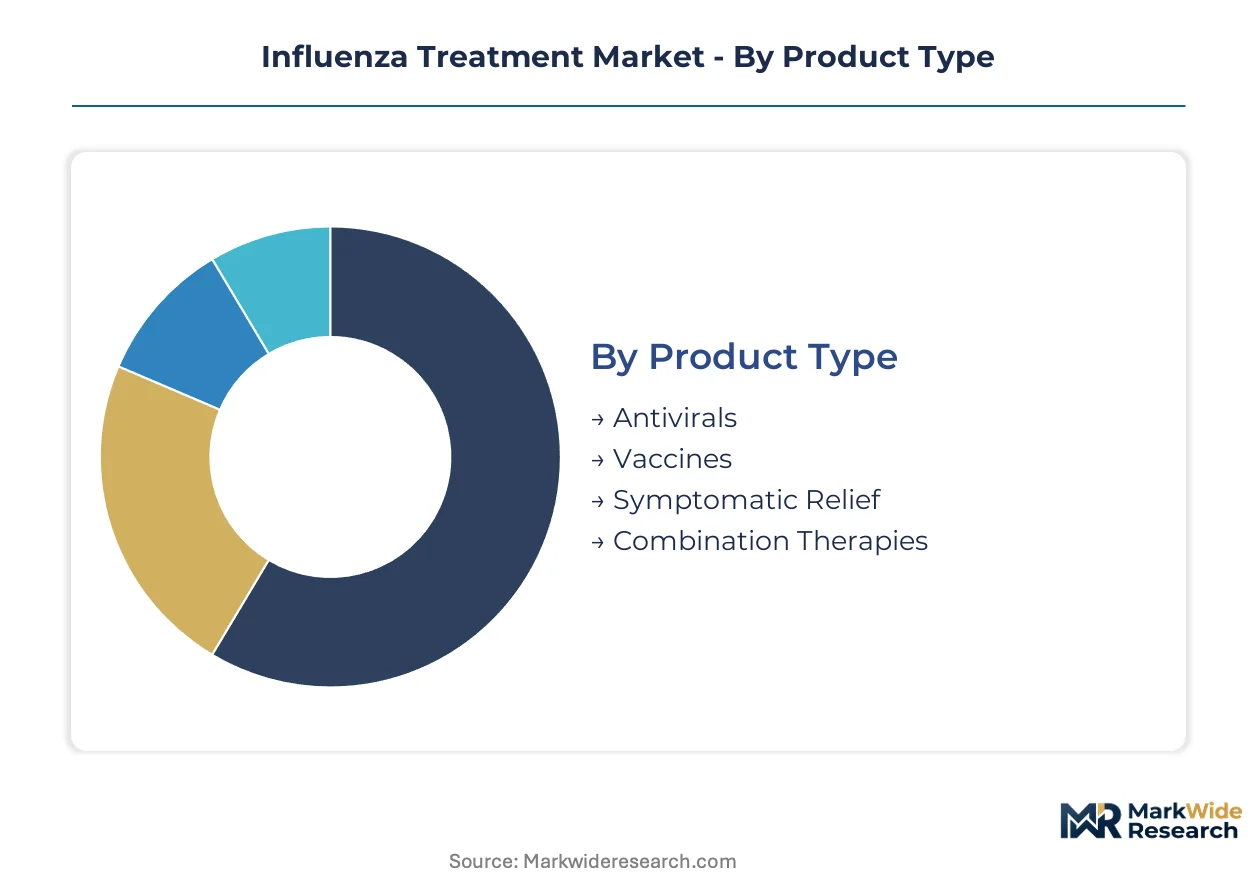
Segmentation in the influenza treatment market reveals how supply chain configuration, regulatory pathways, and patient access models reshape procurement patterns across therapeutic categories. Manufacturers align production investments with the divergent margin structures and approval timelines that distinguish pandemic stockpiles from seasonal retail channels.
Product Type:
Active pharmaceutical ingredient sourcing concentrates differently across each therapeutic modality, with neuraminidase inhibitors and polymerase inhibitors drawing from overlapping but distinct qualified supplier networks.
- Antivirals:Neuraminidase inhibitors and polymerase inhibitors constitute the core pharmacological arsenal, with cap-dependent endonuclease inhibitors enabling shortened one-day regimens. Hospital procurement in the United States and Japan sustains volume through pandemic stockpiling contracts and ICU admission reduction protocols.
- Vaccines:Seasonal strain-matched immunizations generate absolute volume leadership through government immunization programs, though manufacturing yield and antigen selection velocity determine competitive position. Germany's surveillance networks drive demand precision for northern hemisphere formulation.
- Symptomatic Relief:Analgesics and decongestants address fever and respiratory discomfort without viral suppression, distributed primarily through retail pharmacy channels for ambulatory patient self-management.
- Combination Therapies:Dual-mechanism regimens pair polymerase and neuraminidase inhibitors to suppress resistance emergence, with clinicians in the United States adopting these protocols fastest for high-risk populations.
Antivirals absorb the bulk of installed capacity; combination therapies are expanding most quickly.
Administration Route:
Cost tier differentiation separates hospital-administered parenteral formulations from retail-dispensed oral and intranasal alternatives, with manufacturing complexity and cold-chain requirements driving margin stratification.
- Oral:Tablets and capsules dominate ambulatory prescribing through pharmacy dispensing, with once-daily polymerase inhibitors compressing treatment duration and improving adherence profiles.
- Intranasal:Spray formulations deliver rapid mucosal absorption for pediatric and needle-averse populations, though Japan's PMDA maintains stringent stability requirements that extend validation timelines and elevate manufacturing costs.
- Intravenous:Hospital-restricted infusion therapy serves severe or immunocompromised patients unable to tolerate oral absorption, requiring acute care facility infrastructure and specialized nursing protocols.
- Subcutaneous:Depot formulations and alternative injection routes occupy niche positioning for specific patient populations with compromised gastrointestinal function or rapid oral clearance.
Oral formulations command the greatest production volume; intranasal delivery is climbing the fastest as pediatric acceptance and convenience requirements reshape prescribing patterns.
End User:
Application setting determines reimbursement pathway, formulary placement, and the regulatory frameworks governing antiviral dispensing authority across acute and ambulatory environments.
- Hospitals:Acute care facilities manage severe influenza through ICU admission protocols and antiviral stockpiles, with formulary expansion in the United States and Japan reducing length-of-stay metrics during seasonal peaks.
- Clinics:Outpatient medical offices bridge emergency and primary care, deploying rapid molecular diagnostics to enable same-day antiviral initiation without hospital admission.
- Home Care:Post-acute and hospice settings administer prophylaxis and symptomatic management for immunocompromised patients, relying on caregiver training and remote physician oversight.
- Pharmacies:Retail dispensing channels displace hospital-based antiviral distribution for low-risk ambulatory patients through telehealth-integrated prescription workflows and rapid diagnostic co-locations.
Hospitals absorb the bulk of installed capacity; pharmacies are gaining share fastest as point-of-care diagnostic integration expands addressable patient populations.
Distribution Channel:
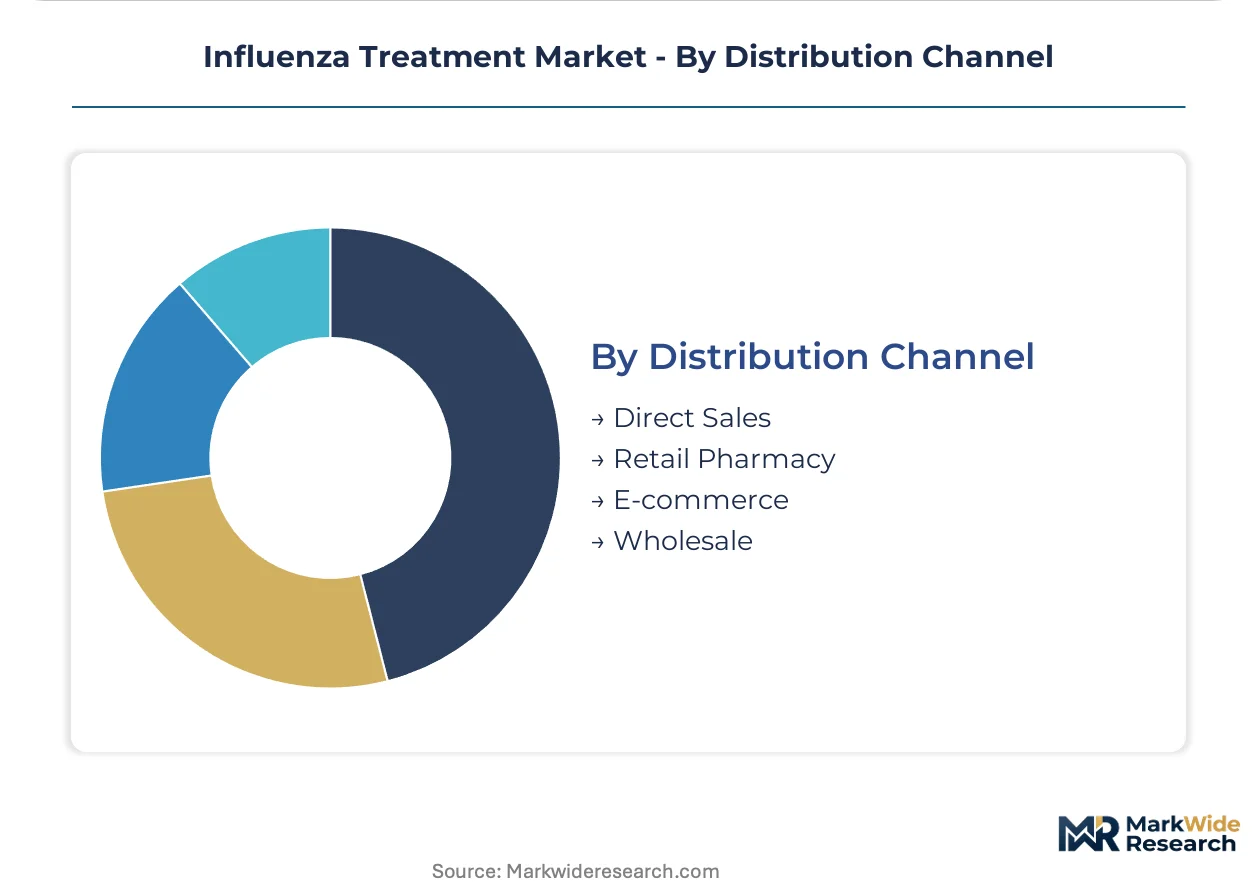
Customer type and procurement scale reshape channel economics, with government stockpiling contracts bypassing traditional wholesale networks and direct manufacturer negotiation.
- Direct Sales:Manufacturer-to-institution contracting serves hospital systems and government stockpiling programs, compressing intermediaries and enabling pandemic surge capacity agreements.
- Retail Pharmacy:Chain and independent pharmacies dispense ambulatory prescriptions through integrated diagnostic and telehealth platforms, with major United States chains deploying rapid testing co-locations.
- E-commerce:Online platforms facilitate over-the-counter symptomatic relief and prescription fulfillment, though antiviral dispensing remains restricted by prescribing authority limitations.
- Wholesale:Distributor networks maintain inventory buffers and cold-chain logistics for seasonal vaccine distribution and retail pharmacy replenishment across fragmented geographic footprints.
Direct sales absorb the bulk of installed capacity; e-commerce is expanding most quickly as digital health integration and patient convenience preferences reshape access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing for neuraminidase inhibitors clusters in Basel, Switzerland, and in Hyderabad, India, where qualified supplier networks feed formulation facilities across three continents.
United States
Hospital formulary expansion and pandemic stockpiling contracts drive procurement volumes for polymerase inhibitors. The FDA's emergency use authorization framework compresses review timelines for novel antiviral submissions. Manufacturing concentration in Research Triangle Park, North Carolina, supports scaled production of cap-dependent endonuclease inhibitors.
Germany
Surveillance networks for neuraminidase inhibitor resistance generate demand for next-generation antivirals with shorter dosing regimens. The EMA's rolling review procedures enable accelerated market access for pandemic-ready therapies. The Rhine-Main biopharma corridor hosts formulation facilities serving European government stockpiling programs.
Japan
ICU admission reduction protocols and seasonal immunization programs sustain high per-capita antiviral consumption. The PMDA maintains stringent stability requirements for intranasal formulations that extend validation timelines. Osaka-based manufacturing clusters specialize in pediatric-appropriate delivery systems.
India
Generic production of patent-expired neuraminidase inhibitors supplies retail pharmacy channels across emerging markets. The CDSCO's abbreviated approval pathways for essential medicines accelerate domestic market entry. Hyderabad's API manufacturing belt provides qualified secondary sourcing for global formulation networks.
United Kingdom
Point-of-care diagnostic integration in community pharmacies expands addressable patient populations for ambulatory antiviral prescribing. The MHRA's reliance on EMA centralized procedures streamlines approval for pandemic stockpile candidates. The Cambridge-London life sciences corridor hosts clinical trial infrastructure for combination therapy protocols.
Influenza Treatment Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers establish warm-base production networks for pandemic surge activation. The vendor base stratifies across three tiers: vertically integrated multinationals with captive API supply, mid-scale specialists in delivery innovation, and regional generic fabricators. Strategic archetypes include polymerase inhibitor developers seeking shortened dosing regimens, intranasal formulation specialists navigating Japan's stability requirements, and combination therapy architects targeting resistance suppression. M&A activity and strategic partnerships concentrate on diagnostic-antiviral integration and secondary API supplier qualification.
Among Swiss-dominant multinationals, Roche Holding AG occupies a position exemplifying vertically integrated manufacturing architecture, while GlaxoSmithKline plc represents the intranasal delivery specialization archetype. Sanofi sits within the seasonal vaccine strain-matching tier, where manufacturing yield velocity determines competitive position relative to government immunization contract awards.
| Leading Market Players |
|---|
| Roche Holding AG |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Sanofi |
| Novartis AG |
| BioCryst Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Daiichi Sankyo Company, Limited |
| Seqirus |
| Others |
Value Network & Pricing Analysis
Government stockpiling programs for pandemic influenza preparedness concentrate procurement authority among national health agencies, enabling contract-based long-term offtake agreements that compress spot-market pricing influence. This buyer concentration privileges manufacturers with warm-base production capacity and validated surge protocols, while retail pharmacy channels for seasonal antivirals operate on more fragmented, price-sensitive terms.
Pricing Analysis
Pandemic stockpile contracts bundle cold-chain logistics, stability validation, and surge activation guarantees into unit pricing, whereas retail pharmacy channels unbundle these services. Three-tier pricing structure across originator antivirals, authorized generics, and commodity substitutes separates hospital formulary placement from retail substitution. Cost compression in patent-expired neuraminidase inhibitors intensifies because Indian generic fabricators flood emerging-market channels. Government procurement officers show lowest price sensitivity; retail pharmacy benefit managers demonstrate highest.
Supply Chain Analysis
Dual-sourcing mandates from the FDA and EMA require qualified secondary suppliers for oseltamivir API, rebalancing procurement from Basel-centered networks toward Hyderabad manufacturing clusters. Active pharmaceutical ingredient production draws from Switzerland, India, and China, with formulation finishing concentrated in North Carolina, the Rhine-Main corridor, and Osaka. Fermentation-derived shikimic acid and synthetic route intermediates constitute critical input dependencies. Single-source vulnerability persists for cap-dependent endonuclease inhibitor precursors. Distribution runs through direct manufacturer-to-institution contracting for stockpiles, with wholesale networks handling seasonal retail replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The influenza treatment market sits in a mechanism-transition phase as polymerase inhibitors displace neuraminidase inhibitors from standard-of-care protocols, compressing development timelines and reshaping manufacturing investment priorities.
For Market Incumbents: Anticipate resistance surveillance networks in Germany and Japan accelerating demand for combination therapy protocols that pair legacy and novel mechanisms. Secure captive supply of API through backward integration into Hyderabad qualified supplier networks. Invest in once-daily formulation R&D to defend formulary position against shorter-regimen competitors.
For New Entrants and Emerging Players: The FDA's emergency use authorization framework in the United States opens a window for developers of rapid diagnostic-antiviral integration platforms. Target pharmacy-based point-of-care dispensing in the United Kingdom and United States, where telehealth-integrated workflows expand addressable populations. Pursue go-to-market partnerships with major retail chains deploying rapid testing co-locations.
For Investors and Strategic Acquirers: The window for entry favors intranasal delivery specialists with validated stability data for Japan's PMDA requirements. Long-term viability hinges on pandemic surge capacity infrastructure rather than seasonal volume alone. Watch for EMA rolling review designations as inflection indicators for first-mover positioning in European stockpiling contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA emergency use authorization compresses time-to-market for novel polymerase inhibitors. |
| Manufacturing Scale-Up | Warm-base production capacity in Research Triangle Park enables pandemic surge activation. |
| Backward Integration | Captive API supply from Hyderabad qualified suppliers mitigates single-source disruption risk. |
| Combination Therapy Development | Dual-mechanism regimens pairing polymerase and neuraminidase inhibitors suppress resistance emergence. |
| Point-of-Care Diagnostic Integration | Rapid molecular testing co-locations in United States pharmacy chains expand ambulatory prescribing. |
Research Methodology
FDA filings, EMA rolling review submissions, and ClinicalTrials.gov protocol registrations formed the secondary backbone for this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at United States and European institutions validated demand assumptions and pricing dynamics. Bottom-up patient-volume modeling and top-down government stockpiling contract aggregation provided cross-check triangulation.
Historical trendline analysis of antiviral dispensing patterns, vaccine dose distribution, and pandemic stockpile replenishment cycles informed the projection framework. Segmentation dimensions included product type, administration route, end-user setting, and distribution channel, with regional regulatory cluster as an additional influenza-specific dimension. CAGRs were derived from fitted growth curves adjusted for patent expiry cliffs and accelerated approval pathway impacts. Forecast inputs incorporated strain-matching velocity assumptions and ICU admission reduction protocol adoption rates.
The model assumes a particular technology adoption path; alternative pathways for cap-dependent endonuclease inhibitor resistance profiles would alter the outlook. Deviation in FDA emergency use authorization trigger thresholds or EMA rolling review pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Malaria Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Lung Cancer Surgery Market