
 Ringworm Treatment Market | 2026-2036
Ringworm Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ringworm Treatment Market Outlook
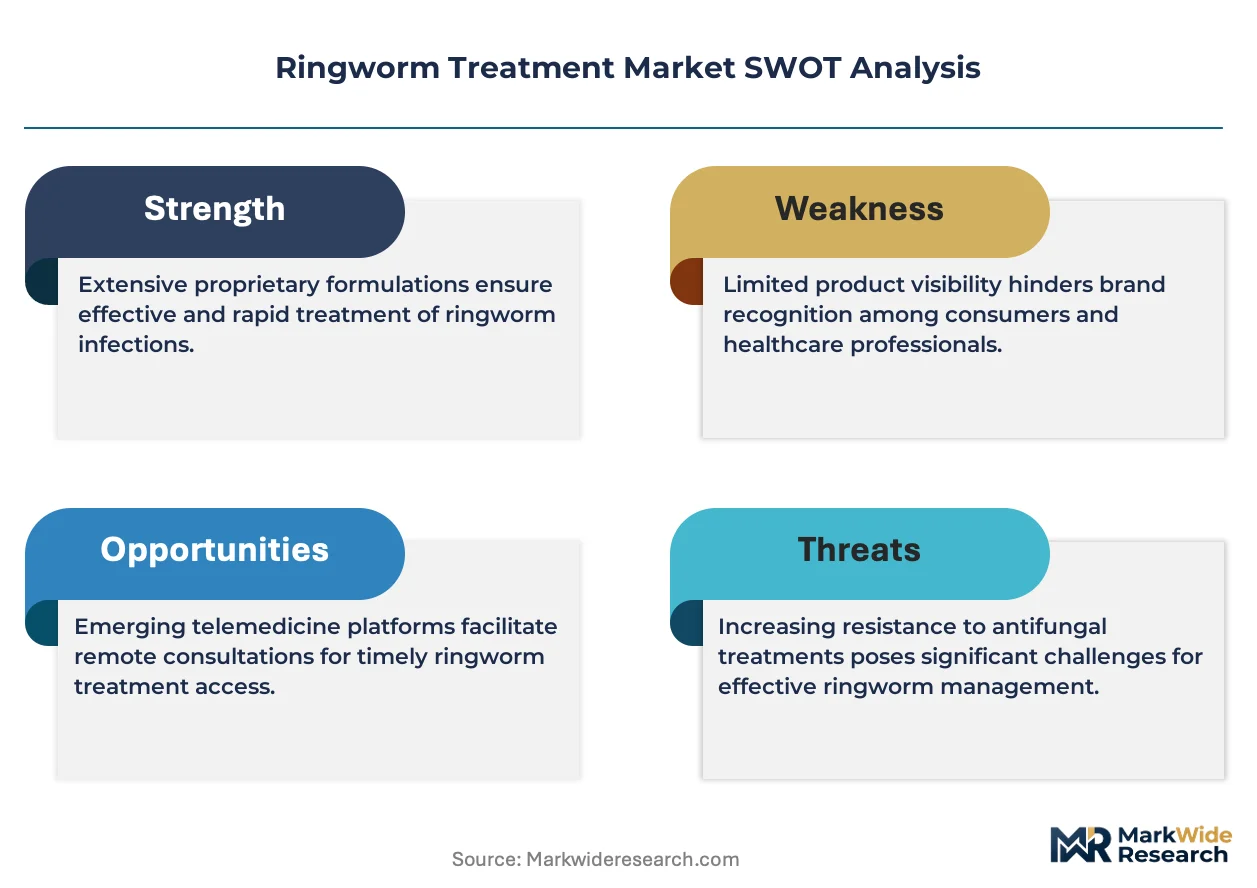
Prescription-grade efficacy standards is rotating the competitive baseline upward as patients and payers demand faster cure rates with lower relapse incidence. Bayer leverages its dermatology heritage and regulatory dossier depth to sustain premium positioning across European and North American channels. Perrigo Company anchors the private-label segment with manufacturing scale that competes aggressively on unit economics in drugstore and mass retail. Sun Pharmaceuticals dominates emerging-market volume through localized production networks and price-accessible formulations.
Ringworm treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting dermatophyte infections of keratinized tissues, with topical azoles and allylamines typically achieving mycological cure within two to four weeks of consistent application. The primary commercial purpose centers on eliminating fungal colonization while preventing transmission in communal settings such as athletic facilities, veterinary clinics, and households. Topical antifungals occupy the largest revenue pool due to first-line prescribing norms and strong OTC accessibility, though oral antifungals command superior margins where tinea capitis or onychomycosis requires systemic therapy. Telemedicine platforms represent the fastest-growing end-user channel as asynchronous dermatology consultations expand prescription fulfillment beyond traditional clinic footprints.
The FDA's OTC monograph reform and the EMA's centralized marketing authorization procedures shape product entry pathways, with the former accelerating switch potential from prescription to self-care status and the latter harmonizing quality benchmarks across EU member states. India's CDSCO enforces bioequivalence requirements for domestic generic manufacturers that supply price-sensitive tropical markets. Stakeholders must monitor how regulatory divergence between accelerated OTC pathways and tightened pharmacovigilance obligations affects portfolio allocation across prescription, switched, and purely consumer-facing segments.
Market Dynamics
Telemedicine platforms are compressing the traditional clinic-to-pharmacy fulfillment chain, enabling asynchronous dermatology consultations that bypass geographic access barriers and reshape how patients initiate ringworm treatment protocols.
Growth Catalysts
- FDA OTC Monograph Reform:Streamlined self-care approval pathways accelerate prescription-to-OTC switches, expanding retail shelf presence for topical azoles and allylamines without lengthy NDA requirements.
- Combination Protocol Adoption:Dermatology clinics increasingly pair oral terbinafine with topical ciclopirox for refractory tinea infections, elevating per-patient revenue and reducing relapse-driven retreatment cycles.
- Athletic Facility Hygiene Mandates:Collegiate and professional sports organizations enforce ringworm screening protocols, generating institutional procurement volume for prophylactic antifungal inventories.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Bulk azole production clusters in select Asian manufacturing hubs, exposing formulators to single-source disruption risk and volatile input pricing.
- Bioequivalence Burden:India's CDSCO enforces stringent comparative efficacy trials for domestic generic entrants, extending time-to-market for price-accessible alternatives in tropical high-prevalence zones.
- Topical Efficacy Ceiling:Keratinized nail plate penetration remains technically constrained, limiting topical solutions to early-stage onychomycosis and preserving oral therapy dominance for advanced cases.
Strategic Opportunities
- Veterinary Crossover Formulations:Zoonotic transmission from companion animals drives demand for human-compatible protocols, creating bundled household treatment offerings through veterinary clinic channels.
- Asynchronous Prescription Platforms:Telemedicine-enabled direct-to-patient fulfillment bypasses traditional pharmacy intermediaries, capturing margin and reducing abandonment at the consultation-to-treatment conversion point.
- EMA Centralized Authorization:Harmonized quality benchmarks across EU member states enable single-registration market access, reducing fragmentation costs for manufacturers targeting European dermatology networks.
Industry Challenges
- Dermatopathology Talent Scarcity:Mycological diagnostic expertise concentrates in academic medical centers, limiting accurate species identification in community settings and driving empiric overtreatment.
- Legacy Pharmacy Inventory Systems:Retail chain ERP platforms lack real-time telemedicine prescription integration, creating fulfillment lag between virtual consultation completion and product availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ringworm Treatment Market |
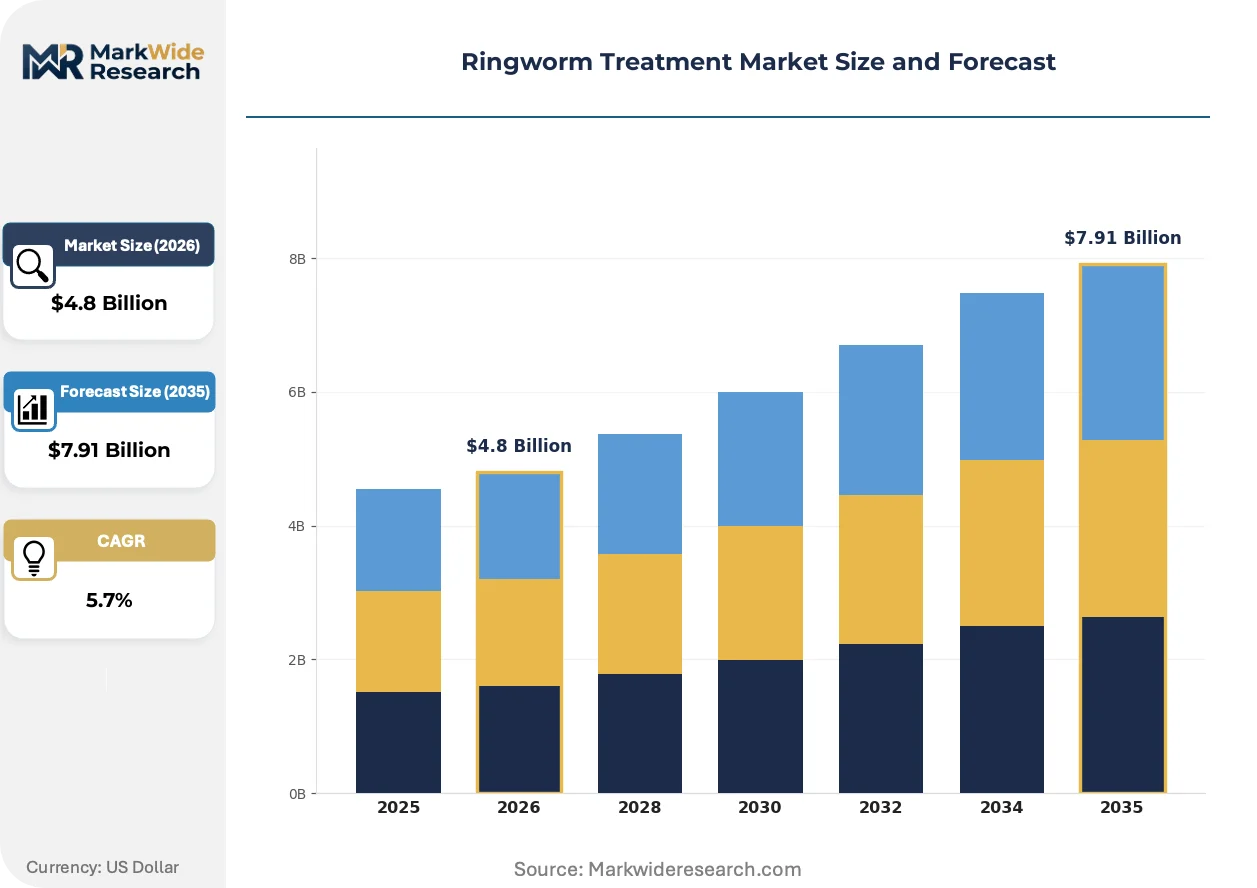
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Medicated Shampoos, Homeopathic Remedies, Herbal Extracts Therapy Area: Cutaneous Ringworm, Scalp Ringworm, Nail Ringworm, Body Ringworm, Facial Ringworm End User: Dermatology Clinics, Veterinary Clinics, Retail Pharmacies, Alternative Medicine Centers, Telemedicine Platforms Distribution Channel: Hospital Pharmacies, Online Pharmacies, Drugstores, Direct Sales, Health & Wellness Stores |
| Companies Covered | Bayer, Perrigo Company, Pfizer, Sun Pharmaceuticals, Johnson & Johnson, Merck, GlaxoSmithKline, Cipla, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ringworm Treatment Market Strategic Shifts
Antifungal development trajectories are pivoting toward delivery mechanism innovation and regulatory pathway optimization, with formulation science and digital health infrastructure converging to redefine patient access models.
Nanostructured lipid carriers for topical terbinafine are supplanting conventional cream bases by enhancing stratum corneum penetration and reducing required application frequency. Specialty dermatology practices in Germany and South Korea have adopted these vehicles for recalcitrant tinea corporis cases. The technology is compressing treatment duration expectations and pressuring legacy formulation margins.
The EMA's centralized marketing authorization procedures are harmonizing bioequivalence standards across EU member states, eliminating redundant national filings that previously fragmented commercialization timelines. Generic manufacturers now optimize dossier preparation for single-point regulatory review rather than sequential member-state negotiations. Dermatology clinics in France and Italy benefit from accelerated access to switched OTC alternatives.
Patient-initiated diagnostic photography through smartphone applications is displacing initial in-person consultations for uncomplicated tinea presentations. Pharmacy chains in the United States integrate these image-based assessments with same-day prescription fulfillment. This channel shift concentrates volume in retail settings equipped for immediate product dispensing rather than traditional clinic-based prescribing.
Ringworm Treatment Market Segmentation
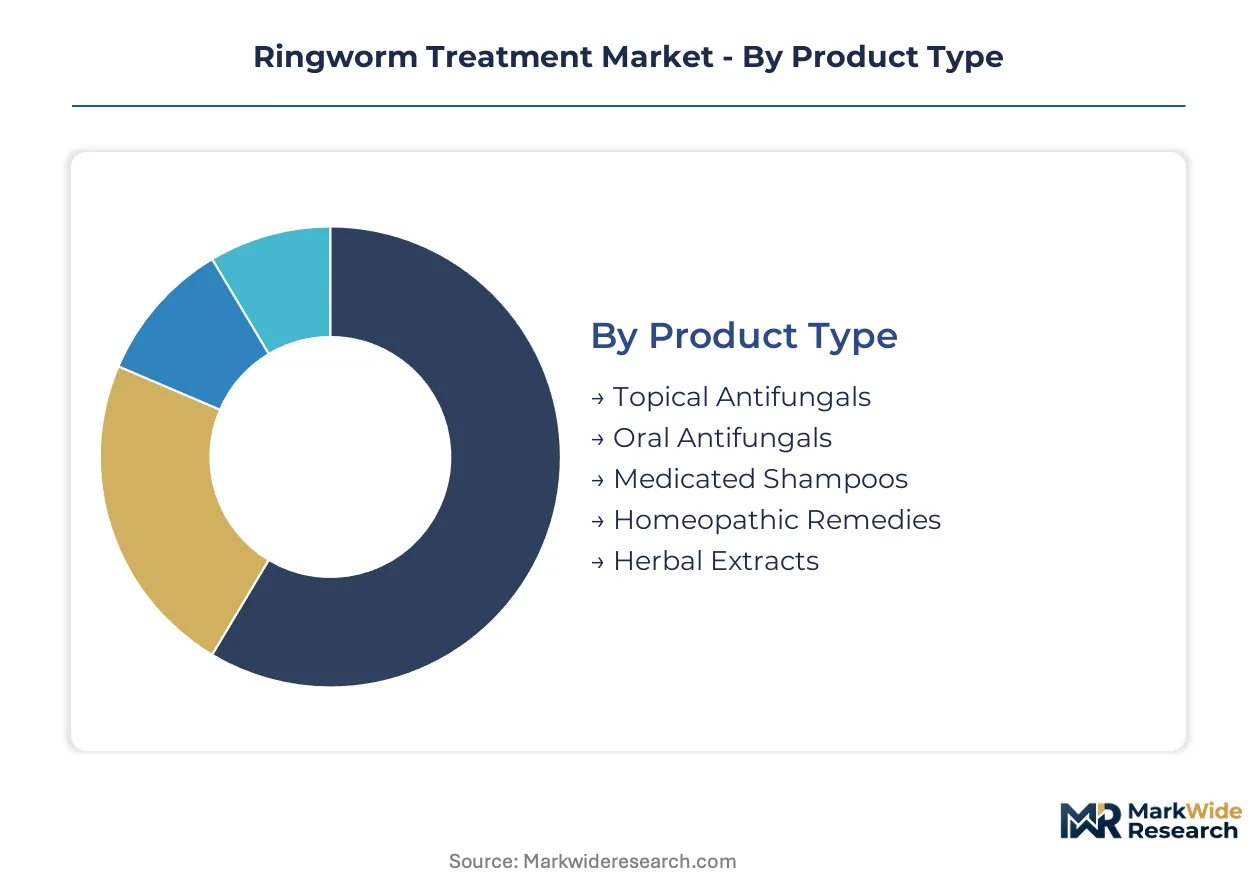
Segmentation in ringworm treatment reflects divergent regulatory pathways, prescribing authority, and patient access models. Product type and distribution channel classifications capture the friction between prescription-grade efficacy and self-care convenience.
Product Type:
FDA OTC monograph reform and EMA centralized procedures create divergent approval timelines across formulation categories, shaping competitive entry patterns.
- Topical Antifungals:Azole and allylamine creams, gels, and sprays delivering localized dermatophyte elimination through stratum corneum penetration. Demand concentrates in United States retail pharmacy chains where FDA's streamlined OTC pathways accelerate shelf placement without NDA requirements.
- Oral Antifungals:Systemic terbinafine and itraconazole formulations achieving mycological cure through nail plate and hair follicle distribution. Prescription concentration in Germany's dermatology networks reflects EMA's tightened pharmacovigilance obligations for hepatotoxicity monitoring.
- Medicated Shampoos:Ketoconazole and selenium sulfide formulations targeting tinea capitis prophylaxis in athletic and institutional settings.
- Homeopathic Remedies:Diluted botanical preparations positioned outside pharmaceutical regulatory frameworks in European wellness channels.
- Herbal Extracts:Tea tree oil and neem-based formulations distributed through India's Ayurvedic retail networks under CDSCO cosmetic classification.
Topical antifungals handle the majority of throughput; telemedicine-enabled oral prescriptions are expanding most quickly on share.
Therapy Area:
Clinical complexity and reimbursement intensity vary sharply across anatomical presentation sites, with nail and scalp infections demanding prolonged therapeutic exposure.
- Cutaneous Ringworm:Tinea corporis and cruris infections of glabrous skin responding to topical monotherapy. Volume concentrates in United States telemedicine platforms where asynchronous photography enables rapid prescription triage.
- Scalp Ringworm:Tinea capitis requiring oral antifungal penetration of hair shafts, prevalent in pediatric populations and institutional transmission clusters.
- Nail Ringworm:Onychomycosis characterized by keratinized plate colonization resistant to topical penetration.
- Body Ringworm:Tinea corporis variants distinguished from cutaneous classification by lesion distribution patterns in tropical climates.
- Facial Ringworm:Tinea faciei presentations requiring differential diagnosis from corticosteroid-exacerbated infections in South Korean cosmetic dermatology clinics.
Cutaneous presentations dominate prescription volume; nail infections command the steepest per-patient revenue trajectory.
End User:
Channel fragmentation reflects divergent diagnostic capabilities, with species identification accuracy varying across clinical and commercial settings.
- Dermatology Clinics:Academic and community practices with mycological culture capacity, concentrated in France and Italy where EMA harmonization accelerated switched-OTC adoption.
- Veterinary Clinics:Companion animal treatment sites generating zoonotic transmission prophylaxis demand for household bundled protocols.
- Retail Pharmacies:United States drugstore chains and mass merchants capturing OTC azole volume through immediate product accessibility.
- Alternative Medicine Centers:Ayurvedic and traditional Chinese medicine practitioners in India and China distributing herbal formulations outside pharmaceutical regulatory pathways.
- Telemedicine Platforms:Asynchronous dermatology consultation services compressing diagnosis-to-treatment intervals through smartphone image submission and same-day prescription fulfillment.
Retail pharmacies handle the majority of throughput; telemedicine platforms are climbing the fastest on patient-initiated consultation share.
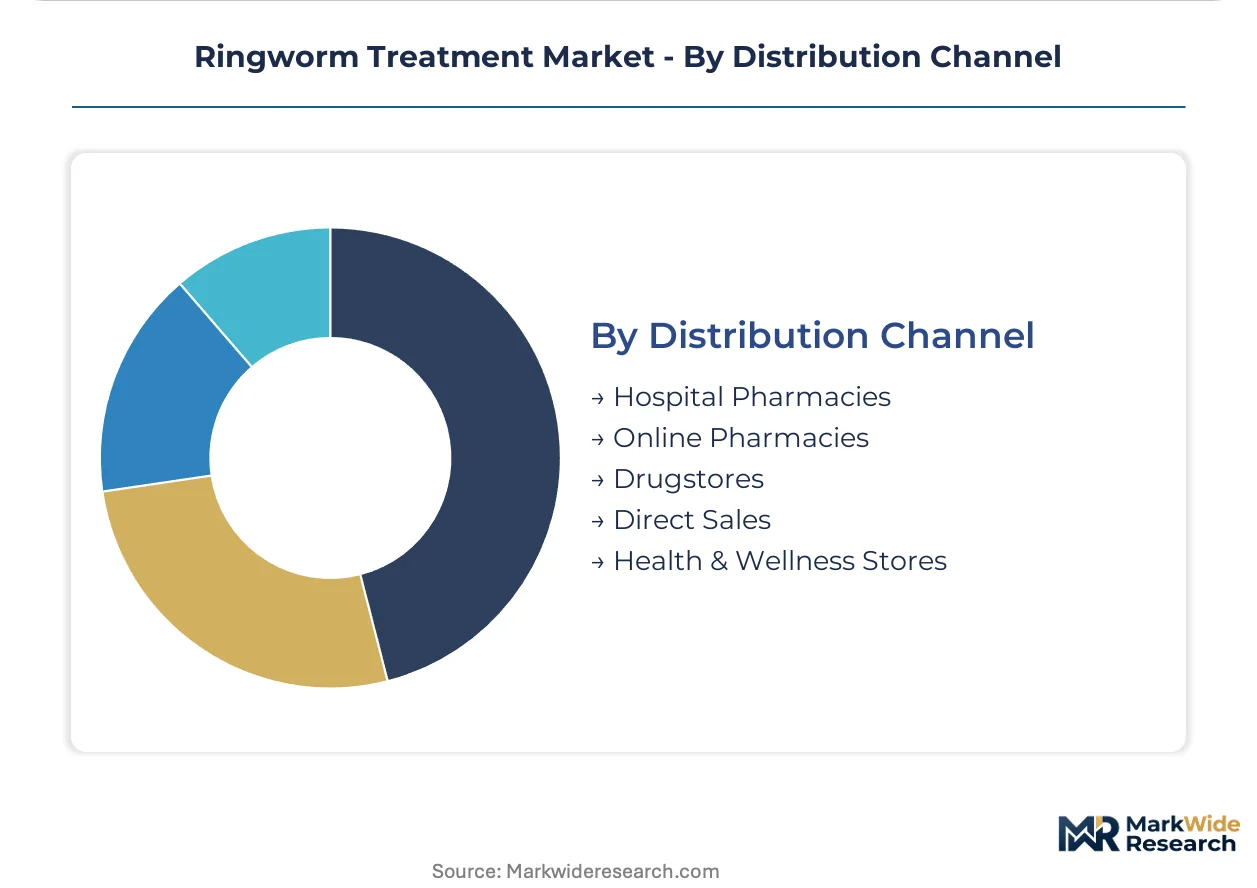
Distribution Channel:
Inventory integration and prescription fulfillment speed determine competitive positioning, with legacy ERP systems creating friction in telemedicine-retail handoffs.
- Hospital Pharmacies:Inpatient and outpatient dispensaries attached to academic medical centers with dermatopathology expertise.
- Online Pharmacies:Direct-to-patient fulfillment platforms bypassing brick-and-mortar intermediaries, concentrated in United States markets with asynchronous prescription validity.
- Drugstores:CVS, Walgreens, and independent chains with immediate topical antifungal availability but lagging telemedicine prescription integration.
- Direct Sales:Manufacturer-controlled channels for veterinary crossover and institutional athletic procurement contracts.
- Health & Wellness Stores:GNC, Holland & Barrett, and regional chains distributing herbal and homeopathic alternatives under cosmetic or supplement classification.
Drugstores handle the majority of throughput; online pharmacies are gaining share fastest on telemedicine prescription routing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of active pharmaceutical ingredients concentrate in Indian and Chinese manufacturing hubs, while finished formulation demand concentrates in North American and European retail channels. Import dependency for azole intermediates shapes procurement timelines across Atlantic markets.
United States
Telemedicine platforms and retail pharmacy chains drive prescription-to-fulfillment velocity for topical antifungals. FDA's streamlined OTC monograph reform accelerates shelf placement without lengthy NDA requirements. Dermatology networks in Texas and Florida expand asynchronous consultation capacity for tinea diagnoses.
Germany
Academic dermatology centers in Munich and Berlin anchor mycological diagnostic expertise for refractory infections. EMA's centralized marketing authorization procedures harmonize quality benchmarks across EU member states. Baden-Württemberg's pharmaceutical cluster specializes in nanostructured lipid carrier formulations for enhanced stratum corneum penetration.
India
Domestic generic manufacturers supply price-accessible formulations to tropical high-prevalence zones across Southeast Asia and Africa. CDSCO enforces bioequivalence requirements that extend time-to-market for new entrants. Maharashtra's Mumbai-Pune corridor hosts concentrated bulk azole production capacity serving export markets.
China
Dual carbon goals and environmental compliance standards reshape active pharmaceutical ingredient manufacturing economics in Jiangsu and Zhejiang provinces. NMPA's marketing authorization procedures govern domestic antifungal registration timelines. Yangtze River Delta chemical parks consolidate intermediate production for allylamine derivatives.
Brazil
Institutional procurement for athletic facility hygiene protocols generates volume in collegiate and professional sports organizations. ANVISA's regulatory framework governs prescription and OTC classification boundaries for topical antifungals. São Paulo's dermatology clinics adopt combination oral-topical protocols for tinea capitis in pediatric populations.
Ringworm Treatment Market Competitive Environment
Concentration sits with diversified pharmaceutical conglomerates and specialized dermatology players. Bayer leverages regulatory dossier depth across European and North American channels. Perrigo Company anchors private-label manufacturing scale. Sun Pharmaceuticals dominates emerging-market volume through localized production networks. Two dominant competitive moves reshape positioning: prescription-to-OTC switch execution and telemedicine platform integration for direct-to-patient fulfillment.
Within the diversified pharmaceutical tier, Bayer and Pfizer occupy positions reflecting legacy dermatology heritage and broad regulatory infrastructure. Perrigo Company exemplifies the private-label archetype competing aggressively on unit economics in drugstore and mass retail channels. Sun Pharmaceuticals represents emerging-market volume leadership through price-accessible formulations and distributed manufacturing networks.
| Leading Market Players |
|---|
| Bayer |
| Perrigo Company |
| Pfizer |
| Sun Pharmaceuticals |
| Johnson & Johnson |
| Merck |
| GlaxoSmithKline |
| Cipla |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts for bulk azole intermediates lock in supply access and price visibility for European and North American formulators facing volatile Asian input markets. These arrangements concentrate procurement power among scaled manufacturers while exposing smaller players to spot market fluctuations.
Pricing Analysis
Retail pharmacy chains anchor a three-tier pricing structure across premium, standard, and economy levels in topical antifungals. Price differentiation hinges on FDA switch status and brand heritage, with switched OTC alternatives commanding shelf placement premiums. Pricing pressure stems from private-label manufacturing scale at Perrigo and Sun Pharmaceuticals. Price-sensitive volume concentrates in India's domestic generic market, while premium positioning persists in German dermatology networks.
Supply Chain Analysis
India and China anchor bulk azole and allylamine active pharmaceutical ingredient production for global ringworm treatment supply. Formulation draws from concentrated intermediate manufacturing in Maharashtra's Mumbai-Pune corridor and Jiangsu province chemical parks. Single-source vulnerability in ketoconazole raw material supply creates disruption exposure. Distribution runs through retail pharmacy chains in the United States and hospital pharmacies in Germany, with telemedicine platforms emerging as direct-to-patient alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail pharmacy chains and telemedicine platforms that control prescription routing and shelf placement. This concentration fragments negotiating leverage among legacy manufacturers.
For Market Incumbents: Consolidate regulatory dossier depth across FDA and EMA jurisdictions to defend premium positioning against private-label encroachment. Expand nanostructured lipid carrier manufacturing capacity in Baden-Württemberg to differentiate formulation performance. Lock in long-term offtake contracts for azole intermediates before input volatility intensifies. For New Entrants and Emerging Players: Asynchronous diagnostic photography integration represents a service-layer gap where incumbents under-serve patient-initiated consultation demand. Target veterinary clinic channels for bundled household zoonotic prophylaxis protocols in Brazil and the United States. Pursue CDSCO bioequivalence certification for price-accessible generic entry into Southeast Asian tropical markets. For Investors and Strategic Acquirers: Nanostructured topical formulation specialists with EMA centralized authorization dossiers represent the most defensible acquisition target archetype. Long-term viability rests on delivery mechanism innovation compressing treatment duration. Watch FDA OTC monograph reform acceleration as inflection signal for prescription-to-switch conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Authorization Dossier Preparation | Harmonized EU access reduces fragmentation costs for generic manufacturers targeting dermatology networks. |
| Telemedicine Platform Integration | Asynchronous prescription fulfillment captures margin from traditional pharmacy intermediaries in United States markets. |
| Backward Integration into API Manufacturing | Captive azole supply insulates formulators from single-source disruption risk in Indian chemical parks. |
| Veterinary Crossover Formulation Development | Zoonotic transmission protocols unlock bundled household demand through companion animal clinic channels. |
| Nanostructured Lipid Carrier Scale-Up | Enhanced stratum corneum penetration technology compresses treatment duration and pressures legacy cream margins. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dermatology clinic directors, retail pharmacy chain procurement managers, CDSCO regulatory affairs leads, veterinary clinic formulary decision-makers, and telemedicine platform operations executives. Secondary validation drew from FDA OTC monograph filings, EMA centralized marketing authorization procedures, CDSCO bioequivalence submission databases, and Indian pharmaceutical export customs records. Bottom-up patient volume modeling and top-down market sizing triangulated value estimates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, therapy area, end-user channel, and distribution pathway. CAGRs were derived from patient incidence trends, prescription fulfillment velocity shifts, and regulatory switch conversion timelines. Forecast inputs incorporated telemedicine platform adoption curves and veterinary zoonotic screening protocol expansion.
Forecasts assume regulatory continuity in FDA OTC monograph reform and EMA centralized authorization procedures; material policy shifts would require re-modeling. Specific risks include CDSCO bioequivalence trial delays, active pharmaceutical ingredient supply disruptions, and telemedicine prescription validity jurisdictional fragmentation. Recalibration cycles align with material shifts in asynchronous dermatology consultation volume and switched-OTC regulatory velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Onchocerciasis Treatment Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market