
 Otoplasty Market | 2026-2036
Otoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Otoplasty Market Intelligence
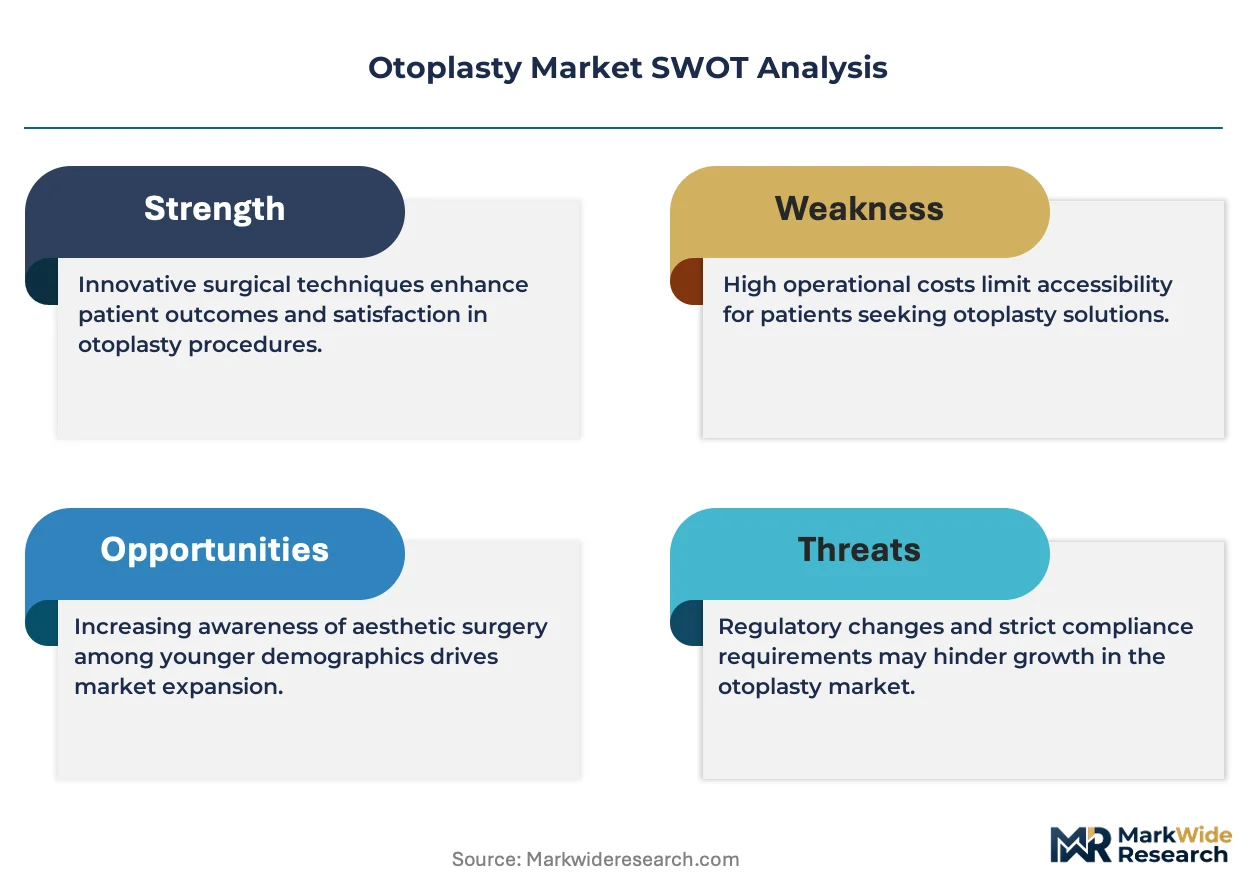
Hospital procurement of otoplasty implants is narrowing toward vendors with integrated sterilization logistics and direct-to-OR delivery capabilities. Stryker Corporation leverages its orthopedic supply chain infrastructure to dominate institutional purchasing channels across North America. Allergan Aesthetics sustains brand recognition in private cosmetic surgery centers through physician training programs and proprietary suture techniques. Integra LifeSciences specializes in biologic mesh overlays for ear reconstruction, occupying a defensible niche in complex microtia cases.
Otoplasty denotes surgical alteration of the external ear's cartilaginous framework to correct protrusion, deformity, or congenital absence, typically employing scoring, suturing, or grafting techniques with local or general anesthesia. The procedure restores aesthetic proportion and psychological function, primarily serving pediatric patients with prominent ears and adults seeking reconstructive symmetry. Pinnaplasty leads procedural volume due to its relative technical simplicity and outpatient feasibility, while ear reconstruction commands premium pricing through autologous rib cartilage harvesting and multi-stage operative timelines. Silicone implants retain share in adult aesthetic cases for predictable contouring, though autologous cartilage is displacing synthetic options in pediatric protocols where long-term biocompatibility governs material selection.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation shape product entry timelines, with both agencies intensifying scrutiny of implantable polymer degradation profiles. The EU AI Act and GDPR provisions increasingly govern preoperative imaging software and patient data management systems deployed across European surgical workflows. Stakeholders must monitor evolving reimbursement codes for congenital versus cosmetic indication distinctions, as payer classification directly determines addressable patient pools and procedure economics.
Market Dynamics
Autologous cartilage harvesting protocols are compressing synthetic implant demand as pediatric biocompatibility standards tighten across US and EU regulatory pathways. This material transition redistributes value from polymer manufacturers toward microsurgical training infrastructure and rib graft instrumentation suppliers.
Growth Catalysts
- EU Medical Device Regulation (MDR) material traceability mandates:Surgical centers accelerate adoption of autologous tissue protocols to bypass polymer degradation documentation burdens.
- Pediatric early-intervention protocols:Parental demand for school-age corrective surgery expands addressable patient pools before cartilage calcification limits graft viability.
- 3D patient-specific modeling:Preoperative simulation software reduces revision rates and operative time in complex microtia reconstruction cases.
Market Restraints
- Cost structure pressure from rib cartilage harvesting:Multi-stage autologous procedures require general anesthesia and inpatient recovery, elevating reimbursement complexity versus outpatient synthetic alternatives.
- Supply concentration in microtia specialist centers:Complex ear reconstruction capability clusters at tertiary pediatric hospitals in the United States, Germany, and Japan, limiting geographic accessibility.
- FDA 510(k) polymer degradation scrutiny:Implantable silicone device pathways face extended review timelines as the agency demands longitudinal biocompatibility data.
Strategic Opportunities
- Underpenetrated India aesthetic surgery market:Rising disposable income and medical tourism infrastructure create entry points for otoplasty service expansion beyond metro Delhi and Mumbai clusters.
- Telemedicine preoperative consultation channels:Remote assessment platforms reduce geographic friction for rural pediatric patient access to specialist evaluation.
- Bioresorbable scaffold technology convergence:Integration of 3D-printed absorbable polymers with autologous cell seeding offers synthetic-autologous hybrid reconstruction pathways.
Industry Challenges
- Microvascular anastomosis skill scarcity:Free-flap ear reconstruction requires subspecialty training pipelines that academic medical centers struggle to sustain.
- CE marking timeline compression under MDR:Notified body capacity constraints delay product certification for novel implantable devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Otoplasty Market |
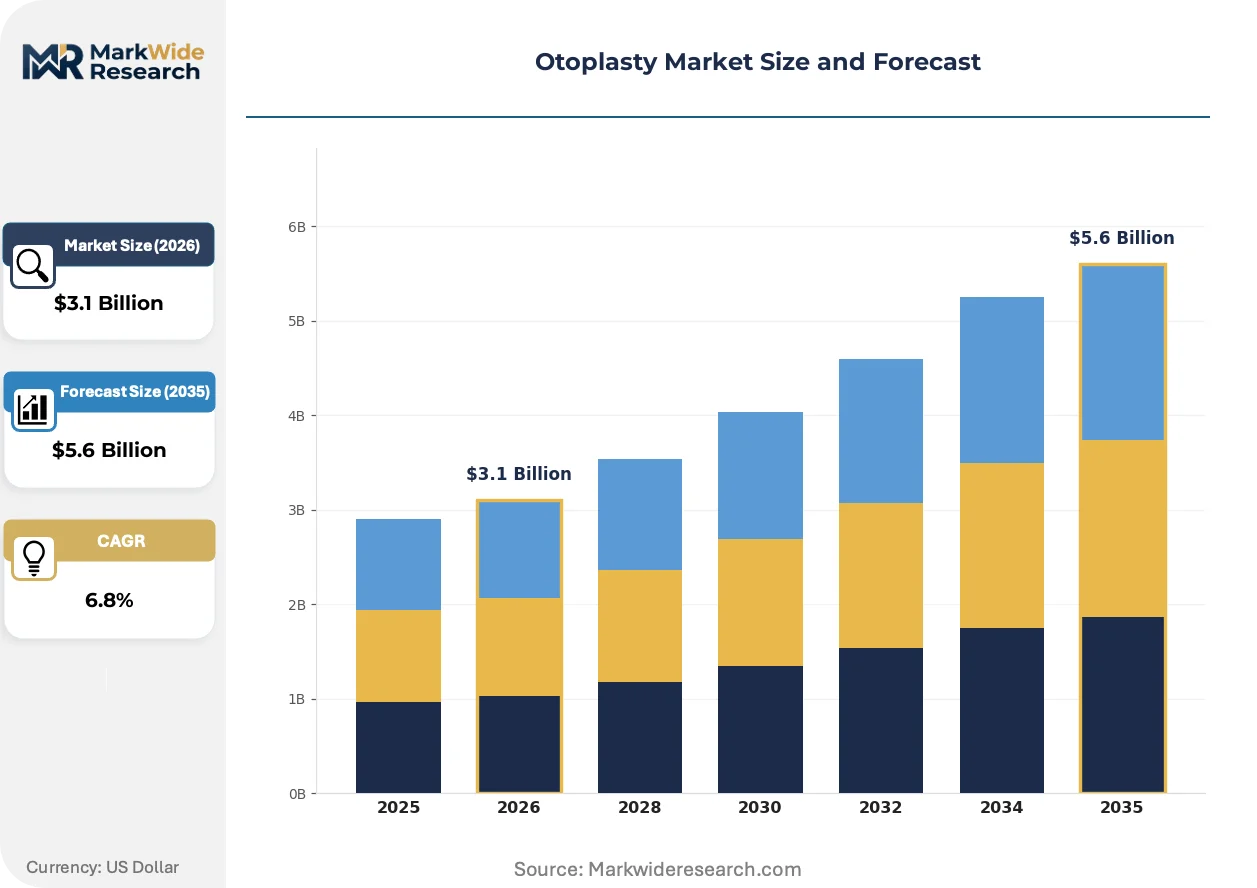
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Ear Reconstruction, Pinnaplasty, Aesthetic Ear Surgery, Surgical Correction Material Type: Silicone, Polypropylene, Autologous Cartilage, Composite Materials Age Group: Pediatrics, Adults, Adolescents, Geriatrics End User: Hospitals, Clinics, Ambulatory Surgery Centers, Cosmetic Surgery Centers |
| Companies Covered | Implantech Associates, HansBiomed Co., Ltd., Stryker Corporation, Earfold, Sklar Surgical Instruments, Allergan Aesthetics, Koken Co., Ltd., Invotec International, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Otoplasty Market Strategic Shifts & Innovations
Preoperative planning software and bioresorbable materials are restructuring operative workflows and postoperative outcomes across reconstructive and aesthetic ear surgery. These shifts compress decision cycles and expand treatable case complexity.
Three-dimensional photogrammetric ear modeling is virtualizing the surgical planning phase. Pediatric reconstructive centers adopt this technology to reduce operative time and improve symmetry outcomes in bilateral microtia cases. The technology is virtualizing traditional two-dimensional template methods and compressing revision rates.
CE marking under the EU Medical Device Regulation intensifies post-market surveillance obligations for implantable ear devices. Manufacturers must establish systematic clinical follow-up registries to demonstrate long-term safety. Pediatric autologous protocols gain relative advantage as they circumvent polymer-specific surveillance requirements.
Direct-to-consumer digital consultation platforms are fragmenting traditional referral pathways. Private cosmetic surgery centers in the United States deploy social media assessment tools to capture patient inquiries before dermatology or primary care gatekeeping. Southern California and Florida markets exhibit the highest platform adoption rates.
Otoplasty Market Segmentation
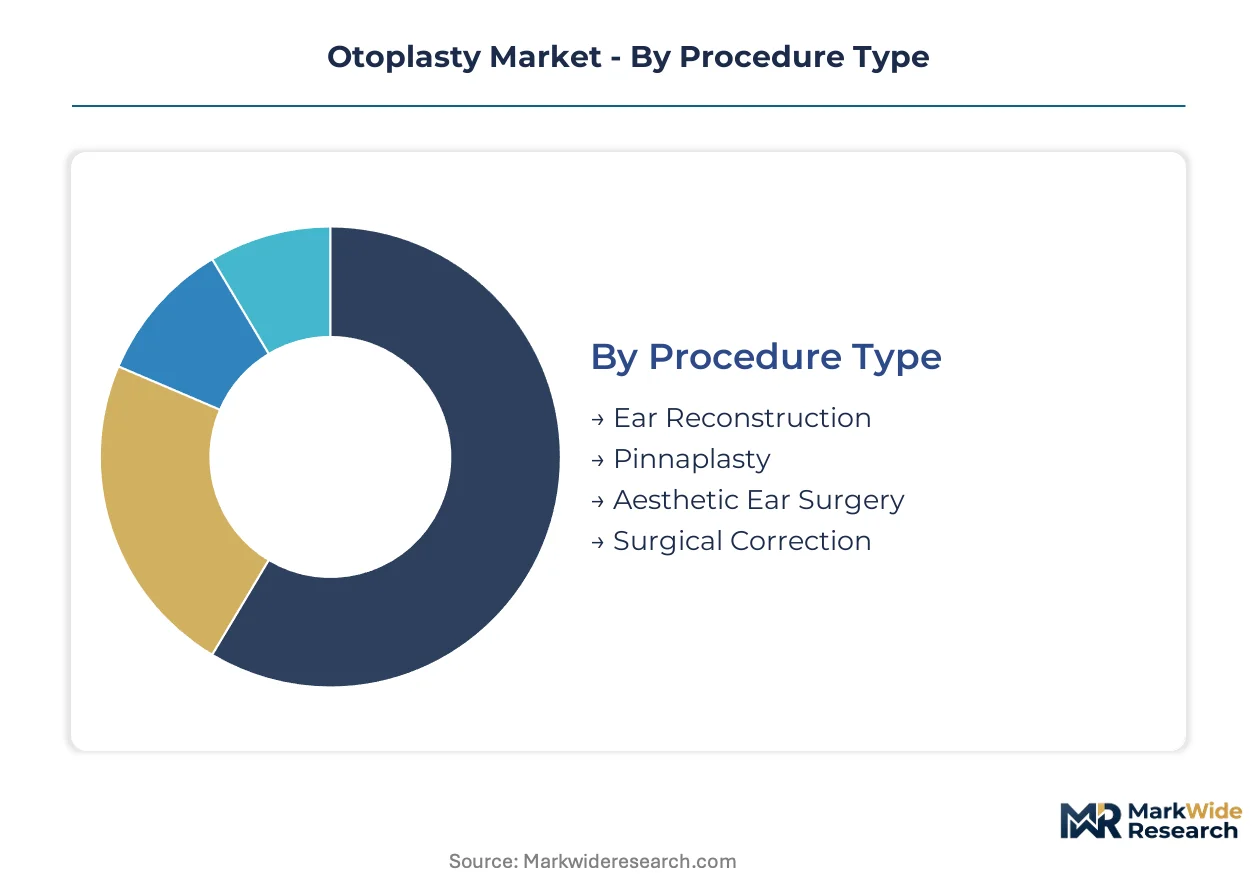
Segmentation in the otoplasty market reveals how procedural complexity, material biocompatibility, and patient life-stage reshape competitive positioning. Each dimension carries distinct regulatory, reimbursement, and technical requirements that determine vendor profitability and market access.
Procedure Type:
Application complexity separates outpatient aesthetic correction from multi-stage reconstructive intervention. Surgeons select approaches based on congenital defect severity, cartilage availability, and anesthesia tolerance.
- Ear Reconstruction:Multi-stage autologous rib cartilage grafting restores congenital microtia or traumatic auricular loss. Demand clusters at tertiary pediatric hospitals in the United States, Germany, and Japan where microvascular flap expertise concentrates.
- Pinnaplasty:Suture-based cartilage reshaping corrects prominent ears without graft harvesting. Outpatient feasibility and local anesthesia protocols drive adoption in private cosmetic surgery centers across Florida and Southern California.
- Aesthetic Ear Surgery:Cosmetic refinement of ear size, position, or contour addresses patient-specific proportion concerns. Adult demand in metropolitan India centers on Delhi and Mumbai medical tourism corridors.
- Surgical Correction:Trauma or oncologic defect repair combines reconstructive and aesthetic objectives. Hospital-based tertiary centers manage these cases through integrated plastic surgery and otolaryngology departments.
Pinnaplasty commands the established base. The steepest expansion runs through Ear Reconstruction.
Material Type:
Supply concentration and regulatory burden differentiate synthetic polymer pathways from autologous tissue protocols. Material selection directly determines operative staging, reimbursement coding, and long-term surveillance obligations.
- Silicone:Prefabricated implants enable predictable contouring in adult aesthetic cases. FDA 510(k) polymer degradation scrutiny extends review timelines as longitudinal biocompatibility data requirements intensify.
- Autologous Cartilage:Patient-derived rib or conchal cartilage eliminates foreign-body rejection risk. Pediatric protocols favor this option as EU MDR material traceability mandates tighten synthetic implant documentation burdens.
- Polypropylene:Mesh frameworks provide structural scaffolding in select reconstructive applications. CE marking timeline compression under MDR notified body capacity constraints delays novel device certification.
- Composite Materials:Bioresorbable polymer-cell seeding hybrids integrate synthetic handling with autologous biocompatibility. Academic medical centers in Boston and Baltimore pioneer 3D-printed scaffold protocols.
Silicone retains the installed base. The steepest expansion trajectory belongs to Autologous Cartilage.
Age Group:
Customer type determines cartilage plasticity, anesthesia risk, and psychological intervention timing. Surgical candidacy windows constrain addressable patient pools and procedure economics.
- Pediatrics:School-age correction before cartilage calcification maximizes graft viability and psychological benefit. Parental awareness campaigns expand early-intervention protocols across US suburban markets.
- Adolescents:Self-image consciousness drives demand for prominent ear correction before social milestone events. European private clinics target this segment through summer vacation scheduling.
- Adults:Elective aesthetic refinement and trauma reconstruction sustain procedural volume. US insurance flexibility for congenital deformity correction outpaces European reimbursement rigidity.
- Geriatrics:Oncologic defect repair and age-related aesthetic concerns represent niche demand. Medicare coding distinctions between reconstructive and cosmetic indications limit penetration.
Adults sustain the revenue base. Pediatrics is climbing the fastest.
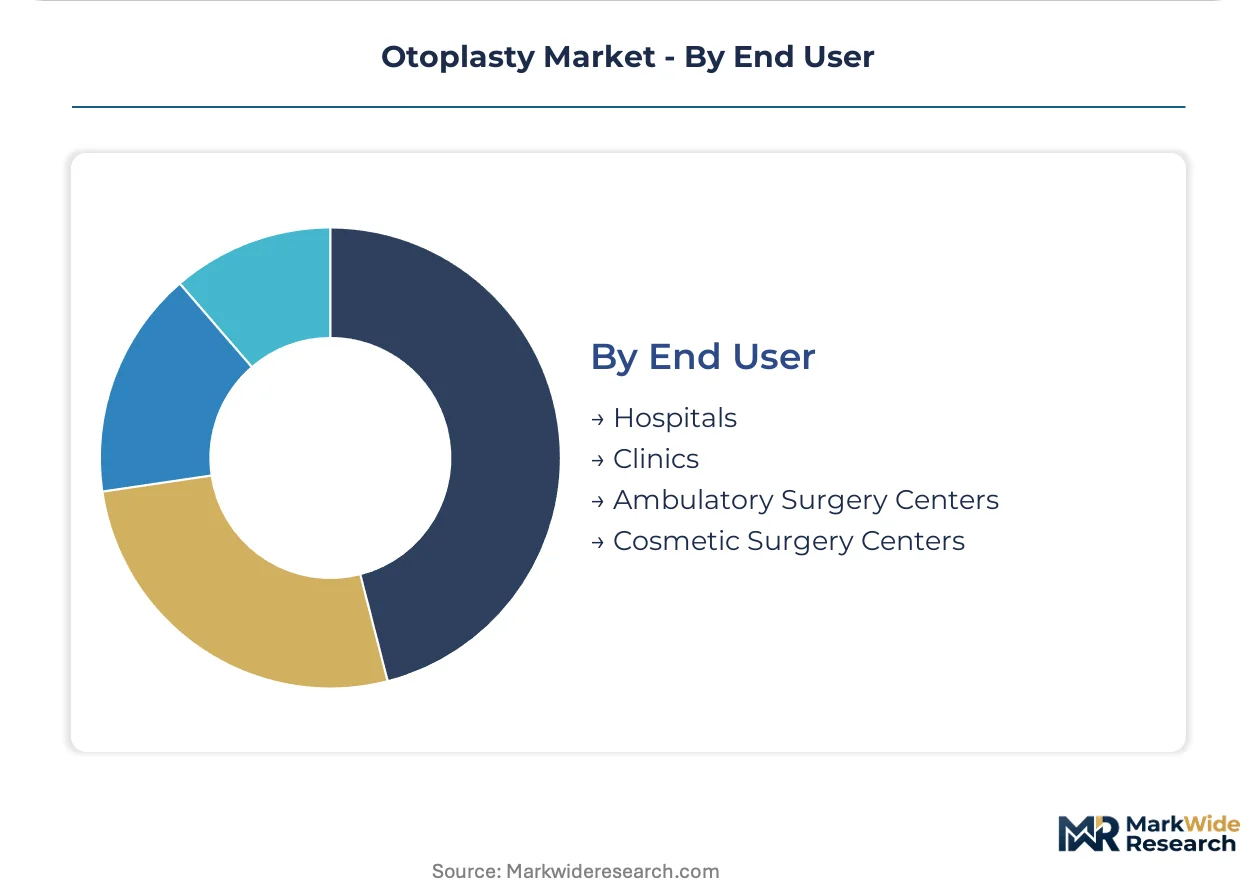
End User:
Facility type dictates procurement authority, sterilization infrastructure, and referral pathway control. Channel concentration shapes vendor pricing power and service bundling requirements.
- Hospitals:Integrated sterilization logistics and direct-to-OR delivery capabilities dominate institutional purchasing. Stryker Corporation leverages orthopedic supply chain infrastructure across North American health systems.
- Cosmetic Surgery Centers:Physician training programs and proprietary suture techniques sustain brand loyalty. Allergan Aesthetics captures this channel through surgeon certification networks.
- Ambulatory Surgery Centers:Outpatient cost efficiency and specialized anesthesia protocols concentrate pinnaplasty volume. United States ASC reimbursement rates favor same-day discharge procedures.
- Clinics:Telemedicine preoperative consultation platforms reduce geographic friction for rural pediatric access. Direct-to-consumer digital tools fragment traditional dermatology referral pathways.
Hospitals anchor volume. Cosmetic Surgery Centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors trans-Pacific medical device logistics, underwriting California's dominance in aesthetic surgery supply chains. Frankfurt's cargo hub feeds EU MDR compliance documentation through German notified bodies. Singapore's Changi air freight corridor enables just-in-time implant delivery across Southeast Asian surgical centers.
United States
Cosmetic surgery center density in Florida and Southern California drives outpatient pinnaplasty volume. FDA 510(k) clearance pathways for silicone implants face extended review timelines as longitudinal biocompatibility data requirements intensify. The Greater Boston corridor hosts academic medical centers pioneering 3D-printed bioresorbable scaffold protocols for microtia reconstruction.
Germany
EU MDR material traceability mandates accelerate autologous cartilage adoption in pediatric protocols. Notified body capacity constraints in Frankfurt and Munich delay novel implantable device certification timelines. The Baden-Württemberg cluster concentrates tertiary microtia reconstruction expertise alongside Stuttgart's precision instrumentation suppliers.
Japan
PMDA post-market surveillance obligations for implantable polymers favor rib cartilage harvesting in congenital cases. METI funding for regenerative medicine infrastructure supports academic-industry partnerships in 3D bioprinting. The Osaka-Kobe medical device corridor supplies microsurgical instrumentation to specialist centers across East Asia.
India
Rising disposable income in Delhi and Mumbai medical tourism corridors creates entry points for aesthetic otoplasty service expansion. CDSCO medical device registration requirements for imported implants favor domestic sterilization logistics partnerships. The Karnataka biotechnology cluster in Bangalore seeds startup activity in patient-specific surgical planning software.
United Kingdom
NHS coding distinctions between congenital and cosmetic indications constrain reimbursement for adult aesthetic procedures. MHRA convergence with EU MDR standards elevates documentation burdens for polymer-based implants. London's private Harley Street clinics capture high-value ear reconstruction referrals from Gulf state medical tourists.
Otoplasty Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying sterilization logistics and microsurgical instrumentation. The vendor base stratifies across three tiers: multinational orthopedic supply chains with direct-to-OR delivery infrastructure, aesthetic-focused device manufacturers with proprietary suture techniques, and biologic mesh specialists occupying complex reconstructive niches. Dominant competitive moves include backward integration into autologous graft instrumentation and geographic expansion through telemedicine preoperative consultation platforms.
Among North American supply chain integrators, Stryker Corporation exemplifies the institutional purchasing channel archetype through orthopedic infrastructure leverage. Allergan Aesthetics occupies a position within the physician training and brand recognition tier, while Integra LifeSciences represents the biologic mesh specialist model for complex microtia cases. Koken Co., Ltd. and HansBiomed Co., Ltd. anchor the Asia-Pacific fabrication segment with Korean and Japanese structural positioning.
| Leading Market Players |
|---|
| Implantech Associates |
| HansBiomed Co., Ltd. |
| Stryker Corporation |
| Earfold |
| Sklar Surgical Instruments |
| Allergan Aesthetics |
| Koken Co., Ltd. |
| Invotec International |
| Integra LifeSciences |
| Others |
Cost & Logistics Intelligence
Undercapacity at EU MDR-notified bodies in Frankfurt and Munich compresses silicone implant certification timelines and elevates autologous cartilage pricing power. Surgical centers absorb premium costs for rib graft instrumentation to bypass polymer documentation burdens, while outpatient pinnaplasty volume in Florida and Southern California sustains per-procedure pricing discipline through ASC reimbursement efficiency.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates complex microtia reconstruction from outpatient pinnaplasty and basic aesthetic refinement. Premium tier pricing draws from autologous cartilage harvesting with multi-stage anesthesia protocols, while standard tier captures silicone implant procedures with FDA 510(k) compliance costs embedded. Cost compression in the economy tier intensifies as Indian medical tourism corridors absorb price-sensitive demand from Gulf state patients. Cosmetic surgery centers exhibit lowest price sensitivity due to proprietary suture technique bundling, whereas rural pediatric clinics face highest sensitivity to rib graft instrumentation costs.
Supply Chain Analysis
Polymer feedstock sourcing rests on German precision instrumentation suppliers, Japanese microsurgical device fabricators, and Korean biologic mesh manufacturers. Silicone raw materials feed from industrial chemical corridors in Germany and Japan, while autologous graft instrumentation draws from Stuttgart's surgical tool cluster and Osaka-Kobe's titanium machining capacity. Single-source vulnerability concentrates in MDR-notified body capacity constraints delaying CE marking for novel implantable devices. Distribution runs through hospital integrated delivery networks in North America, direct-to-OR logistics for cosmetic surgery centers, and telemedicine-enabled consultation platforms fragmenting traditional referral pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in otoplasty outpace hardware growth as remote preoperative consultation platforms and surgeon training certification programs expand recurring revenue streams faster than implant sales. Postoperative surveillance registries and 3D modeling software subscriptions deepen customer lifetime value beyond single-procedure economics.
For Market Incumbents: Harden autologous graft instrumentation supply chains through backward integration into rib harvesting tool manufacturing, insulating against MDR-driven polymer demand volatility. Fortify hospital purchasing committee relationships with direct-to-OR sterilization logistics to defend against Stryker Corporation's orthopedic infrastructure leverage in North American health systems. For New Entrants and Emerging Players: Geographic underpenetration in India's secondary cities beyond Delhi and Mumbai medical tourism corridors offers white-space expansion through CDSCO-registered domestic sterilization partnerships. Target pediatric telemedicine consultation platforms for rural access, deploying social media assessment tools to capture parental inquiries before primary care gatekeeping establishes referral control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among surgical planning software developers with 3D photogrammetric modeling capabilities and postoperative surveillance registry operators. Long-term viability over the projection horizon favors acquisition targets with bioresorbable scaffold intellectual property and academic medical center clinical validation. Monitor FDA 510(k) polymer degradation guidance revisions as inflection signals for autologous cartilage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR-notified body engagement in Frankfurt accelerates autologous protocol competitive positioning. |
| Hospital System Partnership | Integrated sterilization logistics with direct-to-OR delivery secures institutional purchasing volume. |
| Software Companion Development | 3D photogrammetric ear modeling reduces operative time and revision rates in bilateral microtia. |
| Reimbursement Strategy | Congenital versus cosmetic coding distinctions determine addressable patient pools and procedure economics. |
| Acquisition of Specialist Firm | Bioresorbable scaffold technology targets integrate synthetic handling with autologous biocompatibility. |
Research Approach
The analysis maps autologous cartilage protocols, silicone implant pathways, bioresorbable scaffold development, and telemedicine consultation platforms, each validated through reconstructive surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interview data triangulates against FDA 510(k) filings, EU MDR notified body registration databases, CMS Medicare reimbursement coding records, and hospital procurement system contract disclosures. Bottom-up procedure volume estimates and top-down market sizing converge across the analysis window.
Assumptions held fixed include regulatory pathway timelines for polymer degradation documentation and MDR material traceability mandate enforcement intensity. Variables modeled span procedure type complexity, material biocompatibility tier, pediatric versus adult patient segmentation, and end-user facility category. CAGRs derive from procedure volume elasticity to reimbursement rate changes and technology adoption S-curves for 3D surgical planning software. Forecast inputs incorporate cartilage calcification age thresholds limiting graft viability and ASC reimbursement rate differentials favoring outpatient protocols.
Practitioners should monitor FDA polymer degradation guidance revisions, EU MDR notified body capacity expansion announcements, and Indian medical tourism infrastructure investment levels for early signals requiring forecast reassessment. Cross-checking against CMS procedure volume benchmarks and EU hospital discharge registry data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Epiglottitis Treatment Market