
 Endoscope Flushing Pumps Market | 2026-2036
Endoscope Flushing Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Flushing Pumps Market Analysis
Equipment leasing and pay-per-use service contracts is reconfiguring capital deployment across the endoscope flushing pumps landscape, allowing mid-sized surgical centers to access automated systems without upfront purchase. Olympus America leverages its installed base of endoscopy towers to bundle flushing pump placements. STERIS Corporation sustains competitive position through captive service revenue tied to reprocessing chemistry. Medivators anchors its presence with specialized fluid delivery systems designed for high-throughput endoscopy suites.
Endoscope flushing pumps are electromechanical devices that deliver pressurized fluid through endoscopic channels to remove organic debris and biofilm prior to high-level disinfection or sterilization, typically operating at flow rates between 0.5 and 3.0 liters per minute with integrated pressure monitoring to prevent luminal damage. Electric flushing pumps dominate procurement budgets in hospitals due to throughput requirements and labor cost reduction, while portable flushing units represent the fastest-growing configuration as point-of-care diagnostics expand beyond centralized reprocessing departments. Pulsed flow technology commands margin premiums by improving debris dislodgment in complex instrument geometries compared to continuous flow alternatives.
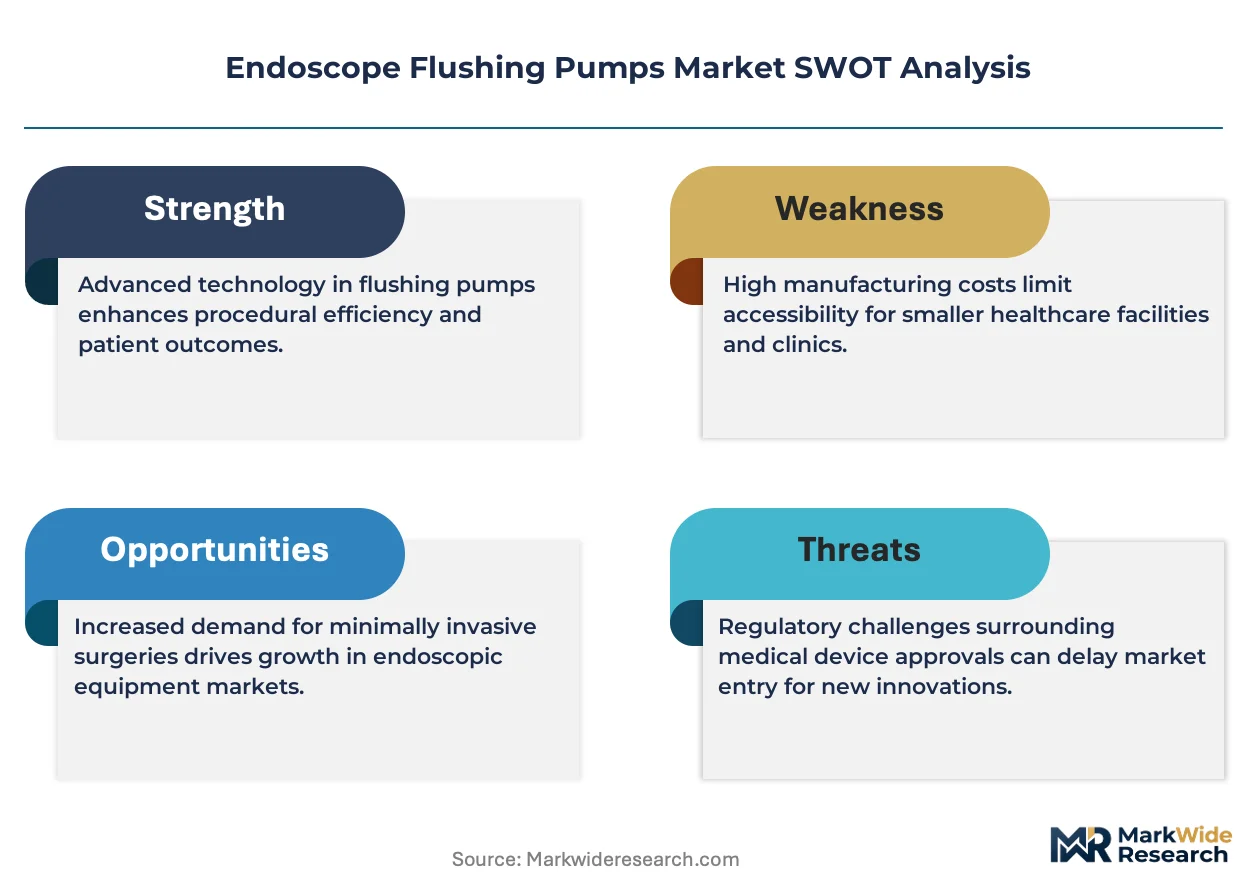
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking market access in the United States and European Union. ISO 15883 standards for washer-disinfectors indirectly influence flushing pump design specifications by establishing cleaning efficacy benchmarks that reprocessing workflows must achieve. Stakeholders should monitor how reimbursement shifts toward outpatient procedures reshape the customer mix between hospital central sterile supply departments and clinic-based point-of-use reprocessing.
Market Dynamics
Automated reprocessing workflows are compressing labor-dependent cleaning protocols across hospital systems, forcing capital equipment decisions that prioritize throughput velocity over standalone unit economics. This structural shift elevates flushing pump specifications from accessory status to workflow-critical infrastructure.
Growth Catalysts
- Ambulatory surgical center expansion:United States outpatient facilities are deploying compact flushing systems to support same-day endoscopy volume growth without centralized sterile processing departments.
- EU MDR sterility assurance mandates:Tighter validation requirements for reusable medical devices are compelling hospitals to upgrade from manual channel irrigation to pressure-monitored automated flushing.
- Pulsed flow technology:Advanced fluid dynamics engineering improves biofilm dislodgment in complex duodenoscope geometries, commanding adoption in high-risk procedure settings.
Market Restraints
- Stainless steel and precision polymer input costs:Pump chamber materials face commodity price volatility that compresses manufacturer margins without corresponding pricing power.
- German equipment supply concentration:Critical electromechanical components for high-throughput systems originate from a narrow supplier base in Baden-Württemberg industrial clusters.
- Single-use endoscope substitution:Disposable bronchoscope and cystoscope adoption in low-acuity settings threatens addressable market for reusable instrument reprocessing equipment.
Strategic Opportunities
- India diagnostic center buildout:Tier-2 and Tier-3 cities lack centralized endoscope reprocessing infrastructure, creating first-mover advantage for portable flushing unit deployment.
- Integrated data logging systems:Convergence of pressure sensors with blockchain-verified cycle documentation enables compliance automation for Joint Commission and DNV audits.
- Pay-per-use service contracts:Equipment-as-a-service models reduce capital barriers for mid-sized surgical centers in Brazil and Mexico.
Industry Challenges
- Biomedical technician specialization gaps:Servicing electromechanical flushing systems requires expertise spanning fluid dynamics, pressure calibration, and endoscope channel anatomy that training programs have not scaled to match installed base growth.
- FDA 510(k) clearance timelines:Novel pressure-monitoring algorithms trigger software-as-medical-device review pathways that extend time-to-market by 8-14 months versus hardware-only submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Flushing Pumps Market |
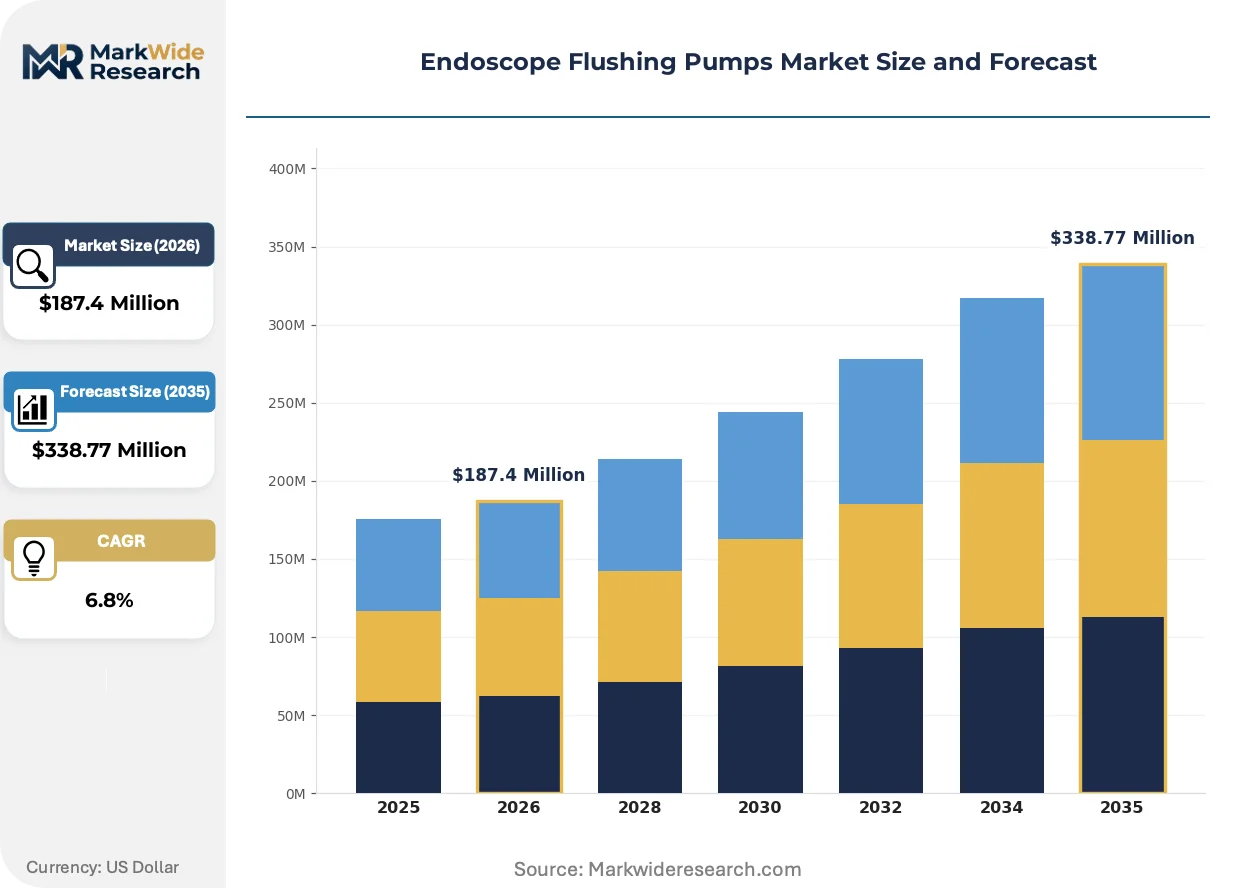
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Flushing Pumps, Manual Flushing Pumps, Portable Flushing Pumps, Wall-Mounted Flushing Pumps End User: Hospitals, Clinics, Surgical Centers, Diagnostic Laboratories Technology: Automated Flushing, Continuous Flow, Pulsed Flow, Pressure Control Application: Gastroenterology, Urology, Respiratory, Orthopedics |
| Companies Covered | Olympus America, STERIS Corporation, Medivators, Hoya, Smith & Nephew, Stryker, Karl Storz, B.Braun, Fujifilm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Flushing Pumps Market Emerging Trajectories
Connected device architectures and predictive maintenance algorithms are transforming flushing pumps from passive fluid delivery tools into intelligent workflow nodes that anticipate reprocessing bottlenecks before they disrupt surgical schedules.
Pressure-sensor arrays with real-time luminal resistance mapping are digitizing channel patency assessment, replacing visual inspection protocols. Academic medical centers in Massachusetts and North Carolina are piloting these systems for complex duodenoscope reprocessing. The technology is digitizing compliance documentation by generating machine-readable validation records that integrate directly with electronic health record systems.
The EU Medical Device Regulation's Unique Device Identification requirements are forcing hardware redesigns to accommodate embedded serialization and traceability modules. Manufacturers serving European hospitals must revalidate entire product lines to maintain CE marking. High-throughput endoscopy suites in France and the Netherlands face the steepest compliance costs due to multi-manufacturer instrument fleets requiring interoperable tracking systems.
Service contract unbundling is fragmenting traditional capital-plus-maintenance purchasing into discrete subscription tiers for software updates, consumables, and field service. Hospital procurement departments in Texas and Florida are driving this shift to align operational expenditures with case volume fluctuations. Ambulatory surgery centers show the highest uptake of unbundled arrangements where per-procedure costing visibility supports value-based care contracting.
Endoscope Flushing Pumps Market Segmentation
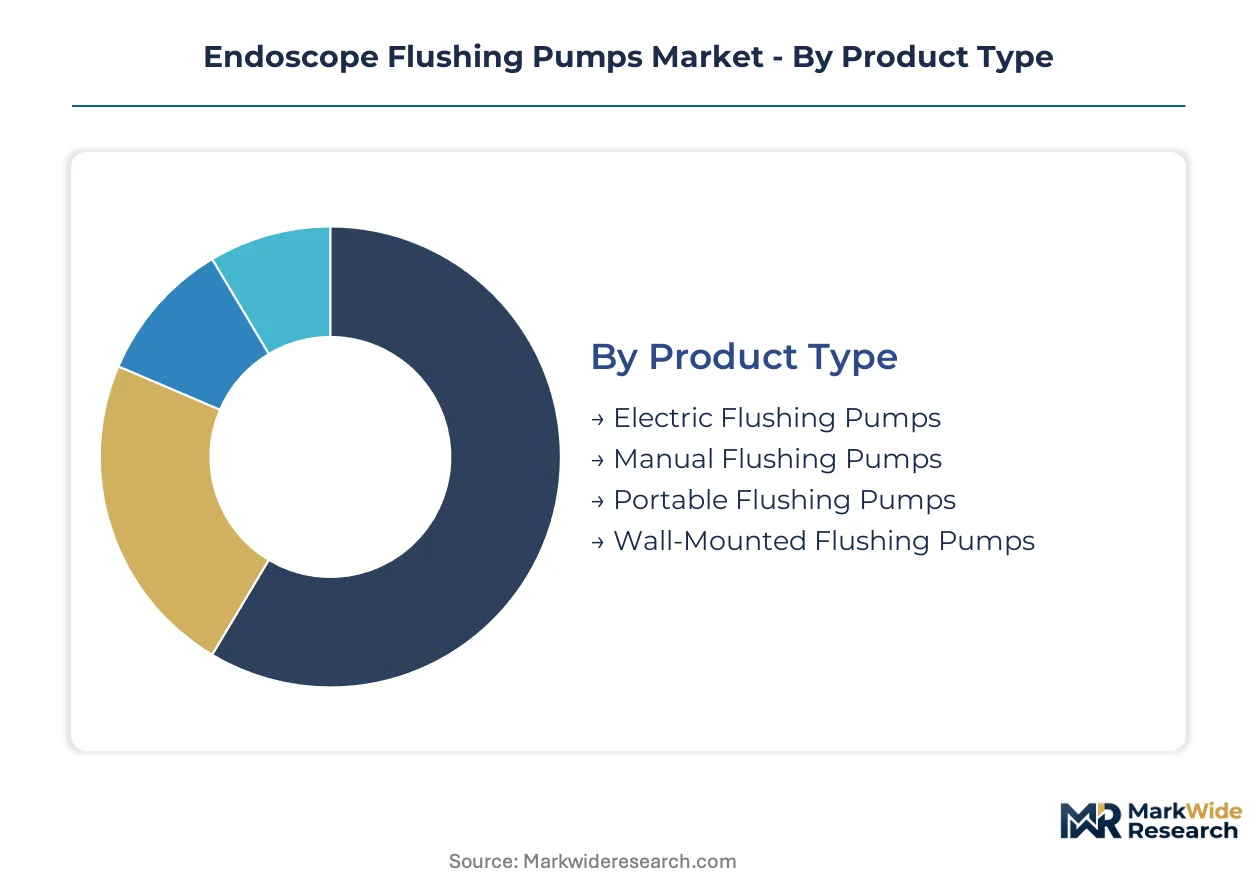
Endoscope flushing pumps serve divergent throughput requirements across centralized hospital sterile processing departments and distributed point-of-care settings. Segmentation reveals how capital intensity, labor availability, and procedure volume reshape equipment specifications and replacement cycles.
Product Type:
Cycle times vary dramatically: electric systems run continuous reprocessing shifts while portable units face sporadic deployment in field settings.
- Electric Flushing Pumps:Electromechanical systems deliver pressurized fluid at 0.5-3.0 liters per minute with integrated pressure monitoring to prevent luminal damage. Hospital central sterile supply departments in Germany specify these for automated reprocessing workflows that compress labor-dependent cleaning protocols.
- Portable Flushing Pumps:Battery-powered or lightweight AC units enable point-of-use reprocessing outside centralized departments. Ambulatory surgical centers in Texas and Florida deploy these to support same-day endoscopy volume growth without dedicated sterile processing infrastructure.
- Manual Flushing Pumps:Hand-operated syringe-style devices provide basic channel irrigation for low-volume settings. Rural clinics in India rely on these where electricity reliability and technician training gaps constrain automated system adoption.
- Wall-Mounted Flushing Pumps:Fixed-installation units integrate with endoscopy tower configurations. High-throughput suites in France favor these for space optimization and permanent plumbing connections.
Electric flushing pumps dominate installed base. Portable flushing pumps are where expansion concentrates.
End User:
Procurement authority and budget structures differ sharply: hospitals consolidate capital decisions while surgical centers prioritize per-procedure costing visibility.
- Hospitals:Central sterile supply departments command capital budgets for high-throughput electromechanical systems. EU MDR sterility assurance mandates are compelling German hospitals to upgrade from manual channel irrigation to pressure-monitored automated flushing.
- Surgical Centers:Outpatient facilities prioritize compact footprint and rapid cycle turnaround. United States ambulatory surgery centers show the highest uptake of unbundled service contracts where per-procedure costing supports value-based care contracting.
- Clinics:Limited procedure volumes favor lower-capital configurations. Tier-2 and Tier-3 cities in India lack centralized reprocessing infrastructure, creating first-mover advantage for portable unit deployment.
- Diagnostic Laboratories:Specialized endoscopy services in academic medical centers drive demand for advanced pressure-sensor arrays. Massachusetts and North Carolina facilities pilot real-time luminal resistance mapping for complex duodenoscope reprocessing.
Hospitals anchor capital equipment procurement. Surgical centers are climbing the fastest in unit volume.
Technology:
Margin structures stratify by validation burden: automated systems carry software-as-medical-device compliance costs while continuous flow alternatives compete on unit economics.
- Automated Flushing:Programmable cycle control with integrated data logging for compliance documentation. Blockchain-verified cycle documentation enables Joint Commission and DNV audit automation.
- Pulsed Flow:Intermittent pressure waves improve biofilm dislodgment in complex instrument geometries. Advanced fluid dynamics engineering commands adoption in high-risk duodenoscope procedure settings.
- Continuous Flow:Steady fluid delivery at fixed pressure parameters. Standard configurations face commodity pricing pressure as manufacturers compete on unit economics.
- Pressure Control:Real-time sensor feedback adjusts flow to prevent endoscope channel damage. FDA 510(k) clearance timelines extend by 8-14 months for novel pressure-monitoring algorithms versus hardware-only submissions.
Automated flushing commands premium positioning. Pulsed flow is gaining share fastest through clinical outcomes differentiation.
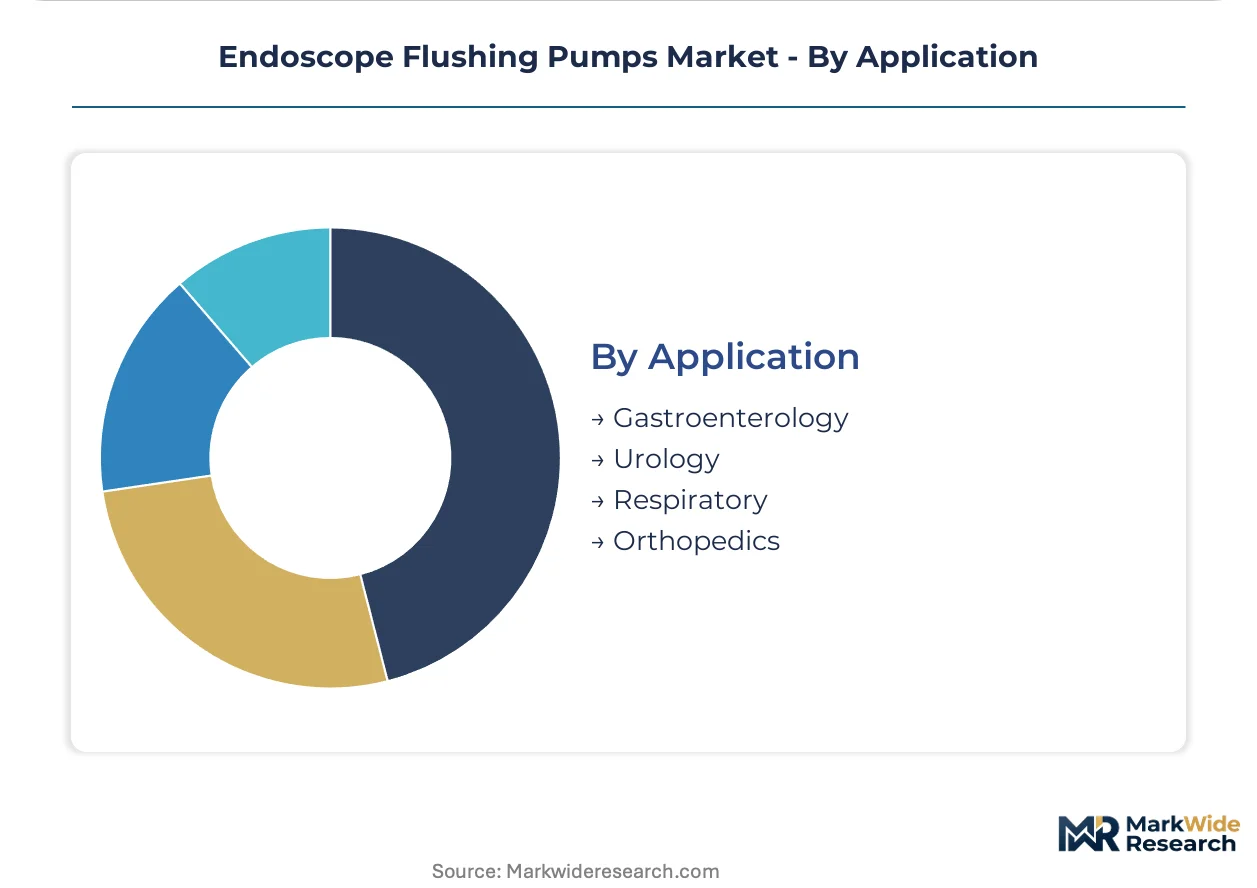
Application:
Procedure complexity and infection risk profiles determine specification intensity: gastrointestinal endoscopy drives volume while respiratory applications face single-use substitution threats.
- Gastroenterology:Colonoscopy and upper endoscopy procedures generate the highest reprocessing volumes. Complex duodenoscope geometries in ERCP procedures demand pulsed flow technology for effective biofilm removal.
- Urology:Cystoscope reprocessing requires specialized fluid compatibility with rigid instrument channels. Outpatient urology clinics in Brazil and Mexico favor pay-per-use service contracts to reduce capital barriers.
- Respiratory:Bronchoscope reprocessing faces displacement pressure from single-use alternatives. Low-acuity settings increasingly adopt disposable instruments, threatening addressable market for reusable equipment.
- Orthopedics:Arthroscope flushing demands higher pressure tolerance for rigid instrument channels. Sports medicine centers specify dedicated systems separate from flexible endoscope workflows.
Gastroenterology anchors procedure volume. Urology is where portable system deployment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in endoscope flushing pumps tilt toward net imports in emerging diagnostic markets while established manufacturing clusters in Germany and the United States supply premium electromechanical systems. Trade patterns concentrate high-value pump assemblies in Baden-Württemberg industrial zones and Massachusetts medical device corridors.
United States
Ambulatory surgical centers in Texas and Florida drive compact flushing system procurement for same-day endoscopy volume expansion. FDA 510(k) clearance pathways shape product development timelines for pressure-monitoring algorithms. Boston-area academic medical centers pilot real-time luminal resistance mapping for complex duodenoscope reprocessing validation.
Germany
Hospital systems automate reprocessing workflows with pressure-monitored flushing systems to comply with sterility assurance mandates. EU Medical Device Regulation tightens validation requirements for reusable medical devices across Baden-Württemberg manufacturing clusters. Stuttgart industrial zones supply critical electromechanical components for high-throughput pump configurations.
India
Tier-2 and Tier-3 diagnostic centers lack centralized reprocessing infrastructure, creating deployment opportunities for portable flushing units. CDSCO medical device registration requirements govern market entry for imported electromechanical systems. Maharashtra and Karnataka urban corridors concentrate first-mover installations for point-of-care endoscopy services.
Brazil
Mid-sized surgical centers favor pay-per-use service contracts to reduce capital barriers for automated flushing adoption. ANVISA medical device regulations establish clinical evidence requirements for pressure-monitored systems. São Paulo metropolitan hospitals anchor procurement volume for high-throughput reprocessing workflows.
Japan
PMDA regulatory frameworks emphasize software-as-medical-device review for connected flushing pump architectures. Kanto and Kansai regions concentrate demand from high-volume endoscopy suites in Tokyo and Osaka academic centers. Domestic manufacturers leverage precision polymer supply chains for pump chamber component fabrication.
Endoscope Flushing Pumps Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision electromechanical assemblies. Market structure consolidates around endoscopy tower manufacturers bundling flushing pumps with installed base leverage, while independent reprocessing equipment vendors compete on service contract unbundling. Three archetypes dominate: integrated endoscopy platform vendors, standalone reprocessing specialists, and precision fluid delivery component suppliers. Competitive moves center on captive service revenue attachment and pay-per-use contract proliferation.
Among platform-integrated vendors, Olympus America and STERIS Corporation exemplify the bundling archetype, leveraging installed tower bases for pump placement pull-through. Medivators occupies a position within the standalone reprocessing specialist tier, anchoring presence through fluid delivery system specialization. These three companies represent the competitive spectrum from comprehensive platform integration to focused reprocessing workflow optimization.
| Leading Market Players |
|---|
| Olympus America |
| STERIS Corporation |
| Medivators |
| Hoya |
| Smith & Nephew |
| Stryker |
| Karl Storz |
| B.Braun |
| Fujifilm |
| Others |
Supply Flow & Price Mechanics
Overcapacity in precision polymer pump chamber fabrication across Baden-Württemberg industrial zones is compressing supplier pricing power while simultaneously elevating buyer leverage for multi-year service contract negotiations. German contract manufacturers now accept extended payment terms to maintain utilization rates, reshaping procurement economics for hospital systems consolidating reprocessing equipment purchases.
Pricing Analysis
Hospital central sterile supply departments anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by pressure-monitoring algorithm sophistication and ISO 15883 validation documentation completeness. Cost compression in economy-tier portable units is intensifying because Brazilian and Mexican mid-sized surgical centers negotiate per-procedure costing visibility. Ambulatory surgery centers show highest price sensitivity due to case volume volatility, while academic medical centers in Massachusetts and North Carolina prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Precision electromechanical component contract manufacturers in Stuttgart industrial zones and Massachusetts medical device corridors hold dominant capacity for high-throughput pump assemblies. Raw material dependencies center on medical-grade stainless steel from German foundries, precision polymers from Japanese suppliers, and pressure sensor arrays from South Korean fabricators. Single-source vulnerability concentrates in Baden-Württemberg for critical pump chamber subassemblies. Distribution runs through endoscopy tower OEM direct sales forces and independent reprocessing equipment distributors serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endoscope flushing pumps market is exiting a capital expenditure contraction cycle as ambulatory surgical center expansion in Texas and Florida restarts equipment procurement programs deferred during outpatient procedure volume declines.
For Market Incumbents: Build switching-cost moats through integrated data logging systems that embed blockchain-verified cycle documentation into hospital electronic health record architectures. Deepen backward integration into precision polymer pump chamber production to offset stainless steel commodity volatility. Defend against single-use endoscope substitution threats by emphasizing total cost-of-ownership advantages for reusable instrument reprocessing in high-volume gastroenterology suites. For New Entrants and Emerging Players: Tier-2 and Tier-3 diagnostic centers in India represent the most penetrable white-space opportunity, lacking centralized reprocessing infrastructure and technician training depth for automated system deployment. Target pay-per-use service contract models to bypass capital budget constraints among Brazilian mid-sized surgical centers. Pursue regulatory fast-track pathways through CDSCO medical device registration for portable flushing units designed for unreliable electricity environments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable flushing pump sub-segments as battery technology commoditization reduces electromechanical component costs. Five-to-ten year viability favors platform-integrated vendors with captive installed base leverage over standalone reprocessing specialists facing bundling pressure. Monitor FDA 510(k) clearance timeline extensions for novel pressure-monitoring algorithms as an inflection signal for software-as-medical-device compliance cost escalation. Quarterly review of ambulatory surgery center bankruptcy filings and GPO contract renewal rates is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR sterility assurance mandates force hardware redesigns for embedded serialization modules in European hospital systems. |
| Hospital System Partnership | Olympus America leverages installed endoscopy tower base to bundle flushing pump placements with service contract attachments. |
| Software Companion Development | Real-time luminal resistance mapping digitizes channel patency assessment for complex duodenoscope reprocessing validation. |
| Reimbursement Strategy | Shift toward outpatient procedure reimbursement reshapes customer mix between hospital sterile supply and clinic point-of-use reprocessing. |
| Backward Integration | STERIS Corporation sustains margins through captive service revenue tied to reprocessing chemistry and consumables supply. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital central sterile supply managers, biomedical engineering directors, ambulatory surgery center procurement officers, and GPO contracts specialists, and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and ISO 15883 washer-disinfector standard revision records. Bottom-up demand modeling from individual facility equipment replacement cycles was triangulated against top-down market sizing from manufacturer shipment disclosures.
Demand-supply balance dynamics across the analysis window were assessed through procedure volume projections by endoscopy type, capital expenditure survey data from healthcare facility administrators, and regulatory compliance cost modeling for sterility assurance mandates. Segmentation dimensions included product configuration, end-user facility type, pressure control technology tier, and clinical application area. CAGRs were derived from logistic adoption curves fitted to automated reprocessing workflow penetration rates, with inputs from pulsed flow technology clinical efficacy studies and single-use endoscope substitution threat assessments.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by precision polymer component suppliers or accelerated single-use endoscope adoption by low-acuity respiratory clinics would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) submission backlogs, EU MDR notified body capacity constraints, and ambulatory surgery center construction permit issuances is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Catheter Coatings Market
Medical Devices
Lactation Massager Market
Medical Devices
Global Dermatome Device Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Asthma Device Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Lyophilized Injectable Market