
 Clean Label Starch Market | 2026-2036
Clean Label Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Starch Market Intelligence
The EU Green Deal's Farm to Fork strategy is decoupling food texturizing properties from reliance on chemically modified additives, accelerating a shift toward physically processed ingredients. In this environment, Ingredion Incorporated leverages its extensive portfolio of non-GMO corn and tapioca starches to serve multinational food brands. Cargill Incorporated competes on its vast agricultural supply chain and large-scale production capabilities for native starches. Meanwhile, Tate & Lyle PLC differentiates through its specialization in functional clean label starches for challenging applications like low-pH sauces.
Clean label starches are functional carbohydrates sourced from corn, tapioca, potato, or rice, processed using physical or enzymatic methods instead of chemical modification. This ensures they can be listed on packaging with simple, consumer-friendly names. Their primary purpose is to provide viscosity, texture, and stability in food products. While native starch constitutes a significant volume segment, physically modified starches command higher price points due to their enhanced process tolerance. Demand from the bakery and sauces & dressings applications is particularly strong, requiring starches that withstand heat and shear.
Regulatory frameworks are central to defining market boundaries, with the US Food and Drug Administration (FDA) scrutinizing ingredient labeling claims. In parallel, the European Food Safety Authority (EFSA) provides opinions that influence the classification of food additives across the European Union. Compliance with China's GB standards is also essential for market access. Suppliers must navigate these varied definitions of "natural" and "clean" to formulate products that meet both legal requirements and consumer expectations across key markets.
Market Dynamics
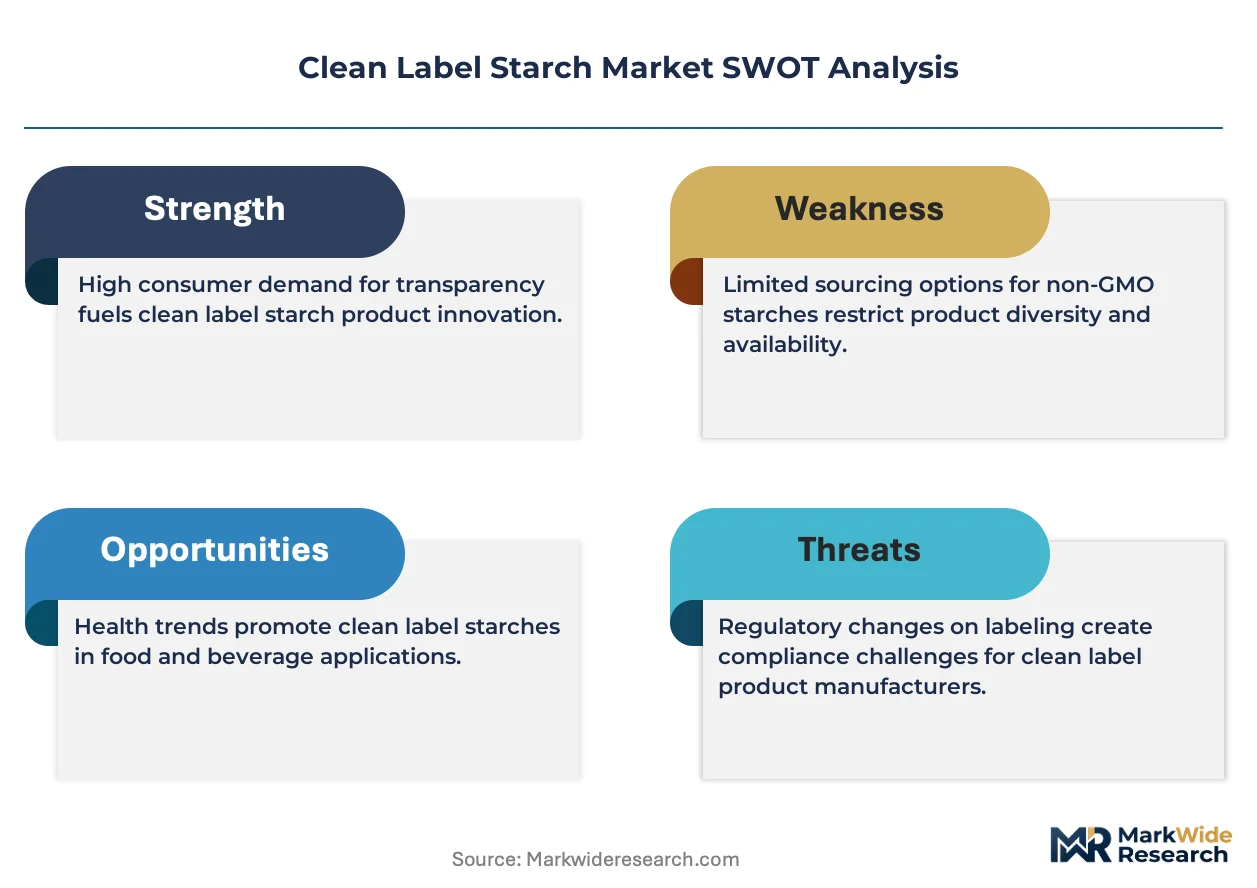
The central force shaping the market is the decoupling of food texture from chemical modification, driven by consumer demand for transparent ingredient lists. This shift forces manufacturers to adopt physical processing methods to achieve functionality while maintaining a clean label, creating new value tiers based on processing complexity and performance.
Growth Catalysts
- Plant-Based Formulation:Demand from the rapidly expanding dairy alternatives and plant-based meat sectors requires starches for viscosity and mouthfeel without animal-derived ingredients.
- EU Regulatory Pressure:The EU Green Deal's Farm to Fork strategy encourages the reduction of chemical additives, creating a direct incentive for food manufacturers to switch to physically modified starches.
- Non-GMO Verification:Consumer and retailer pressure in the United States and Canada for non-GMO project verified labels drives demand for starches sourced from certified corn and tapioca supply chains.
Market Restraints
- Input Cost Volatility:Prices for raw materials like non-GMO corn, potato, and tapioca are subject to agricultural commodity cycles, weather events, and geopolitical factors, impacting production costs.
- Performance Gaps:Physically modified starches, while improving, do not always match the process tolerance, shear stability, or freeze-thaw performance of their chemically modified counterparts in extreme applications.
- Regulatory Fragmentation:Divergent definitions of "natural" and "clean label" between the US FDA, EU's EFSA, and China's GB standards create compliance complexities for multinational food brands.
Strategic Opportunities
- Geriatric and Medical Nutrition:Formulating texturally appropriate, easy-to-swallow foods for aging populations and patients with dysphagia represents a significant, underpenetrated application for functional clean label starches.
- Enzymatic Modification:Developing novel enzymes that can alter starch functionality without being classified as a chemical modification offers a pathway to higher performance while maintaining a simple ingredient label.
- Pet Food Humanization:Applying clean label texturizing and stabilization principles to premium pet foods, particularly wet foods and gravies, aligns with consumer trends in pet care.
Industry Challenges
- Sensory Profile Replication:A primary operational hurdle is achieving the identical mouthfeel, viscosity, and clarity of established chemically modified starches, which can require extensive reformulation and sensory panel testing.
- Supply Chain Traceability:Documenting and certifying a non-GMO, physically processed supply chain from farm to finished ingredient requires significant investment in tracking systems and auditing, adding cost and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Starch Market |
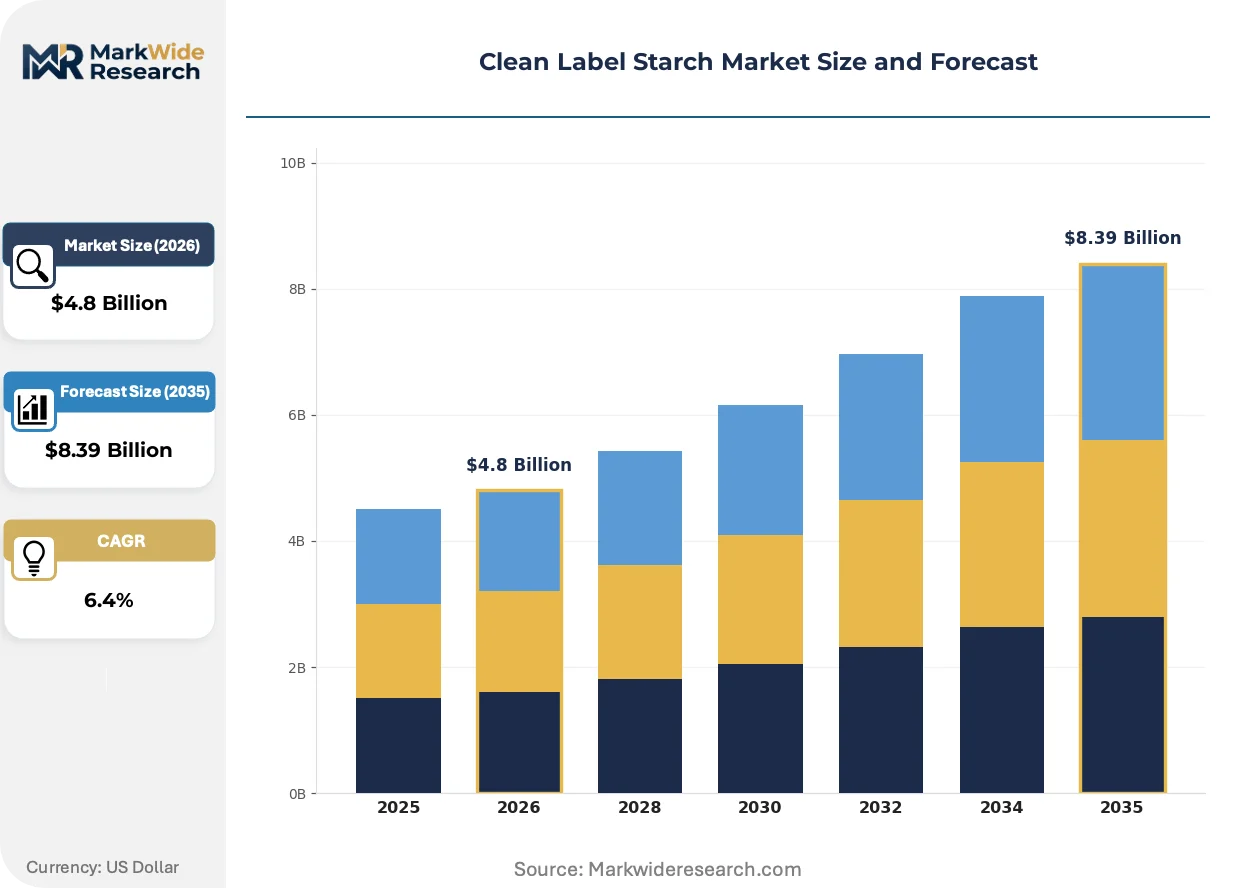
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Resistant Starch, Pregelatinized Starch, Oxidized Starch Application: Bakery, Confectionery, Meat Processing, Dairy Alternatives, Sauces & Dressings End User Industry: Food Manufacturing, Beverage Production, Cosmetics, Pharmaceuticals, Personal Care Packaging Type: Pouches, Bulk Bags, Paper Bags, Plastic Bags, Containerized Packaging |
| Companies Covered | Archer Daniels Midland Company, Emsland Group, Cargill Incorporated, AGRANA Beteiligungs-AG, Grain Processing Corporation, Ingredion Incorporated, Roquette Frères, Avebe U.A., Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Starch Market Strategic Shifts & Innovations
The convergence of food science and consumer marketing defines the current innovation cycle in clean label starches. Ingredient lists have become a primary branding tool, compelling suppliers to innovate on both functionality and the simplicity of their declaration on packaging.
Advanced physical modification methods, including thermal-inhibition and agglomeration, create starches with superior process tolerance. Food formulators in bakery and sauces are rapidly adopting these ingredients to replace chemical alternatives. This technology is integrating enhanced stability and texture directly into the starch granule, reducing the need for complex multi-ingredient stabilizer systems.
Regulatory frameworks, particularly the EU Green Deal's Farm to Fork strategy, create tailwinds for non-chemically treated ingredients. The policy pressures manufacturers to reformulate products away from additives with E-numbers, including many chemically modified starches. The sauces and dressings segment in Europe is most affected, accelerating R&D into heat- and acid-stable physically modified starches.
Consumer purchasing behavior is shifting toward 'ingredient-first' evaluation, where short, simple ingredient lists act as a proxy for quality. This trend disrupts brand loyalty built on flavor alone, impacting both private label and established national brands. The shift is most pronounced within the baby food and plant-based dairy categories across North America and Western Europe.
Clean Label Starch Market Segmentation
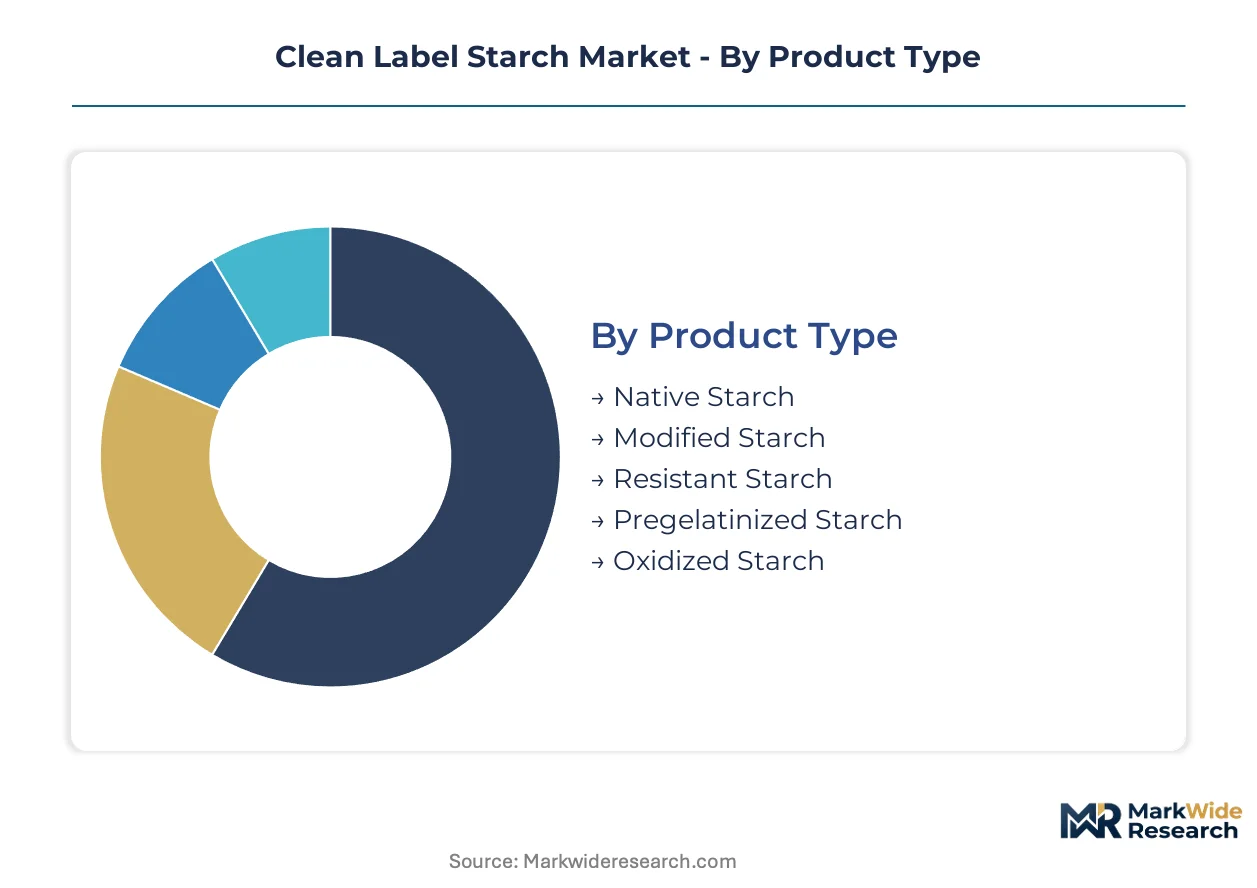
The clean label starch market's segmentation highlights the diverse functional requirements and end-user demands influencing product development and supply chain specialization. Understanding these distinct segments allows manufacturers to tailor ingredient solutions that meet specific performance criteria and regulatory expectations across global markets.
Product Type:
Manufacturing clean label starches by product type involves varying levels of capital investment, particularly for advanced modification techniques that enhance functionality.
- Native Starch:This category includes starches extracted directly from plant sources like corn, tapioca, or potato, undergoing minimal physical processing. Native starches provide basic thickening and texturizing properties, forming a foundational volume segment in many food applications.
- Modified Starch:These starches undergo physical or enzymatic treatments to enhance their functional properties, such as process tolerance, shear stability, or freeze-thaw resistance. Demand for physically modified starches is concentrating in sauces and dressings, driven by the need for robust performance in challenging formulations.
- Resistant Starch:This starch type resists digestion in the small intestine, functioning as a dietary fiber with prebiotic benefits. It is incorporated into foods for nutritional enhancement, particularly in baked goods and breakfast cereals.
- Pregelatinized Starch:This starch is pre-cooked and dried, allowing it to thicken instantly in cold water without heating. It finds use in convenience foods and instant mixes, offering rapid viscosity development.
- Oxidized Starch:Produced by treating native starch with oxidizing agents, this type offers improved clarity, reduced retrogradation, and enhanced film-forming properties. It is often utilized in confectionery and coatings for its smooth texture.
Native Starch absorbs the bulk of installed capacity; Modified Starch is expanding most quickly.
Application:
Clean label starch applications often dictate ingredient costs, with specialized uses demanding higher-performing, premium solutions for texture and stability.
- Dairy Alternatives:This rapidly expanding sector utilizes clean label starches to replicate the creamy mouthfeel and stability of traditional dairy products, including plant-based milks, yogurts, and cheeses. Formulators seek starches that provide viscosity and suspension without contributing off-flavors.
- Sauces & Dressings:These products require starches that can withstand high temperatures, shear forces, and low-pH environments while maintaining stable viscosity and texture. Demand is particularly strong for physically modified starches that prevent syneresis and improve shelf life.
- Bakery:Starches in bakery products improve texture, moisture retention, and crumb structure in items like breads, cakes, and pastries. They also contribute to extended shelf life and freeze-thaw stability.
- Confectionery:In confectionery, clean label starches provide gelling, thickening, and stabilizing functions for candies, gummies, and other sweet treats. They help control texture and prevent sugar crystallization.
- Meat Processing:Starches are used in meat processing for binding water, improving texture, and reducing cook loss in products like processed meats and plant-based meat alternatives. They contribute to juiciness and yield.
Demand for Bakery applications drives significant volume, while Dairy Alternatives showcases premiumization trends.
End User Industry:
The volume requirements for clean label starches vary significantly across end user industries, influencing production scale and supply chain dynamics.
- Food Manufacturing:This industry represents the largest consumer of clean label starches, integrating them into a vast array of products for texture, stability, and clean label formulation. Processors utilize starches across multiple categories to meet consumer demand for simple ingredient lists.
- Pharmaceuticals:Clean label starches serve as excipients, binders, disintegrants, and fillers in pharmaceutical formulations, particularly for medical nutrition products and capsules. The focus here is on purity, consistency, and specific functional properties for controlled release.
- Beverage Production:Starches are used in beverages to provide body, mouthfeel, and stability, especially in ready-to-drink formulations and plant-based drinks. They help prevent sedimentation and improve sensory attributes.
- Cosmetics:In cosmetics, starches function as thickeners, emulsifiers, and mattifying agents in creams, lotions, and powders. They offer a natural alternative to synthetic ingredients, aligning with clean beauty trends.
- Personal Care:Personal care products like shampoos, conditioners, and body washes incorporate starches for texture modification, emulsification, and skin-feel enhancement. They contribute to product stability and sensory appeal.
Food Manufacturing accounts for the largest share of consumption, with Pharmaceuticals exhibiting the strongest growth in specialized formulations.
Packaging Type:
Different customer types in the clean label starch market prefer specific packaging formats, impacting logistics and handling efficiencies.
- Bulk Bags:These large, flexible containers, often holding 500-1000 kg, are preferred by large-scale food manufacturers and industrial clients for cost-effective transportation and high-volume storage. They optimize supply chain logistics for major processing facilities.
- Pouches:Smaller, flexible packaging formats like pouches offer convenience and portion control for specialized ingredients or smaller batch productions. They are gaining traction for premium, high-value clean label starch variants.
- Paper Bags:Traditional paper bags, typically 20-25 kg, remain a common packaging choice for mid-sized manufacturers and distributors. They offer a balance of cost-effectiveness and ease of handling for various applications.
- Plastic Bags:Similar to paper bags in size, plastic bags provide enhanced moisture barrier properties and durability, suitable for environments where humidity control is critical. They are used for a range of clean label starch products.
- Containerized Packaging:This refers to large, rigid containers or drums used for very high-volume shipments, often for international trade or dedicated supply lines. It provides robust protection and efficient intermodal transport.
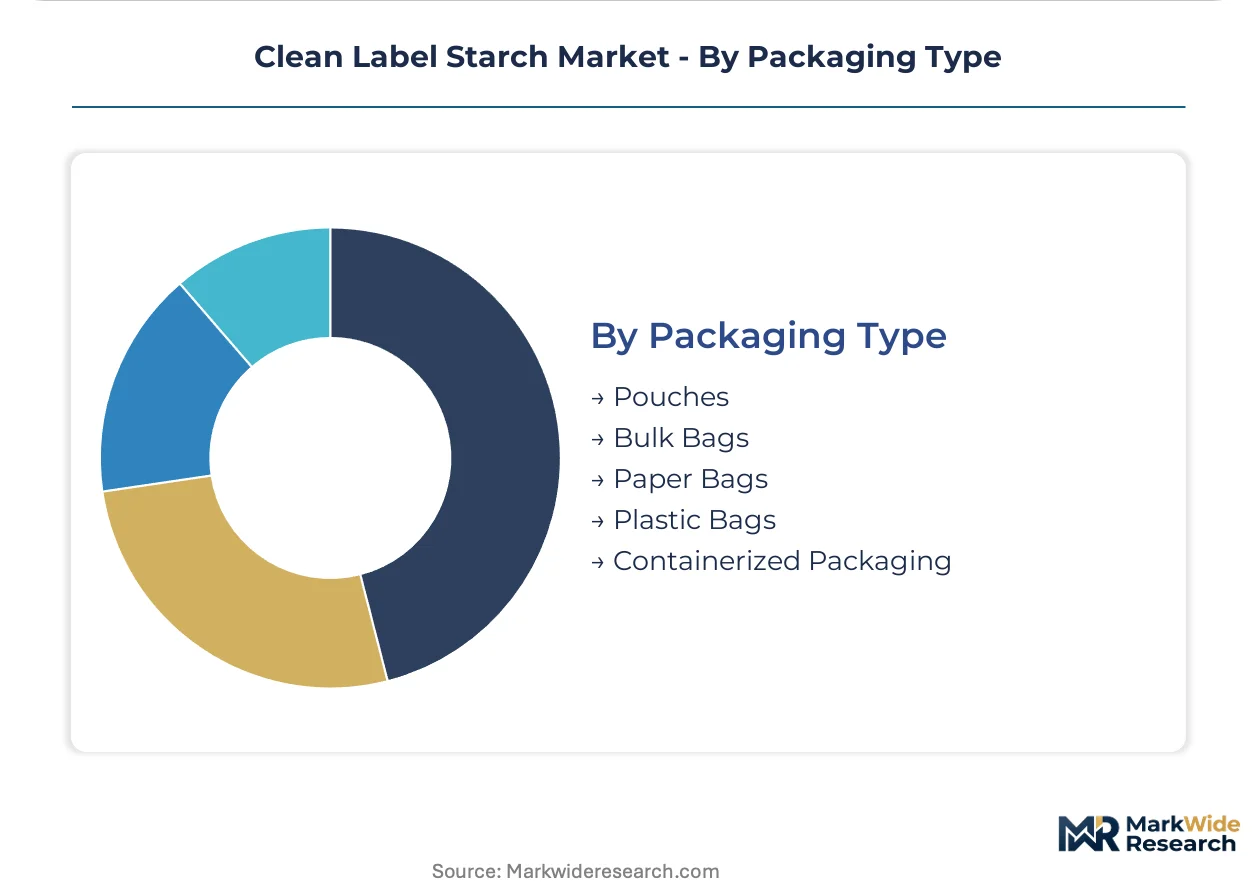
Bulk Bags remain the dominant packaging format for industrial clients; Pouches are gaining traction in specialized, smaller-batch applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturing hubs like Chicago and Frankfurt drive significant demand for clean label starches. These centers leverage advanced processing capabilities to meet consumer expectations for transparent ingredient lists. The market growth reflects a global shift towards healthier and more natural food formulations.
United States
Consumer demand for non-GMO verification and plant-based foods fuels clean label starch adoption in the United States. The US FDA scrutinizes ingredient labeling claims, influencing product development. California's food technology sector, particularly around Silicon Valley, innovates with these starches for new product launches.
Germany
The bakery and sauces & dressings sectors in Germany seek clean label starches for robust performance. EFSA opinions strongly influence ingredient classification across the European Union. North Rhine-Westphalia, with its dense food processing industry, sees high demand for physically modified starches.
China
Rapid expansion of processed food categories, alongside rising health awareness, boosts clean label starch consumption in China. Compliance with China's GB standards is essential for market entry and product acceptance. The Yangtze River Delta region, a major food manufacturing hub, integrates these ingredients into diverse product lines.
India
Growing demand from the dairy alternatives and bakery segments drives clean label starch usage in India. The Food Safety and Standards Authority of India (FSSAI) regulates food additives and labeling. Maharashtra, home to numerous food processing zones, experiences heightened adoption of functional starches.
France
The EU Green Deal's Farm to Fork strategy directly influences clean label ingredient adoption in France. EFSA guidelines encourage the reduction of chemical additives, accelerating the shift. Île-de-France, a center for food innovation, sees significant R&D into heat- and acid-stable physically modified starches.
Clean Label Starch Market Key Industry Players
The competitive structure tilts toward a tiered landscape, balancing large-scale ingredient suppliers with specialized clean label starch innovators. Major players often operate diversified portfolios, spanning various food and industrial applications. Strategic archetypes include global agricultural processors, dedicated functional ingredient providers, and regional niche specialists. Portfolio diversification and capacity expansion represent dominant competitive moves among these firms.
At the scale-driven end, Cargill Incorporated leverages its vast agricultural supply chain and production capabilities for native starches. Ingredion Incorporated exemplifies a global diversified ingredient player, offering an extensive portfolio of non-GMO corn and tapioca starches. Tate & Lyle PLC sits within the specialized functional starch providers, differentiating through its focus on challenging applications like low-pH sauces.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Emsland Group |
| Cargill Incorporated |
| AGRANA Beteiligungs-AG |
| Grain Processing Corporation |
| Ingredion Incorporated |
| Roquette Frères |
| Avebe U.A. |
| Tate & Lyle PLC |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material sourcing anchors the supply position for major clean label starch producers, directly influencing their pricing power and ability to manage input cost volatility. This strategic control allows for more stable offerings in a fluctuating commodity market.
Pricing Analysis
Performance-based pricing anchors the clean label starch market, particularly for specialized physically modified variants. Pricing stratifies across premium, standard, and economy tiers based on functionality like process tolerance and non-GMO certification. Pricing softness stems from input cost volatility in raw materials such as corn and tapioca. Food manufacturing clients focused on high volume exhibit higher price sensitivity compared to specialized medical nutrition producers.
Supply Chain Analysis
Dual-sourcing requirements for critical ingredients drive complexity within the clean label starch supply chain. Geographic supply concentrates in key agricultural regions like the United States for corn and Southeast Asia for tapioca. Raw material dependencies on these agricultural commodities create a structural risk of commodity price volatility. Distribution runs through a mix of direct sales to large food manufacturers and specialized ingredient distributors for smaller clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clean label starch market functions as a cost-of-compliance story, where adherence to regulations like the EU Green Deal's Farm to Fork strategy creates a significant barrier-to-entry moat for compliant ingredient players. This regulatory environment favors those capable of supplying physically processed alternatives.
For Market Incumbents:
To counter performance gaps in physically modified starches compared to chemical alternatives, incumbents must invest heavily in advanced enzymatic modification R&D. Diversifying raw material sourcing beyond corn and tapioca also reduces dependency on single commodity cycles. Strategic capacity additions in non-GMO certified supply chains can solidify market position and meet increasing demand.
For New Entrants and Emerging Players:
Specialty ingredient distributors offer new entrants a rapid pathway to market penetration, particularly for innovative clean label starch solutions. Targeting underpenetrated applications like geriatric and medical nutrition provides white-space opportunities. A co-development go-to-market angle with food manufacturers can showcase functionality and secure early adoption.
For Investors and Strategic Acquirers:
Exit pathways concentrate in acquisition by large, diversified ingredient players seeking to expand their clean label portfolios over the long term. Identifying specialized functional starch innovators with proprietary enzymatic modification technologies represents a prime acquisition target archetype. The signal to watch is the rapid adoption rate of these novel starches in challenging low-pH or high-shear applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Non-GMO Tapioca Sourcing | Ensures a stable, certified supply of a key raw material for multinational food brands. |
| R&D in Enzymatic Starch Modification | Develops next-generation clean label starches with enhanced process tolerance and stability for challenging applications. |
| Strategic Partnership with Plant-Based Food Innovator | Accelerates market penetration in the rapidly expanding dairy alternatives and meat alternative sectors. |
| Investment in Advanced Physical Modification Technology | Enhances the functional performance of starches, meeting demand from bakery and sauces & dressings segments. |
| Certification for China's GB Standards Compliance | Unlocks market access and ensures product acceptance within the large and growing Chinese processed food market. |
Research Approach
Multi-period observation of consumer demand for clean label products and regulatory shifts anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with food R&D directors, ingredient procurement managers, and regulatory affairs specialists. Secondary validation drew from regulatory body publications, food industry trade journals, and agricultural commodity reports. This approach ensured bottom-up insights were triangulated with top-down market dynamics.
The segment-weighting approach allocated market share across product type, application, end user industry, and regional regulatory compliance. The analytical framework modeled market evolution over the projection horizon, with CAGRs derived from historical growth trends and anticipated shifts. Key industry-specific forecast inputs included plant-based food growth rates and investment in physical modification technology.
Caveats apply where major shifts in agricultural commodity prices or new regulatory interpretations of "clean label" could materially shift the outlook. Forecasts reflect assumptions documented regarding technological advancements and consumer behavior. Deviation in these underlying assumptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Isoamyl Laurate Market
Ingredients
Europe Malt Extract Market
Ingredients
Sodium Reduction Ingredients Market
Ingredients
Sodium Alginate Market
Ingredients
Potato Granules Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Soy Lecithin Market
Ingredients
Modified Flour Market
Ingredients
North America Potato Starch Market
Ingredients
Global Starch Derivatives Market
Ingredients
US Plant-Based Oils Market
Ingredients
Textured Soy Flour Market
Ingredients
China Corn Glucose Market
Ingredients
China Protein Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Caramel Ingredient Market