
 Asia-Pacific Specialty Food Ingredient Market | 2026-2036
Asia-Pacific Specialty Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Specialty Food Ingredient Market Outlook
Halal certification timelines under MUI Indonesia and JAKIM Malaysia is collapsing from eighteen months to under eight, forcing ingredient suppliers to pre-validate supply chains or lose shelf placement. Cargill leverages its integrated sweetener network across Thai cane belts to sustain volume commitments. Kerry Group anchors reformulation partnerships with ASEAN beverage brands seeking reduced-sugar profiles. ADM competes through its Singapore technical center, which controls regional application testing for emulsifier stability in tropical climates.
Specialty food ingredients comprise functionally active compounds—typically dosed at 0.01% to 5.0% by weight—including high-intensity sweeteners such as steviol glycosides with minimum 95% purity, lecithin-derived emulsifiers with HLB values tailored to oil-in-water systems, and cultured dextrose preservatives produced through controlled fermentation. Their primary purpose is to deliver precise sensory, shelf-life, or nutritional outcomes that commodity ingredients cannot replicate in processed foods. Sweeteners command the deepest margin pools as beverage manufacturers absorb premium pricing for heat-stable, non-caloric alternatives. Emulsifiers represent the fastest-growing category, driven by plant-based dairy analogues requiring lipid-protein stabilization. Preservatives face structural pressure from clean-label mandates, though buffered vinegar systems are gaining traction as replacement chemistry.
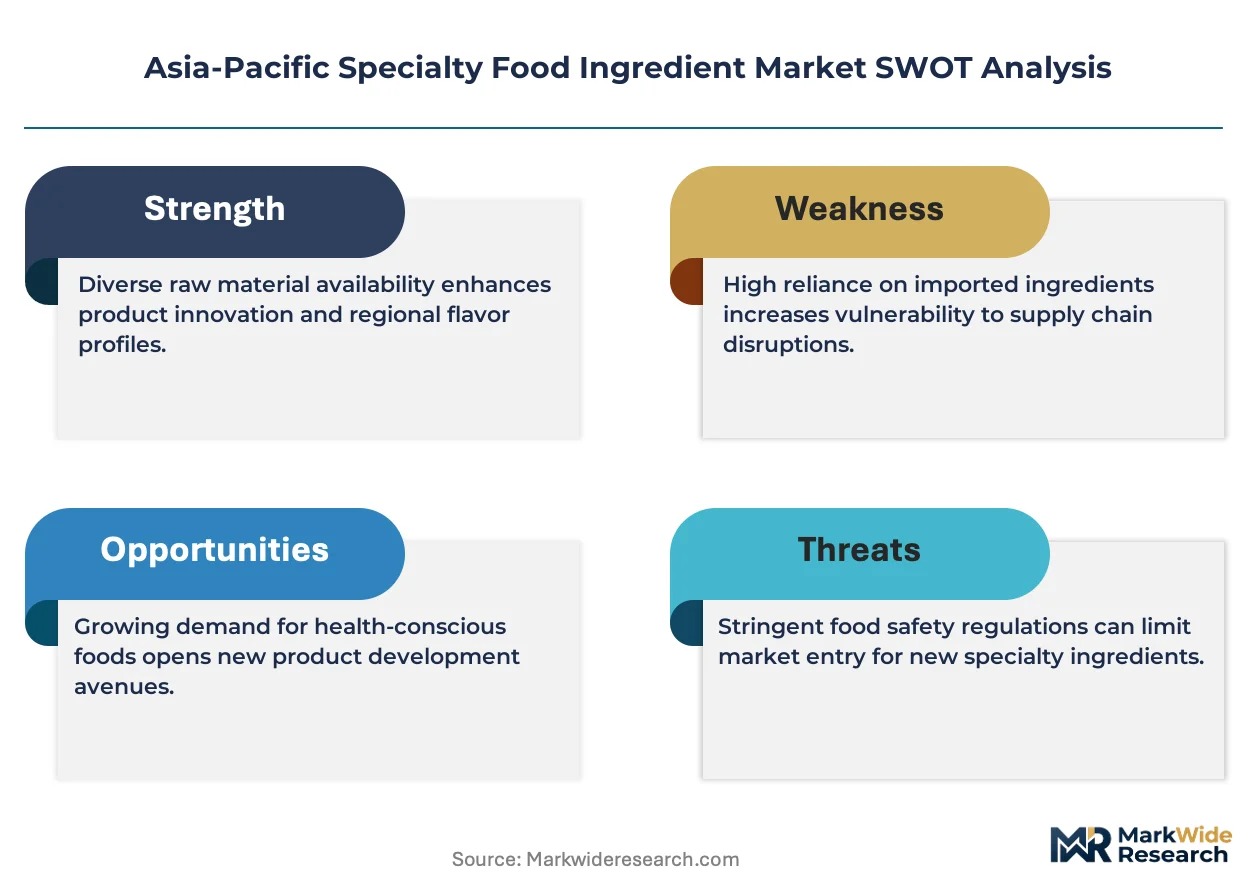
SAMR's GB 2760 food additive standard, India's FSSAI ingredient approval schedule, and JAKIM's halal integrity traceability requirements collectively determine which suppliers gain formulation access across the region's largest consumer bases. Compliance costs now function as a de facto market-access filter, advantaging multinationals with dedicated regulatory affairs teams in Shanghai and Mumbai. Stakeholders must monitor divergence between China's national standards and Codex Alimentarius guidelines, as alignment gaps create reformulation burdens for pan-Asian product lines.
Market Dynamics
Halal certification compression under MUI Indonesia and JAKIM Malaysia is collapsing approval timelines from eighteen months to under eight, forcing ingredient suppliers to pre-validate supply chains or forfeit shelf placement in Southeast Asia's largest Muslim consumer markets.
Growth Catalysts
- Plant-based dairy analogues:Thailand and Vietnam beverage formulators are accelerating clean-label emulsifier purchases to stabilize lipid-protein matrices in oat and coconut milk systems.
- SAMR's GB 2760 revisions:China's tightened additive approval pathways are advantaging pre-qualified suppliers with dedicated regulatory affairs teams in Shanghai.
- Processed dairy corridor demand:Maharashtra and Gujarat's concentrated dairy processing infrastructure is pulling high-intensity sweeteners and cultured preservatives at scale.
Market Restraints
- Cane belt supply concentration:Thai sugarcane region weather volatility exposes integrated sweetener networks to raw material disruption.
- Clean-label chemistry limitations:Buffered vinegar preservative systems face performance gaps against synthetic alternatives in ambient shelf-life extension.
- FSSAI approval bottlenecks:India's ingredient approval schedule creates 14-18 month regulatory friction for novel emulsifier entrants.
Strategic Opportunities
- Philippines halal export platform:Underpenetrated Muslim consumer goods manufacturing base offers white-space positioning for pre-certified ingredient suppliers.
- Reduced-sugar beverage mandates:ASEAN health ministry sugar reduction targets create regulatory tailwind for steviol glycoside and monk fruit extract applications.
- Singapore technical center model:Regional application testing hubs controlling tropical climate emulsifier stability validation represent distribution innovation anchor points.
Industry Challenges
- Halal traceability system integration:JAKIM's integrity requirements demand blockchain-enabled supply chain reconfiguration that legacy ERP systems cannot accommodate without middleware investment.
- Tropical climate formulation expertise:Shortage of food chemists trained in heat-stable emulsifier behavior above 35°C ambient conditions constrains regional R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Specialty Food Ingredient Market |
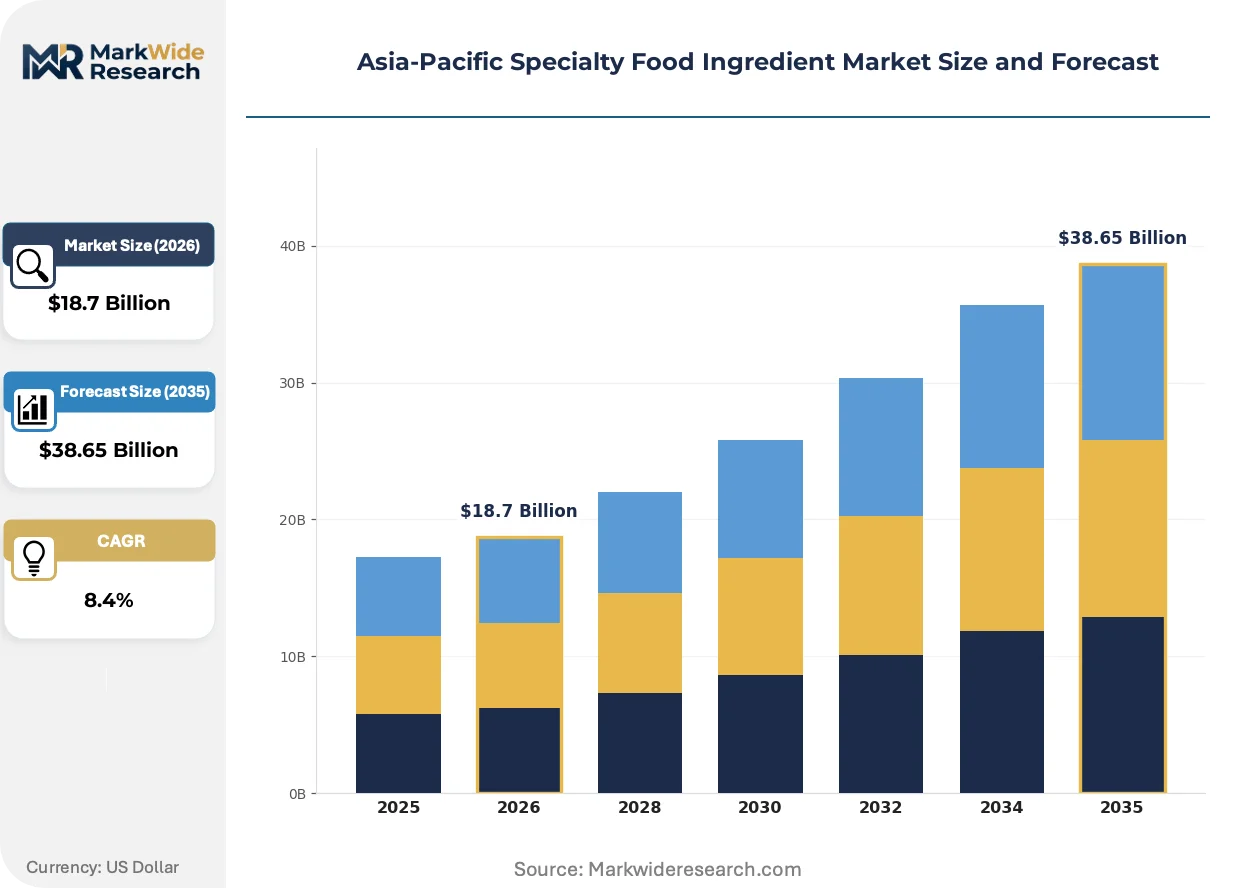
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Emulsifiers, Preservatives, Flavor Enhancers Application: Beverages, Dairy Products, Bakery, Sauces End User: Food Manufacturers, Restaurants, Retailers, Caterers Distribution Channel: Online Retail, Wholesalers, Supermarkets, Direct Sales |
| Companies Covered | ADM, Givaudan, Cargill, Roquette Frères, Ingredion, Kerry Group, International Flavors & Fragrances, CJ CheilJedang, Tate & Lyle, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Specialty Food Ingredient Market Strategic Shifts
Clean-label preservation chemistry is actively displacing legacy synthetic systems across ASEAN processed food manufacturing, while regulatory divergence between China's national standards and Codex Alimentarius guidelines forces parallel formulation tracks.
Micro-encapsulation technology for heat-sensitive bioactive compounds is fragmenting traditional spray-drying dominance in functional ingredient production. Thai and Vietnamese plant-based beverage manufacturers are adopting lipid-shell encapsulation at pilot scale to protect probiotic viability through pasteurization. This capability compression is enabling clean-label shelf-life claims previously achievable only through chemical preservatives.
SAMR's alignment gaps with Codex Alimentarius guidelines are creating reformulation burdens for pan-Asian product lines. Multinationals maintaining dual specification sheets—one for China, one for ASEAN—absorb compliance cost premiums that regional competitors cannot match. Sweetener and emulsifier categories face the deepest specification divergence, forcing dedicated China-only SKU development.
Direct technical partnership models are replacing distributor-mediated ingredient procurement in Southeast Asia's largest beverage formulators. Malaysian and Indonesian manufacturers now demand embedded application scientists from suppliers, unbundling traditional trading margins into service fees. This channel compression concentrates purchasing influence with multinationals operating Singapore-based technical centers capable of same-week reformulation support.
Asia-Pacific Specialty Food Ingredient Market Segmentation
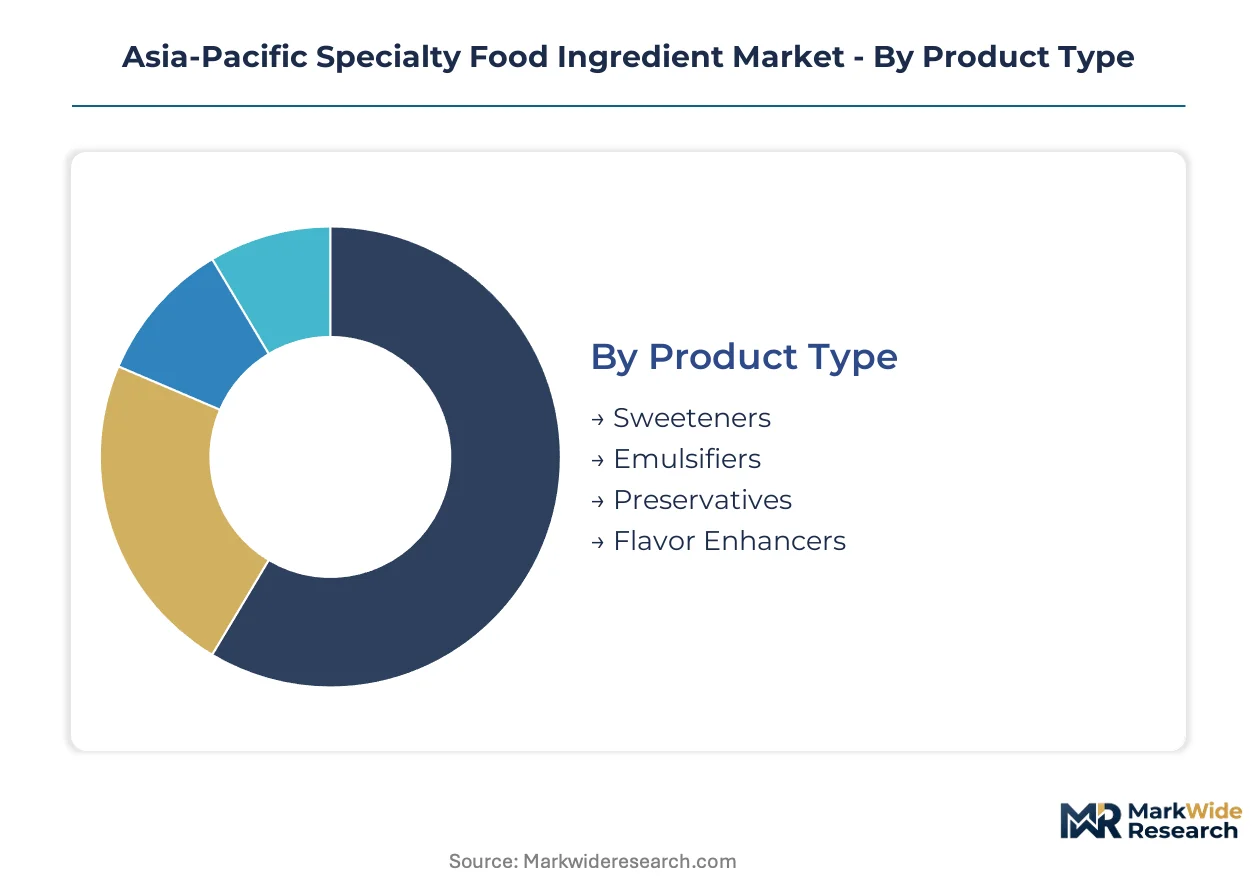
Specialty food ingredient purchasing patterns diverge sharply across application contexts and channel structures. Margin capture depends on matching technical specifications to precise end-use requirements rather than commodity volume plays.
Product Type:
Sweeteners command the deepest margin pools across this category, while emulsifiers are rotating up the value capture rankings fastest.
- Sweeteners:High-intensity compounds including steviol glycosides with minimum 95% purity specifications. Heat-stable, non-caloric alternatives concentrate demand in China's beverage reformulation sector under SAMR's GB 2760 compliance pressure.
- Emulsifiers:Lecithin-derived systems with HLB values engineered for oil-in-water stabilization. Thailand and Vietnam plant-based dairy analogue manufacturers are accelerating clean-label purchases to stabilize lipid-protein matrices in oat and coconut milk systems.
- Preservatives:Cultured dextrose and buffered vinegar chemistry produced through controlled fermentation. Clean-label mandates constrain synthetic alternatives.
- Flavor Enhancers:Umami-active compounds and nucleotide-based systems. Sodium reduction targets in ASEAN processed foods are pulling reformulation demand.
Sweeteners hold installed capacity. Emulsifiers is rotating up the share rankings.
Application:
Beverage formulators absorb premium pricing most readily, while dairy applications concentrate volume throughput.
- Beverages:Plant-based milk alternatives and reduced-sugar soft drinks dominate technical service intensity. ASEAN health ministry sugar reduction targets create regulatory tailwind for reformulation partnerships with embedded application scientists.
- Dairy Products:Processed cheese, yogurt, and flavored milk systems in Maharashtra and Gujarat's dairy corridor pull high-intensity sweeteners and cultured preservatives at industrial scale.
- Bakery:Extended shelf-life bread and clean-label cake systems. Tropical climate heat stability above 35°C ambient conditions constrains emulsifier selection.
- Sauces:Fermented and emulsified condiment categories. Uniform dispersion requirements favor HLB-tuned emulsifier specifications.
Beverages command service fee premiums. Dairy is rotating up the share rankings.
End User:
Food manufacturers consolidate purchasing influence through direct technical partnerships, while restaurant channels fragment procurement.
- Food Manufacturers:Multinational and regional processors with dedicated R&D facilities. Malaysian and Indonesian manufacturers now demand embedded application scientists from suppliers, unbundling traditional trading margins into service fees.
- Restaurants:Chain operators and central kitchen systems. Standardized menu specifications favor pre-blended ingredient systems over discrete component purchasing.
- Retailers:Private-label food product developers. Clean-label positioning requirements compress acceptable preservative chemistry options.
- Caterers:Institutional and event food service operators. Volume volatility limits long-term supply commitments.
Food manufacturers hold installed capacity. Retailers is rotating up the share rankings.
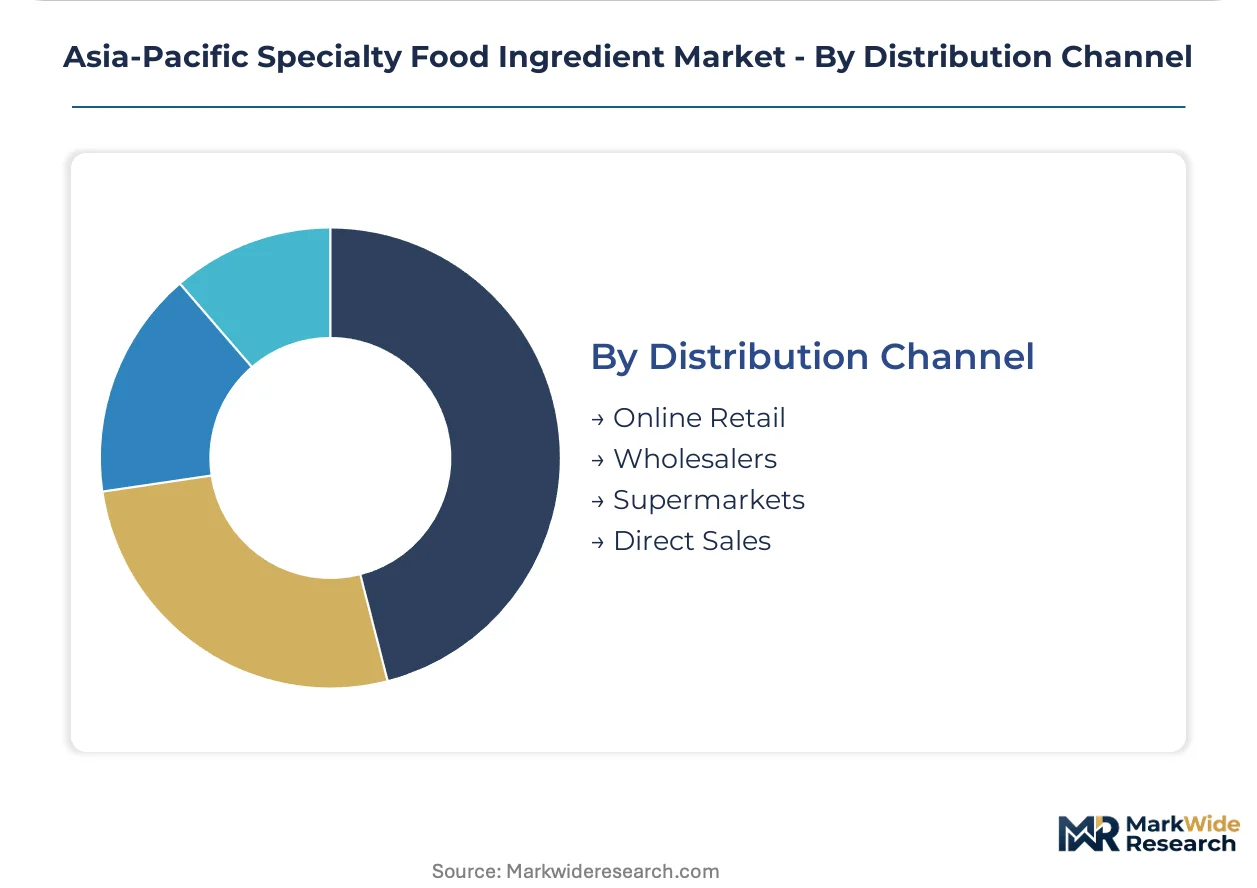
Distribution Channel:
Direct sales capture relationship value through technical embedding, while online retail fragments price transparency.
- Direct Sales:Supplier technical teams co-located with major formulators. Singapore-based technical centers enable same-week reformulation support for ASEAN beverage manufacturers.
- Wholesalers:Regional ingredient distributors with inventory positioning. Traditional trading margins compress as manufacturers demand unbundled service fees.
- Supermarkets:Retail ingredient packaging for small-scale food service. Limited specialty chemical penetration outside commodity preservatives.
- Online Retail:E-procurement platforms for standard-grade ingredients. Price transparency advantages smaller manufacturers without established supplier relationships.
Direct sales holds installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers with embedded technical partnerships concentrate purchasing power across four national markets. Each jurisdiction imposes distinct compliance architectures that filter supplier access.
China
Beverage reformulators under SAMR's GB 2760 revisions absorb premium pricing for heat-stable sweeteners. Shanghai-based regulatory affairs teams now function as market-access gatekeepers for multinational suppliers. Yangtze River Delta dairy processors pull cultured preservatives at industrial scale.
India
Maharashtra and Gujarat's processed dairy corridor drives high-intensity sweetener throughput. FSSAI's 14-18 month ingredient approval schedule creates regulatory friction for novel emulsifier entrants. Mumbai technical centers anchor reformulation partnerships for regional beverage brands.
Indonesia
MUI's compressed halal certification timelines force pre-validated supply chain investments. JAKIM-aligned traceability requirements demand blockchain-enabled ERP reconfiguration. Jakarta and Surabaya food manufacturers consolidate purchasing through direct technical embedding.
Thailand
Plant-based beverage formulators accelerate clean-label emulsifier purchases for oat and coconut milk stabilization. Cane belt weather volatility exposes integrated sweetener networks to raw material disruption. Bangkok-based application scientists enable same-week reformulation support.
Vietnam
ASEAN health ministry sugar reduction targets pull steviol glycoside demand into Ho Chi Minh City beverage manufacturing. Lipid-shell encapsulation pilot programs protect probiotic viability through pasteurization. Regulatory alignment gaps with Codex Alimentarius force parallel formulation tracks.
Asia-Pacific Specialty Food Ingredient Market Competitive Environment
Player mix skews toward multinational ingredient conglomerates with integrated regulatory affairs networks. The supplier base concentrates around three strategic tiers: integrated sweetener-emulsifier platforms, technical service specialists with Singapore hub operations, and regional distributors compressing under direct partnership demands. Competitive moves center on regulatory pre-qualification investments and technical center capacity expansion.
Among integrated platform operators, Cargill and ADM occupy positions anchored by cane belt supply control and tropical climate application testing respectively. Kerry Group exemplifies the technical service archetype through embedded scientist deployment. These three conglomerates represent the dominant competitive anchors as halal certification compression and SAMR compliance requirements raise market-access barriers.
| Leading Market Players |
|---|
| ADM |
| Givaudan |
| Cargill |
| Roquette Frères |
| Ingredion |
| Kerry Group |
| International Flavors & Fragrances |
| CJ CheilJedang |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month halal certification timelines collapsing to under eight months compress supplier cash conversion cycles and concentrate pricing power with pre-validated multinationals. This lead-time compression forces ingredient suppliers to carry higher working inventory buffers while absorbing upfront blockchain traceability investments, reshaping margin structures across Southeast Asia's Muslim consumer markets.
Pricing Analysis
Cost-plus contracts indexed to Thai cane belt raw sugar futures dominate sweetener procurement, with premium tiers tied to SAMR GB 2760 pre-qualification status and JAKIM halal integrity certification. Price differentiation separates heat-stable steviol glycoside grades from standard variants, while volume scale drives standard-emulsifier commoditization. Pricing pressure stems from clean-label chemistry R&D absorption costs. Regional beverage manufacturers show highest price sensitivity; multinational food manufacturers absorb service-embedded premiums.
Supply Chain Analysis
Inbound logistics costs through Singapore port congestion and intra-ASEAN container availability constrain just-in-time delivery commitments for temperature-sensitive emulsifiers. Supply concentrates in Thailand's cane belt regions, China's Yangtze River Delta chemical clusters, and India's Maharashtra-Gujarat dairy corridor. Raw material dependencies include palm-derived lecithin feedstock, fermentation-culture media, and high-purity stevia leaf extracts. Single-source vulnerability runs through Thai cane belt weather exposure. Distribution runs through Singapore technical centers enabling same-week reformulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific specialty food ingredients constitute a high-growth disruption as SAMR's GB 2760 revisions and halal certification compression simultaneously raise compliance barriers and consolidate purchasing influence with technically embedded suppliers.
For Market Incumbents: Consolidate regulatory pre-qualification investments across Shanghai and Mumbai technical centers to defend against emerging regional challengers lacking SAMR-aligned approval pathways. Deepen backward integration into Thai cane belt sweetener feedstock to buffer raw material disruption. Prioritize blockchain-enabled halal traceability ERP middleware to capture JAKIM-compliant shelf placement.
For New Entrants and Emerging Players: Differentiate on tropical-climate formulation expertise above 35°C ambient conditions, targeting Vietnam and Philippines beverage manufacturers underserved by Singapore-hub technical support. Penetrate the Philippines halal export platform where pre-certified ingredient supply remains underdeveloped. Deploy embedded application scientist partnerships to unbundle traditional distributor margins.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because compliance cost escalation filters regional competitors and concentrates share with multinational platforms possessing dedicated regulatory affairs infrastructure. Acquisition targets should display integrated sweetener-emulsifier production with existing SAMR or JAKIM pre-qualification. Monitor divergence between China's GB standards and Codex Alimentarius guidelines as inflection signal for parallel formulation cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Qualification Investment | SAMR GB 2760 alignment secures formulation access in China's beverage reformulation sector. |
| Backward Integration into Feedstock | Cane belt supply control buffers Thai weather volatility for integrated sweetener networks. |
| Technical Center Capacity Expansion | Singapore hubs enable same-week tropical climate emulsifier stability validation for ASEAN manufacturers. |
| Blockchain Traceability Implementation | JAKIM-compliant ERP middleware captures halal-certified shelf placement in Indonesia and Malaysia. |
| Embedded Scientist Partnership Model | Direct technical embedding unbundles distributor margins into service fees with Malaysian and Indonesian formulators. |
Study Parameters
A spread of perspectives from regulatory affairs directors at multinational ingredient suppliers, procurement leads at ASEAN beverage manufacturers, halal certification auditors under MUI and JAKIM, and technical center application scientists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SAMR GB standard filings, FSSAI approval schedules, ASEAN customs trade data, and industry association reports on clean-label chemistry adoption. Bottom-up volume estimates from individual product categories triangulated against top-down market sizing from regional production cluster analysis.
Segmentation dimensions modeled include product type tier, application intensity, end-user procurement sophistication, and distribution channel structure across the projection horizon. CAGRs derived from regression analysis against historical approval timeline compression and reformulation partnership penetration rates. Forecast inputs incorporated SAMR regulatory alignment gap trajectories and ASEAN health ministry sugar reduction mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued halal certification timeline compression and stable SAMR-Codex divergence; material deviation would warrant model refresh. Forecasts reflect base-case regulatory enforcement intensity and tropical climate formulation demand continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Ingredients
Specialty Shortenings Market
Specialty Ingredients
Mangosteen Extract Market
Specialty Ingredients
Specialty Mint Oils Market
Specialty Ingredients
Grape Seed Extract in Pet Food Application Market
Specialty Ingredients
North America Grape Seed Extract Market
Specialty Ingredients
Marine Spicules Market
Specialty Ingredients
Specialty Syrup Market
Specialty Ingredients
South America Specialty Food Ingredient Market
Specialty Ingredients
Haitian Vetiver Oil Market
Specialty Ingredients
Pericarp Waste Market
Specialty Ingredients
Customized Nutrient Premixes Market
Specialty Ingredients
Specialty Food Ingredients Market
Specialty Ingredients
Cupuacu Butter Market
Specialty Ingredients
Middle East and Africa Customized Premixes Market
Specialty Ingredients
Tea-Based Skin Care Products Market
Specialty Ingredients
Fermentation Products Market